
 Transformer Testing Equipment Market | 2026-2036
Transformer Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Transformer Testing Equipment Market Outlook
Renewable energy developers is redrawing procurement priorities in transformer testing equipment, displacing traditional utility-led buying cycles with project-driven volume spikes. OMICRON electronics GmbH leverages its diagnostic software ecosystem to anchor premium positions in automated testing systems. Megger Group competes through field-proven portability across on-site testing deployments. Doble Engineering Company specializes in dissolved gas analysis integration, sustaining loyalty among preventive maintenance buyers in North American utilities.
Transformer testing equipment comprises instruments that evaluate electrical, thermal, and mechanical integrity of power and distribution transformers through measurements of turns ratio, winding resistance, insulation power factor, and excitation current at rated or elevated voltages. These systems verify compliance with IEC 60076, IEEE C57, and national utility specifications before energization or after service events. Insulation resistance testers occupy mature, high-volume positions where price competition limits margin expansion, while automated testing systems capture expanding margin pools as smart grid investments accelerate demand for remote-monitored, software-integrated diagnostics. Third-party testing services represent the fastest-growing end-user channel, driven by utility outsourcing and independent certification requirements for renewable interconnection.
IEC 60076 and IEEE C57 establish the baseline test protocols that manufacturers must support, while EPA and OSHA frameworks in the United States impose worker safety and environmental compliance burdens on field testing operations. The EU F-Gas Regulation and CE marking requirements shape product design for European market access, particularly for oil-filled transformer diagnostics involving insulating fluid handling. Stakeholders must monitor how national grid codes evolve around inverter-based renewable integration, as harmonic tolerance testing and dynamic load validation reshape equipment specifications faster than traditional standard revision cycles.
Market Dynamics
Ultra-high voltage transmission buildouts across China and India are compressing transformer commissioning timelines, forcing utilities to abandon sequential testing protocols in favor of parallel diagnostic workflows that demand automated, software-integrated equipment capable of remote monitoring and real-time data fusion.
Growth Catalysts
- State Grid Corporation of China's UHV expansion:Massive interprovincial transmission corridors require factory-acceptance and field-commissioning protocols that absorb high volumes of turns-ratio and winding-resistance analyzers.
- IEC 60076-18 ed. 2.0:Tightened frequency-response analysis mandates for winding deformation detection compel utilities to upgrade from manual sweep-frequency instruments to automated diagnostic platforms.
- Offshore wind interconnection:Subsea cable-fed transformer installations in the North Sea and Baltic Sea create demand for dissolved gas analysis systems capable of detecting moisture ingress under marine environmental stress.
Market Restraints
- Copper and silicon steel price volatility:Input cost swings for transformer core materials compress OEM margins and delay capital equipment purchases for in-house testing facilities.
- Specialized sensor supply concentration:Piezoelectric acoustic emission sensors for partial discharge detection rely on Japanese and German component suppliers, creating single-source vulnerability.
- Laboratory-grade calibration bottlenecks:Traceable high-voltage reference standards require national metrology institute certification cycles that extend equipment lead times by 8-14 weeks.
Strategic Opportunities
- India's renewable energy corridors:Green Energy Corridor projects in Rajasthan and Gujarat lack sufficient third-party testing infrastructure, creating white space for mobile diagnostic service providers.
- EU F-Gas Regulation phase-down:Restrictions on SF6-insulated switchgear accelerate demand for alternative insulation testing protocols for dry-type and natural ester-filled transformers.
- Edge computing convergence with IoT sensors:On-device inference for thermal imaging and partial discharge pattern recognition enables predictive maintenance without cloud dependency, opening rural utility segments.
Industry Challenges
- High-voltage test technician scarcity:Experienced personnel capable of safely executing induced overvoltage and impulse tests are retiring faster than training programs replenish supply.
- Legacy asset database incompatibility:Utilities with decades of paper-based transformer histories struggle to migrate historical dissolved gas analysis trends into modern predictive analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transformer Testing Equipment Market |
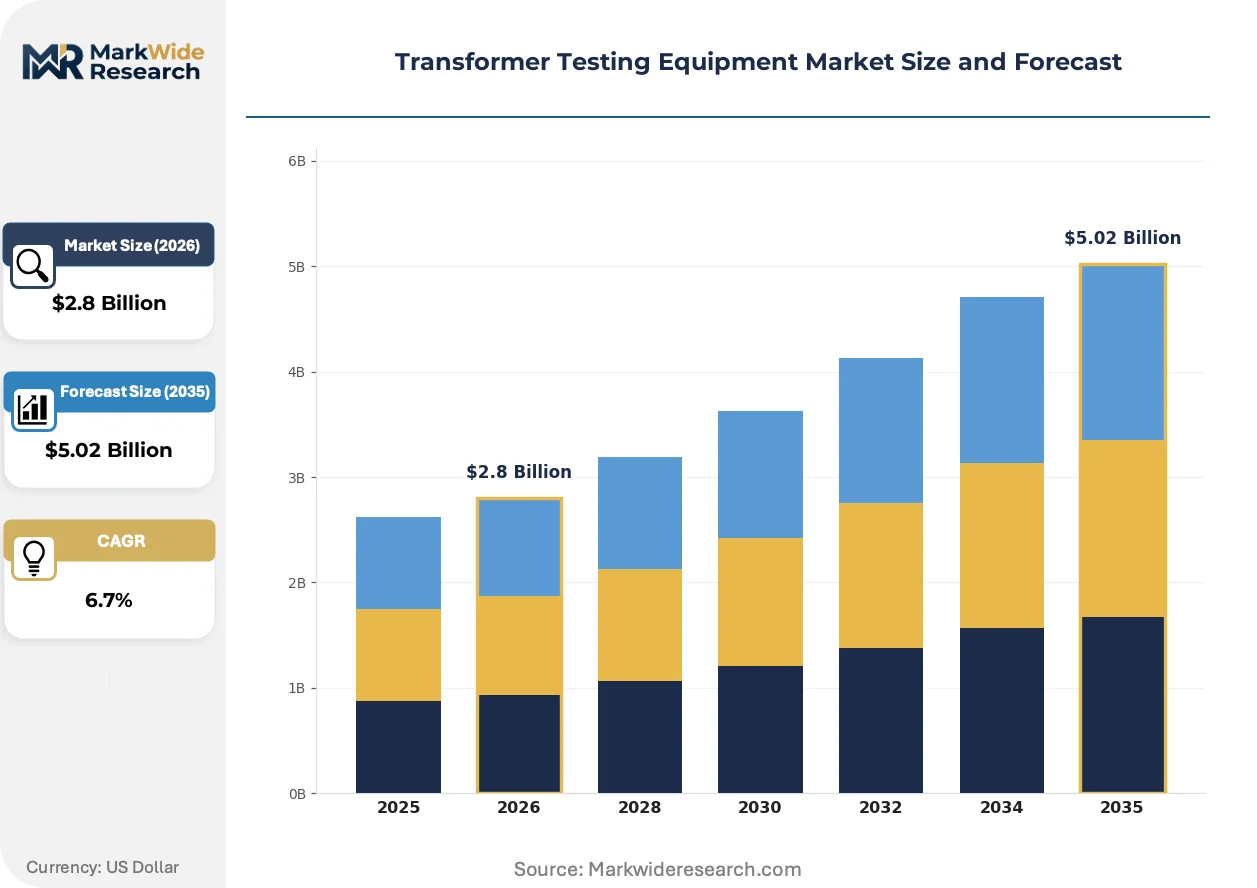
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulation Resistance Tester, Power Factor Tester, Transformer Turns Ratio Tester, Circuit Tester Application: On-Site Testing, Laboratory Testing, Factory Acceptance Testing, Preventive Maintenance End User: Utilities, Industrial Plants, Renewable Energy Sector, Third-Party Testing Services Technology: Digital, Analog, Smart Testers, Automated Testing Systems |
| Companies Covered | OMICRON electronics GmbH, Doble Engineering Company, Megger Group, Fluke Corporation, Keysight Technologies, ABB Ltd., General Electric Company, Schneider Electric SE, Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transformer Testing Equipment Market Strategic Shifts
Diagnostic hardware is converging with software-defined measurement architectures, compressing the traditional separation between field-portable instruments and laboratory-grade systems while embedding machine-learning inference directly at the sensor edge.
Handheld turns-ratio testers with integrated Bluetooth data streaming are miniaturizing. Solar farm commissioning crews in Australia and Chile now deploy pocket-sized winding analyzers that upload results directly to cloud-based asset registries, collapsing the interval between field measurement and central engineering review from days to minutes.
China's GB/T 1094.10-2022 revision tightens sound level measurement tolerances for power transformers. Manufacturers serving the State Grid and China Southern Power Grid must now deploy precision acoustic camera arrays during factory testing, shifting procurement toward integrated vibration-sensor platforms that correlate mechanical noise with core magnetostriction signatures.
Third-party certification bodies are capturing testing volume previously handled by utility internal labs. Germany's DEKRA and TÜV Rheinland now operate dedicated transformer diagnostic centers near major wind turbine assembly hubs in Bremerhaven and Cuxhaven, displacing OEM-performed acceptance testing with independent verification that satisfies project finance due-diligence requirements.
Transformer Testing Equipment Market Segmentation
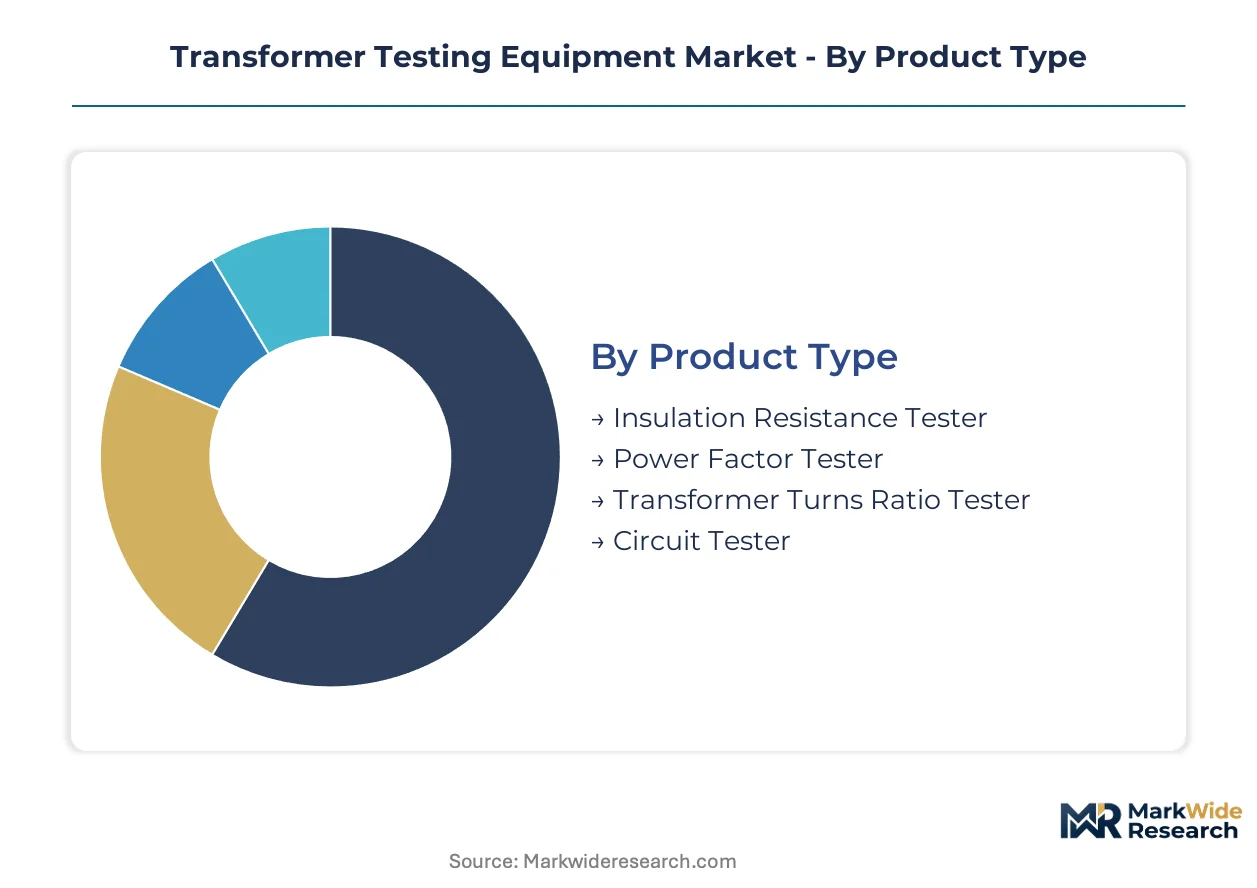
Transformer testing equipment segments reveal divergent margin structures and channel economics. Product type determines capital intensity, while application context dictates whether procurement flows through OEM-direct, distributor, or third-party service channels.
Product Type:
Channel mix varies sharply by product complexity: handheld insulation testers move through electrical distributors and e-commerce, while automated systems require direct OEM engagement with utility engineering teams.
- Insulation Resistance Tester:Portable megohmmeters measuring dielectric integrity at 500V to 15kV test voltages. Megger Group and Fluke dominate distributor shelves. Demand concentrates in utility field crews across the United States and India performing routine substation maintenance, constrained by price competition that compresses distributor margins below 15%.
- Transformer Turns Ratio Tester:Precision instruments verifying winding polarity and ratio accuracy against nameplate specifications. State Grid Corporation of China procurement absorbs the largest factory-direct volumes for UHV transformer commissioning, driven by GB/T 1094.1 compliance mandates and compressed project timelines requiring parallel testing workflows.
- Power Factor Tester:Dissipation factor analyzers evaluating insulation power factor and capacitance at line frequency. Doble Engineering serves North American utilities through long-term service contracts.
- Circuit Tester:Continuity and load-break verification tools for distribution transformer secondary circuits. Industrial plant procurement in Germany favors CE-marked units with integrated data logging.
By volume, insulation resistance testers lead. By growth pace, automated testing systems are gaining share fastest.
Application:
Cost tier separation is pronounced: factory acceptance testing commands premium pricing for traceable calibration certificates, while preventive maintenance operates on tighter capital budgets.
- Factory Acceptance Testing:Protocols executed at manufacturer facilities before transformer shipment, encompassing full IEC 60076-1 compliance suites including no-load loss and impedance voltage measurements. Siemens Energy and Hitachi Energy internal labs in Germany and Japan drive demand for integrated test bays with automated data acquisition, constrained by laboratory-grade calibration bottlenecks that extend equipment lead times.
- Preventive Maintenance:Periodic diagnostic programs for in-service transformers, emphasizing dissolved gas analysis and frequency-response analysis for winding deformation detection. Third-party testing services in the North Sea offshore wind corridor create expanding demand for mobile dissolved gas analysis systems capable of marine-environment operation.
- On-Site Testing:Commissioning and troubleshooting at installation locations. Australian solar farm developers favor Bluetooth-enabled handheld units for rapid cloud upload.
- Laboratory Testing:R&D and failure analysis for forensic investigation. National metrology institutes in China and Germany maintain reference standards.
Factory acceptance testing captures the highest unit margins. Preventive maintenance is expanding most quickly as utility outsourcing accelerates.
End User:
Customer type determines specification authority: utilities write standards that industrial plants and renewable developers must follow.
- Utilities:Vertically integrated grid operators specifying test protocols for their own fleets and supplier compliance. State Grid Corporation of China and PG&E in the United States anchor procurement volumes, driven by IEC 60076-18 ed. 2.0 frequency-response analysis mandates and internal technician training investments.
- Third-Party Testing Services:Independent certification bodies and mobile diagnostic contractors. DEKRA and TÜV Rheinland operations in Bremerhaven and Cuxhaven displace OEM-performed acceptance testing for North Sea wind interconnection projects, satisfying project finance due-diligence requirements.
- Renewable Energy Sector:Solar and wind developers requiring commissioning verification. Rajasthan Green Energy Corridor projects in India lack sufficient testing infrastructure.
- Industrial Plants:Manufacturing facilities with captive substations. German automotive plants specify predictive maintenance integration with SCADA systems.
Utilities dominate current procurement value. Third-party testing services are climbing the fastest as certification outsourcing expands.
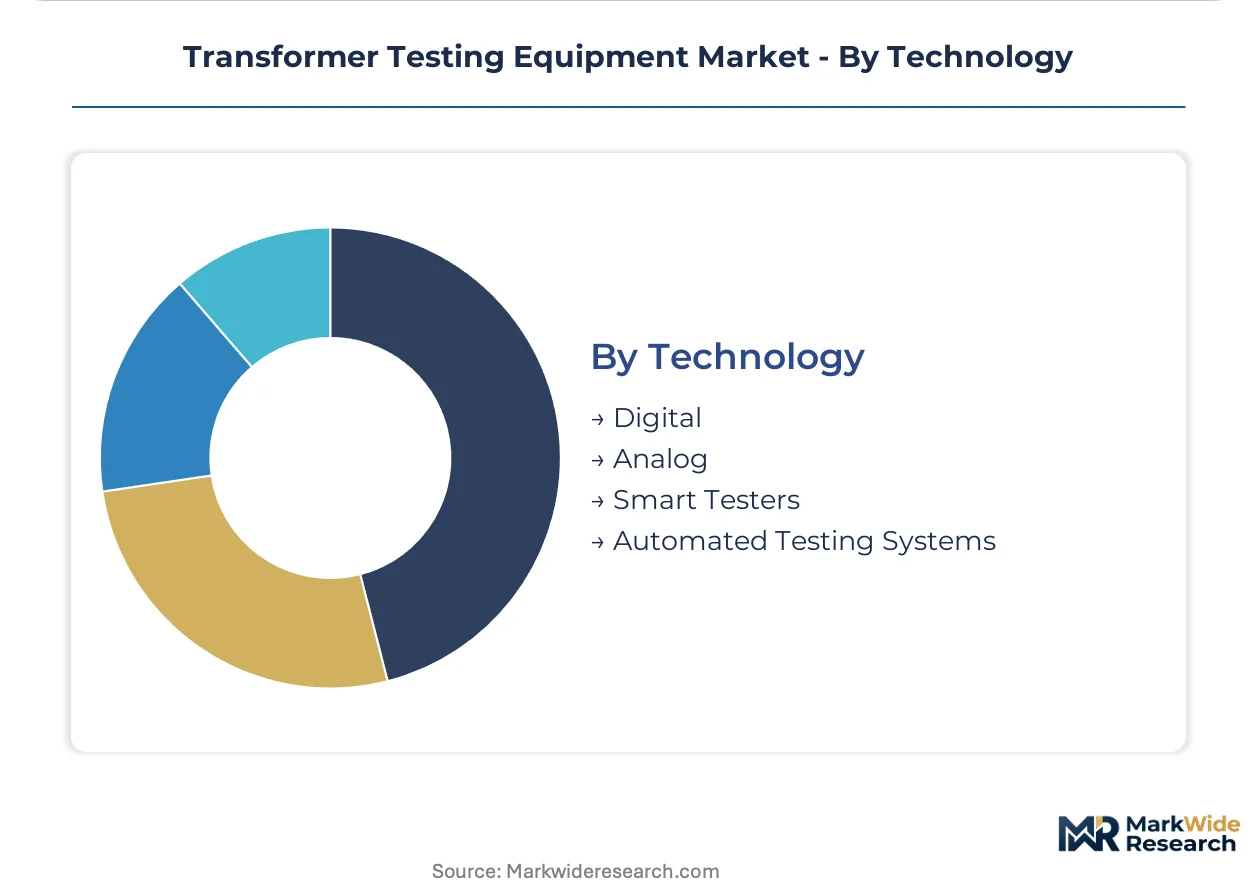
Technology:
Maturity gradients separate established digital platforms from emerging smart architectures with embedded edge inference.
- Automated Testing Systems:Software-integrated platforms executing multiple test sequences with remote monitoring and real-time data fusion. OMICRON electronics serves European utilities with diagnostic ecosystems that compress commissioning timelines for ultra-high voltage corridors, driven by parallel workflow requirements that abandon sequential protocols.
- Smart Testers:Handheld instruments with on-device machine learning for pattern recognition and cloud connectivity. Solar commissioning crews in Chile and Australia deploy pocket-sized winding analyzers with direct asset registry upload.
- Digital:Microprocessor-based instruments with stored test sequences and digital displays. Standard for utility field crews in India and the United States.
- Analog:Electromechanical instruments with needle indicators. Limited to backup verification in legacy facilities and training environments.
Digital platforms lead by installed base. Smart testers show the steepest expansion trajectory as edge computing converges with IoT sensor deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export automated testing systems to Chinese utilities commissioning ultra-high voltage corridors, while Japanese sensor suppliers feed acoustic emission hardware into European offshore wind diagnostic networks.
China
State Grid Corporation of China absorbs the largest factory-direct volumes of turns-ratio and winding-resistance analyzers for interprovincial UHV transmission buildouts. GB/T 1094.10-2022 tightens sound level measurement tolerances, forcing acoustic camera array adoption during factory testing. Xi'an and Shenyang host transformer manufacturing clusters where precision vibration-sensor platforms correlate mechanical noise with core magnetostriction signatures.
United States
PG&E and other vertically integrated utilities anchor preventive maintenance procurement for dissolved gas analysis systems. EPA and OSHA frameworks impose worker safety compliance burdens on field testing operations. California's solar farm commissioning crews deploy Bluetooth-enabled handheld units for rapid cloud upload to central asset registries.
Germany
Siemens Energy internal labs drive demand for integrated test bays with automated data acquisition for factory acceptance protocols. EU F-Gas Regulation phase-down accelerates alternative insulation testing for dry-type transformers. Bremerhaven and Cuxhaven host DEKRA and TÜV Rheinland diagnostic centers displacing OEM-performed acceptance testing for North Sea wind interconnection.
India
Rajasthan and Gujarat Green Energy Corridor projects lack sufficient third-party testing infrastructure, creating white space for mobile diagnostic service providers. Central Electricity Authority mandates compress commissioning timelines for renewable interconnection. Mumbai and Ahmedabad industrial zones absorb portable megohmmeters for routine substation maintenance.
Australia
Solar farm developers in Queensland and New South Wales favor pocket-sized winding analyzers with direct asset registry upload. Edge computing convergence with IoT sensors enables predictive maintenance without cloud dependency in rural utility segments. Sydney-based certification bodies expand mobile testing fleets for utility outsourcing contracts.
Transformer Testing Equipment Market Competitive Environment
Player mix skews toward specialized diagnostic equipment manufacturers with deep software integration capabilities. The competitive terrain splits between European precision instrumentation houses and Asian industrial conglomerates with captive testing divisions. Two strategic archetypes dominate: software-integrated platform providers and field-portable instrument specialists. Capacity expansion in automated testing systems and strategic partnerships for sensor technology licensing represent the dominant competitive moves.
Within the software-integrated tier, OMICRON electronics GmbH exemplifies the diagnostic ecosystem approach anchoring premium positions. Megger Group and Doble Engineering Company occupy positions across field-portable and preventive maintenance segments. These three entities represent the competitive spectrum from automated platform provision to specialized dissolved gas analysis integration.
| Leading Market Players |
|---|
| OMICRON electronics GmbH |
| Doble Engineering Company |
| Megger Group |
| Fluke Corporation |
| Keysight Technologies |
| ABB Ltd. |
| General Electric Company |
| Schneider Electric SE |
| Yokogawa Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at German and Japanese precision instrumentation plants shapes both supply concentration and price floors for automated testing systems, compressing margins on legacy digital platforms while insulating premium software-integrated tiers from commodity pressure.
Pricing Analysis
Current-generation automated testing systems command three-to-four-fold premiums over prior-generation digital platforms, while next-generation smart testers with edge inference capabilities are pricing at early-adopter premiums in Australian and Chilean solar markets. Pricing stratifies across premium certification-grade, standard utility-spec, and economy distributor-tier levels, with IEC 60076-18 ed. 2.0 compliance and traceable calibration certificates as the primary price differentiation drivers. Cost compression in handheld insulation testers is intensifying because of distributor margin pressure below 15%, while automated system buyers show lowest price sensitivity due to parallel workflow productivity gains.
Supply Chain Analysis
Strategic stockpiling of piezoelectric acoustic emission sensors dominates inventory strategy among European partial discharge equipment manufacturers, contrasting with just-in-time component flows for handheld testers. Supply concentrates in Germany for precision instrumentation, Japan for specialized sensors, and China for high-volume digital platforms. Manufacturing rests on copper winding components, silicon steel cores, and laboratory-grade calibration references. Single-source vulnerability in Japanese and German sensor suppliers creates structural supply chain risk. Distribution runs through OEM-direct channels for automated systems and electrical distributors for portable instruments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transformer testing equipment sits in early-cycle expansion as renewable interconnection mandates and UHV transmission buildouts accelerate adoption of software-integrated diagnostic platforms ahead of traditional replacement cycles.
For Market Incumbents: Secure software ecosystem lock-in through diagnostic platform subscriptions that embed predictive analytics, defending against emerging entrants offering standalone smart testers. Prioritize backward integration into sensor technology to reduce single-source exposure from Japanese and German component suppliers. Capacity addition in India addresses third-party testing service gaps before mobile diagnostic competitors establish beachheads. For New Entrants and Emerging Players: Mobile diagnostic service gaps in India's Rajasthan and Gujarat Green Energy Corridors offer the most penetrable white space, where insufficient testing infrastructure delays renewable interconnection timelines. Target third-party certification contracts for North Sea offshore wind projects, where independent verification requirements displace OEM-performed acceptance testing. Pursue partnership-based go-to-market angles with existing certification bodies rather than direct utility sales cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-integrated platform providers with diagnostic ecosystem subscriptions, positioning these archetypes for superior long-term viability across the 5-10 year window. Acquisition targets should display deep vertical integration into sensor technology or established service contracts with State Grid Corporation of China. The signal to watch as inflection indicator is utility outsourcing velocity for preventive maintenance programs, particularly dissolved gas analysis and frequency-response analysis mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Software Ecosystem Expansion | OMICRON electronics anchors premium positioning through integrated predictive analytics platforms for European utilities. |
| Mobile Diagnostic Service Fleet Buildout | DEKRA and TÜV Rheinland capture North Sea wind certification volume previously handled by OEM internal labs. |
| Edge Computing Sensor Integration | Smart testers with on-device inference open rural utility segments without cloud dependency in Australian markets. |
| Backward Integration into Acoustic Emission Sensors | Reduced single-source exposure from Japanese and German suppliers mitigates supply chain vulnerability for partial discharge systems. |
| Third-Party Certification Center Establishment | Independent verification facilities near major wind turbine assembly hubs satisfy project finance due-diligence requirements. |
Study Parameters
Cross-validation between primary interviews with utility engineering directors, transformer OEM test lab managers, third-party certification body operations heads, and renewable project commissioning leads anchors the qualitative findings, while secondary validation draws from IEC and IEEE standard revision documents, State Grid Corporation procurement disclosures, and national metrology institute certification records. Bottom-up equipment shipment analysis triangulates against top-down utility capital expenditure tracking across the projection horizon.
Sensitivity analysis on input material cost volatility and technician labor availability stress-tests the analytical framework across product type, application context, end-user category, and technology generation segmentation dimensions. CAGRs derive from equipment replacement cycle analysis and renewable interconnection mandate trajectories, with factory acceptance testing protocol requirements and preventive maintenance outsourcing velocity as industry-specific forecast inputs.
Underlying assumptions cover sustained UHV transmission investment in China and renewable capacity additions in India, with deviation risk concentrated in copper and silicon steel price volatility and high-voltage test technician scarcity. Forecasts reflect these documented conditions. Revision becomes warranted when utility outsourcing velocity for third-party testing services crosses thresholds that fundamentally alter channel economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
Semiconductor Chip Test Probes Market
Test and Measurement
Edge Computing Enclosure Environmental Stress Test Equipment Market
Test and Measurement
LAN Tester Market
Test and Measurement
Brightness Meter Market
Test and Measurement
VXI Test Equipment Market
Test and Measurement
Tribometer Market
Test and Measurement
Humidity Testers Market
Test and Measurement
EMC Shielding and Test Equipment Market
Test and Measurement
Miniature Atomic Clock Market
Test and Measurement
In-Process Composite Layup Monitoring Sensors and Test Equipment Market
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
VXI Testing Equipment Market
Test and Measurement
Micro Ohmmeter Market
Test and Measurement
Permeation Testing Machines Market
Test and Measurement
Pump Testers Market