
 Asia-Pacific Tunable Laser Market | 2026-2036
Asia-Pacific Tunable Laser Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Tunable Laser Market Outlook
Telecom carrier procurement in the Asia-Pacific is decoupling from single-vendor dependence as open optical networking gains traction across national backbones. Lumentum Operations LLC leverages its vertical integration in indium phosphide components to maintain pricing leverage on high-channel-count modules. Coherent Corp. anchors its position through captive supply of integrated coherent receivers paired with tunable laser assemblies. Santec Corporation differentiates via specialized swept-source engines for optical coherence tomography, a niche where Japanese precision manufacturing standards create durable barriers.
A tunable laser is a solid-state or semiconductor light source whose output wavelength adjusts across a defined spectral band through temperature, current, or external cavity control, typically spanning C-band or L-band windows with linewidths below 100 kHz for coherent communications. Fiber laser architectures dominate telecommunications applications due to superior beam quality and thermal stability in dense wavelength-division multiplexing systems. Semiconductor laser platforms lead in medical device integration, where compact form factors and millisecond switching speeds enable real-time surgical guidance. Sensing applications across industrial manufacturing are gravitating toward hybrid digital-analog control schemes that merge FPGA-based wavelength lockers with analog current tuning for sub-picometer stability.
Japan's METI enforces JIS standards on laser safety and electromagnetic compatibility that constrain import pathways for non-certified equipment. China's MIIT mandates domestic encryption modules and GB-standard optical interfaces for government and carrier networks, effectively conditioning market access on local certification. South Korea's MFDS and KISA jointly regulate medical laser exports through performance verification protocols that extend approval timelines for foreign suppliers. Stakeholders must monitor how India's BIS phased manufacturing program and TRAI spectrum auction timelines reshape component sourcing rules across the subcontinent.
Market Dynamics
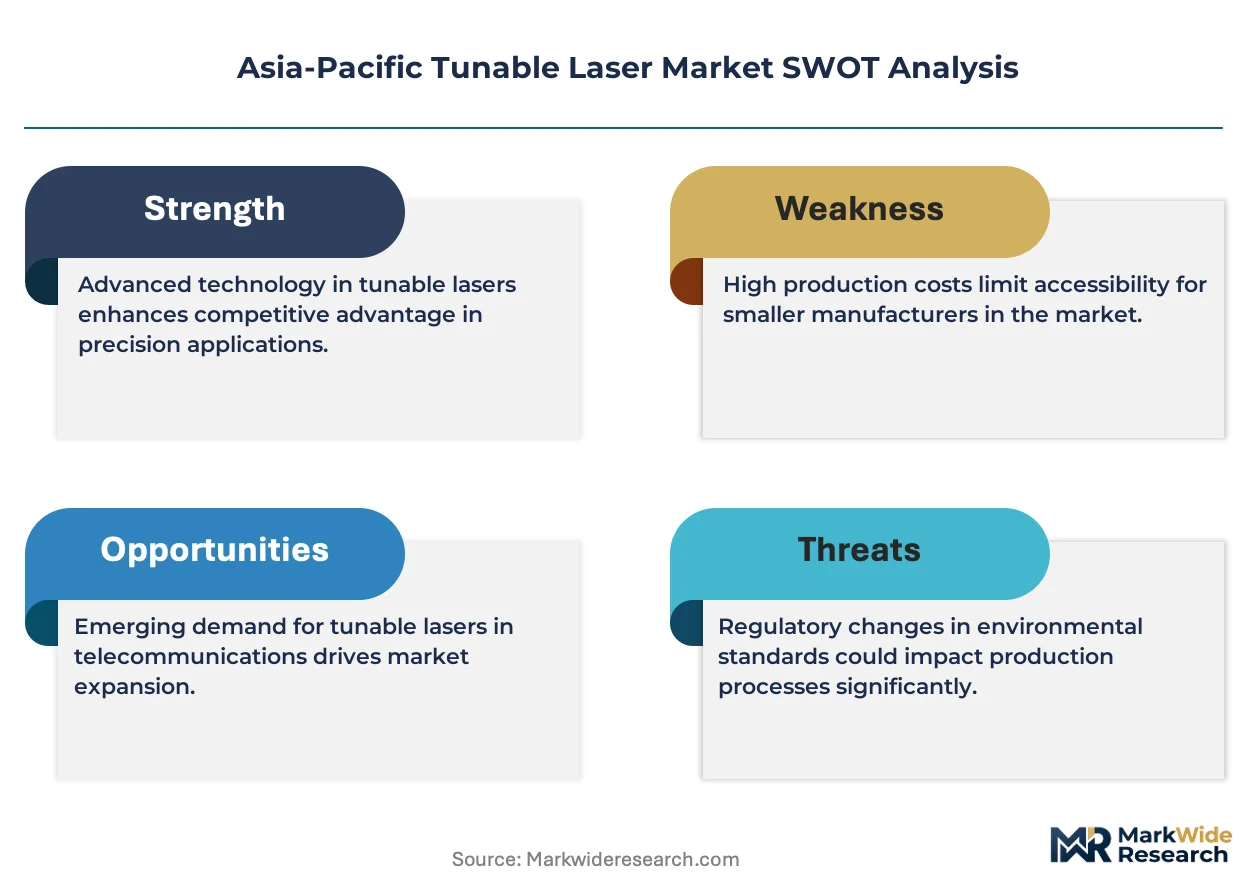
Open optical networking architectures are restructuring procurement relationships across Asia-Pacific national backbones, forcing tunable laser suppliers to disaggregate hardware from software control layers and certify interoperability across multi-vendor line systems.
Growth Catalysts
- MIIT spectrum allocation policies:China's Ministry of Industry and Information Technology has released contiguous C-band blocks for 400G coherent trials, mandating tunable sources for government backbone upgrades.
- Photonics cluster concentration:Yangtze River Delta manufacturing ecosystems achieve 40% shorter component integration cycles than dispersed supply configurations, compressing time-to-yield for external cavity lasers.
- Green technology incentives:Japan's METI subsidies for energy-efficient telecom equipment favor thermally stable indium phosphide platforms over legacy architectures in carrier RFPs.
Market Restraints
- Indium phosphide wafer supply:Three foundries control 80% of qualified III-V substrate production, exposing module assemblers to allocation shocks during optical semiconductor demand surges.
- JIS certification timelines:Japan's METI-enforced electromagnetic compatibility testing extends import approval cycles by 8-14 months for non-JIS-certified swept-source engines.
- Silicon photonics substitution:Integrated silicon-based coherent transceivers with embedded tunable sources are capturing low-channel-count metro applications below 100G.
Strategic Opportunities
- India's Bengaluru telecom corridor:TRAI's 5G backhaul spectrum auctions and BIS phased manufacturing mandates create localized sourcing requirements for tunable laser assemblies.
- Optical coherence tomography expansion:South Korea's MFDS fast-track approval pathway for ophthalmic diagnostic devices accelerates swept-source adoption in premium medical imaging.
- Hybrid control convergence:FPGA-based wavelength lockers merged with analog current tuning are opening industrial sensing applications requiring sub-picometer stability.
Industry Challenges
- III-V epitaxy talent scarcity:MOCVD reactor operation and quantum well design expertise concentrates in Japan's Tsukuba and China's Suzhou, constraining foundry expansion elsewhere.
- GB-standard optical interface certification:China's MIIT mandates domestic encryption module integration, forcing foreign suppliers to re-qualify tunable laser assemblies for government network eligibility.
- Legacy DWDM system integration:Open line system migration requires backward-compatible wavelength stability protocols that complicate firmware architectures for coherent pluggables.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Tunable Laser Market |
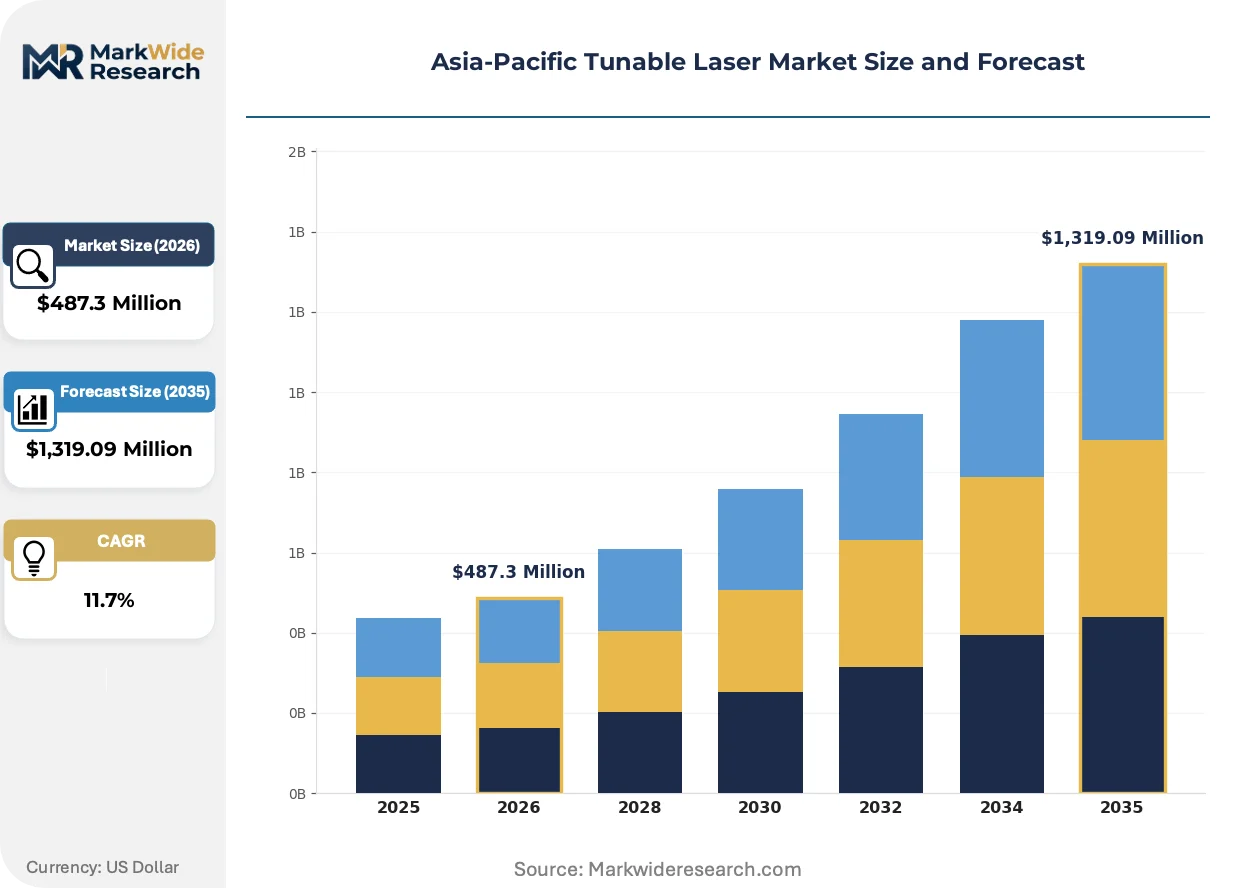
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Laser, Solid-State Laser, Semiconductor Laser, Dye Laser Application: Telecommunications, Material Processing, Medical Devices, Sensing End User: Research Labs, Industrial Manufacturing, Healthcare, Defense Technology: Optical, Digital, Analog, Hybrid |
| Companies Covered | Lumentum Operations LLC, Coherent Corp., Keysight Technologies, Santec Corporation, Newport Corporation, Furukawa Electric Co., Ltd., EXFO Inc., EMCORE Corporation, HÜBNER Photonics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Tunable Laser Market Strategic Shifts
Control plane disaggregation and wavelength stability demands are converging to reshape how tunable sources interface with network management systems across Asia-Pacific carrier environments.
Hybrid digital-analog wavelength stabilization is consolidating around FPGA-locked external cavity architectures that merge millisecond switching speeds with thermal drift compensation. Japanese precision equipment manufacturers are adopting these platforms for optical coherence tomography systems where real-time surgical guidance demands sub-100 kHz linewidth maintenance. The technology is consolidating swept-source market share by compressing the performance gap between semiconductor and fiber laser platforms.
METI's green technology certification framework now mandates power consumption disclosure for telecom optical components above 10Gbps, conditioning carrier procurement scoring on thermal efficiency metrics. Japanese carriers have embedded these requirements into 2024-2025 RFP evaluation matrices, privileging suppliers with indium phosphide vertical integration. Medical device exports face parallel efficiency verification under PMDA technical documentation standards, extending compliance preparation cycles for foreign swept-source vendors.
Carrier procurement departments are unbundling hardware acquisition from multi-year maintenance contracts, shifting toward annual technology refresh commitments with separate sparing agreements. This disaggregation is displacing traditional turnkey system purchases across South Korea's Pangyo technopolis and China's Yangtze River Delta. The pattern is most visible in China Mobile's open optical networking trials, where tunable laser modules are sourced independently from line system integrators.
Asia-Pacific Tunable Laser Market Segmentation
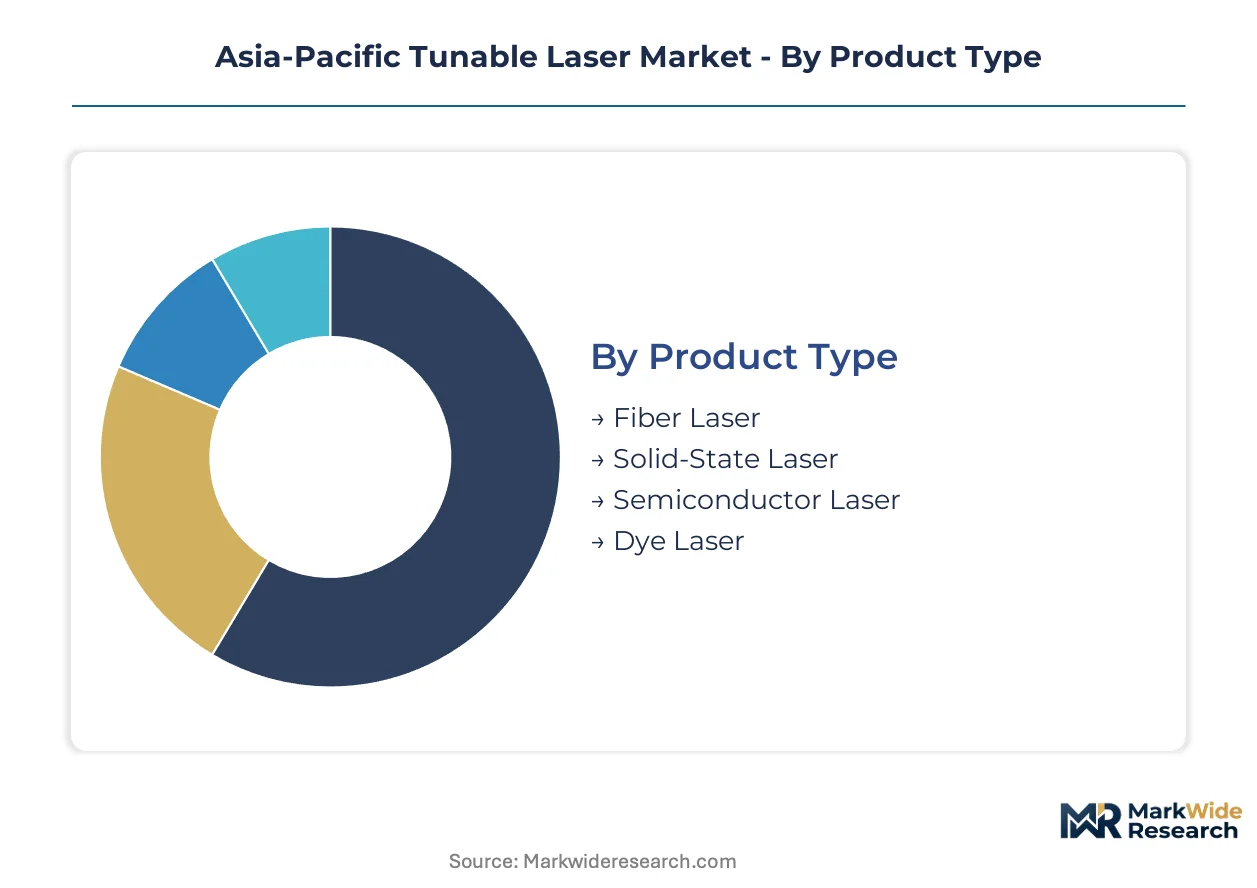
Technology architecture and wavelength stability specifications determine competitive positioning across Asia-Pacific procurement channels. Carrier procurement teams evaluate tunable sources against thermal drift coefficients and channel spacing precision rather than headline power ratings alone.
Product Type:
Gain medium composition dictates thermal stability, linewidth performance, and integration compatibility with coherent transceiver assemblies.
- Fiber Laser:Erbium-doped or ytterbium-doped fiber cavities deliver sub-100 kHz linewidths with exceptional beam quality for dense wavelength-division multiplexing backbones. China's Yangtze River Delta cluster concentrates manufacturing for 400G coherent trials, though indium phosphide supply constraints limit foundry expansion.
- Semiconductor Laser:Indium phosphide quantum well structures enable millisecond wavelength switching in compact form factors, dominating medical device integration where Japan's PMDA efficiency standards privilege thermal stability. South Korea's MFDS fast-track pathway accelerates swept-source adoption in ophthalmic diagnostics.
- Solid-State Laser:Crystal-based architectures with external cavity feedback provide narrow linewidth outputs for precision metrology applications.
- Dye Laser:Organic gain media enable broad tunability across visible spectra for specialized spectroscopy research.
Fiber laser platforms lead on scale in telecommunications infrastructure; semiconductor architectures lead on momentum in medical device exports.
Application:
End-use environments impose divergent requirements on switching speed, thermal management, and control interface protocols.
- Telecommunications:Coherent optical transport systems demand C-band and L-band tunability with integrated wavelength lockers for 100G-400G line rates. China's MIIT spectrum allocations mandate domestic encryption module compatibility, conditioning module qualification for government backbone eligibility.
- Sensing:Industrial manufacturing applications require sub-picometer stability for structural health monitoring and gas detection. Hybrid digital-analog control schemes merging FPGA-based lockers with analog current tuning are displacing pure analog architectures.
- Material Processing:High-power tunable sources enable precision cutting and welding across automotive and electronics manufacturing.
- Medical Devices:Optical coherence tomography systems in Japan and South Korea demand real-time surgical guidance capabilities with swept-source engines.
Telecommunications commands volume concentration; sensing applications are expanding most quickly through industrial automation adoption.
End User:
Procurement authority and technical specification ownership vary sharply across institutional buyer categories.
- Industrial Manufacturing:Factory automation and process control systems integrate tunable lasers for inline quality inspection and LiDAR-based navigation. India's BIS phased manufacturing program creates localized sourcing requirements for foreign component suppliers.
- Healthcare:Hospital systems and diagnostic equipment manufacturers in Japan and South Korea drive swept-source demand for ophthalmic and cardiovascular imaging. METI green technology subsidies condition carrier RFP scoring on thermal efficiency metrics.
- Research Labs:Academic and government research institutions specify custom wavelength ranges for spectroscopy and quantum communication experiments.
- Defense:Military procurement programs require ruggedized packaging and electromagnetic interference hardening for field-deployable systems.
Industrial manufacturing leads on scale; healthcare leads on momentum through regulatory fast-track pathways.
Technology:
Control plane architecture determines interoperability with network management systems and wavelength stability under thermal load.
- Hybrid:FPGA-locked external cavity designs merge millisecond switching speeds with thermal drift compensation, consolidating market share in both telecommunications and medical imaging. Japanese precision equipment manufacturers favor these platforms for optical coherence tomography where sub-100 kHz linewidth maintenance is mandatory.
- Digital:Software-defined wavelength control enables remote provisioning and automated channel assignment in open optical networking architectures. China's open line system trials are displacing traditional turnkey purchases.
- Optical:Pure optical feedback mechanisms provide inherent stability without electronic control complexity for laboratory environments.
- Analog:Current and temperature tuning circuits offer cost-optimized solutions for legacy dense wavelength-division multiplexing systems.
Hybrid control architectures lead on scale; digital platforms are gaining share fastest through open networking procurement restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MOCVD reactor operators and quantum well designers concentrate in Japan's Tsukuba and China's Suzhou, anchoring III-V epitaxy talent pools that constrain foundry expansion elsewhere in the region.
China
MIIT's contiguous C-band spectrum releases for 400G coherent trials drive government backbone procurement, mandating tunable sources with domestic encryption module compatibility. GB-standard optical interface certification conditions market access on local re-qualification of foreign assemblies. The Yangtze River Delta photonics cluster compresses component integration cycles by 40% versus dispersed supply configurations.
Japan
METI green technology subsidies privilege thermally stable indium phosphide platforms in carrier RFP evaluation matrices. JIS electromagnetic compatibility testing extends import approval cycles by 8-14 months for non-certified swept-source engines. Tsukuba's precision manufacturing ecosystems maintain durable barriers in optical coherence tomography through sub-100 kHz linewidth standards.
South Korea
MFDS and KISA joint protocols regulate medical laser exports through performance verification requirements that lengthen foreign supplier timelines. The Pangyo technopolis anchors open optical networking procurement restructuring, with carrier departments unbundling hardware from multi-year maintenance contracts. Fast-track approval pathways accelerate swept-source adoption in ophthalmic diagnostic devices.
India
TRAI's 5G backhaul spectrum auctions and BIS phased manufacturing mandates create localized sourcing requirements for tunable laser assemblies. The Bengaluru telecom corridor concentrates demand from carrier infrastructure buildouts. Factory automation and process control systems integrate tunable sources for inline quality inspection across industrial manufacturing sub-sectors.
Australia
Research institutions and government laboratories specify custom wavelength ranges for spectroscopy and quantum communication experiments. Academic procurement channels favor narrow linewidth solid-state architectures with external cavity feedback. Defense programs require ruggedized packaging and electromagnetic interference hardening for field-deployable systems.
Asia-Pacific Tunable Laser Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across procurement channels reshaped by open optical networking architectures. The vendor base organizes around three strategic archetypes: vertically integrated component manufacturers with captive III-V foundry access, modular assembly specialists sourcing epitaxial wafers from qualified foundries, and precision equipment manufacturers serving medical imaging niches. Dominant competitive moves include backward integration into indium phosphide substrate production and strategic partnerships to secure MOCVD reactor capacity.
Within the vertically integrated tier, Lumentum Operations LLC and Coherent Corp. exemplify archetypes combining component manufacturing with captive supply chains. Santec Corporation occupies a specialist position in swept-source engines for precision medical applications. These three entities represent distinct competitive vectors: Lumentum leverages pricing leverage on high-channel-count modules, Coherent anchors position through integrated coherent receiver pairings, and Santec differentiates via Japanese precision manufacturing standards in optical coherence tomography.
| Leading Market Players |
|---|
| Lumentum Operations LLC |
| Coherent Corp. |
| Keysight Technologies |
| Santec Corporation |
| Newport Corporation |
| Furukawa Electric Co., Ltd. |
| EXFO Inc. |
| EMCORE Corporation |
| HÜBNER Photonics |
| Others |
Value Chain & Pricing Dynamics
Indium phosphide wafer costs cascade through module assembly tiers, with III-V substrate scarcity compressing margins at the foundry level while carrier procurement unbundling squeezes integrator pricing power downstream.
Pricing Analysis
Carrier procurement departments are unbundling hardware acquisition from multi-year maintenance contracts, shifting toward annual technology refresh commitments with separate sparing agreements. Three-tier pricing structure across premium, standard, and economy levels separates indium phosphide-integrated coherent modules from silicon photonics alternatives and legacy fixed-wavelength sources. Price differentiation hinges on channel count density and JIS certification status, with METI green technology subsidies privileging thermally stable platforms in Japanese carrier RFPs. Price erosion runs through standard-tier metro modules as silicon photonics substitution accelerates below 100G applications, while premium-tier 400G coherent assemblies retain pricing power due to III-V epitaxy talent scarcity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale carrier demand across China's Yangtze River Delta and South Korea's Pangyo technopolis, while medical device manufacturers in Japan source through precision equipment distributors with JIS-certified warehousing. Geographic supply concentration centers on Japan's Tsukuba and China's Suzhou for MOCVD reactor operation and quantum well design expertise, with raw material dependencies on indium phosphide substrates, erbium-doped fiber, and FPGA-based wavelength locker components. Single-source vulnerability in qualified III-V substrate production exposes assemblers to allocation shocks during optical semiconductor demand surges. Distribution runs through certified channel partners for government network eligibility under MIIT domestic encryption mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential through hybrid control convergence, where FPGA-locked external cavity architectures command premium positioning against pure analog alternatives.
For Market Incumbents: Lock in captive indium phosphide foundry capacity through long-term wafer supply agreements with Tsukuba and Suzhou operators, while accelerating GB-standard optical interface certification to maintain government backbone eligibility under MIIT mandates. Defensive positioning requires backward integration into substrate production and firmware architectures that resolve legacy DWDM backward-compatibility protocols.
For New Entrants and Emerging Players: Swept-source engines for optical coherence tomography represent a technology-first wedge with durable barriers from Japanese precision manufacturing standards and MFDS fast-track approval pathways. Target India's Bengaluru telecom corridor where TRAI 5G backhaul auctions and BIS phased manufacturing mandates create localized sourcing requirements underserved by established III-V foundries.
For Investors and Strategic Acquirers: Consolidation pressure builds where MOCVD reactor capacity constraints meet open optical networking procurement restructuring, favoring acquisitions of modular assembly specialists with qualified foundry relationships. Watch for inflection signals in MIIT spectrum auction timelines and carrier disaggregation commitment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into III-V Substrate Production | Captive wafer supply insulates margin compression from foundry allocation shocks during demand surges. |
| GB-Standard Optical Interface Certification | Domestic encryption module compatibility secures eligibility for China government backbone procurement. |
| Hybrid Digital-Analog Control Platform Launch | FPGA-locked architectures capture industrial sensing applications requiring sub-picometer wavelength stability. |
| MFDS Fast-Track Approval Pathway Investment | Accelerated ophthalmic diagnostic device certification opens South Korean swept-source market access. |
| Open Optical Networking Partnership | Interoperability certification with multi-vendor line systems displaces traditional turnkey procurement relationships. |
Study Parameters
Multiple input streams — primary interviews with MOCVD reactor operators, carrier procurement directors, and medical device regulatory affairs leads; secondary validation through MIIT spectrum allocation disclosures, METI subsidy program documentation, and TRAI auction records; plus customs data on III-V substrate trade flows — were reconciled through bottom-up and top-down triangulation.
Segmentation dimensions across technology architecture, application environment, and end-user procurement authority were modeled against coherent transceiver deployment trajectories and swept-source medical imaging adoption curves throughout the forecast period. CAGRs were derived from installed base turnover rates and replacement cycle compression in open networking environments, with specific inputs from indium phosphide foundry capacity utilization and JIS certification queue lengths.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to silicon photonics substitution velocity, III-V epitaxy talent migration patterns, and regulatory shifts in spectrum allocation and domestic content requirements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Global Optical Network Hardware Market
Optical Components
Objective Lens Market
Optical Components
Optical Transceiver Market
Optical Components
Europe Eye Tracking Solutions Market
Optical Components
Ring Panel Filters Market
Optical Components
Europe Optical Imaging Market
Optical Components
Optical Transmitter Market
Optical Components
US Lithium Niobate Modulator Market
Optical Components
Digital Cinema Lens Market
Optical Components
Global Adaptive Optics Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
Digital Optical Transmitter Market
Optical Components
Flip-Chip VCSEL Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Electronic Digital Magnifiers Market
Optical Components
LAMEA Lithium Niobate Modulator Market