
 Global Diffractive Optical Elements Market | 2026-2036
Global Diffractive Optical Elements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diffractive Optical Elements Market Intelligence
Custom design and integration services for complex optical systems is rewriting the value chain for diffractive optical elements. Jenoptik AG leverages its deep expertise in system-level solutions for industrial and life science markets. SUSS MicroOptics SA specializes in high-precision micro-optics manufacturing, serving niche applications. Meanwhile, Coherent Corp competes with a broad portfolio spanning lasers and photonic components for diverse end-uses.
A diffractive optical element is a component that utilizes micro-structured patterns to manipulate light through diffraction. These patterns, often created using photolithography on substrates like fused silica, enable functions impossible with traditional refractive optics. Beam splitters and phase gratings constitute mature product segments, while computer-generated holograms are gaining traction. Laser beam shaping remains the principal application, defining performance benchmarks for the entire industry.
Component quality and interoperability are governed by international standards such as ISO 10110. In Europe, products incorporating DOEs, like medical lasers or industrial machines, must comply with CE marking requirements. These regulations enforce stringent performance and safety criteria, influencing material selection and manufacturing processes. Stakeholder focus is now on mastering fabrication techniques for continuous relief and hybrid optics to meet future performance demands.
Market Dynamics
The diffractive optical elements market is defined by the dual pressures of consumer electronics demanding mass-produced, miniaturized components and specialized industrial sectors requiring highly customized, system-integrated solutions. This divergence shapes fabrication investment, material science, and design tool development across the industry.
Growth Catalysts
- Advanced Fabrication:New lithography techniques create continuous-relief DOEs with higher diffraction efficiency, improving performance in laser material processing and medical imaging.
- Aerospace Sector Demand:The push for lightweight optical systems in head-up displays and reconnaissance drones drives adoption, prioritizing performance and compactness over cost.
- China's Electronics Sector:China's vast electronics and laser manufacturing base creates concentrated demand for beam splitters, supported by national industrial policy.
Market Restraints
- High Fabrication Costs:Capital-intensive photolithography and mastering processes for custom designs create a cost barrier, limiting adoption in price-sensitive applications.
- Design Expertise Scarcity:Designing efficient computer-generated holograms requires specialized software and deep optical physics knowledge, creating an engineering talent bottleneck.
- Hybrid Optics Competition:Hybrid refractive-diffractive elements present a substitution threat, offering a performance-cost compromise that displaces pure DOEs in some optical systems.
Strategic Opportunities
- Consumer Electronics Miniaturization:Integrating DOEs into smartphone cameras, augmented reality glasses, and 3D sensing modules represents a significant volume opportunity.
- Quantum Information Systems:The convergence of photonics and quantum computing creates opportunities for DOEs in laser beam manipulation for ion trapping and cooling.
- Automotive LiDAR Adoption:Solidifying autonomous driving safety standards will drive demand for DOEs as essential beam-steering components in solid-state LiDAR systems.
Industry Challenges
- CE Marking and ISO Compliance:Navigating CE marking for medical devices in Europe and adhering to ISO 10110 for optical element quality requires extensive testing and documentation, extending product development timelines.
- Intellectual Property Navigation:The complex IP landscape around computer-generated hologram algorithms and fabrication processes creates licensing challenges and potential for disputes between design firms and manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diffractive Optical Elements Market |
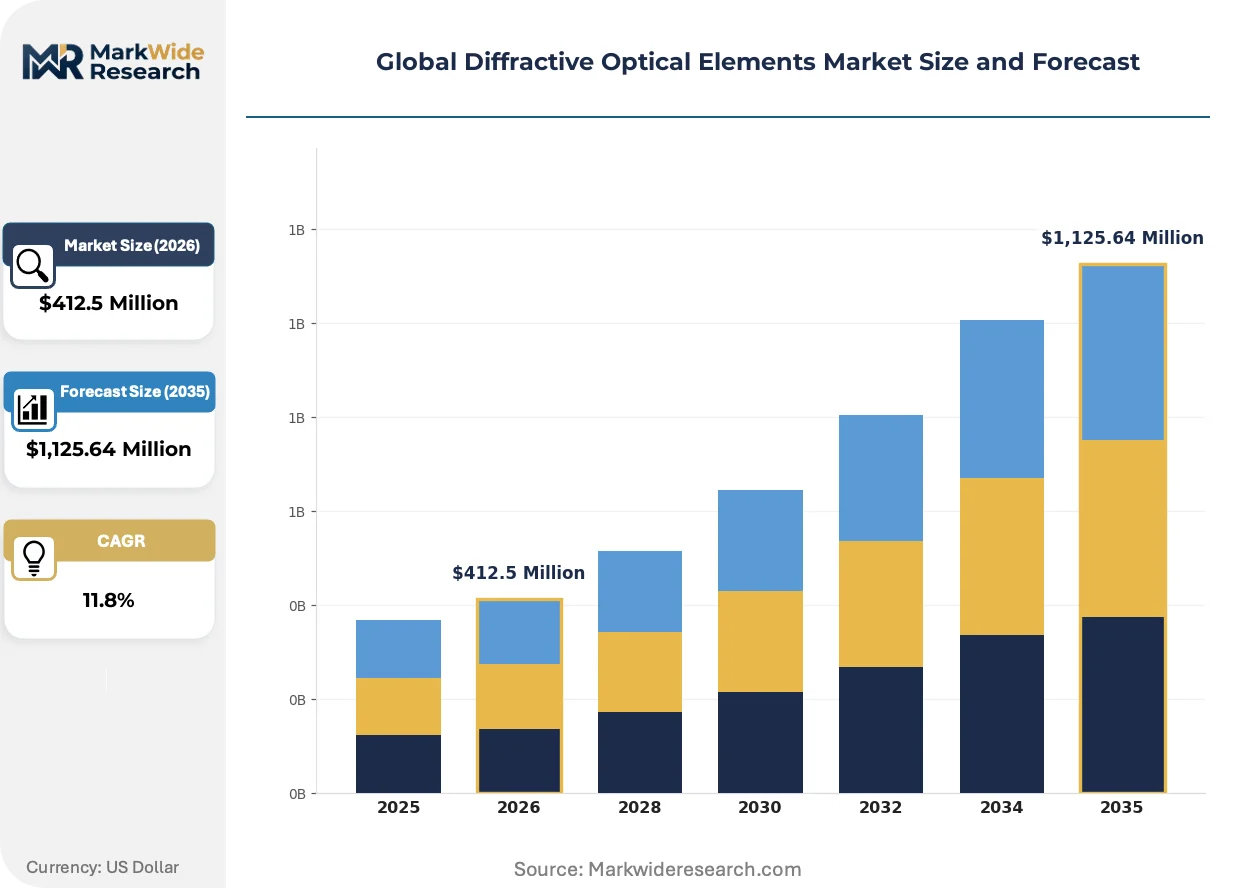
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,125.64 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phase Grating, Amplitude Grating, Computer Generated Holograms, Diffractive Lenses, Beam Splitters Technology: Binary Optics, Multilevel Optics, Continuous Relief, Hybrid Optics, Surface Relief Application: Laser Beam Shaping, Optical Data Storage, Spectroscopy, Optical Communication, Imaging Systems End User Industry: Telecommunications Providers, Aerospace Manufacturers, Defense Contractors, Research Institutions, Consumer Electronics Firms |
| Companies Covered | Jenoptik AG, Holo/Or Ltd, Zeiss Group, AGC Inc, Coherent Corp, SUSS MicroOptics SA, Edmund Optics Inc, Holoeye Photonics AG, Nalux Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diffractive Optical Elements Market Strategic Shifts & Innovations
A fundamental shift from selling discrete optical components to providing integrated, function-driven solutions is underway. This evolution prioritizes system-level performance and computational design, altering how value is created and captured in the diffractive optics supply chain.
Computer-generated holograms (CGHs) are diffractive elements that produce custom, arbitrary light distributions based on computational algorithms. Adoption is accelerating in semiconductor wafer inspection and laser-based additive manufacturing, where precise beam control is critical. This technology is virtualizing the function of multiple complex refractive lenses and mechanical components into a single, flat, lightweight optical surface.
Europe's CE marking requirements, particularly under the Medical Device Regulation (MDR), impose stringent safety and performance validation for products incorporating DOEs. This regulatory pressure forces manufacturers to invest in material traceability and documented process controls. Medical laser systems for ophthalmology and dermatology are most affected, leading to a preference for suppliers with established ISO 13485 quality management systems.
End-users in industrial and life science markets are increasingly seeking system-level design partnerships rather than purchasing off-the-shelf components. This model bypasses traditional component distributors, favoring direct engagement with manufacturers who offer co-design services. This trend is most visible in the development of custom microscopy illumination systems and industrial laser modules in Germany and Switzerland.
Global Diffractive Optical Elements Market Segmentation
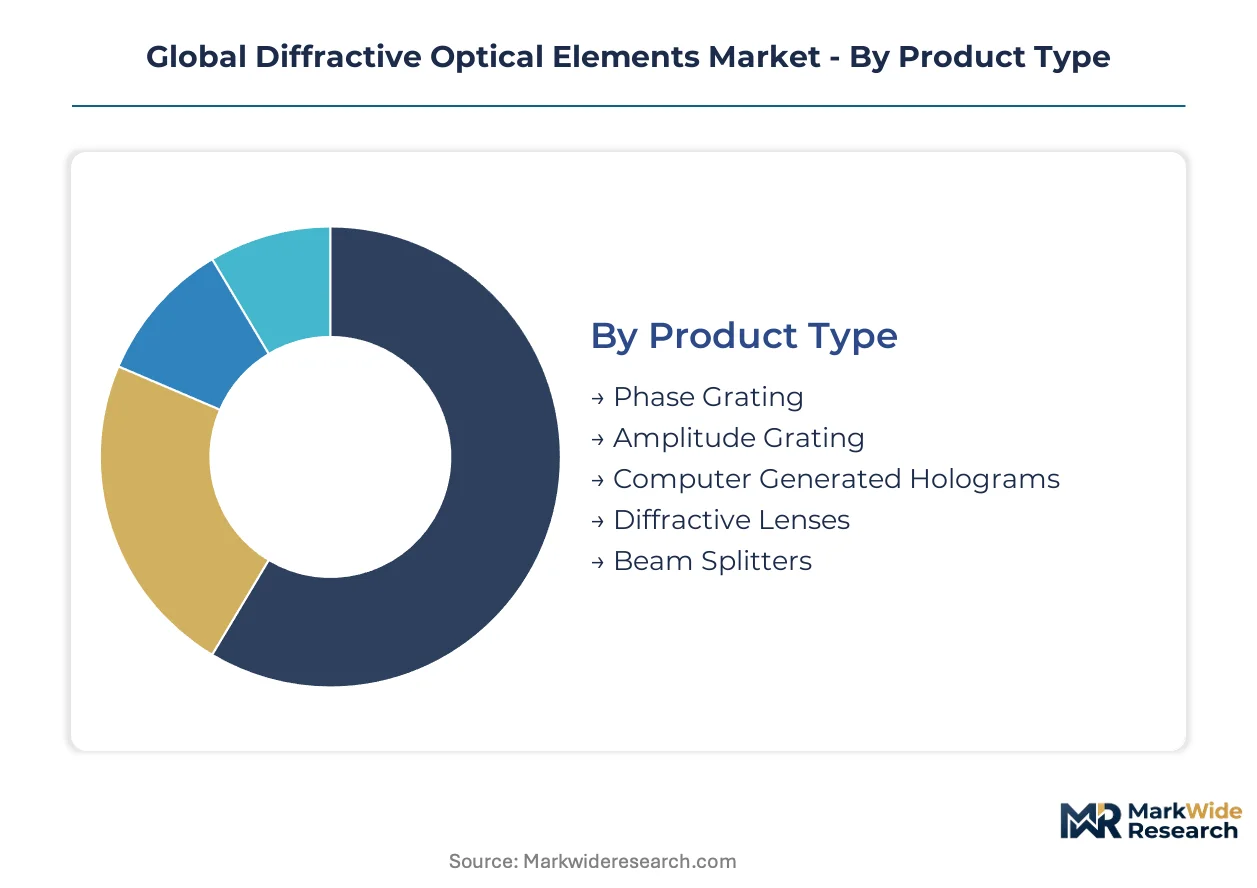
The global diffractive optical elements market segments reflect varying levels of technical complexity and integration requirements. Understanding these distinctions is critical for manufacturers to align product development with diverse end-user demands across industrial and consumer sectors.
Product Type:
The product type segmentation highlights varying after-sales service intensities, from standardized components to highly customized optical solutions. Each product offers distinct advantages in light manipulation for specific applications.
- Phase Grating:These elements alter the phase of incident light, creating specific diffraction patterns without absorbing light. Demand arises from optical metrology and spectroscopy applications requiring precise wavelength separation.
- Amplitude Grating:Amplitude gratings modify light intensity by absorption or blocking, producing diffraction patterns. They find use in calibration standards and educational optics where light attenuation is acceptable.
- Computer Generated Holograms:CGHs produce custom, arbitrary light distributions based on computational algorithms for precise beam control. Adoption is accelerating in semiconductor wafer inspection and laser-based additive manufacturing, where their ability to virtualize multiple refractive lenses into a single surface is prized.
- Diffractive Lenses:These lenses utilize diffraction to focus or disperse light, offering lightweight and compact alternatives to traditional refractive lenses. They are increasingly integrated into augmented reality glasses and compact imaging systems for miniaturization.
- Beam Splitters:Diffractive beam splitters divide an incident laser beam into multiple output beams with controlled intensity and angle. China's expansive electronics and laser manufacturing sectors create concentrated demand for these mature components, driving volume production.
By volume, Beam Splitters lead due to broad industrial adoption. By growth pace, Computer Generated Holograms are ahead, driven by advanced manufacturing requirements.
Technology:
The technological approaches in diffractive optical element fabrication influence supply chain concentration, with specialized processes dictating production capabilities. Each method presents unique manufacturing challenges and performance characteristics.
- Binary Optics:These optics use a series of etched steps to approximate a continuous phase profile, simplifying manufacturing processes. They provide cost-effective solutions for high-volume, less demanding applications.
- Multilevel Optics:Multilevel optics employ multiple lithographic and etching steps to create finer approximations of continuous profiles, offering improved diffraction efficiency. They serve industrial laser systems requiring enhanced performance over binary designs.
- Continuous Relief:Advanced lithography techniques create continuous-relief DOEs with smooth phase profiles, achieving higher diffraction efficiency and optical precision. These elements improve performance in laser material processing and medical imaging, where superior light manipulation is critical.
- Hybrid Optics:Hybrid refractive-diffractive elements combine the advantages of both optical principles to optimize performance and reduce system size. They present a substitution threat, offering a performance-cost compromise that displaces pure DOEs in some optical systems by balancing aberration correction and form factor.
- Surface Relief:Surface relief diffractive optics involve etching patterns directly onto a substrate surface, offering design flexibility. They are fundamental in creating gratings for spectroscopy and sensor applications.
Continuous Relief technologies offer superior performance for demanding applications. Hybrid Optics are gaining share by balancing optical performance with cost efficiency.
Application:
The application spectrum for diffractive optical elements reveals varying end-use intensity, from fundamental light manipulation to complex system integration. Each application leverages specific DOE characteristics to achieve desired optical outcomes.
- Laser Beam Shaping:This principal application uses DOEs to transform laser beam profiles into desired shapes, such as lines or flat-top distributions. It defines performance benchmarks for the entire industry, particularly in industrial laser cutting and welding.
- Optical Data Storage:DOEs manipulate light for reading and writing data in optical storage devices, enabling precise spot formation. This application requires high stability and repeatability for data integrity.
- Spectroscopy:Diffractive gratings disperse light into its constituent wavelengths, forming the core of many spectroscopic instruments. These elements are essential for chemical analysis and material characterization.
- Optical Communication:DOEs manage light signals in fiber optic networks, facilitating wavelength division multiplexing and signal routing. They enhance data transmission capacity and network efficiency.
- Imaging Systems:Integrating DOEs into imaging systems allows for aberration correction, field flattening, and compact designs, particularly in consumer electronics. The ongoing miniaturization of components for smartphone cameras and augmented reality glasses creates new design opportunities.
Laser Beam Shaping remains the foundational application. Imaging Systems demonstrate significant potential for future volume expansion.
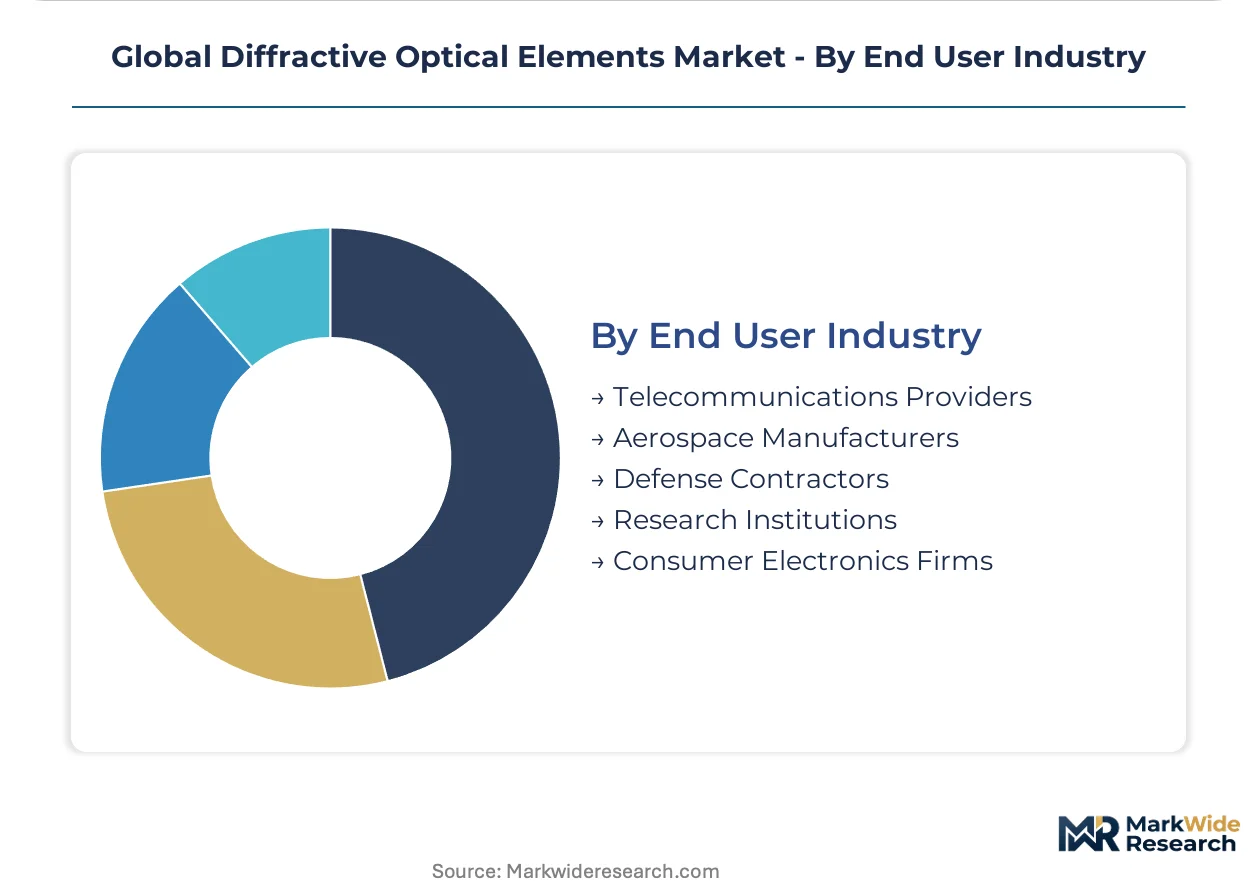
End User Industry:
The end user industry segmentation highlights distinct regulatory stringency levels, influencing material selection and manufacturing processes for diffractive optical elements. Each sector presents unique demands for performance and compliance.
- Telecommunications Providers:These firms integrate DOEs into optical network components for signal routing and management. Demand focuses on reliability and high data throughput for global communication infrastructure.
- Aerospace Manufacturers:The push for lightweight optical systems in head-up displays and reconnaissance drones drives adoption, prioritizing performance and compactness over cost. This sector requires components with extreme environmental durability and stringent qualification.
- Defense Contractors:DOEs are deployed in military targeting systems, night vision devices, and surveillance equipment, demanding robust performance in harsh conditions. Security and reliability are paramount for these applications.
- Research Institutions:Academic and private research entities utilize DOEs for experimental setups in quantum optics, advanced microscopy, and photonics development. This segment often drives innovation for next-generation DOE designs.
- Consumer Electronics Firms:Integrating DOEs into smartphone cameras, augmented reality glasses, and 3D sensing modules represents a significant volume opportunity. This segment demands mass-produced, miniaturized components with low unit costs, influencing fabrication investment.
Consumer Electronics Firms represent a major volume driver. Aerospace Manufacturers require highly specialized and durable diffractive optical elements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diffractive optical elements production is concentrated in key manufacturing hubs globally. China's expansive electronics and laser sectors drive significant demand for these components. Germany and the United States also play critical roles in advanced fabrication and specialized applications.
China
China's vast electronics and laser manufacturing base generates concentrated demand for diffractive beam splitters. National industrial policies support domestic production and technological advancement in this sector. The Yangtze River Delta region, with its numerous electronics factories, drives high-volume production and component integration. This supports the market for miniaturized optical components.
Germany
German industrial and life science markets require highly customized, system-integrated diffractive optical elements. Products incorporating DOEs must comply with CE marking requirements, especially under the Medical Device Regulation. Bavaria and Baden-Württemberg, home to advanced laser and optics firms, foster system-level design partnerships. These regions drive innovation in high-precision optical solutions.
United States
Demand from US aerospace manufacturers for lightweight optical systems in drones and head-up displays is substantial. Regulatory frameworks from the FAA ensure stringent performance and safety criteria for these specialized components. California and the Greater Boston area lead in research and development for quantum information systems. These clusters also drive innovation in solid-state LiDAR for autonomous vehicles.
Japan
Japan's semiconductor and advanced imaging industries demand high-precision diffractive optical elements for wafer inspection. Adherence to JIS standards ensures quality and interoperability for optical components across various applications. The Kanto and Kansai regions, with their strong electronics and optics clusters, specialize in micro-optics manufacturing. These areas focus on miniaturization for consumer electronics.
Global Diffractive Optical Elements Market Key Industry Players
Specialized system integrators and high-volume component manufacturers split the diffractive optical elements market. This structure reflects the dual pressures of customized industrial solutions and mass-produced consumer electronics components. Key strategic archetypes include precision micro-optics specialists focusing on niche applications and broad-portfolio photonic component providers serving diverse end-uses. Many firms pursue strategic partnerships to expand application reach and technology licensing for advanced fabrication techniques, while others focus on capacity expansion for volume segments.
Within the specialized system integration tier, Jenoptik AG, a German stock corporation, represents companies leveraging deep expertise in system-level solutions for industrial and life science markets. SUSS MicroOptics SA, a Swiss public limited company, exemplifies firms specializing in high-precision micro-optics manufacturing, often serving niche applications requiring extreme precision. Coherent Corp, an American corporation, anchors the broad-portfolio segment, providing a wide array of lasers and photonic components for diverse end-uses across multiple industries. These companies collectively illustrate the varied approaches to value creation and market positioning in the diffractive optics landscape.
| Leading Market Players |
|---|
| Jenoptik AG |
| Holo/Or Ltd |
| Zeiss Group |
| AGC Inc |
| Coherent Corp |
| SUSS MicroOptics SA |
| Edmund Optics Inc |
| Holoeye Photonics AG |
| Nalux Co Ltd |
| Others |
Cost & Logistics Intelligence
Intellectual property navigation creates a critical risk vector, significantly influencing both pricing tier spreads and the overall supply chain shape for diffractive optical elements. This complexity drives strategic decisions regarding product development and market entry.
Pricing Analysis
CE marking dictates the pricing tier structure for medical and industrial DOEs in Europe, enforcing performance and safety validation. Pricing stratifies across premium, standard, and economy tiers based on customization level and diffraction efficiency. Price differentiation stems from design complexity and after-sales service bundles. Pricing softness reflects competition from hybrid optics, particularly in cost-sensitive applications. Consumer electronics firms represent the most price-sensitive buyers, while aerospace manufacturers prioritize performance over unit cost.
Supply Chain Analysis
Specialized photolithography equipment and high-purity fused silica form the upstream feedstock for diffractive optical elements. Supply concentrates in Germany, Japan, and the United States for advanced fabrication, while China dominates high-volume production of standardized components. The industry depends on a limited number of suppliers for mastering tools, creating single-source vulnerability. Distribution runs through direct sales channels for custom, system-integrated solutions and component distributors for mass-market products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial capital expenditure drives the diffractive optical elements market, positioning it for a cyclical recovery phase. Strategic focus should leverage this renewed investment across key end-user sectors.
For Market Incumbents: Build deep system integration expertise to counteract the threat from hybrid optics competition. Expand custom design and co-development services for industrial and life science markets. Invest in continuous relief fabrication R&D to maintain performance leadership. Secure ISO 13485 certification to reinforce competitive positioning in regulated medical device segments.
For New Entrants and Emerging Players: Pursue niche applications requiring specialized optical physics knowledge, such as quantum information systems. Target underpenetrated segments like solid-state LiDAR for autonomous vehicles, offering innovative beam-steering solutions. A go-to-market angle focused on cost-effective, high-volume binary optics can capture share in China's electronics sector. Forge strategic partnerships to access advanced fabrication capabilities.
For Investors and Strategic Acquirers: The market sits at a growth acceleration phase that favors specialized technology providers with strong intellectual property. Focus on firms holding patents in computer-generated holograms or advanced hybrid optics. Long-term viability rests on increasing integration into miniaturized consumer electronics and high-performance industrial systems. Watch LiDAR adoption rates as a key inflection indicator for volume expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand continuous relief fabrication capacity | This enhances diffraction efficiency for demanding applications like medical imaging and laser material processing. |
| Develop system-level design partnerships | This captures value by providing integrated solutions rather than discrete components to industrial end-users. |
| Invest in computer-generated hologram algorithms | This enables precise beam control for semiconductor inspection and additive manufacturing, virtualizing complex optics. |
| Secure ISO 13485 certification | This ensures compliance for medical device components, opening access to regulated European markets. |
| Form strategic alliances for LiDAR integration | This positions companies to capitalize on the growing demand for autonomous driving safety systems. |
Research Approach
Operator-level perspectives from optical engineers, R&D directors, procurement managers, and regulatory compliance officers anchored the qualitative base for this study. Primary interviews with industry stakeholders were validated against secondary data from patent databases, academic journals, and industry association reports. This approach ensured a robust bottom-up and top-down triangulation of market insights.
Scenario-bracketing informed the quantitative forecast framework, mapping potential market trajectories across the projection horizon. Segmentation dimensions included product type, technology, application, end-user industry, and geographic region. Compound Annual Growth Rates were derived from historical data analysis and projected demand drivers, with inputs from consumer electronics production volumes and aerospace R&D budgets.
Sensitivities concentrate around technological breakthroughs, regulatory shifts, and global economic downturns, which could revise market forecasts. Forecasts reflect assumptions documented through extensive research and expert consultations. Cross-checking against external benchmark reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Transmitter Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market
Optical Components
Europe Scintillator Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
High Speed Fiber Optic Sensor Market
Optical Components
Global Fiber Bragg Grating Amplifier Market
Optical Components
Lithium Niobate Modulator Market
Optical Components
Silicon Photonics Market
Optical Components
Photointerrupter Market
Optical Components
Asia-Pacific Tunable Laser Market
Optical Components
Optical Encoder Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
Italy Lithium Niobate Modulator Market
Optical Components
ROADM WSS Component Market
Optical Components
Japan Lithium Niobate Modulator Market
Optical Components
Infrared Filter Market