
 Global Nitrogen Market | 2026-2036
Global Nitrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nitrogen Market Outlook
ISO 8573 air quality certification is redrawing competitive boundaries for industrial gas suppliers. Air Liquide leverages its integrated ammonia-to-nitrogen pipeline network across Western Europe to sustain margin advantages. Linde PLC anchors its position through captive hydrogen supply and large-scale cryogenic separation facilities in the US Gulf Coast. Yara International competes on agricultural-grade urea derivatives, dominating the farm-input channel with controlled-release formulations.
Nitrogen, the diatomic gas constituting 78% of atmospheric composition, is separated industrially via pressure swing adsorption or cryogenic distillation to achieve purities exceeding 99.999% for semiconductor and pharmaceutical applications. Its primary commercial purpose centers on ammonia synthesis via the Haber-Bosch process, which consumes over 80% of industrially fixed nitrogen for fertilizer production. Ammonia retains the largest value share among product types, though nitrates for explosives and water treatment command premium pricing in specialty channels. Fertilizer applications absorb the dominant volume, while industrial applications in electronics and metal treatment generate the highest per-unit margins.
The EPA enforces stringent emissions caps on US ammonia plants under the Clean Air Act, pushing producers toward carbon capture retrofits. REACH and the EU Green Deal mandate lifecycle carbon disclosures for nitrogen fertilizers sold in Europe, altering procurement criteria for agricultural distributors. China's MEE imposes dual carbon intensity thresholds on coal-based ammonia facilities, reshaping feedstock choices across Shandong and Inner Mongolia. Stakeholders must monitor how carbon border adjustment mechanisms redefine trade flows for urea and ammonia derivatives before committing to long-term offtake contracts.
Market Dynamics
The EU Green Deal's emissions trading framework and China's dual carbon goals are forcing ammonia producers to reconfigure feedstock choices and carbon capture investments. These regulatory pressures are redrawing competitive boundaries between coal-based, natural gas-based, and renewable hydrogen-derived nitrogen production pathways.
Growth Catalysts
- India's urea subsidy regime:Food security mandates sustain elevated offtake volumes from fertilizer manufacturers, anchoring demand growth in the world's most populous nation.
- ISO 8573 air quality certification:Semiconductor and pharmaceutical end-users now require ultra-high purity nitrogen, expanding addressable markets for industrial gas suppliers with certified separation capabilities.
- Pressure swing adsorption technology:Modular on-site nitrogen generation is displacing bulk liquid delivery in metal treatment and electronics fabrication facilities.
Market Restraints
- Natural gas price volatility:Feedstock costs constitute 70-80% of ammonia production expenses, compressing margins for Gulf Coast and North Sea producers during price spikes.
- Supply concentration in Shandong and Inner Mongolia:China's MEE carbon intensity thresholds threaten capacity rationalization at coal-based facilities serving regional derivatives markets.
- Technical limitation in cryogenic separation energy intensity:Conventional distillation requires 0.8-1.2 kWh per kilogram of nitrogen, creating a floor on production costs that renewable alternatives struggle to undercut.
Strategic Opportunities
- Brazil's agricultural expansion:Soybean and corn intensification in Mato Grosso and Goiás is driving ammonia demand for localized urea-ammonium nitrate production.
- Green hydrogen-ammonia convergence:Electrolyzer cost declines and renewable power purchase agreements are enabling carbon-free ammonia pilots in Scandinavia and Iberia.
- Direct ocean freight channel development:Bypassing traditional transshipment hubs, producers are chartering ammonia carriers to deliver directly to Indian and Southeast Asian port terminals.
Industry Challenges
- Process safety engineering talent scarcity:Haber-Bosch unit operations require specialized expertise that aging workforces in Germany and the US struggle to replenish.
- Carbon capture retrofit capex burdens:Post-combustion amine systems demand $150-250 million per ammonia train, straining balance sheets ahead of EU carbon border adjustments.
- REACH lifecycle disclosure compliance timelines:Agricultural distributors face compressed certification deadlines for nitrogen fertilizers sold into European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nitrogen Market |
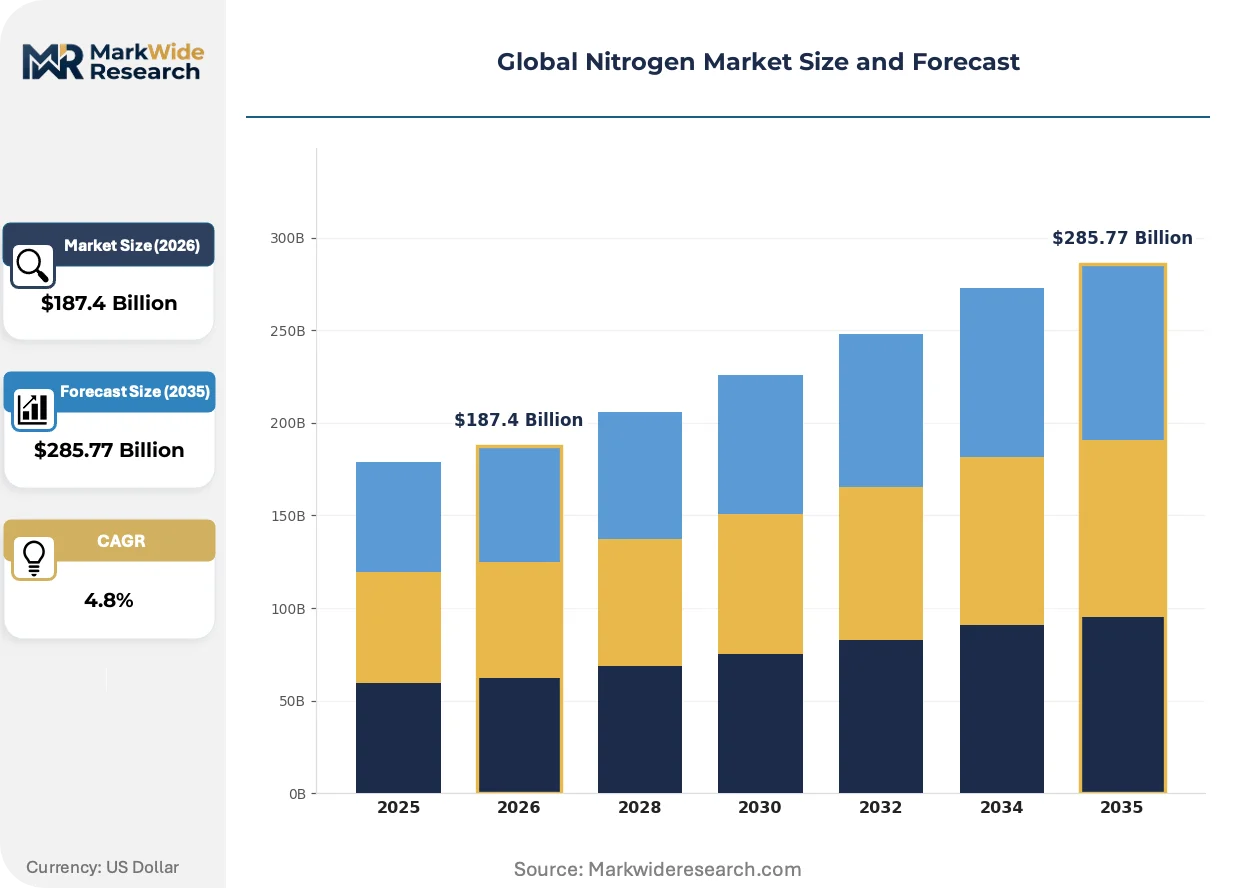
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ammonia, Urea, Nitrates, Nitrites End Use Industry: Agriculture, Chemical Manufacturing, Food Processing, Pharmaceuticals Distribution Channel: Direct Sales, Wholesale, Retail, Online Application: Fertilizers, Explosives, Industrial Applications, Water Treatment |
| Companies Covered | Air Liquide, Linde PLC, Air Products and Chemicals, Parker Hannifin Corp, Atlas Copco Group, Messer Group, Taiyo Nippon Sanso Corporation, Ingersoll Rand, Yara International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nitrogen Market Strategic Shifts
Electrification of ammonia synthesis and modular nitrogen generation systems are fragmenting traditional supply relationships between industrial gas majors and captive consumers. These shifts are compressing the scale economies that once protected regional incumbents.
Membrane separation technology for on-site nitrogen generation is fragmenting the bulk liquid distribution model that Air Liquide and Linde PLC built across Western Europe and the US Gulf Coast. Food packaging and electronics manufacturers now deploy skid-mounted pressure swing adsorption units with 95-99.9% purity output, eliminating cylinder delivery logistics and long-term take-or-pay contracts. The installed base of small-scale generators is compressing spot market liquidity for liquid nitrogen in industrial clusters.
REACH and the EU Green Deal's lifecycle carbon disclosure mandates are altering procurement criteria for agricultural distributors sourcing urea and ammonium nitrate. Buyers now require Scope 1-3 emissions documentation from ammonia producers, disqualifying coal-based supply from Shandong in favor of natural gas-derived product from Qatar and Trinidad. German and French farm cooperatives are consolidating purchasing volumes to secure certified-low-carbon nitrogen formulations.
Consolidation among Indian fertilizer importers is concentrating procurement leverage against Middle Eastern and Russian ammonia suppliers. State trading corporations and cooperative federations now negotiate annual offtake agreements with indexed pricing and destination flexibility clauses, displacing the spot cargo spot market that dominated trade through the 2010s. This buyer concentration is most visible in Kandla and Mundra port zones, where three entities control over 60% of urea import discharge capacity.
Global Nitrogen Market Segmentation
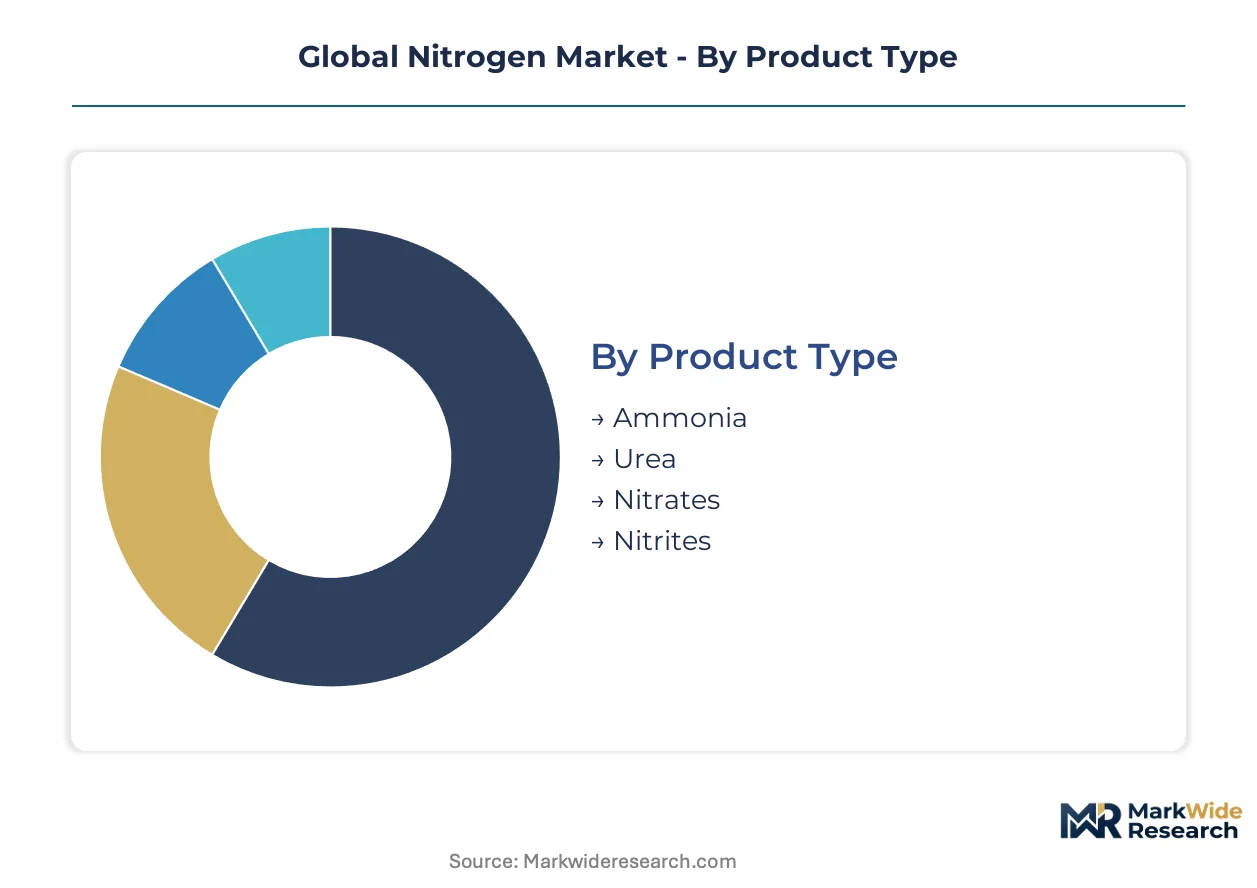
Nitrogen product flows diverge sharply across end-use specifications, with agricultural-grade ammonia and semiconductor-purity gas occupying entirely different value chains. Regulatory thresholds on carbon intensity and purity certification determine which producers can serve which segments, fragmenting what appears chemically uniform into commercially distinct markets.
Product Type:
REACH lifecycle disclosure rules and China's MEE carbon intensity thresholds are splitting product qualification pathways, with European and Asian regulators imposing incompatible certification burdens on chemically identical molecules.
- Ammonia:The Haber-Bosch synthesis output serves as the foundational feedstock for all downstream nitrogen derivatives. Demand concentrates in Indian fertilizer manufacturing, where urea subsidy regimes and food security mandates sustain elevated offtake volumes from domestic plants and import terminals alike.
- Urea:This solid derivative crystallizes from ammonia-carbon dioxide reaction, commanding the dominant volume share in agricultural applications. REACH and EU Green Deal mandates now require Scope 1-3 emissions documentation from producers, disqualifying coal-based supply from Shandong in favor of natural gas-derived product from Qatar and Trinidad.
- Nitrates:Ammonium nitrate and calcium nitrate formulations serve dual markets in fertilizers and explosives, with the latter commanding premium pricing in specialty mining and construction channels.
- Nitrites:Sodium and potassium variants function as corrosion inhibitors and food preservatives, with pharmaceutical-grade specifications requiring ISO 8573 air quality certification for medical gas applications.
Ammonia handles the majority of throughput; nitrates are expanding most quickly on share through explosives and water treatment specialty channels.
End Use Industry:
Cost tier differentiation separates bulk agricultural consumers from precision industrial buyers, with the latter paying multiples for certified purity and documented carbon footprint.
- Agriculture:Fertilizer manufacturers absorb over four-fifths of industrially fixed nitrogen, with Indian state trading corporations and cooperative federations consolidating procurement leverage against Middle Eastern and Russian suppliers.
- Chemical Manufacturing:Caprolactam and acrylonitrile producers require anhydrous ammonia feedstock at consistent specification, sourcing through long-term indexed contracts rather than spot cargo markets.
- Food Processing:Modified atmosphere packaging and freezing applications demand food-grade nitrogen with residual oxygen below specified thresholds, with on-site pressure swing adsorption units displacing bulk liquid delivery in large facilities.
- Pharmaceuticals:API synthesis and inerting operations require ultra-high purity nitrogen exceeding specifications, with semiconductor-grade suppliers extending certification downstream to capture pharmaceutical volumes.
Agriculture commands absolute volume dominance; pharmaceuticals generate the steepest margin expansion trajectory per kilogram consumed.
Distribution Channel:
Supply chain configuration determines access to certified-low-carbon product, with direct relationships to ammonia producers increasingly displacing intermediaries for carbon-accountable buyers.
- Direct Sales:Annual offtake agreements with indexed pricing and destination flexibility clauses now dominate Indian urea procurement, displacing the spot cargo market that characterized trade through the 2010s.
- Wholesale:Agricultural distributors in Germany and France are consolidating purchasing volumes to secure certified-low-carbon nitrogen formulations, squeezing independent intermediaries without emissions documentation capabilities.
- Retail:Farm supply cooperatives and garden center networks handle packaged urea and compound fertilizers for smallholder and consumer segments.
- Online:Industrial gas suppliers are piloting digital procurement platforms for cylinder and microbulk nitrogen, though agricultural volumes remain offline due to subsidy administration complexity.
Direct sales channels handle the majority of throughput; online platforms are climbing the fastest on share through industrial gas digitization pilots.
Application:
Margin structure inverts volume hierarchy, with fertilizer applications generating thin returns on massive throughput and industrial specialty uses capturing value on purity premiums.
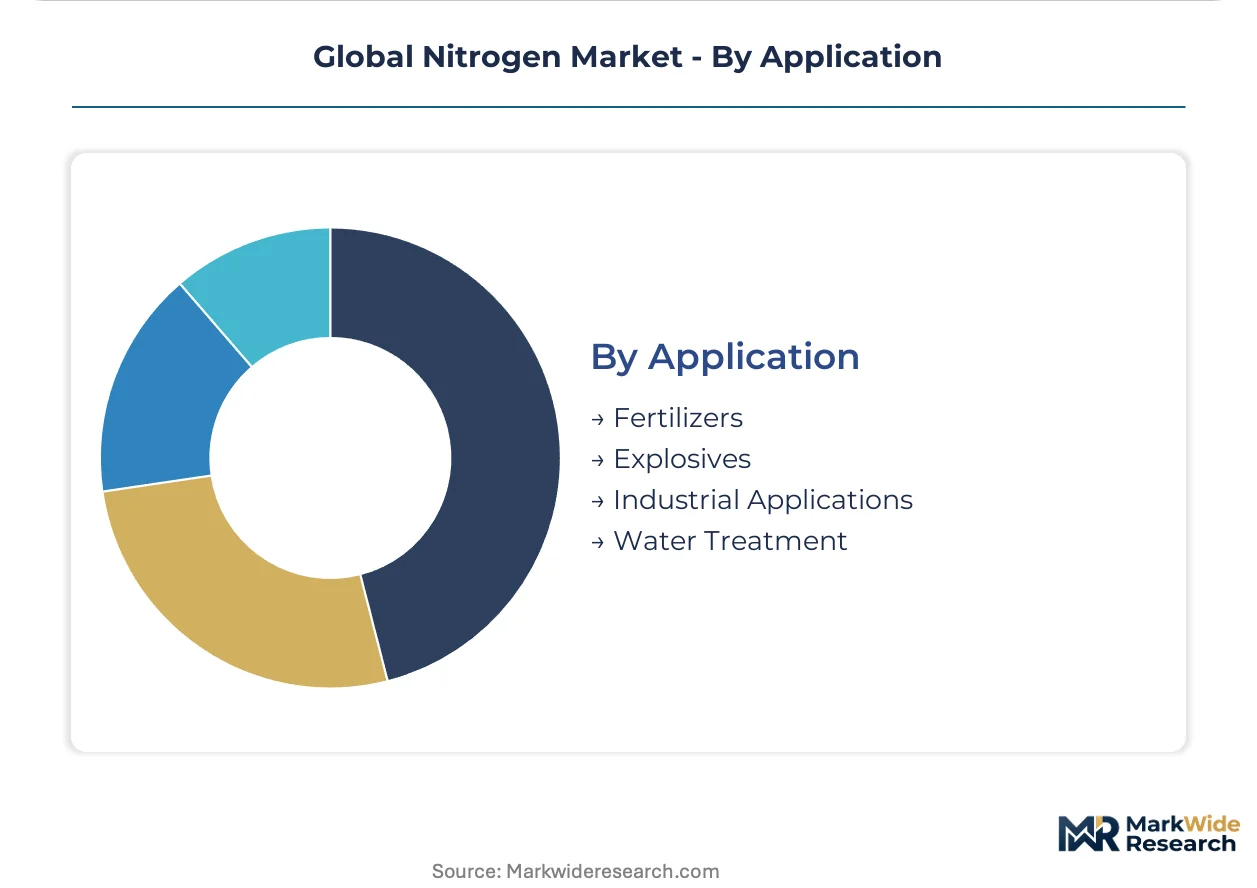
- Fertilizers:Urea, ammonium nitrate, and UAN solutions drive agricultural productivity across Brazil's Mato Grosso soybean belt and India's Indo-Gangetic plain, with localized production expanding to reduce import dependency.
- Explosives:Ammonium nitrate fuel oil and emulsion formulations serve mining operations in Australia's Pilbara and Canada's oil sands, with security regulations restricting distribution to licensed handlers.
- Industrial Applications:Metal treatment, electronics fabrication, and laser cutting operations deploy nitrogen for inerting and thermal processing, with ISO 8573 certification requirements fragmenting supplier qualification.
- Water Treatment:Nitrates for biological nutrient removal and nitrites for corrosion inhibition command specialty pricing in municipal and industrial wastewater systems.
Fertilizers handle the majority of throughput; industrial applications are gaining share fastest on semiconductor and metal treatment demand expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's urea subsidy regime and China's dual carbon goals are redrawing production and trade flows across the nitrogen value chain. Brazil's agricultural expansion and Germany's carbon border preparations are reshaping import procurement patterns. The United States maintains substantial Haber-Bosch capacity while navigating EPA emissions enforcement.
China
Coal-based ammonia facilities in Shandong and Inner Mongolia face MEE carbon intensity thresholds that threaten capacity rationalization. The dual carbon goals mandate feedstock switching toward natural gas and renewable hydrogen pilots. Producers in Ningxia and Shaanxi are trialing electrolyzer-integrated ammonia synthesis to retain market access under tightening export standards.
India
Food security mandates sustain elevated urea offtake from domestic plants and import terminals at Kandla and Mundra. State trading corporations and cooperative federations now control over sixty percent of discharge capacity, consolidating procurement leverage against Middle Eastern suppliers. The Department of Fertilizers administers subsidy disbursements that shield farm-gate prices from international ammonia volatility.
Brazil
Soybean and corn intensification in Mato Grosso and Goiás drives ammonia demand for localized urea-ammonium nitrate production. ANVISA regulates fertilizer quality standards while MAPA oversees import licensing for derivative products. Producers in Sergipe and Bahia are expanding ammonia terminal capacity to reduce dependency on Gulf Coast transshipment.
Germany
REACH lifecycle disclosure mandates and EU Green Deal carbon border adjustments are disqualifying coal-based urea imports from Shandong. Farm cooperatives in Lower Saxony and North Rhine-Westphalia consolidate purchasing volumes to secure certified-low-carbon nitrogen formulations. BASF and SKW Piesteritz operate the remaining domestic ammonia trains under ETS compliance pressure.
United States
Gulf Coast ammonia producers leverage abundant natural gas feedstock and carbon capture retrofit eligibility under the Inflation Reduction Act. EPA Clean Air Act enforcement pushes facilities toward post-combustion amine systems at Texas and Louisiana complexes. The US Gulf maintains export competitiveness through integrated pipeline networks serving Caribbean and Latin American derivatives markets.
Global Nitrogen Market Competitive Environment
Player mix skews toward integrated industrial gas majors with captive hydrogen supply and cryogenic separation infrastructure. Market structure concentrates around three to four vertically positioned suppliers controlling pipeline networks and large-scale production trains. Strategic archetypes include global industrial gas integrators, regional ammonia specialists with agricultural channel dominance, and modular on-site generator fabricators disrupting bulk liquid distribution. Competitive moves center on carbon capture retrofit partnerships and direct ocean freight channel development bypassing traditional transshipment hubs.
Among European-integrated industrial gas suppliers, Air Liquide and Linde PLC exemplify the pipeline-network archetype with ammonia-to-nitrogen infrastructure across Western production corridors. Yara International occupies a position representing agricultural-grade specialists competing on controlled-release formulations and farm-input channel penetration. These three anchors illustrate how certification capabilities and feedstock integration separate premium-tier positioning from commodity ammonia trading.
| Leading Market Players |
|---|
| Air Liquide |
| Linde PLC |
| Air Products and Chemicals |
| Parker Hannifin Corp |
| Atlas Copco Group |
| Messer Group |
| Taiyo Nippon Sanso Corporation |
| Ingersoll Rand |
| Yara International |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon border adjustments and ISO 8573 air quality certification simultaneously gate supply qualification and price differentiation in nitrogen markets. Agricultural distributors now pay premiums for documented low-carbon ammonia while semiconductor fabs absorb surcharges for ultra-high purity grades.
Pricing Analysis
Certification level creates the primary spread between agricultural-grade ammonia and semiconductor-purity nitrogen. Pricing stratifies across premium, standard, and economy tiers based on carbon intensity documentation and purity thresholds. Cost compression in standard-grade urea is intensifying because Indian state trading corporations consolidate procurement leverage. Bulk fertilizer manufacturers exhibit highest price sensitivity while pharmaceutical and electronics buyers absorb purity premiums with minimal negotiation.
Supply Chain Analysis
Port congestion at Kandla and Mundra and container availability constraints on the Middle East-India trade lane elevate inbound logistics costs for ammonia importers. Production concentrates in China, Qatar, and Trinidad, with feedstock choices determining carbon intensity profiles. Supply chains rest on natural gas price volatility and coal-based capacity rationalization risks in Shandong. Distribution runs through direct annual offtake agreements with destination flexibility clauses, displacing spot cargo markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon disclosure mandates fragment nitrogen markets into specialty niches. Precision agriculture and semiconductor fabrication create divergent demand profiles that reward targeted positioning.
For Market Incumbents: Fortify pipeline network control across Western Europe and captive hydrogen supply positions on the US Gulf Coast. Carbon capture retrofit partnerships with ammonia producers defend margin position against EU carbon border adjustments. Certification investment in ISO 8573 separation capabilities protects semiconductor-grade market access. For New Entrants and Emerging Players: Differentiate on modular pressure swing adsorption systems for on-site nitrogen generation in Brazilian agricultural processing and Indian metal treatment clusters. Target food packaging and electronics fabrication facilities seeking to eliminate cylinder delivery logistics. Go-to-market through equipment leasing with purity-guaranteed service contracts. For Investors and Strategic Acquirers: EU ETS phase-in and carbon border adjustment mechanisms reshape the acquisition landscape toward low-carbon ammonia assets. Five-to-ten year viability favors natural gas-based producers with carbon capture eligibility or renewable hydrogen integration pilots. Watch for MEE enforcement actions against Shandong coal-based facilities as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Partnership | Post-combustion amine systems at Gulf Coast ammonia trains secure IRA tax credit eligibility. |
| Direct Ocean Freight Channel Development | Ammonia carriers bypassing transshipment hubs reduce landed costs at Indian port terminals. |
| Green Hydrogen-Ammonia Integration | Electrolyzer-integrated synthesis in Scandinavia enables carbon-free product qualification under EU Green Deal. |
| Modular On-Site Generation Deployment | Skid-mounted pressure swing adsorption units displace bulk liquid distribution in electronics clusters. |
| Procurement Consolidation Alliance | German and French farm cooperatives secure certified-low-carbon nitrogen through volume aggregation. |
Study Parameters
The analysis maps ammonia synthesis, cryogenic separation, pressure swing adsorption, and membrane technology sub-sectors, each validated through plant managers, procurement leads at fertilizer manufacturers, distribution channel partners, and technical R&D directors. Primary interviews with industrial gas suppliers and agricultural distributors combined with customs/trade data, SEC 10-K filings, national emissions registries, and IEA ammonia tracking databases. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Consistency checks against external benchmarks validated output ranges across the projection horizon. Segmentation dimensions include product grade tier, end-use industry, distribution channel format, and regional production hub. CAGRs derive from feedstock cost trajectory modeling and regulatory compliance timeline analysis. Forecast inputs incorporate natural gas price volatility scenarios and carbon intensity threshold enforcement schedules.
Material uncertainties — MEE enforcement intensity, EU carbon border adjustment implementation scope, electrolyzer cost decline curves — sit outside the modeled envelope. Forecasts reflect assumptions about subsidy continuity in India and trade flow redirection from coal-based supply regions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
High Purity Gas Market
Industrial Gases
Industrial Gases for Metals and Metal Fabrication Market
Industrial Gases
Commercial Hydrogen Market
Industrial Gases
Argon Gas Market
Industrial Gases
Neon Gas for Laser Market
Industrial Gases
Sulfur Recovery Tail Gas Analyzer Market
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Middle East Industrial Gas Market
Industrial Gases
Global Argon Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
Gas and Liquid Argon Market
Industrial Gases
Industrial Hydrogen Market
Industrial Gases
Xenon Gas Market