
 Ultra-High Purity Materials Market | 2026-2036
Ultra-High Purity Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-High Purity Materials Market Outlook
Subscription-based purity certification and real-time batch monitoring is repositioning how ultra-high purity materials get sold, shifting revenue from one-time product sales to ongoing compliance services. The Quartz Corporation leverages vertical integration from mine to final purification to control supply security for semiconductor-grade quartz. Jiangsu Pacific Quartz Co., Ltd anchors high-volume production of crucibles and tubing for Chinese solar and chip fabs. Wolfspeed, Inc. specializes in silicon carbide substrate purity for power electronics, competing on material consistency rather than commodity chemistry.
Ultra-high purity materials are substances refined to impurity levels below one part per billion, achieved through multi-stage distillation, zone refining, or chemical vapor purification processes that eliminate metallic ions, organics, and particulates. These materials serve as non-negotiable inputs in semiconductor lithography, pharmaceutical synthesis, and aerospace propulsion where trace contamination destroys yield or safety. Gases dominate value capture due to the complexity of achieving six-nines purity in corrosive or reactive chemistries like fluorinated etchants. Semiconductor verticals command the deepest specification requirements, with node shrinkage below three nanometers pushing research-grade materials into mainstream production. Ultra-pure grade segments carry the widest margin pools because qualification cycles lock customers into single-source supply agreements for five to seven years.
EPA enforces Maximum Achievable Control Technology standards for volatile organic compound emissions at U.S. purification plants, while REACH mandates full substance registration and hazard communication for chemicals imported into the European Union. China's SAMR implements GB standards for electronic-grade materials that foreign suppliers must meet to access domestic foundry supply chains. Semiconductor manufacturers, pharmaceutical formulators, and materials distributors must monitor how tightening purity thresholds in one jurisdiction trigger harmonization pressure across all qualified supply bases.
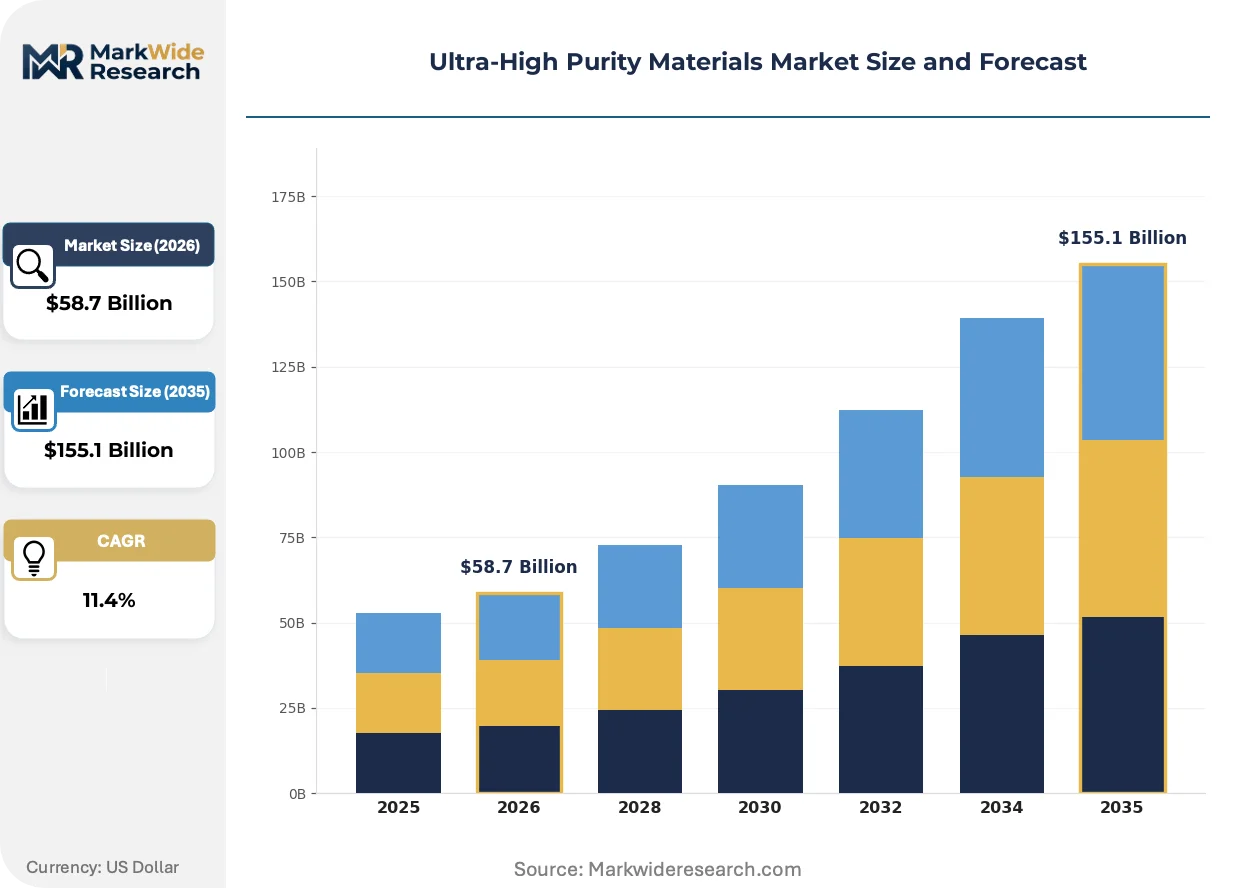
Market Dynamics
Semiconductor node shrinkage below three nanometers is forcing foundries to recertify entire chemical supply chains at parts-per-trillion thresholds, locking suppliers into multi-year qualification cycles that reshape competitive moats.
Growth Catalysts
- Advanced Node Proliferation:Taiwan and South Korea foundries are expanding three-nanometer and two-nanometer capacity, multiplying demand for six-nines purity gases and wet chemicals in lithography and etch processes.
- REACH Impurity Threshold Tightening:ECHA mandates are pushing parts-per-billion specifications toward parts-per-trillion for electronic-grade materials imported into European Union member states.
- Solar-to-Semiconductor Pivot:Chinese polysilicon purification infrastructure is redirecting capacity toward semiconductor-grade silicon as photovoltaic margins compress.
Market Restraints
- Helium Supply Concentration:Qatar and the United States control over eighty percent of global helium extraction, creating vulnerability for cryogenic purification processes dependent on supercooling.
- Capital Intensity of Zone Refining:Multi-stage zone refining equipment for germanium and silicon purification requires seven-figure capital deployment per production line with decade-long depreciation cycles.
- Substitution Pressure from Silicon Carbide:Wolfspeed and II-VI are advancing silicon carbide substrate alternatives that reduce reliance on ultra-pure silicon in power electronics applications.
Strategic Opportunities
- Indian Semiconductor Mission Incentives:India's PLI scheme for semiconductor manufacturing is attracting purification plant investments to serve emerging foundry clusters in Gujarat and Tamil Nadu.
- Real-Time Batch Monitoring Services:IoT-enabled purity certification platforms are creating recurring revenue streams alongside traditional chemical sales to pharmaceutical formulators.
- Gallium Nitride Epitaxy Expansion:RF and power electronics manufacturers are qualifying new ultra-pure precursor chemistries for GaN-on-silicon growth processes.
Industry Challenges
- Specialized Metrology Talent Scarcity:ICP-MS and gas chromatography operators with parts-per-trillion detection expertise command premium wages as semiconductor fabs compete for limited personnel pools.
- Cross-Border Certification Harmonization:Suppliers must simultaneously satisfy EPA Maximum Achievable Control Technology, REACH substance registration, and China's SAMR GB standards without unified testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-High Purity Materials Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $155.1 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Gases, Solvents, Liquids, Powders Industry Vertical: Semiconductor, Pharmaceuticals, Biotechnology, Aerospace Grade: Ultra-Pure, Research Grade, Analytical Grade, Technical Grade Packaging Type: Drums, Bottles, Cylinders, Bulk Packaging |
| Companies Covered | The Quartz Corporation, Toyo Tanso Co., Ltd., Australian Silica Quartz Group Ltd, Mersen, Superior Graphite, Jiangsu Pacific Quartz Co., Ltd, SGL Carbon, Wolfspeed, Inc., Sibelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-High Purity Materials Market Strategic Shifts
Process analytical technology and continuous purification systems are displacing batch-oriented production, compressing lead times while enabling real-time impurity detection that prevents entire lot rejections.
Point-of-use purification skids are modularizing how semiconductor fabs receive process gases, collapsing the traditional separation between bulk chemical delivery and final polishing stages. Leading foundries in Taiwan are installing these units directly at lithography tool hookups. This architecture is modularizing supplier relationships by letting fabs mix bulk commodity feedstock with specialized final-filtration vendors rather than relying on single-source six-nines providers.
EPA enforcement of Maximum Achievable Control Technology standards for volatile organic compound emissions is tightening at U.S. purification plants, forcing capital upgrades to thermal oxidizers and carbon capture systems. The compliance burden falls heaviest on mid-scale fluorinated gas producers serving etch applications. These operators are consolidating distillation capacity into fewer, larger facilities to amortize environmental control investments across higher throughput.
Subscription-based purity certification is displacing traditional certificate-of-analysis documentation as pharmaceutical and semiconductor buyers demand continuous batch monitoring rather than point-in-time testing. Distributors serving North American biopharma clusters are building in-house analytical laboratories to capture this service revenue. This shift is most visible in Boston and San Francisco metro areas where contract manufacturers now specify real-time data feeds as contract terms.
Ultra-High Purity Materials Market Segmentation
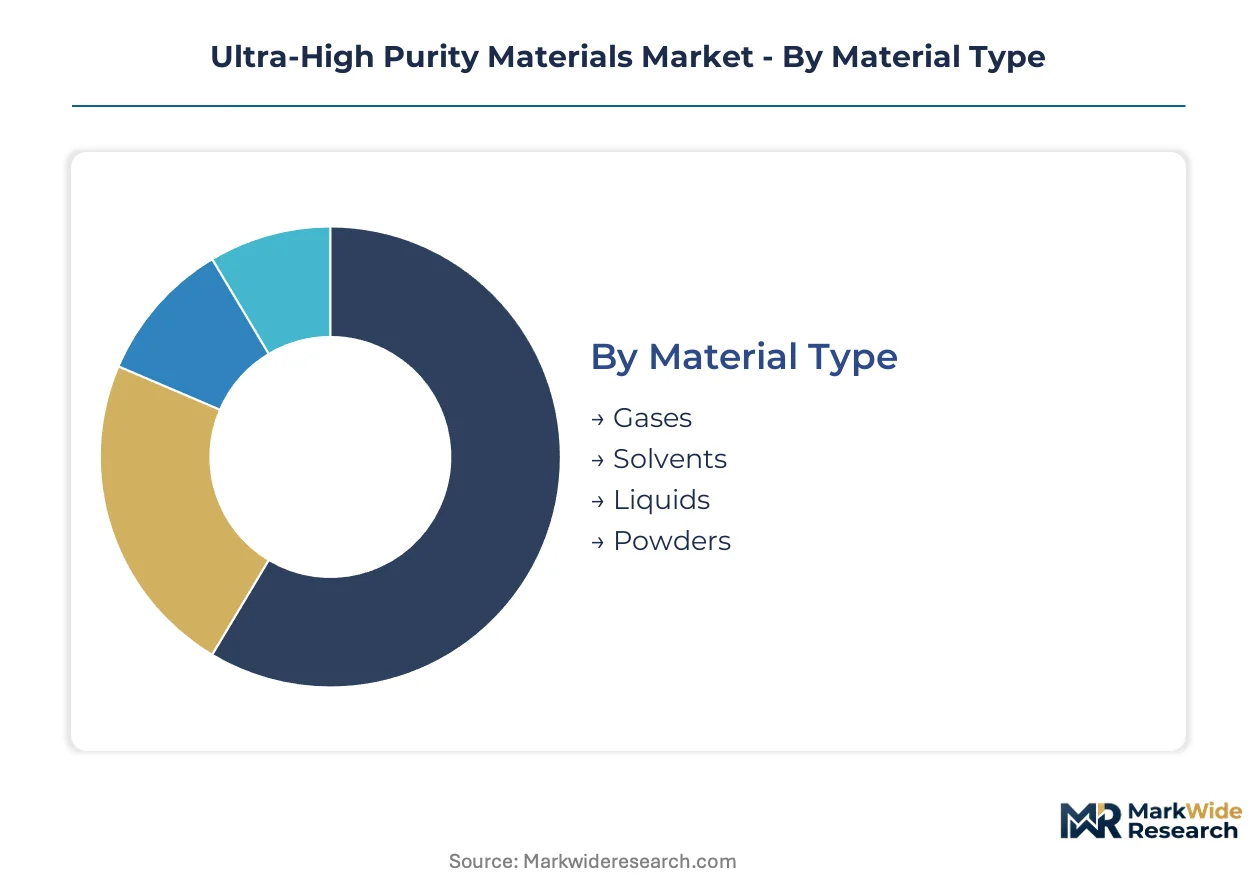
Ultra-high purity materials demand fragments across material states, end-use tolerances, and delivery formats that each impose distinct purification and logistics requirements. Segmentation reveals where specification intensity creates pricing power versus where commoditization pressures dominate procurement.
Material Type:
Standalone purification systems handle gases and powders in discrete processing steps, while liquids and solvents integrate into continuous manufacturing lines requiring point-of-use polishing.
- Gases:Achieving six-nines purity in fluorinated etchants and dopant gases demands multi-stage cryogenic distillation with helium-cooled separation trains. Taiwan and South Korea foundries now specify parts-per-trillion thresholds for lithography process gases, locking qualified suppliers into exclusive supply agreements.
- Solvents:Electronic-grade isopropyl alcohol and N-methyl-2-pyrrolidone require molecular sieve dehydration and sub-micron filtration to eliminate metallic ion contamination. Chinese polysilicon producers are redirecting solvent purification capacity toward semiconductor specifications as photovoltaic margins compress.
- Liquids:Wet chemicals for wafer cleaning and etching integrate directly into fab chemical delivery systems.
- Powders:High-purity metal oxides and ceramic precursors serve powder metallurgy and additive manufacturing feedstock requirements.
Volume placements concentrate in Gases; the faster expansion belongs to Solvents.
Industry Vertical:
Cost tier stratification separates node-driven semiconductor specifications from batch-oriented pharmaceutical compliance requirements.
- Semiconductor:Sub-three-nanometer lithography and atomic layer deposition processes mandate impurity control below one part per billion, with qualification cycles extending five to seven years. Taiwan Semiconductor Manufacturing and Samsung Foundry are expanding three-nanometer capacity, multiplying demand for six-nines purity materials across etch, deposition, and cleaning steps.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and formulation require USP-grade solvents and excipients with documented batch pedigree for FDA submission packages. Boston and San Francisco biopharma clusters now specify real-time purity data feeds as standard contract terms.
- Biotechnology:Cell culture media and chromatography reagents demand endotoxin-free certification with protein content below detectable thresholds.
- Aerospace:Propulsion system fuels and thermal protection materials require ultra-low particulate contamination for combustion stability.
Revenue concentration sits with Semiconductor; Biotechnology climbs the fastest as cell and gene therapy manufacturing scales.
Grade:
Margin pools deepen with certification stringency, separating qualified supply agreements at the ultra-pure tier from catalog sales at technical grades.
- Ultra-Pure:Sub-part-per-billion impurity specifications with full batch traceability and single-source qualification requirements. Semiconductor fabs below three-nanometer nodes now demand parts-per-trillion certification for critical process materials, extending supplier lock-in periods.
- Research Grade:High-purity materials for analytical method development and process characterization with documented assay certificates.
- Analytical Grade:Standardized purity for routine quality control and environmental testing applications.
- Technical Grade:Baseline purity for industrial processes where contamination tolerance permits higher impurity ceilings.
Pricing power concentrates in Ultra-Pure; Research Grade gains share fastest as contract manufacturers internalize analytical capabilities.
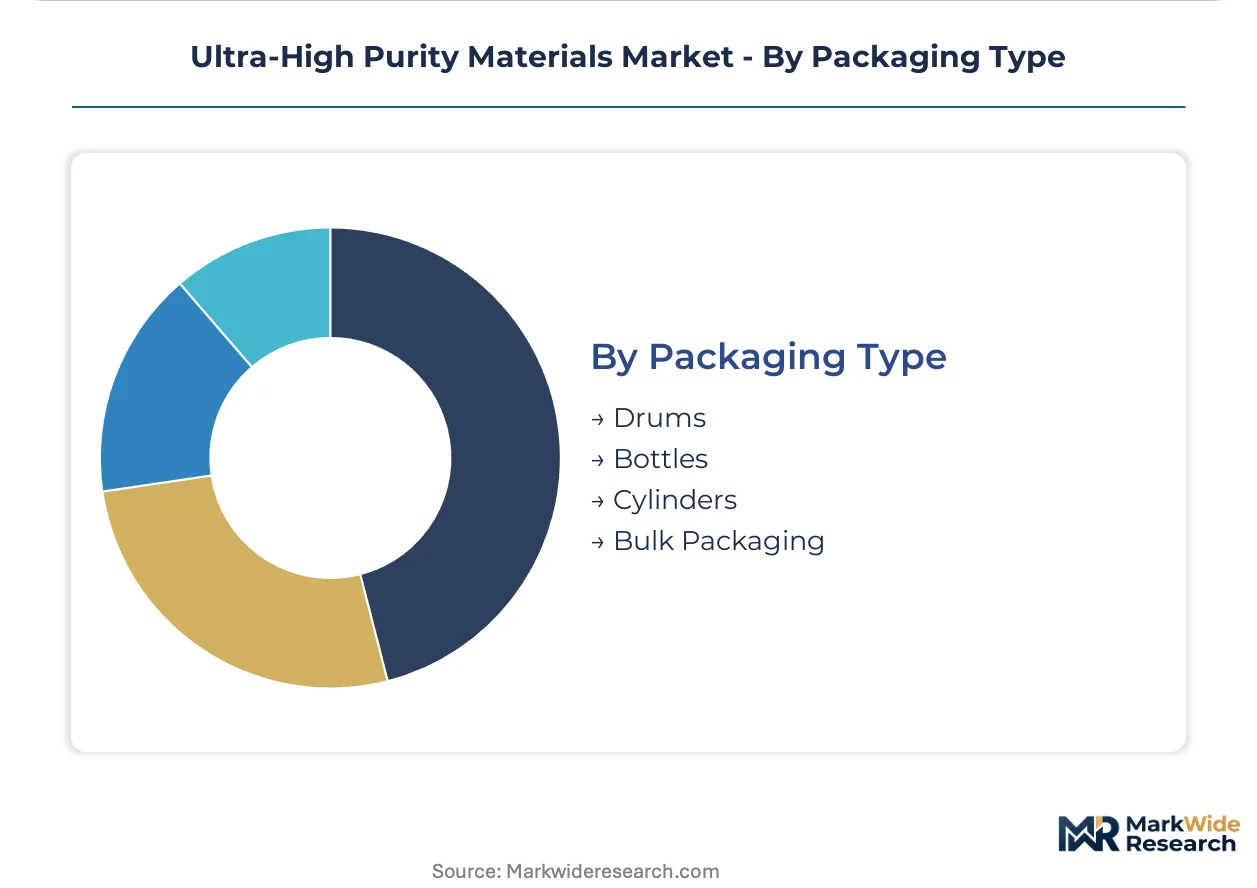
Packaging Type:
Supply concentration varies with container complexity, from standardized drum logistics to specialized cylinder handling for reactive gases.
- Cylinders:High-pressure containment for corrosive and pyrophoric gases with specialized valve configurations and internal surface passivation. Taiwan foundries are installing point-of-use purification skids that accept commodity cylinder feedstock, modularizing final polishing from bulk delivery.
- Bulk Packaging:ISO tank and tube trailer delivery for high-volume solvents and liquefied gases with integrated sampling ports.
- Drums:Standardized liquid containment for solvents and wet chemicals with liner options for moisture-sensitive materials.
- Bottles:Small-format containment for laboratory-scale procurement and just-in-time dispensing systems.
Shipment volumes concentrate in Cylinders; Bulk Packaging expands most quickly as foundries consolidate chemical delivery infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of solar-grade polysilicon feedstock while Taiwan and South Korea fabs consume the most stringent semiconductor-grade materials, creating a geographic split between bulk purification capacity and advanced node demand.
United States
EPA Maximum Achievable Control Technology enforcement tightens volatile organic compound limits at domestic purification plants, forcing thermal oxidizer upgrades. The CHIPS Act funds new Arizona and Texas foundry clusters where suppliers must certify materials at parts-per-trillion thresholds. Boston biopharma manufacturers now specify real-time purity data feeds as standard procurement terms.
China
SAMR GB standards for electronic-grade materials block foreign suppliers lacking domestic certification, while polysilicon producers redirect solar capacity toward semiconductor specifications. Yangtze River Delta foundries in Shanghai and Wuxi expand three-nanometer pilot lines. Jiangsu Pacific Quartz anchors high-volume crucible production for indigenous chip fabrication.
Taiwan
TSMC and United Microelectronics expand three-nanometer capacity at Tainan and Hsinchu Science Parks, multiplying demand for six-nines purity gases. Point-of-use purification skids now accept commodity cylinder feedstock, modularizing final polishing from bulk delivery. Local chemical distributors build in-house analytical laboratories to capture subscription-based certification revenue.
South Korea
Samsung Foundry and SK Hynix advance two-nanometer research at Pyeongtaek and Icheon complexes, extending supplier qualification cycles to seven years. The national semiconductor strategy subsidizes domestic precursor chemistry development. Korean gas distributors consolidate cylinder handling infrastructure to amortize helium-cooled distillation investments.
Germany
REACH substance registration mandates push electronic-grade import specifications toward parts-per-trillion, harmonizing with ECHA enforcement trends. BASF and Merck KGaA operate integrated purification complexes in Ludwigshafen and Darmstadt. Frankfurt-area pharmaceutical formulators demand full batch pedigree documentation for FDA-aligned submission packages.
Ultra-High Purity Materials Market Competitive Environment
Capital-heavy producers compete with asset-light designers across distinct value chain positions, with integrated miners and specialized refiners occupying separate competitive tiers. The structure concentrates around three archetypes: vertically integrated quartz miners controlling mine-to-final-purification pipelines, carbon and graphite specialists serving high-temperature process applications, and compound semiconductor substrate producers competing on material consistency. Dominant competitive moves include backward integration into raw material extraction and geographic expansion toward emerging foundry clusters in India and Southeast Asia.
Within the integrated mining tier, The Quartz Corporation exemplifies captive supply control from extraction through semiconductor-grade finishing. Among Asia-Pacific fabricators, Jiangsu Pacific Quartz Co., Ltd and Toyo Tanso Co., Ltd occupy positions spanning high-volume production and specialized carbon materials respectively. Wolfspeed, Inc. anchors the compound semiconductor substrate segment where silicon carbide purity standards create distinct qualification barriers from commodity chemistry markets.
| Leading Market Players |
|---|
| The Quartz Corporation |
| Toyo Tanso Co., Ltd. |
| Australian Silica Quartz Group Ltd |
| Mersen |
| Superior Graphite |
| Jiangsu Pacific Quartz Co., Ltd |
| SGL Carbon |
| Wolfspeed, Inc. |
| Sibelco |
| Others |
Value Chain & Pricing Dynamics
EPA Maximum Achievable Control Technology enforcement gates both qualified supply and premium-tier pricing access for fluorinated gas producers, forcing thermal oxidizer upgrades that consolidate distillation capacity into fewer, larger facilities capable of amortizing environmental controls across higher throughput.
Pricing Analysis
Margin tightening in ultra-pure grades reflects five-to-seven-year qualification cycles that lock semiconductor fabs into single-source supply agreements. Three-tier pricing structure across ultra-pure, research, and technical grades separates parts-per-trillion certified materials from catalog sales. Cost-down pressure on technical grades accelerates because Chinese polysilicon producers redirect solar capacity toward semiconductor specifications. Pharmaceutical formulators in Boston and San Francisco show least price sensitivity due to FDA submission batch pedigree requirements.
Supply Chain Analysis
Return flows of spent cylinders and refurbishment of high-pressure containment systems create reverse logistics value capture for gas distributors consolidating handling infrastructure. Supply concentrates in Taiwan, South Korea, and China, with helium extraction anchored in Qatar and the United States for cryogenic separation trains. Production draws from high-purity quartz mines in North Carolina and Jiangsu province, plus fluorinated precursor chemistries from German integrated complexes. Single-source vulnerability runs through helium-dependent cryogenic distillation. Distribution runs through point-of-use purification skids at Taiwan foundries mixing bulk feedstock with specialized final-filtration vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive quartz mining and helium-cooled separation infrastructure defines the vertical-integration race, with qualification cycle duration serving as the decisive downstream lever.
For Market Incumbents: Extend qualification lock-in periods by investing in real-time batch monitoring platforms that pharmaceutical formulators now specify as contract terms. Consolidate cylinder handling infrastructure to amortize helium-cooled distillation investments across higher throughput, defending against substitution pressure from silicon carbide substrates in power electronics applications.
For New Entrants and Emerging Players: Capture India's PLI scheme incentives for purification plant investments serving Gujarat and Tamil Nadu foundry clusters. Target gallium nitride epitaxy precursor chemistries as the most penetrable segment, where RF and power electronics manufacturers are qualifying new ultra-pure materials. Pursue joint development agreements with emerging foundries before seven-year qualification cycles harden incumbent positions.
For Investors and Strategic Acquirers: TSMC and Samsung Foundry expanding three-nanometer capacity is the leading indicator that parts-per-trillion certification capabilities will command acquisition premiums across the next decade. Target mid-scale fluorinated gas producers with thermal oxidizer upgrade pathways to consolidate into fewer, larger facilities. Monitor ECHA REACH enforcement tightening electronic-grade import specifications as the inflection signal for harmonized global purity thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartz Mining | The Quartz Corporation controls mine-to-final-purification pipelines for semiconductor-grade supply security. |
| Real-Time Batch Monitoring Platform | Subscription-based purity certification creates recurring revenue alongside traditional chemical sales to biopharma clusters. |
| Helium-Cooled Distillation Consolidation | Korean gas distributors amortize capital intensity across fewer, larger facilities serving Samsung and SK Hynix. |
| Point-of-Use Purification Skid Deployment | Taiwan foundries modularize final polishing from bulk delivery, collapsing traditional supplier relationships. |
| Indian Purification Plant Investment | PLI scheme attracts capacity to serve emerging Gujarat and Tamil Nadu semiconductor manufacturing clusters. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews involving fab procurement directors, gas distributor operations heads, ICP-MS metrology specialists, and pharmaceutical formulation managers. ECHA REACH substance registrations, EPA MACT enforcement records, SAMR GB standard certifications, and semiconductor foundry capex disclosures provided triangulation points. Bottom-up capacity modeling and top-down demand aggregation reconciled volume estimates.
Shipment value and volume streams were reconciled across material type, grade tier, packaging format, and end-use vertical throughout the forecast period. CAGRs derived from node shrinkage trajectories, foundry buildout schedules, and regulatory threshold tightening curves. Industry-specific inputs included helium supply concentration metrics, zone refining capital depreciation cycles, and qualification cycle duration benchmarks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA REACH threshold harmonization, helium supply disruption scenarios, and silicon carbide substitution rates in power electronics. Practitioners should monitor TSMC and Samsung Foundry two-nanometer research timelines, Indian PLI scheme disbursement velocity, and ICP-MS operator wage inflation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High Purity Lignin Market
High-Value Chemicals
High Molecular Weight Polyisobutylene Market
High-Value Chemicals
Hydroxycarboxylic Acids Market
High-Value Chemicals
Global Epichlorohydrin (ECH) Market
High-Value Chemicals
High Temperature Plastic Market
High-Value Chemicals
Battery Grade High Purity Lithium Fluoride Market
High-Value Chemicals
High Purity Silica Market
High-Value Chemicals
High Molecular Ammonium Polyphosphate Market
High-Value Chemicals
Hydroquinone Market
High-Value Chemicals
Hydroxocobalamin Chloride Market
High-Value Chemicals
Ultra-High-Purity Anhydrous Hydrogen Chloride (Hcl) Gas Market
High-Value Chemicals
High Purity Isobutylene (HPIB) Market
High-Value Chemicals
Phenanthroline Monohydrate Market
High-Value Chemicals
Global High Purity AHCL Market
High-Value Chemicals
Global 1-Hexanol Market
High-Value Chemicals
Global High Temperature Grease Market