
 Commercial Hydrogen Market | 2026-2036
Commercial Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Hydrogen Market Insights
Long-term hydrogen supply contracts with embedded carbon intensity guarantees is expanding the addressable market beyond spot molecule sales. Linde plc leverages its pipeline network density in the US Gulf Coast to anchor industrial offtake relationships with ammonia and methanol producers. Air Liquide differentiates through electrolyzer-liquefaction integration at its Normand'Hy facility, sustaining margin capture across the value chain. Plug Power specializes in captive generation architectures for warehouse mobility fleets, occupying a defensible niche in material handling fuel cell deployment.
Commercial hydrogen comprises gaseous or liquefied H₂ produced, purified, and delivered for industrial and energy applications, typically meeting purity thresholds of 99.97% for PEM fuel cells and 99.999% for semiconductor manufacturing. Steam methane reforming currently dominates production economics, though electrolysis is displacing fossil routes where renewable electricity costs fall below USD 30 per MWh. Chemical industry offtake represents the most mature demand pool, while fuel cell vehicles constitute the fastest-growing end user segment as fleet operators seek zero-emission alternatives to diesel. Pipeline distribution commands the lowest unit cost at scale, yet liquid hydrogen transport and on-site generation are gaining share in distributed and remote applications.
The US Inflation Reduction Act hydrogen production tax credits, administered by the IRS and Treasury, are reshaping project finance structures for domestic electrolyzer deployments. EU delegated acts under the Renewable Energy Directive, enforced by national regulators and the European Commission, define renewable hydrogen eligibility criteria that determine market access for imports into Rotterdam and Hamburg terminals. Japan's METI has established supply chain subsidy frameworks through its Green Innovation Fund, directing procurement toward Australian and Middle Eastern export projects. Stakeholders must monitor the divergence between certified green hydrogen premiums and carbon border adjustment mechanisms to calibrate production site selection and offtake contracting strategies.
Market Dynamics
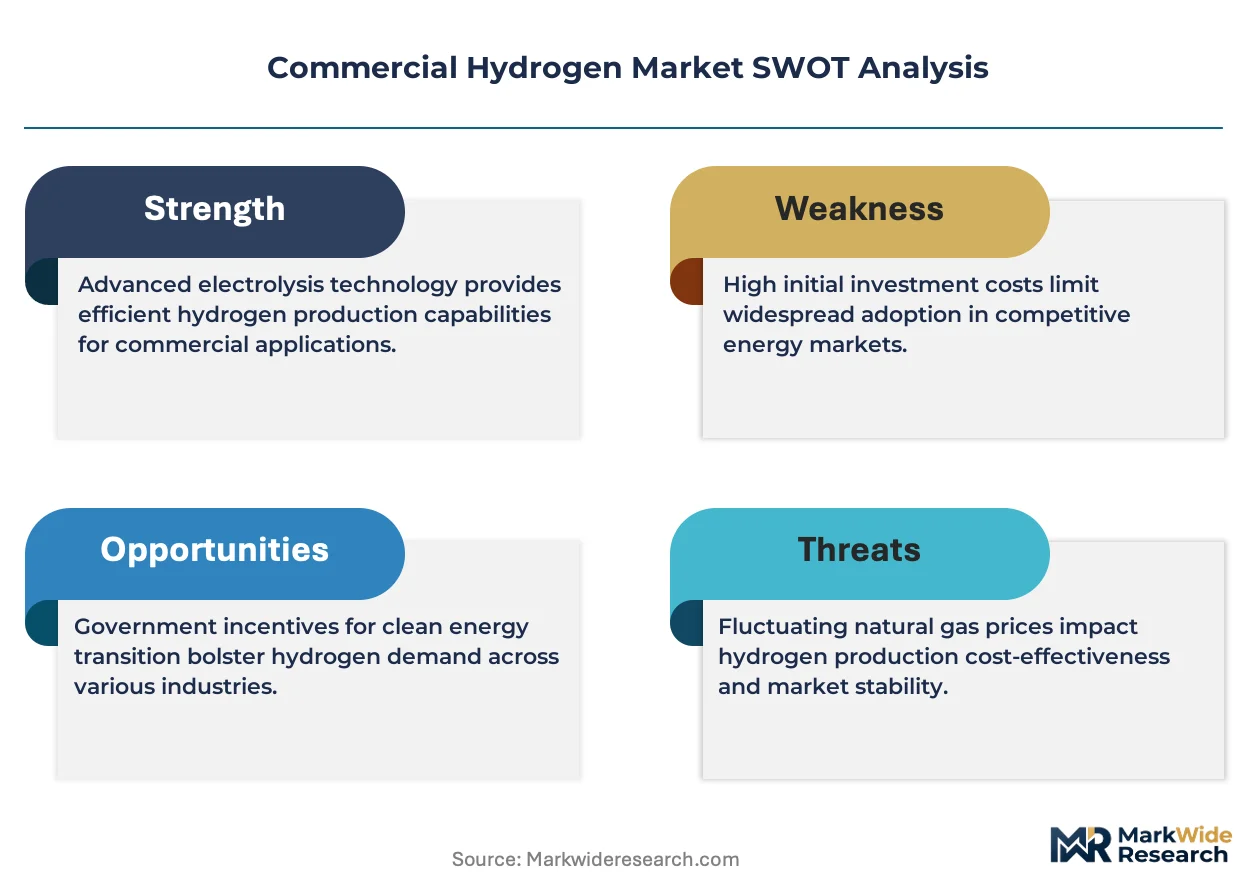
The US Inflation Reduction Act production tax credits are compressing delivered cost differentials between electrolytic and steam methane reforming routes, forcing incumbent producers to restructure offtake contracts around carbon intensity guarantees rather than spot molecule pricing.
Growth Catalysts
- Electrolyzer cost compression:Alkaline and PEM stack manufacturing scale-up in China and Europe is reducing capital intensity for green hydrogen projects, enabling project finance at smaller production volumes than previously viable.
- German H2Global auction mechanism:The double-auction structure bridges price gaps between international producers and domestic industrial offtakers, creating bankable revenue streams for export-oriented electrolyzer developments.
- Fuel cell vehicle fleet procurement:Warehouse operators and municipal bus agencies are aggregating demand through multi-year hydrogen supply agreements, shifting procurement from spot purchases to contracted molecule delivery.
Market Restraints
- Renewable electricity price volatility:Electrolyzer economics remain exposed to hourly and seasonal power price swings in markets without firm renewable offtake agreements, compressing project returns during peak demand periods.
- Pipeline infrastructure concentration:The US Gulf Coast and Rotterdam-Antwerp corridor control the majority of existing hydrogen transport capacity, creating bottlenecks for new production sites seeking market access.
- Grey hydrogen cost floor:Steam methane reforming with unabated emissions maintains a persistent production cost advantage in regions without carbon pricing or border adjustment mechanisms, delaying electrolyzer displacement.
Strategic Opportunities
- Industrial cluster offtake aggregation:The Netherlands, Belgium, and Germany's Rhine-Ruhr corridor present concentrated demand from ammonia, methanol, and steel producers seeking feedstock decarbonization pathways.
- Liquid hydrogen maritime bunkering:Singapore and Rotterdam port authorities are developing import terminal infrastructure for ammonia cracking and liquefaction, creating demand for long-haul shipping fuel substitution.
- EU Renewable Energy Directive delegated acts:The additionality and temporal correlation requirements for renewable hydrogen certification are creating premium market segments for compliant producers.
Industry Challenges
- Electrolyzer engineering talent scarcity:Stack design, membrane fabrication, and system integration expertise concentrates at a handful of European and Asian suppliers, constraining deployment timelines for new market entrants.
- Certification timeline compression:Project developers must secure TÜV or DNV certification for carbon intensity claims while simultaneously negotiating offtake contracts, creating sequencing risk in project execution.
- Legacy asset integration complexity:Industrial hydrogen consumers with existing steam methane reforming facilities face stranded asset risk when retrofitting for electrolyzer feedstock compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Hydrogen Market |
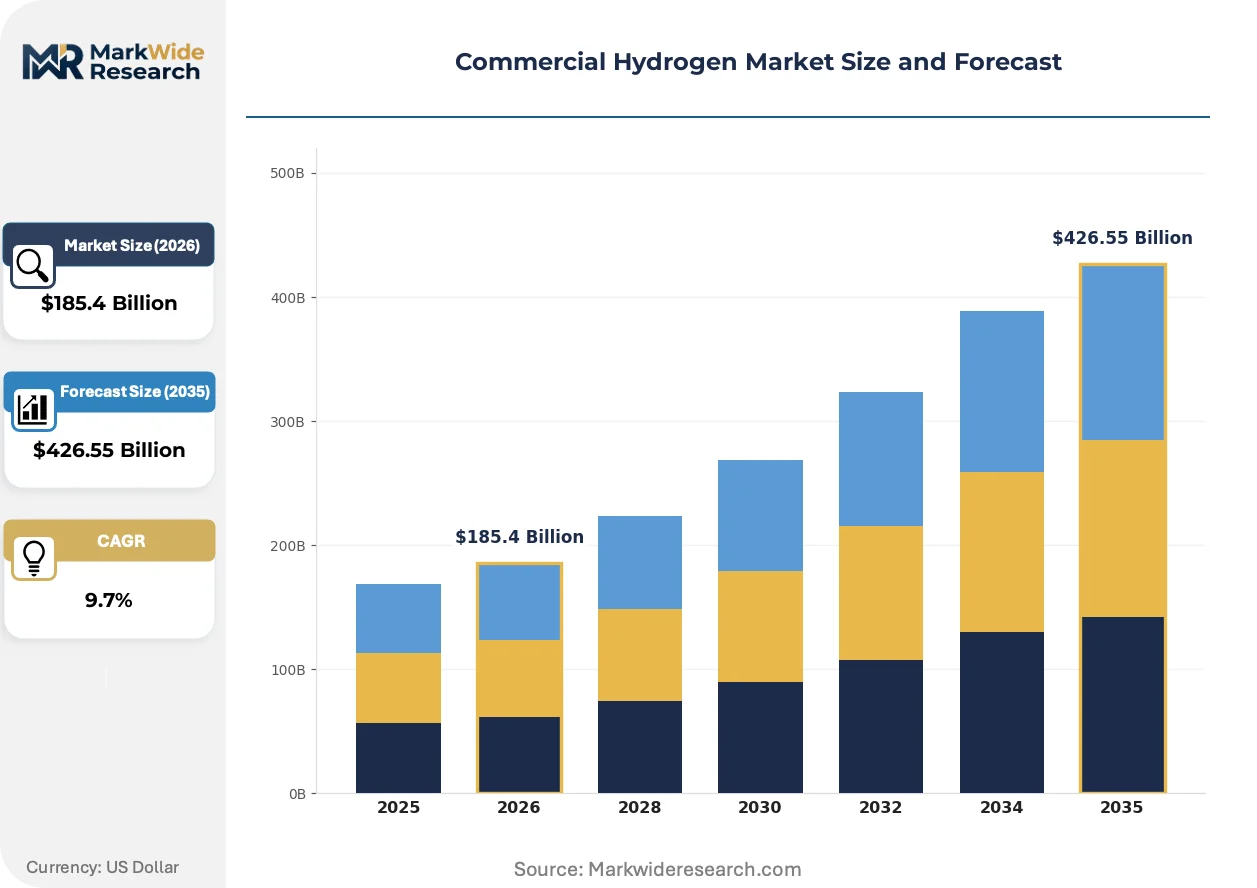
| Market Size in 2026 | $185.4 Billion |
| Market Size in 2035 | $426.55 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Steam Methane Reforming, Electrolysis, Gasification, Biomass Reforming End User: Chemical Industry, Refining Sector, Fuel Cell Vehicles, Power Generation Distribution Mode: Pipelines, Tube Trailers, Liquid Hydrogen Transport, On-Site Generation Application: Industrial Uses, Fuel Cells, Energy Storage, Chemical Feedstock |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Inc., Saudi Arabian Oil Co., Shell plc, Chart Industries, Plug Power, Siemens Energy AG, Cummins Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Hydrogen Market Trends and Innovations
Electrolyzer manufacturing and hydrogen logistics are converging around modular system architectures and digitalized production monitoring, compressing deployment timelines and enabling distributed generation models that bypass traditional pipeline dependence.
Solid oxide electrolysis cell technology is automating high-temperature steam electrolysis efficiency gains by integrating industrial waste heat recovery from chemical and steel production facilities. Steelmakers in Sweden and Germany are piloting this configuration to reduce electricity consumption per kilogram of hydrogen output. The technology is compressing the delivered cost gap against grey hydrogen in industrial cluster settings where waste heat streams are available.
The EU's delegated acts under the Renewable Energy Directive are mandating hourly temporal correlation between renewable electricity generation and hydrogen production for certification eligibility. Project developers are reconfiguring electrolyzer operations to match renewable output curves rather than running baseload. This regulatory architecture is most affecting planned import projects from North Africa and the Middle East seeking Rotterdam terminal access.
Long-term contracting with embedded carbon intensity guarantees is displacing spot molecule procurement among ammonia and methanol producers. Industrial offtakers in Germany and the Netherlands are negotiating fifteen to twenty-year supply agreements with penalty clauses for certification failures. This contracting evolution is most visible in the Rhine-Ruhr industrial corridor where chemical producers face EU carbon border adjustment exposure on export sales.
Commercial Hydrogen Market Segmentation
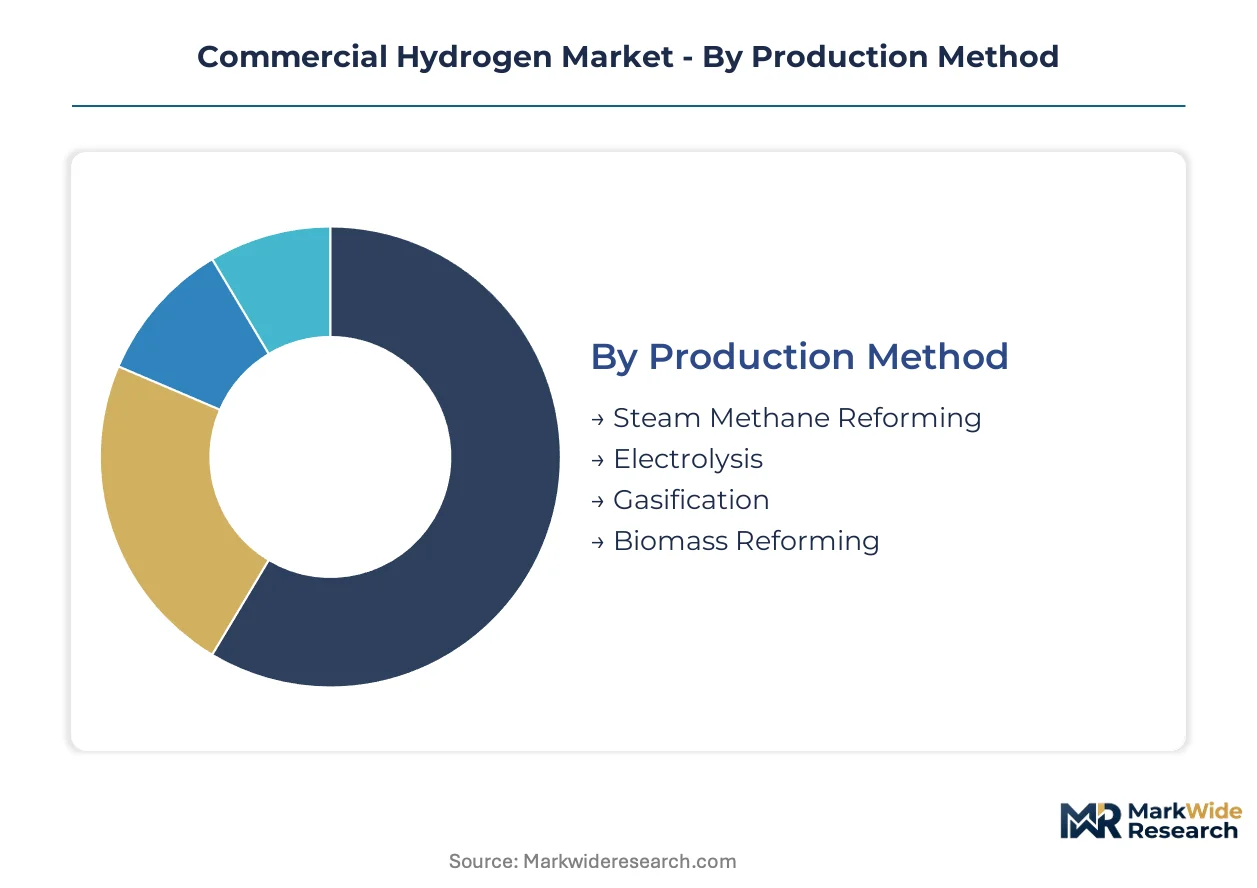
Commercial hydrogen markets fragment across production routes, delivery mechanisms, and purity specifications that determine regulatory treatment and contract pricing. Each segment carries distinct certification burdens under EU delegated acts, US IRA tax credit rules, and Japan's METI supply chain frameworks.
Production Method:
Certification requirements diverge sharply: electrolysis routes face EU temporal correlation mandates and US Treasury guidance on renewable electricity sourcing, while steam methane reforming confronts carbon intensity thresholds for green hydrogen premiums.
- Steam Methane Reforming:Natural gas feedstock conversion via high-temperature catalytic reaction yields 99.97% purity hydrogen at lowest unit cost. Demand concentrates in US Gulf Coast ammonia and methanol facilities where IRA carbon capture bonuses partially offset emissions penalties. Grey hydrogen from unabated SMR retains cost advantage in markets lacking carbon border adjustments.
- Electrolysis:Water splitting via alkaline or PEM stacks produces zero-direct-emission hydrogen when paired with renewable electricity. German H2Global auction winners and Rotterdam terminal import projects dominate procurement, driven by EU Renewable Energy Directive delegated acts mandating hourly production-renewables matching.
- Gasification:Coal or petroleum coke partial oxidation generates hydrogen with high carbon intensity; deployment concentrates in China and India where domestic coal reserves anchor feedstock security.
- Biomass Reforming:Agricultural residue thermochemical conversion offers carbon-negative pathways when coupled with CCS; limited commercial scale due to feedstock logistics constraints.
Leading the category by volume: Steam Methane Reforming. Growing fastest: Electrolysis.
End User:
Cost tiers stratify sharply: chemical industry offtakers negotiate decade-long contracts with embedded carbon guarantees, while fuel cell vehicle fleets aggregate demand through municipal procurement frameworks.
- Chemical Industry:Ammonia and methanol synthesis represent the most mature demand pool, requiring 99.999% purity for catalyst protection. Rhine-Ruhr corridor producers face EU carbon border adjustment exposure on export sales, accelerating contracted green hydrogen procurement.
- Fuel Cell Vehicles:Warehouse mobility fleets and municipal bus operators aggregate demand through multi-year supply agreements. Hyundai and Toyota fleet scaling in California and Germany is compressing delivered cost premiums against diesel alternatives.
- Refining Sector:Hydrocracking and desulfurization operations consume hydrogen at massive scale; margins compress when crude slate shifts toward heavier, sulfur-rich grades.
- Power Generation:Gas turbine blending and long-duration storage applications remain nascent, constrained by round-trip efficiency losses versus battery alternatives.
Dominant by contract value: Chemical Industry. Expanding most quickly: Fuel Cell Vehicles.
Distribution Mode:
Supply concentration determines infrastructure access: pipeline networks in Rotterdam-Antwerp and US Gulf Coast create bottlenecks for new production sites, while liquid and on-site alternatives serve distributed demand.
- Pipelines:Dedicated hydrogen transmission achieves lowest unit cost at scale; Linde's US Gulf Coast network anchors industrial cluster offtake relationships. Regulatory siting challenges constrain greenfield construction timelines.
- Liquid Hydrogen Transport:Cryogenic liquefaction at -253°C enables long-haul maritime bunkering; Singapore and Rotterdam terminal development is creating demand for ammonia cracking and re-liquefaction infrastructure.
- Tube Trailers:Compressed gas delivery serves distributed industrial and vehicle fueling demand where pipeline access is unavailable; higher unit costs limit deployment to premium applications.
- On-Site Generation:Electrolyzer installations at consumption points bypass transport entirely; Plug Power's captive architectures for warehouse fleets exemplify this distributed model.
Highest throughput: Pipelines. Gaining share fastest: Liquid Hydrogen Transport.
Application:
Maturity gradients separate established industrial uses from emerging fuel cell and energy storage segments, with margin capture varying across value chain integration levels.
- Industrial Uses:Metal processing, glass manufacturing, and electronics fabrication require consistent purity grades; Air Liquide's Normand'Hy integration of electrolyzer-liquefaction sustains margin capture across production and delivery.
- Chemical Feedstock:Ammonia and methanol synthesis constitute the largest volume application; steelmakers in Sweden and Germany pilot hydrogen direct reduction with solid oxide electrolysis waste heat recovery.
- Fuel Cells:PEM and solid oxide systems convert hydrogen to electricity for mobility and stationary power; deployment accelerates where diesel displacement penalties apply.
- Energy Storage:Power-to-gas and seasonal storage applications compete with batteries on round-trip efficiency; economics improve with prolonged discharge duration requirements.
Largest volume footprint: Industrial Uses. Steepest expansion trajectory: Fuel Cells.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates where natural gas reserves meet carbon capture infrastructure, while consumption clusters in industrial corridors facing carbon border adjustment exposure. This geographic mismatch is reshaping trade flows and terminal investment priorities.
United States
The US Gulf Coast hosts the densest pipeline network, with ammonia and methanol producers anchoring industrial offtake. IRA production tax credits administered by the IRS and Treasury are restructuring project finance for electrolyzer deployments. Houston and the broader Texas-Louisiana corridor dominate existing steam methane reforming capacity.
Germany
Rhine-Ruhr chemical producers face EU carbon border adjustment pressure on export sales, accelerating contracted green hydrogen procurement. The H2Global double-auction mechanism bridges price gaps between international producers and domestic industrial buyers. Hamburg terminal development is creating import infrastructure for North African and Middle Eastern supply.
China
Coal gasification dominates production economics, though electrolyzer manufacturing scale-up in coastal provinces is reducing capital intensity for green hydrogen projects. MIIT standards and dual carbon goals are directing industrial policy toward electrolyzer deployment. Yangtze River Delta chemical clusters are piloting renewable hydrogen feedstock integration.
Japan
METI supply chain subsidies through the Green Innovation Fund are directing procurement toward Australian and Middle Eastern export projects. Kansai industrial consumers are negotiating long-term supply agreements with embedded carbon intensity guarantees. Osaka Bay terminal infrastructure is developing for liquid hydrogen maritime imports.
Netherlands
Rotterdam-Antwerp corridor pipeline concentration creates bottlenecks for new production sites seeking market access. EU delegated acts under the Renewable Energy Directive define renewable hydrogen eligibility for terminal imports. Port authorities are developing ammonia cracking and liquefaction infrastructure for maritime bunkering applications.
Commercial Hydrogen Market Competitive Landscape
Capital-heavy producers compete with asset-light designers for margin capture across the hydrogen value chain. The market structure consolidates around integrated gas majors with existing pipeline networks and specialized electrolyzer manufacturers with modular system architectures. Three archetypes dominate: industrial gas incumbents leveraging infrastructure density, energy majors repurposing carbon capture assets, and pure-play electrolyzer specialists targeting distributed generation. Competitive moves center on long-term offtake contracting with carbon guarantees and electrolyzer-liquefaction integration to sustain margin capture.
Among industrial gas incumbents, Linde plc, Air Liquide, and Air Products and Chemicals, Inc. occupy positions anchored by pipeline network density and liquefaction expertise. These entities exemplify the integrated infrastructure archetype, with European and North American concentrations reflecting historical industrial cluster development. Their competitive positioning depends on sustaining offtake relationships through embedded carbon intensity guarantees rather than spot molecule pricing.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Saudi Arabian Oil Co. |
| Shell plc |
| Chart Industries |
| Plug Power |
| Siemens Energy AG |
| Cummins Inc. |
| Others |
Pricing and Supply Chain Analysis
Electrolyzer engineering talent scarcity in Germany's Rhine-Ruhr corridor widens pricing-tier spreads between certified green hydrogen and unabated grey supply, as labor-cost differentials compound with certification premiums to stratify contract values across industrial offtake segments.
Pricing Analysis
Margin tightening in electrolytic supply traces to IRA-guided renewable electricity sourcing requirements and EU temporal correlation mandates. Contract-based long-term offtake dominates, with price differentiation resting on TÜV certification grade and volume scale. Grey hydrogen from unabated steam methane reforming retains cost advantage where carbon border adjustments are absent. Chemical industry buyers exhibit highest price sensitivity; semiconductor manufacturers show lowest, accepting 99.999% purity premiums.
Supply Chain Analysis
Direct-to-industrial-cluster channels handle concentrated ammonia and methanol producer demand. Supply concentrates in the United States, Germany, and China, with stack manufacturing drawing from iridium catalysts, proton exchange membranes, and titanium bipolar plates. Single-source vulnerability in electrolyzer membrane fabrication creates bottlenecks. Distribution runs through dedicated pipeline networks where Linde's US Gulf Coast density anchors regional pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vertical-integration depth, with electrolyzer-liquefaction integration and captive pipeline networks emerging as the decisive margin-capture levers across the value chain.
For Market Incumbents: Acquire electrolyzer-liquefaction integration capabilities to sustain margin capture across production and delivery. Secure long-term renewable electricity offtake agreements to anchor IRA tax credit eligibility. Defend against pure-play specialists by embedding carbon intensity guarantees into fifteen to twenty-year industrial contracts with penalty clauses for certification failures.
For New Entrants and Emerging Players: Digital procurement platforms for distributed warehouse mobility fleets offer the most penetrable entry vector. Target on-site generation architectures where Plug Power's captive model has validated unit economics. Pursue municipal bus agency aggregation frameworks as the primary go-to-market angle, bypassing pipeline-dependent industrial clusters.
For Investors and Strategic Acquirers: Re-rating potential sits with solid oxide electrolysis cell specialists given waste heat recovery integration with steel and chemical facilities. Long-term viability favors developers with secured renewable electricity offtake and Hamburg or Rotterdam terminal access rights. Watch H2Global auction clearing prices as the inflection signal for bankable revenue stream formation.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer-Liquefaction Integration | Air Liquide's Normand'Hy facility sustains margin capture across production and delivery stages. |
| Long-term Supply Agreement | German chemical producers negotiate fifteen to twenty-year contracts with embedded carbon guarantees. |
| Backward Integration into Renewable Electricity | Project developers secure firm offtake to satisfy IRA Treasury guidance and EU temporal correlation. |
| Green Certification Program | TÜV and DNV certification for carbon intensity claims unlocks premium market segments in Rotterdam. |
| Joint Venture for Terminal Infrastructure | Singapore and Rotterdam port authorities develop ammonia cracking capacity for maritime bunkering demand. |
Research Methodology
Document review covered SEC 10-K filings, EU delegated acts, and IEA hydrogen project databases, complemented by interviews with electrolyzer system integrators, industrial gas procurement directors, and renewable power developers. Primary fieldwork with EPC contractors and hydrogen offtake managers at ammonia facilities informed capacity deployment timelines. Secondary validation drew from FERC filings, customs trade data, and H2Global auction results. Bottom-up electrolyzer shipment data triangulated against top-down industrial hydrogen demand estimates.
Segment-level outputs across production method, end user, distribution mode, and application categories informed the analytical framework over the projection horizon. Modeled dimensions included purity specification tiers, carbon intensity certification levels, and regional regulatory clusters. CAGRs were derived from electrolyzer cost curves, renewable electricity price trajectories, and offtake contract formation rates. Forecast inputs incorporated IRA Treasury guidance evolution and EU delegated act implementation timelines.
The model holds under sustained IRA tax credit administration and EU carbon border adjustment enforcement; deviation in renewable electricity price volatility or electrolyzer engineering talent availability would shift deployment trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Metal Cutting Gas Market
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
Acetylene Gas Market
Industrial Gases
Gas Processing Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
Pressure Swing Adsorption Nitrogen Generator Market
Industrial Gases
Transcritical CO2 Market
Industrial Gases
Krypton Gas Market
Industrial Gases
Neon Gas Market
Industrial Gases
Helium Market
Industrial Gases
Europe Specialty Gas Market
Industrial Gases
US Industrial Gas Regulator Market
Industrial Gases
Gas Sampling Line Market
Industrial Gases
Dielectric Gases Market
Industrial Gases
Middle East Industrial Gas Market
Industrial Gases
US Specialty Gas Market