
 Global Industrial Denox Systems and Services Market | 2026-2036
Global Industrial Denox Systems and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Denox Systems and Services Market Intelligence
A long-standing division between capital-intensive system manufacturing and asset-light service delivery is unwinding as clients seek integrated lifecycle support. Mitsubishi Power leverages its engineering and manufacturing scale for large-scale power plant projects. In contrast, Johnson Matthey specializes in the high-performance catalysts that are critical components within these systems. CECO Environmental positions itself across both equipment and service-based solutions for a diverse industrial client base, adapting to varied operational needs.
Industrial Denox systems are engineered solutions designed to neutralize nitrogen oxides (NOx) from flue gas streams produced by combustion processes. These systems, particularly Selective Catalytic Reduction (SCR), utilize a catalyst and a reducing agent like ammonia to convert NOx into harmless nitrogen and water. Selective Catalytic Reduction systems represent the dominant technology for new installations due to superior efficiency, especially within the power generation and cement manufacturing applications. The services segment sees consistent activity from maintenance and consulting, providing a stable recurring revenue stream for providers.
Regulatory mandates are the primary market driver, with frameworks like the US EPA's air quality standards and the EU's Industrial Emissions Directive setting strict NOx limits. In parallel, China's Ministry of Ecology and Environment (MEE) enforces stringent controls on emissions from coal-fired power plants and heavy industry. Future investment decisions for industrial operators will hinge on balancing the total cost of ownership of advanced systems against the financial penalties for non-compliance.
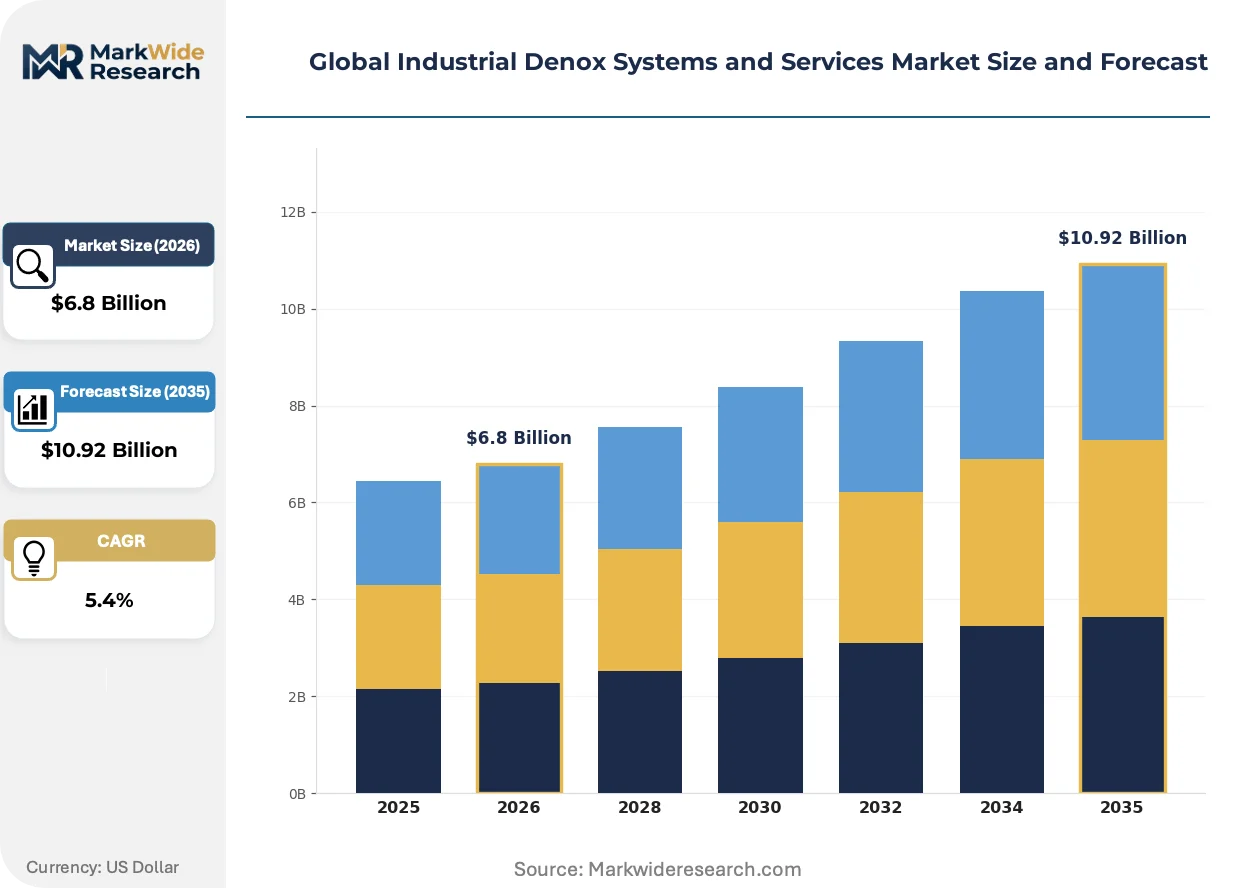
Market Dynamics
The central dynamic shaping the industrial Denox market is the unavoidable financial calculation facing operators: the high capital cost of new abatement systems versus the escalating regulatory and financial penalties for non-compliance with tightening air quality standards.
Growth Catalysts
- Industrial Expansion in India:India's ongoing expansion of its thermal power generation fleet creates baseline demand for new system installations, as projects must comply with the Central Electricity Authority's stringent environmental norms for NOx emissions.
- Stringent Emissions Frameworks:China's Ministry of Ecology and Environment (MEE) continues to enforce strict NOx limits on heavy industries like steel and cement, compelling operators to invest in high-efficiency abatement technologies like SCR.
- Advanced Catalyst Development:Innovations in catalyst materials improve NOx conversion efficiency and resistance to poisoning from sulfur in flue gas, enhancing the operational viability and total cost of ownership for SCR systems in demanding applications.
Market Restraints
- Ammonia Price Volatility:As the primary reducing agent for SCR systems, ammonia's price and availability are tied to the fertilizer and chemical industries, exposing plant operators to unpredictable fluctuations in operational costs.
- High Capital Outlay:The significant upfront investment required to engineer, procure, and install an industrial-scale SCR system remains a substantial barrier for smaller companies or facilities in capital-constrained sectors.
- Technical Operating Complexity:Effective operation of Denox systems requires specialized expertise in managing catalyst activity, optimizing ammonia injection rates, and preventing byproduct formation, which can be a hurdle for some industrial teams.
Strategic Opportunities
- Service-Based Lifecycle Contracts:Shifting from equipment sales to comprehensive service agreements that include catalyst management, performance monitoring, and regulatory reporting provides a stable, recurring revenue opportunity for system providers.
- Maritime Sector Applications:The enforcement of NOx Emission Control Areas (ECAs) by the International Maritime Organization (IMO) creates a distinct market for compact SCR systems adapted for marine diesel engines on commercial vessels.
- Waste-to-Energy Plant Retrofits:A growing pipeline of waste-to-energy projects, especially in Europe, presents a key opportunity for retrofitting facilities with modern Denox systems to comply with the EU's Industrial Emissions Directive.
Industry Challenges
- Skilled Technician Scarcity:A persistent shortage of qualified engineers and field technicians with the expertise to install, commission, and service complex SCR systems can lead to project delays and suboptimal system performance.
- Legacy System Integration:Integrating modern Denox controls with older, pre-existing plant-wide distributed control systems (DCS) often presents significant technical and software compatibility challenges, increasing project complexity and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Denox Systems and Services Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Selective Catalytic Reduction, Non-Selective Catalytic Reduction, Electron Beam, Absorption, Adsorption Service Type: Installation, Maintenance, Consulting, Upgradation, Monitoring Application: Power Generation, Cement Manufacturing, Pulp & Paper, Chemical Processing, Metal Fabrication End User: Energy Producers, Construction Firms, Paper Manufacturers, Chemical Plants, Fabrication Facilities |
| Companies Covered | Mitsubishi Power, Babcock & Wilcox Enterprises, Inc., Johnson Matthey, CECO Environmental, Yara International, Hitachi Zosen Inova, BASF SE, Alstom, Doosan Babcock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Denox Systems and Services Market Strategic Shifts & Innovations
The market's focus is shifting from hardware provision to integrated performance management. Digital monitoring tools and advanced materials science are becoming central to competitive differentiation, driven by both stringent regulations and the industrial pursuit of greater operational efficiency and lower total cost of ownership.
Digital twin modeling of catalyst performance allows operators to simulate aging, poisoning, and thermal effects. Large power generation utilities are the primary adopters, applying these models to their critical thermal power plants to forecast maintenance cycles. This predictive capability is fragmenting the traditional, reactive break-fix service model into a more specialized, data-driven consulting and performance optimization market.
Revisions to the EU's Industrial Emissions Directive (IED), alongside its Best Available Techniques (BAT) reference documents, are mandating stricter NOx limits across a wide range of industries. This forces many facilities, from chemical plants to foundries, to evaluate and upgrade their existing abatement capabilities. The cement manufacturing sector is particularly affected, accelerating investment in SCR technology to achieve compliance levels that older SNCR systems cannot reach.
Operator procurement behavior is evolving from discrete capital equipment purchases toward performance-guaranteed, long-term service agreements that cover system uptime and emissions compliance. This change disrupts the traditional business model of selling equipment and spare parts as separate transactions. This trend is most visible in the mature industrial markets of North America and Western Europe, where operators prioritize predictable operational expenditures and total lifecycle cost.
Global Industrial Denox Systems and Services Market Segmentation
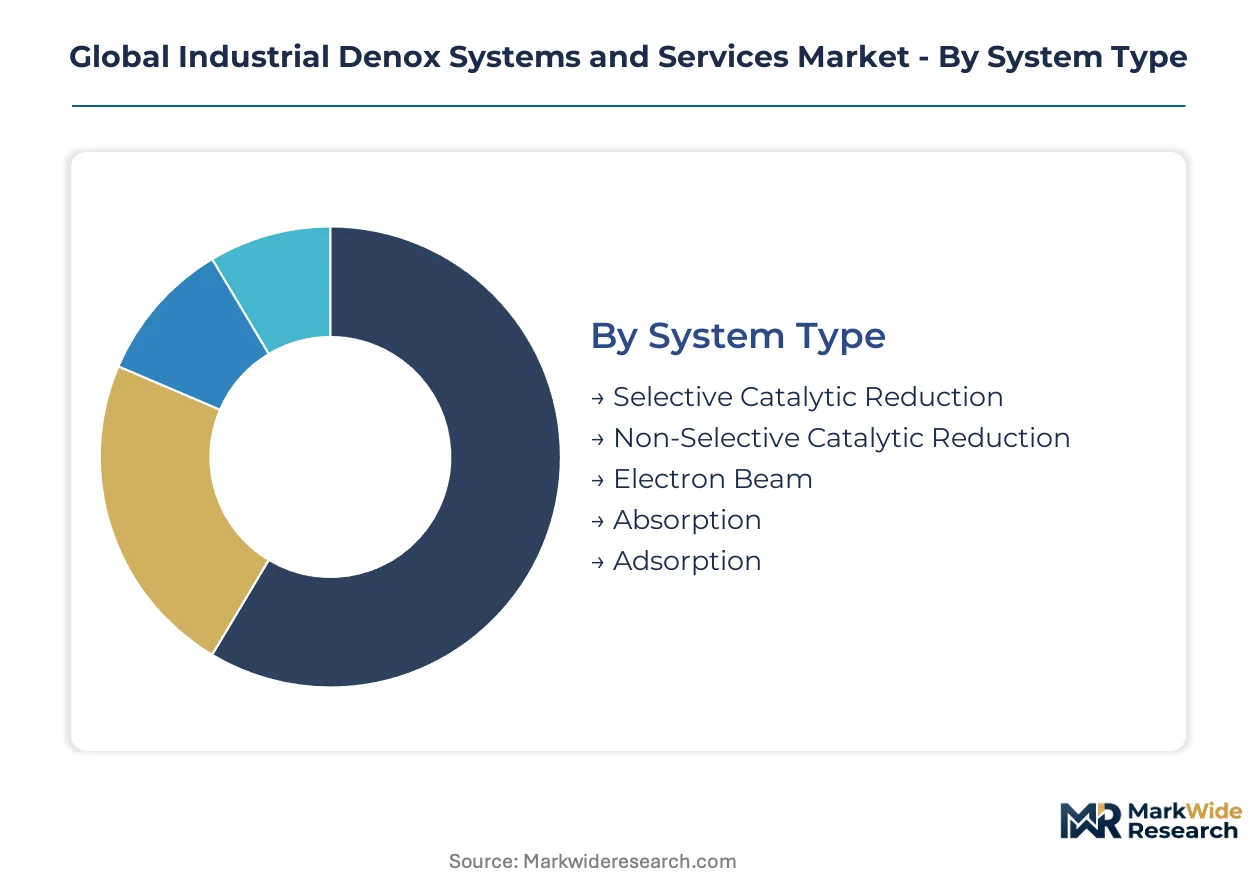
The segmentation analysis illuminates the diverse technological and operational landscape of the industrial Denox market. Understanding these distinct segments helps industrial operators and solution providers align strategies with evolving regulatory demands and operational needs. This granular view reveals where investment capital and service delivery models concentrate across the value chain.
System Type:
The industrial Denox market faces significant substitution pressure, particularly from advanced technologies replacing older, less efficient systems.
- Selective Catalytic Reduction:This advanced system utilizes a catalyst and a reducing agent, typically ammonia, to convert nitrogen oxides into harmless nitrogen and water. Demand concentrates heavily within the power generation sector, driven by stringent NOx limits from regulations like the EU's Industrial Emissions Directive.
- Non-Selective Catalytic Reduction:These systems inject a reducing agent directly into the flue gas stream without a catalyst, converting NOx at high temperatures. Legacy installations in older industrial facilities continue to utilize this technology, though new installations are rare due to lower conversion efficiency.
- Electron Beam:This technology employs electron beams to break down NOx and SOx simultaneously, forming particulate matter that can be removed.
- Absorption:Absorption systems use liquid solutions to capture and remove NOx from flue gas, often involving chemical reactions within the scrubber.
- Adsorption:Adsorption systems utilize solid materials with high surface areas to physically bind NOx molecules, typically requiring regeneration cycles.
Non-Selective Catalytic Reduction anchors the volume base while Selective Catalytic Reduction gains share at the steepest rate.
Service Type:
Service delivery models in the Denox market exhibit varied margin profiles, reflecting the complexity and criticality of each offering.
- Maintenance:This segment encompasses routine inspections, component replacement, and performance tuning to ensure continuous operation and compliance of Denox systems. Energy producers in North America prioritize proactive maintenance contracts to minimize downtime and avoid regulatory penalties.
- Installation:This service involves the engineering, procurement, and construction of new Denox systems or major retrofits within industrial facilities. The expansion of thermal power capacity in India drives significant installation demand for new SCR units.
- Consulting:Consulting services provide expert advice on regulatory compliance, system optimization, and technology selection for industrial operators.
- Upgradation:Upgradation services focus on enhancing existing Denox systems with newer catalysts or control technologies to improve efficiency.
- Monitoring:Monitoring services track system performance and emissions data in real-time, providing critical insights for operational adjustments and reporting.
Installation services represent critical upfront activity, while maintenance services expand most quickly due to recurring operational needs.
Application:
The volume of NOx emissions and the scale of abatement required vary significantly across industrial applications, dictating system design and service intensity.
- Power Generation:This application involves large-scale thermal power plants, where combustion of fossil fuels produces substantial NOx emissions requiring robust abatement. Global utilities invest heavily in SCR systems to meet national air quality standards and carbon reduction targets.
- Cement Manufacturing:This sector's high-temperature kilns are significant NOx sources, driving demand for efficient Denox solutions, particularly SCR technology. European cement plants are accelerating investment in advanced systems to comply with revised EU Industrial Emissions Directive mandates.
- Pulp & Paper:The pulp and paper industry utilizes combustion processes that generate NOx, requiring abatement solutions tailored to specific flue gas compositions.
- Chemical Processing:Chemical plants often produce diverse flue gas streams containing NOx, necessitating specialized Denox systems for compliance.
- Metal Fabrication:Metal fabrication processes, including welding and heat treatment, contribute to atmospheric NOx, requiring localized abatement technologies.
Power Generation applications command the largest market share, with Cement Manufacturing climbing the fastest due to regulatory pressure.
End User:
End-user procurement behavior is shaped by their operational scale, regulatory exposure, and internal technical capabilities.
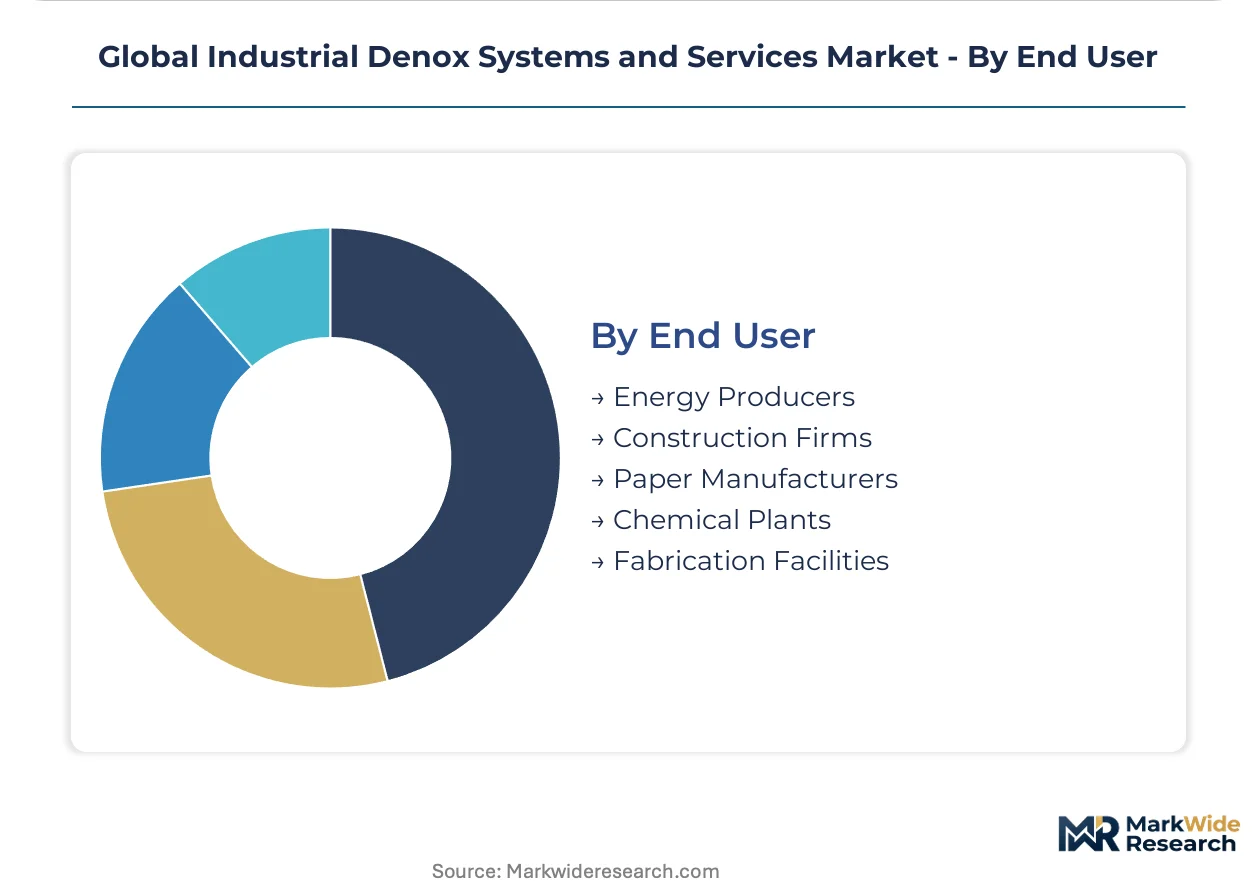
- Energy Producers:These entities, primarily power utilities and independent power producers, operate large combustion sources requiring continuous, high-efficiency NOx abatement. They prioritize long-term performance guarantees and integrated lifecycle support for their critical assets.
- Chemical Plants:Operators of chemical processing facilities require Denox systems tailored to complex and varied flue gas compositions, often with strict process integration needs. Compliance with specific local environmental permits drives their technology selection.
- Construction Firms:Construction firms may utilize Denox systems for temporary power generation or specific industrial processes on large-scale projects.
- Paper Manufacturers:Paper manufacturers integrate Denox solutions into their boiler and recovery furnace operations to manage NOx emissions.
- Fabrication Facilities:These facilities implement Denox systems to address NOx emissions from industrial furnaces, kilns, and other high-temperature processes.
Energy Producers represent the largest customer base, while Chemical Plants are gaining share fastest due to increasing process complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global industrial Denox market exhibits a dynamic interplay between regions that are net importers of abatement technology and those that are rapidly expanding their domestic manufacturing capabilities. Demand for Denox systems and services is primarily shaped by the scale of industrial activity and the stringency of local emissions regulations. This creates distinct investment patterns across major industrial economies.
China
China's Ministry of Ecology and Environment (MEE) mandates stringent NOx limits on heavy industries, particularly steel and cement, compelling operators to invest in high-efficiency abatement technologies. The nation's dual carbon goals further accelerate the adoption of advanced Denox systems for cleaner industrial production. Industrial clusters in the Yangtze River Delta are seeing significant retrofits and new installations to meet these strict environmental targets.
India
India's ongoing expansion of its thermal power generation fleet creates baseline demand for new Denox system installations. The Central Electricity Authority's (CEA) stringent environmental norms for NOx emissions ensure that all new projects incorporate advanced abatement solutions. Gujarat and Maharashtra, with their expanding industrial bases, are key regions for new SCR unit deployments.
Germany
Germany's industrial operators face pressure from the EU's Industrial Emissions Directive (IED) to upgrade existing facilities and ensure compliance with stricter NOx limits. The growing waste-to-energy sector in Germany presents a significant opportunity for retrofitting modern Denox systems. Facilities in the Ruhr Valley, a traditional industrial heartland, are actively evaluating and implementing these upgrades.
United States
United States EPA air quality standards drive investment in Denox systems, particularly within the power generation and chemical processing sectors. Energy producers prioritize long-term performance guarantees and integrated lifecycle support for their critical assets. The Gulf Coast region, with its high concentration of refineries and chemical plants, sees continuous demand for specialized Denox solutions.
Japan
Japan's industrial sector, under the guidance of the Ministry of Economy, Trade and Industry (METI), continually seeks to improve energy efficiency and reduce emissions from manufacturing processes. Compliance with national environmental standards ensures a steady demand for advanced Denox technologies, especially in critical industrial areas. The Tokyo Bay area, a major industrial hub, is a focal point for these technology deployments.
Global Industrial Denox Systems and Services Market Key Industry Players
Concentration sits with large-scale engineering firms offering comprehensive Denox solutions, alongside specialized catalyst manufacturers driving innovation in core components. The market structure is evolving as clients seek integrated lifecycle support, blurring the traditional lines between equipment provision and service delivery. Strategic partnerships and portfolio diversification are common competitive moves as companies aim to capture a broader share of the value chain.
Specialists in integrated lifecycle support include Mitsubishi Power, leveraging its engineering scale for large-scale power plant projects. Johnson Matthey exemplifies expertise in high-performance catalysts, critical for efficient NOx conversion within these systems. CECO Environmental positions itself across both equipment and service-based solutions, adapting to varied industrial client needs and offering comprehensive environmental solutions.
| Leading Market Players |
|---|
| Mitsubishi Power |
| Babcock & Wilcox Enterprises, Inc. |
| Johnson Matthey |
| CECO Environmental |
| Yara International |
| Hitachi Zosen Inova |
| BASF SE |
| Alstom |
| Doosan Babcock |
Cost & Logistics Intelligence
Large-scale system integration and catalyst manufacturing exhibit significant scale economies, shaping both supply concentration and underlying price floors for industrial Denox solutions. High fixed costs associated with engineering design and specialized production facilities favor established players, influencing competitive dynamics across the market.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing, where system complexity and performance guarantees drive cost structures. Price differentiation stems from catalyst efficiency, system customization for specific flue gas compositions, and comprehensive after-sales service bundles. Pricing pressure stems from client demand for lower total cost of ownership over the system lifecycle. Smaller industrial facilities, particularly within cement manufacturing, exhibit higher price sensitivity compared to large power generation utilities.
Supply Chain Analysis
Extended inventory holding periods for specialized catalysts and long lead times for engineered components characterize the Denox supply chain. Supply concentration for critical catalyst materials and advanced system engineering primarily sits with China, Europe, and Japan. Raw material dependencies include ammonia, specific catalyst metals like vanadium and titanium dioxide, and specialized steel alloys for reactor vessels. Ammonia price volatility presents a structural supply chain risk, impacting operational costs for system operators. Direct sales channels, often involving specialized EPC contractors, dominate distribution for large-scale Denox projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is experiencing a cyclical recovery, driven by renewed industrial capital expenditure in power generation and heavy industry, particularly in rapidly industrializing economies.
For Market Incumbents: Secure long-term service contracts and pursue strategic mergers and acquisitions for advanced catalyst technology. The emergence of compact SCR systems for new applications represents a threat requiring continuous innovation. Vertical integration into catalyst manufacturing or focused R&D into next-generation materials serves as a critical lever for margin protection and market share. Consolidating engineering expertise across diverse industrial applications will reinforce competitive advantages.
For New Entrants and Emerging Players: Anchor in specialized niches like the maritime sector for compact SCR systems or waste-to-energy plant retrofits in Europe. Smaller industrial facilities and specific niche applications, such as localized abatement for metal fabrication, represent the most penetrable segments. An effective go-to-market angle involves offering outcome-based performance guarantees alongside modular system designs, reducing upfront capital barriers for clients. Focus on digital monitoring solutions for operational efficiency.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service providers offering comprehensive lifecycle support for Denox systems. The long-term viability of this market remains strong, sustained by global emissions mandates and persistent industrial growth. Catalyst specialists and digital monitoring platform providers represent attractive acquisition archetypes, offering both technological differentiation and stable revenue streams. The adoption rate of performance-based service agreements serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Catalyst Production Capacity | Increasing catalyst supply ensures system availability for critical industrial operations and supports market growth in new installations. |
| Form Joint Ventures with Local EPC Firms | Partnerships with local engineering, procurement, and construction firms facilitate market entry and project execution in regions like India. |
| Launch Advanced Digital Twin Software | Digital twin technology optimizes catalyst performance and predicts maintenance needs, improving system uptime for power generation utilities. |
| Develop Compact SCR Systems for Marine Engines | Tailored SCR solutions address stringent IMO NOx emission regulations for the growing global maritime sector. |
| Invest in Green Ammonia Production | Securing low-carbon ammonia supply mitigates price volatility and enhances the environmental profile of Denox system operations. |
Research Approach
Operator-level perspectives from power plant engineers, cement plant operators, environmental compliance managers, and catalyst R&D scientists anchored the qualitative base for this analysis. Primary interviews were triangulated with extensive secondary research, drawing from sources such as EU Industrial Emissions Directive documents, US EPA air quality reports, China MEE regulations, and industry association publications. A combination of bottom-up data aggregation and top-down market sizing provided a robust foundation for market estimates.
Sensitivity analysis framed the quantitative modeling, integrating historical data with projected regulatory impacts across the analysis window. The analytical framework incorporated segmentation dimensions including system type, service type, application, end-user, and regional regulatory stringency. Compound annual growth rates were derived from projected regulatory enforcement and planned industrial capacity additions. Key industry-specific forecast inputs included planned thermal power capacity expansions in India and revisions to the EU Industrial Emissions Directive.
Decision-makers should treat outputs as directional under base assumptions that current regulatory frameworks remain stable and industrial expansion continues; material deviation would warrant model refresh. Geopolitical shifts impacting ammonia supply, unexpected technological breakthroughs, or global economic downturns affecting industrial output represent risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Portable Butane Gas Cartridge Market
Industrial Gases
High Purity Argon Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
South-East Asia (SEA) Syngas Market
Industrial Gases
Sulfur Recovery Tail Gas Analyzer Market
Industrial Gases
Neon Gas for Laser Market
Industrial Gases
Dielectric Gases Market
Industrial Gases
Welding Gas Market
Industrial Gases
Acetylene Gas Market
Industrial Gases
Food-Grade Gases Market
Industrial Gases
Nitrogen Gas Market
Industrial Gases
Krypton Gas Market
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market
Industrial Gases
Global Nitrogen Market
Industrial Gases
GCC Industrial Gases Market