
 Industrial Gas Regulator Market | 2026-2036
Industrial Gas Regulator Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Gas Regulator Market Intelligence
The capability gap between integrated system providers and component specialists is redrawing competitive lines. Emerson Electric Co. leverages its deep automation expertise to offer complete digital solutions for process control. In contrast, Parker Hannifin Corporation specializes in high-performance pneumatic and electromechanical components for diverse industrial applications. Linde plc sustains its market position through its extensive gas supply network and associated hardware offerings, ensuring compatibility across its ecosystem.
An industrial gas regulator is a valve that automatically reduces high-pressure gas from a source cylinder or line to a lower, usable pressure. These devices are constructed from materials like brass or stainless steel to ensure compatibility with specific gases and prevent contamination. Diaphragm regulators are standard for applications requiring high purity, such as in laboratories and food processing. Piston regulators, known for their durability, continue to dominate heavy-duty applications like welding and metal fabrication.
Adherence to ISO 2503 for gas welding equipment and CE marking directives in Europe governs product design and market access. In the United States, OSHA regulations mandate specific safety features for pressure relief devices in workplace environments. This forces manufacturers to navigate a complex matrix of national and international standards. The critical decision for buyers involves weighing the upfront cost of digital regulators against their long-term safety and efficiency gains.
Market Dynamics
The central force shaping the industrial gas regulator market is the digitization of process control, creating a performance and safety gap between traditional mechanical devices and next-generation regulators integrated with Industrial Internet of Things (IIoT) platforms.
Growth Catalysts
- Food & Beverage Processing:Expansion in this sector drives demand for high-purity diaphragm regulators, particularly for modified atmosphere packaging (MAP) and carbonation, where precise gas mixture and contamination control are critical for product quality and shelf life.
- CE Marking Directives:In Europe, compliance with CE marking for pressure equipment mandates stringent design, manufacturing, and testing standards, which favors manufacturers of higher-quality, certified regulators and raises barriers to entry for non-compliant products.
- Manufacturing in China:The country's extensive industrial base, especially in metal fabrication, electronics, and chemical production, creates concentrated pockets of high-volume demand for both standard and specialized gas control equipment, supporting economies of scale for producers.
Market Restraints
- High Upfront Cost:The significant price differential between advanced digital regulators with remote monitoring and basic mechanical piston or diaphragm models inhibits adoption in cost-sensitive industries or smaller enterprises, slowing the technology replacement cycle.
- Material Sourcing Volatility:Dependence on specific grades of corrosion-resistant materials like 316L stainless steel and specialized elastomers for seals exposes manufacturers to price fluctuations and supply chain disruptions from a concentrated base of raw material suppliers.
- Piston Regulator Durability:In heavy-duty applications like shipyard welding and steel cutting, the proven robustness and simple maintenance of legacy piston regulators present a significant barrier to substitution by more complex and environmentally sensitive digital alternatives.
Strategic Opportunities
- Hydrogen Economy Infrastructure:The global build-out of hydrogen production, storage, and distribution networks creates a significant new market for specialized regulators designed to handle high pressures, prevent hydrogen embrittlement, and ensure safety in fuel cell and industrial applications.
- Sensor and AI Integration:Embedding smart sensors for predictive maintenance, coupled with AI algorithms to analyze flow and pressure data, offers a path to create self-diagnosing regulators that can preempt failures, reducing downtime in critical processes.
- Industrialization in Southeast Asia:Rapid industrial growth in nations like Vietnam and Indonesia opens new markets for mid-range regulators, particularly in manufacturing, automotive assembly, and food processing, where basic automation is being implemented.
Industry Challenges
- Technician Skill Gaps:A shortage of technicians with the hybrid mechanical and software expertise required to install, calibrate, and troubleshoot networked digital regulators creates a bottleneck for service and support, limiting successful field deployments.
- Legacy System Integration:Ensuring backward compatibility and seamless data communication between new, intelligent regulators and decades-old plant control systems, such as proprietary DCS or SCADA platforms, poses a significant technical and financial hurdle for end-users.
- Certification Timelines:The lengthy and costly process of obtaining certifications like ISO 2503 for new designs or alternative materials slows the pace of innovation and delays market entry for next-generation products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Gas Regulator Market |
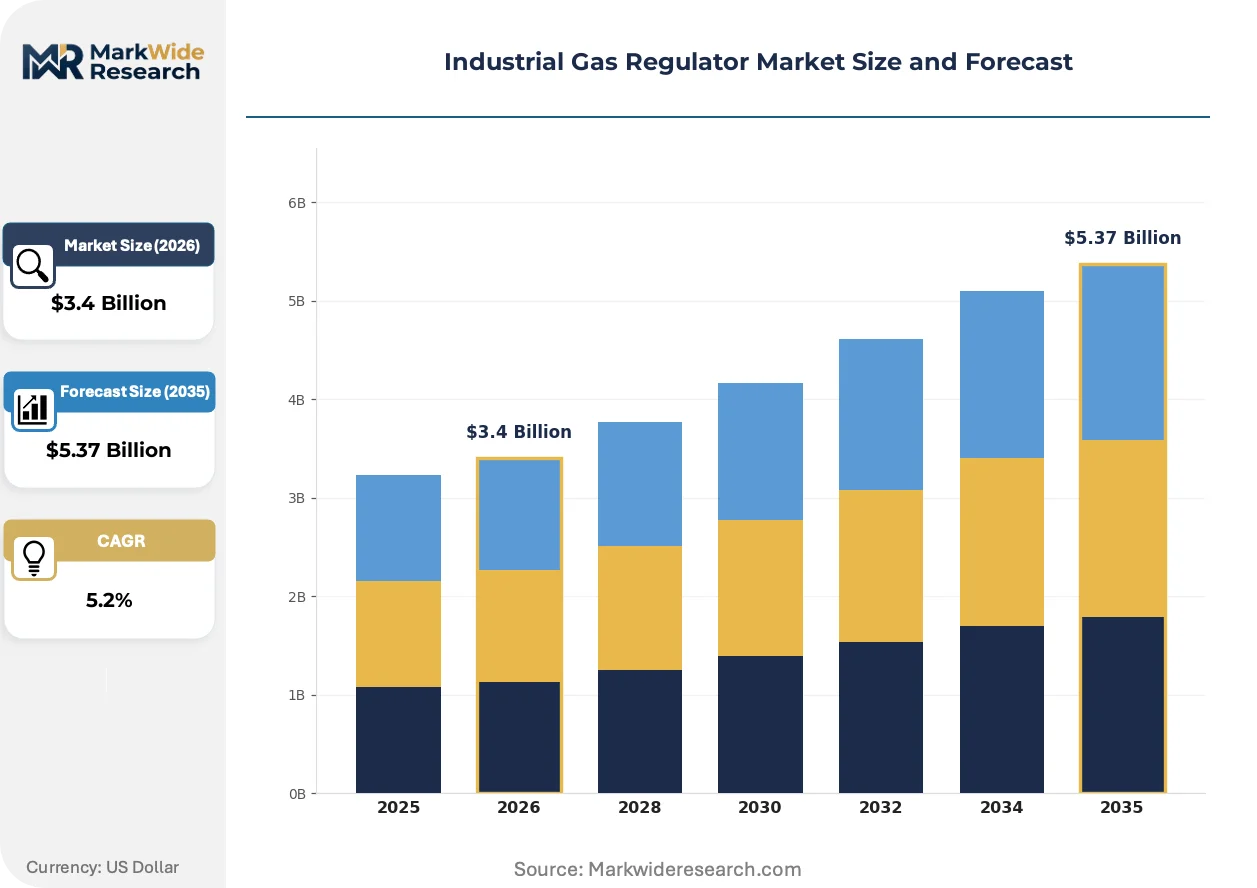
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.37 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm Regulator, Piston Regulator, Bellows Regulator, Back Pressure Regulator, Pressure Relief Valve Technology: Analog, Digital, Pneumatic, Electro-Mechanical, Hydromechanical Application: Welding Plants, Chemical Plants, Food & Beverage Processing, Paint & Coating, Metal Fabrication End User: Manufacturing Facilities, Laboratories, Oil & Gas Refineries, Power Generation Units, Aerospace Maintenance |
| Companies Covered | Emerson Electric Co., Linde plc, Air Liquide S.A., Air Products and Chemicals Inc., Parker Hannifin Corporation, Honeywell International Inc., Cavagna Group S.p.A., GCE Group, Itron Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Gas Regulator Market Strategic Shifts & Innovations
The evolution from standalone mechanical components to intelligent, data-generating nodes within a larger industrial network defines the market's trajectory. This shift prioritizes operational intelligence, predictive maintenance, and system-wide efficiency over the performance of a single, isolated device.
Digital twin technology for regulators creates a virtual model to simulate real-world pressure, flow, and material stress conditions. The aerospace and semiconductor fabrication sectors lead adoption for process optimization and pre-emptive failure analysis. This technology is decomposing the traditional divide between physical hardware and digital process management, enabling new service-based revenue models.
OSHA regulations in the United States mandate specific safety features, including integrated pressure relief devices and documented inspection protocols for equipment in workplace environments. This requirement forces manufacturers to engineer redundant safety mechanisms and clear operational markings, adding to product complexity. The chemical processing and metal fabrication sectors are most affected, prioritizing regulators with verifiable compliance to mitigate liability.
Buyers are increasingly opting for bundled service contracts that include the gas, the regulation hardware, and ongoing maintenance from a single source. This model challenges the role of traditional standalone component distributors, concentrating power with major gas suppliers. This trend is most prominent in European laboratory and healthcare verticals, where budget predictability and guaranteed uptime are primary procurement drivers.
Industrial Gas Regulator Market Segmentation
Understanding the industrial gas regulator market through segmentation reveals distinct demand patterns and technological preferences across various industry verticals. This granular view helps manufacturers tailor product development and service offerings to specific operational requirements and regulatory landscapes.
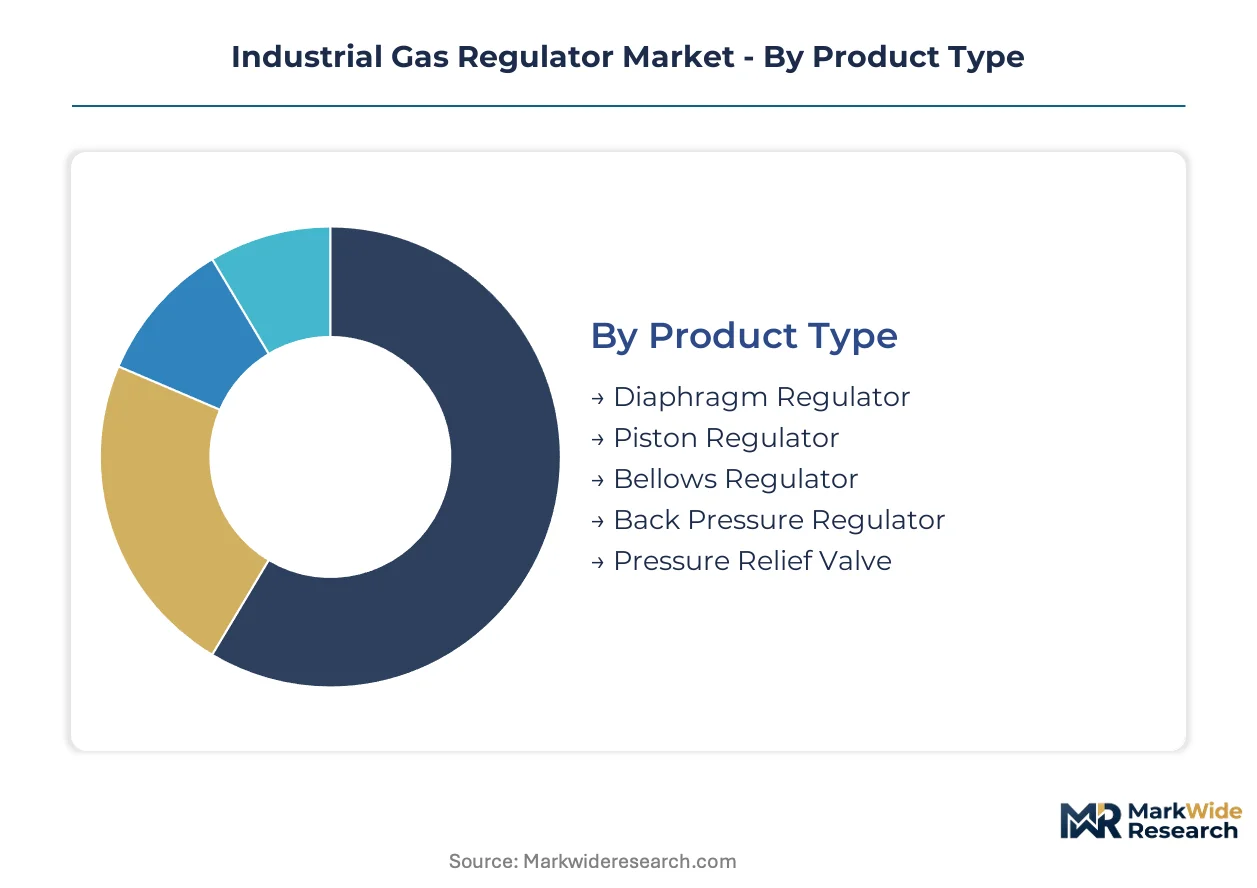
Product Type:
Margin pools within this product category often sit with specialized regulators designed for high purity or critical safety applications.
- Diaphragm Regulator:These devices employ a flexible diaphragm for highly accurate and stable pressure control, crucial for maintaining gas purity. Demand for these regulators is concentrated in the food & beverage processing and pharmaceutical sectors due to stringent contamination prevention needs.
- Piston Regulator:Known for their robust construction and high flow capabilities, piston regulators are designed for durability in demanding environments. These mechanical devices are widely adopted in heavy industrial applications like metal fabrication and welding plants due to their resilience.
- Bellows Regulator:Offering superior leak integrity and sensitivity, bellows regulators are essential for ultra-high purity and corrosive gas handling.
- Back Pressure Regulator:This type maintains a constant upstream pressure by controlling the flow out of a system, critical for process stability in chemical production.
- Pressure Relief Valve:An automatic safety device designed to protect systems from over-pressurization by releasing excess gas, mandated across various industrial settings.
The dominant share belongs to Piston Regulator, while Diaphragm Regulator is closing the gap fastest.
Technology:
The market's technology segments are tiered by cost and capability, with advanced digital solutions commanding a premium.
- Digital:Incorporates advanced sensors, microprocessors, and communication interfaces for precise control, remote monitoring, and predictive maintenance capabilities. Advanced manufacturing facilities and high-tech industries increasingly adopt digital regulators for process optimization and data analytics.
- Analog:These traditional mechanical regulators rely on springs and diaphragms to provide basic pressure reduction and control. Cost-sensitive industries and smaller-scale operations continue to utilize analog devices for their simplicity and lower upfront investment.
- Pneumatic:These systems use compressed air to actuate and control the regulator, often integrated into larger automated industrial control networks.
- Electro-Mechanical:Combining electrical signals with mechanical components, these regulators offer automated and precise pressure adjustments for complex process control.
- Hydromechanical:Utilizes hydraulic fluid pressure for robust control, typically found in heavy-duty industrial applications requiring significant force and reliability.
The market is gradually shifting from Analog towards Digital, driven by efficiency and data integration demands.
Application:
Application segments are differentiated by the specific process requirements and gas types handled, influencing regulator design and material selection.
- Food & Beverage Processing:This application requires high-purity diaphragm regulators for modified atmosphere packaging, carbonation, and inert gas blanketing. Strict hygiene standards and product quality requirements in Europe and North America drive demand for certified equipment.
- Chemical Plants:Demands robust and corrosion-resistant regulators for managing a wide range of process gases, often under high pressure and hazardous conditions. Safety regulations and the need for precise reactor control necessitate highly reliable and certified devices.
- Welding Plants:Utilizes durable piston regulators for delivering oxygen, acetylene, and shielding gases in metal joining and cutting operations.
- Paint & Coating:Employs regulators for precise control of atomizing air and solvent vapor pressures in industrial spray painting and finishing lines.
- Metal Fabrication:A broad application requiring various regulators for cutting, heating, forming, and surface treatment processes, emphasizing robustness and flow capacity.
While Metal Fabrication remains a foundational application, Food & Beverage Processing presents significant opportunities due to stringent purity demands.
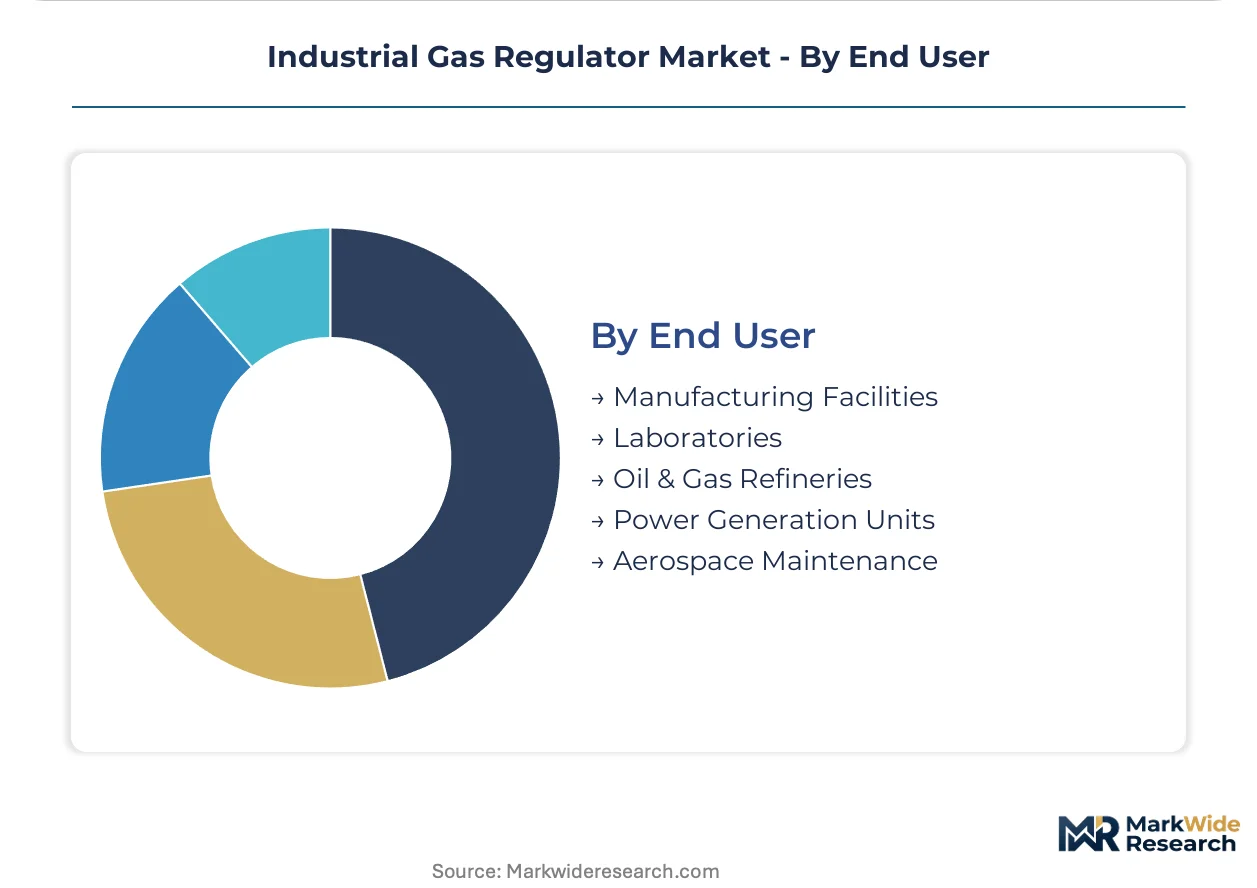
End User:
End-user segmentation highlights diverse operational scales and technical requirements, from large industrial complexes to specialized laboratories.
- Manufacturing Facilities:This segment represents a vast and varied user base, requiring regulators for general industrial processes such as assembly, cleaning, and material handling. Automation and lean manufacturing initiatives in countries like Germany and Japan are driving the adoption of more integrated control solutions.
- Laboratories:Requires highly precise, contamination-free regulators for analytical instrumentation, gas chromatography, and various research and development activities. Stringent experimental protocols and the need for accurate results in pharmaceutical and academic research drive demand for specialized diaphragm regulators.
- Oil & Gas Refineries:Employs heavy-duty and explosion-proof regulators for managing high-pressure process gases, flare systems, and inerting in hazardous environments.
- Power Generation Units:Utilizes robust regulators for fuel gas delivery, turbine control, and inert gas blanketing within conventional and renewable power plants.
- Aerospace Maintenance:Requires specialized regulators for critical applications such as aircraft tire inflation, hydraulic system charging, and inert gas purging in maintenance operations.
The diverse needs of Manufacturing Facilities contrast with the specialized requirements of Laboratories, influencing product development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power for industrial gas regulators shows asymmetry, with established markets like Germany commanding premium pricing for specialized digital solutions. In contrast, high-volume manufacturing hubs such as China prioritize cost-effectiveness for standard mechanical devices. This divergence influences product development and market entry strategies across continents.
United States
The United States market sees demand from its extensive food & beverage processing and chemical sectors. OSHA regulations mandate specific safety features for pressure relief devices in workplace environments. Industrial clusters in the Gulf Coast region, particularly around Houston, drive significant procurement for process control equipment in oil and gas refineries.
China
China's vast manufacturing base, including metal fabrication and electronics production, creates concentrated demand for gas control equipment. Adherence to national GB standards ensures product quality and safety across industrial applications. The Yangtze River Delta region, encompassing cities like Shanghai, serves as a significant hub for high-volume regulator consumption.
Germany
German industrial sectors, particularly advanced manufacturing and automotive assembly, drive demand for high-precision and integrated gas regulators. CE marking directives for pressure equipment mandate stringent design and manufacturing standards for market access. Bavaria, with its strong engineering and high-tech industries, concentrates procurement for specialized automation solutions.
India
India's rapid industrialization and growth in automotive and food processing sectors fuel demand for both basic and mid-range regulators. Compliance with BIS standards is essential for product certification and market acceptance within the country. Maharashtra, particularly around Pune, represents a key manufacturing cluster driving adoption of automation in industrial gas management.
Japan
Japan's semiconductor fabrication and precision manufacturing industries require ultra-high purity and highly sensitive gas regulators. JIS standards ensure the quality and reliability of industrial products used in critical applications. The Kanto region, including Tokyo, is a focal point for advanced research and development, influencing demand for specialized gas control solutions.
Industrial Gas Regulator Market Key Industry Players
Concentration sits with established industrial conglomerates offering broad automation portfolios, alongside specialized component manufacturers. The market structure includes integrated system providers, focused on complete process control solutions, and niche specialists delivering high-performance components. Competitive moves often involve portfolio diversification to capture emerging digital opportunities and strategic partnerships to extend market reach in new industrial applications. This blend of generalists and specialists defines the competitive dynamics in the industrial gas regulator market.
Within the integrated solutions tier, Emerson Electric Co. represents a provider leveraging deep automation expertise for comprehensive process control systems across various industries. Linde plc, a global industrial gas company, occupies a position anchored by its extensive gas supply network and associated hardware offerings. Parker Hannifin Corporation, a US-based entity, exemplifies specialization in high-performance pneumatic and electromechanical components, serving diverse industrial applications that demand precision and durability. These players collectively shape the market's innovation trajectory and service delivery models.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Linde plc |
| Air Liquide S.A. |
| Air Products and Chemicals Inc. |
| Parker Hannifin Corporation |
| Honeywell International Inc. |
| Cavagna Group S.p.A. |
| GCE Group |
| Itron Inc. |
| Others |
Cost & Logistics Intelligence
Average lead times for specialized digital regulators, often extending to 12-16 weeks, reflect a concentrated supply chain for critical components. This supply concentration directly influences premium pricing power for advanced solutions within this market.
Pricing Analysis
Configured-to-order digital regulator pricing commands a premium over standard mechanical units. The dominant pricing structure remains per-unit transactional, with some large industrial buyers securing contract-based long-term agreements. Price differentiation stems from certification levels, such as CE marking compliance, and the degree of customization for specific gas compatibility. Pricing pressure stems from the influx of cost-effective analog piston regulators from Asian manufacturers. Smaller enterprises and basic metal fabrication shops exhibit higher price sensitivity compared to high-purity laboratory or aerospace applications.
Supply Chain Analysis
Strategic stockpiling of critical materials and finished goods characterizes the industrial gas regulator supply chain, balancing just-in-time principles for standard parts with resilience for specialized components. Geographic supply concentration includes China for high-volume manufacturing, Germany for precision engineering, and Japan for advanced material sourcing. Raw material dependencies include 316L stainless steel, specialized elastomers, and embedded microprocessors. Material sourcing volatility represents a key structural risk. Distribution runs through a hybrid model, combining direct sales for integrated solutions with specialized industrial distributors for component sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial gas regulator market requires a robust substitution defense as advanced digital regulators increasingly displace traditional mechanical devices. Incumbents must navigate this technological shift.
For Market Incumbents: Shield existing market share by deepening vertical integration into advanced sensor and IIoT component manufacturing. Incumbents should acquire digital-native specialists to accelerate their smart regulator portfolio development. Investing in ISO 2503 and CE marking certifications for next-generation materials reinforces product credibility against low-cost mechanical alternatives. Expanding bundled service contracts, including predictive maintenance, leverages existing customer relationships to counter digital disruptors.
For New Entrants and Emerging Players: Anchor in emerging high-growth segments like the hydrogen economy infrastructure, targeting specialized high-pressure and embrittlement-resistant regulator designs. Another white-space target is the rapid industrialization in Southeast Asia, particularly for mid-range regulators in manufacturing and automotive assembly. The most penetrable segment remains basic automation in these developing markets. A compelling go-to-market angle involves offering value-based digital solutions paired with robust localized technical support and training.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the digital regulator manufacturing sub-segment, driven by R&D in IIoT and advanced materials. Long-term viability favors entities capable of integrating software-defined control with precision hardware. Acquisition targets should focus on digital-native specialists with proven sensor integration capabilities or material science innovators addressing hydrogen embrittlement. The signal to watch for inflection is the sustained year-over-year increase in IIoT platform integration rates within new industrial installations.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Solution Acquisition | Accelerates market entry for advanced process control systems in Europe. |
| Hydrogen Regulator R&D | Positions firms to capture demand from fuel cell and industrial hydrogen applications. |
| Bundled Service Expansion | Strengthens customer loyalty and recurring revenue streams for Linde plc. |
| Manufacturing Footprint in Southeast Asia | Accesses new industrialization markets in Vietnam and Indonesia for mid-range regulators. |
| ISO 2503 Certification Investment | Ensures product compliance and market access for welding equipment in global markets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews, complemented by rigorous secondary validation. Interviewees included plant managers, procurement leads, R&D directors, and safety officers across diverse industrial verticals. Secondary data sources encompassed ISO standards, OSHA reports, national industrial statistics, and company financial filings. This approach utilized both bottom-up and top-down triangulation to ensure data accuracy.
The forecasting framework projects market evolution across the analysis window, integrating various macro and microeconomic indicators. Segmentation dimensions modeled include product type, technology, application, end-user, and regional regulatory clusters. Compound annual growth rates were derived through a combination of regression analysis and market share projections. Key industry-specific forecast inputs included global industrial output growth rates and regional regulatory compliance costs.
Decision-makers should treat outputs as directional under current base assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions regarding stable raw material supply and consistent regulatory enforcement. Specific risk factors, such as raw material price shocks or unforeseen new regulatory mandates, could significantly alter market trajectories. Revision becomes warranted when global industrial production indices or key material costs cross defined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
Europe Syngas Market
Industrial Gases
Asia-Pacific Industrial Gases Market
Industrial Gases
Nitrogen Gas Springs Market
Industrial Gases
Global Rare Gases Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
North America Industrial Gases Market
Industrial Gases
Gas Processing Market
Industrial Gases
Argon Gas Market
Industrial Gases
LAMEA Industrial Nitrogen Market
Industrial Gases
Nitrogen Gas Market
Industrial Gases
Sulfur Recovery Tail Gas Analyzer Market
Industrial Gases
Industrial Gases for Metals and Metal Fabrication Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market
Industrial Gases
Global Industrial Denox Systems and Services Market