
 Global Industrial Gas Market | 2026-2036
Global Industrial Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Gas Market Outlook
Electronic-grade purity specifications above 99.9999% is collapsing the gap between commodity air separation and premium gas supply. Linde plc leverages captive production of ultra-high-purity nitrogen to dominate semiconductor foundry contracts. Air Liquide sustains margin leadership through on-site pipeline networks anchored to petrochemical clusters in Belgium and Singapore. Taiyo Nippon Sanso Corporation specializes in rare gas recovery systems that differentiate its position in laser-grade argon.
Industrial gases encompass atmospheric and process gases produced through cryogenic distillation, pressure swing adsorption, or steam methane reforming, with purity grades spanning from standard commercial specifications to parts-per-billion contamination limits for semiconductor lithography. These gases serve as feedstocks, inerting agents, oxidizers, or coolants across virtually all heavy manufacturing and precision fabrication processes. Oxygen commands the largest volume share in metal manufacturing and chemical processing, where oxyfuel combustion and gasification reactions consume tonnage-scale quantities. Hydrogen represents the fastest-expanding product category, driven by refinery desulfurization and emerging ammonia synthesis for maritime fuel applications. Electronics applications concentrate margin pools in bulk supply and liquid tank delivery modes, where long-term take-or-pay contracts lock in decade-spanning revenue visibility.
The EPA enforces emissions thresholds for hydrogen production facilities under the Clean Air Act, compelling operators to deploy carbon capture or electrolytic alternatives. EMA and REACH frameworks govern pharmaceutical-grade gas certification in Europe, while China's MEE imposes dual carbon goals that restrict coal-based syngas routes. FDA oversight of medical oxygen and nitrous oxide purity standards shapes healthcare procurement protocols in the United States. Stakeholders must monitor electrolyzer cost curves and carbon border adjustment mechanisms to determine whether green hydrogen premiums justify upstream capacity commitments.
Market Dynamics
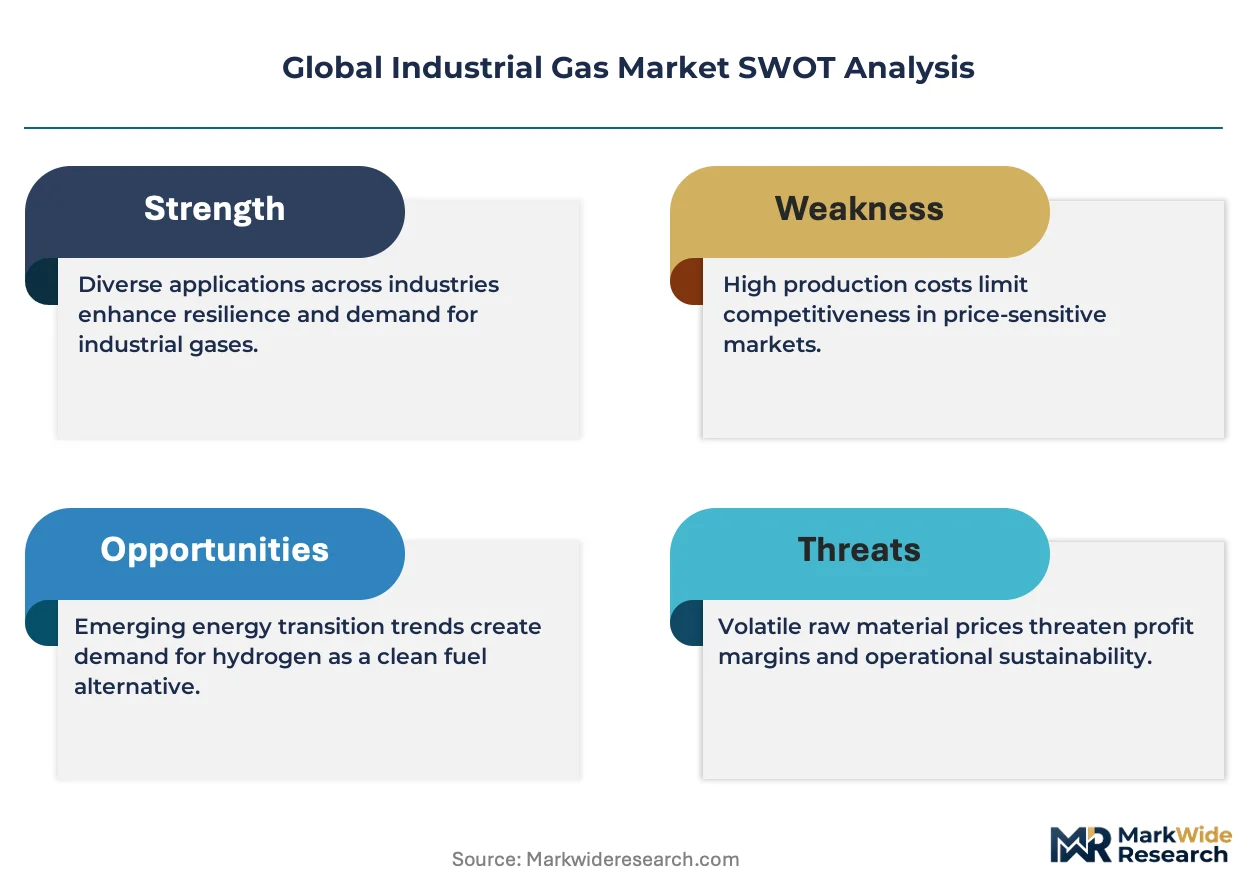
Electronic-grade purity specifications above 99.9999% are collapsing the traditional boundary between commodity air separation and premium gas supply, forcing asset reconfiguration across production networks.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated gases are redirecting semiconductor fabs toward reclaimed and recycled rare gas alternatives, expanding recovery system deployments.
- Semiconductor lithography:Extreme ultraviolet lithography tools require parts-per-billion contamination limits in nitrogen and argon, pulling capacity toward ultra-high-purity infrastructure.
- China's dual carbon goals:Coal-based syngas restrictions under MEE enforcement are accelerating electrolytic hydrogen investments in coastal industrial clusters.
Market Restraints
- Natural gas feedstock volatility:Steam methane reforming economics swing with Henry Hub and TTF pricing, compressing margins at hydrogen production facilities.
- ASU equipment concentration:Cryogenic air separation unit manufacturing concentrates among German and Japanese engineering houses, creating 18-24 month delivery bottlenecks.
- Grid carbon intensity:Electrolytic hydrogen produced in coal-heavy grids fails EU carbon border adjustment thresholds, limiting export eligibility.
Strategic Opportunities
- India's PLI scheme:Semiconductor and solar manufacturing incentives are creating first-mover openings for on-site gas supply contracts in Gujarat and Tamil Nadu.
- Ammonia maritime fuel:Bunkering infrastructure development in Rotterdam and Singapore is generating demand for low-carbon hydrogen feedstock at scale.
- Carbon capture integration:45Q credits and EU Innovation Fund support are enabling blue hydrogen cost parity with unabated production in US Gulf Coast and Netherlands clusters.
Industry Challenges
- ASU commissioning timelines:Multi-year construction cycles for large-scale air separation units mismatch semiconductor fab ramp schedules, requiring pre-commitment contracting.
- Electronic-grade certification:SEMI and customer-specific contamination protocols demand 12-18 month qualification periods that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Gas Market |
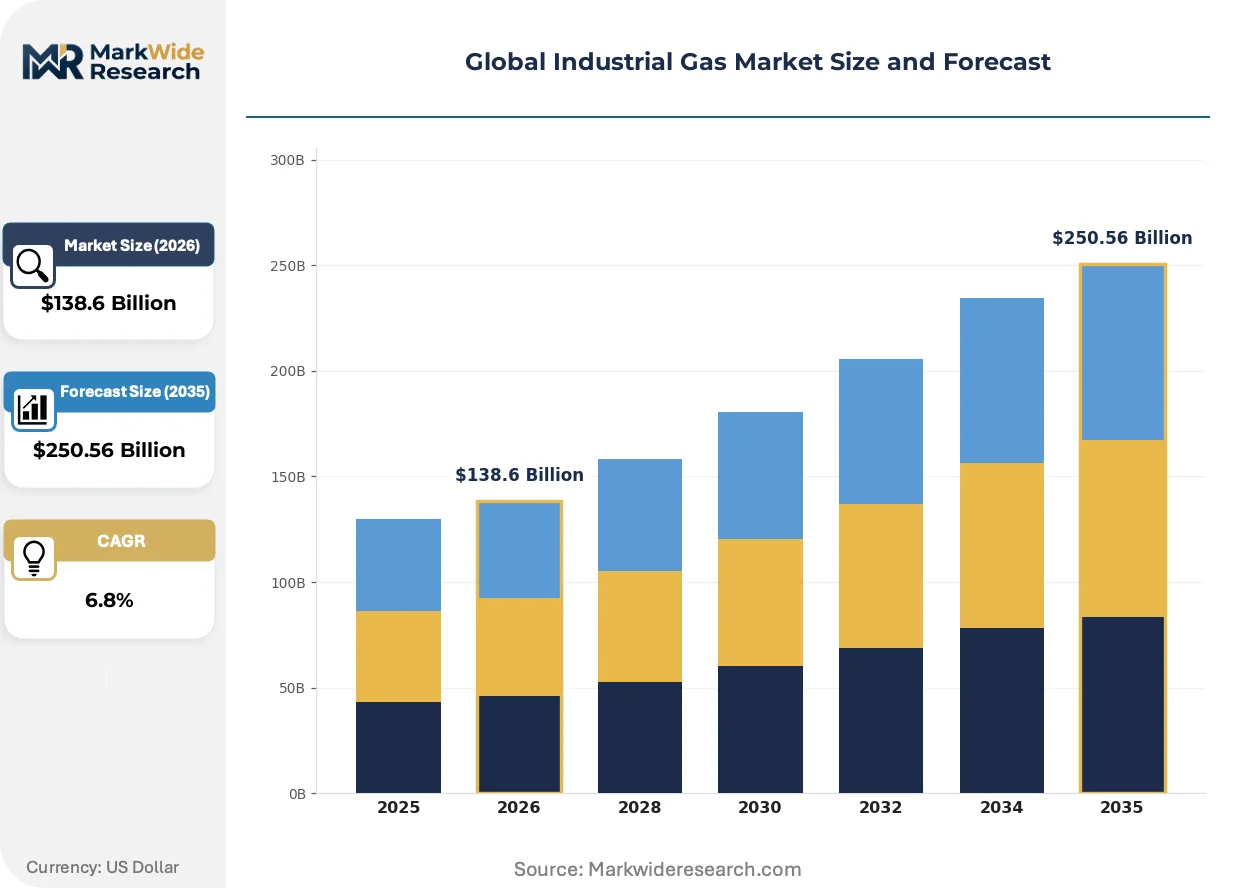
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $250.56 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen, Nitrogen, Argon, Hydrogen Application: Metal Manufacturing, Chemical Processing, Food Packaging, Electronics End User: Healthcare, Oil & Gas, Automotive, Aerospace Delivery Mode: Cylinders, Liquid Tanks, Pipe Distribution, Bulk Supply |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals Inc., Taiyo Nippon Sanso Corporation, Messer Group GmbH, BASF SE, SOL Group, Iwatani Corporation, Matheson Tri-Gas Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Gas Market Strategic Shifts
Production technology and regulatory frameworks are converging to separate hydrogen supply into color-coded quality tiers that command divergent pricing and offtake security.
Proton-exchange membrane electrolyzers are displacing alkaline systems in semiconductor and pharmaceutical applications where rapid load-following and compact footprint outweigh capital cost premiums. Fab operators in Taiwan and South Korea are specifying PEM units for on-site hydrogen generation to bypass liquid delivery logistics. The shift is compressing alkaline equipment's addressable market to bulk chemical and refining applications where steady-state operation dominates.
The EU F-Gas Regulation's 2030 phase-down targets are forcing refrigerant gas users toward carbon dioxide and ammonia alternatives in cold chain and industrial cooling. Equipment manufacturers in Germany and Italy are reengineering compressor systems for higher-pressure CO2 operation. Medical and electronics end-uses retain fluorinated gas access through quota allocations, creating two-tier supply availability.
Long-term take-or-pay contracts with decade-spanning terms are consolidating procurement authority at headquarters level, displacing site-level spot purchasing for bulk nitrogen and oxygen. Semiconductor foundries in Arizona and Dresden are centralizing gas supply decisions under procurement teams that negotiate directly with Linde and Air Liquide. The concentration shifts margin pressure onto distributors and local packagers excluded from direct mill relationships.
Global Industrial Gas Market Segmentation
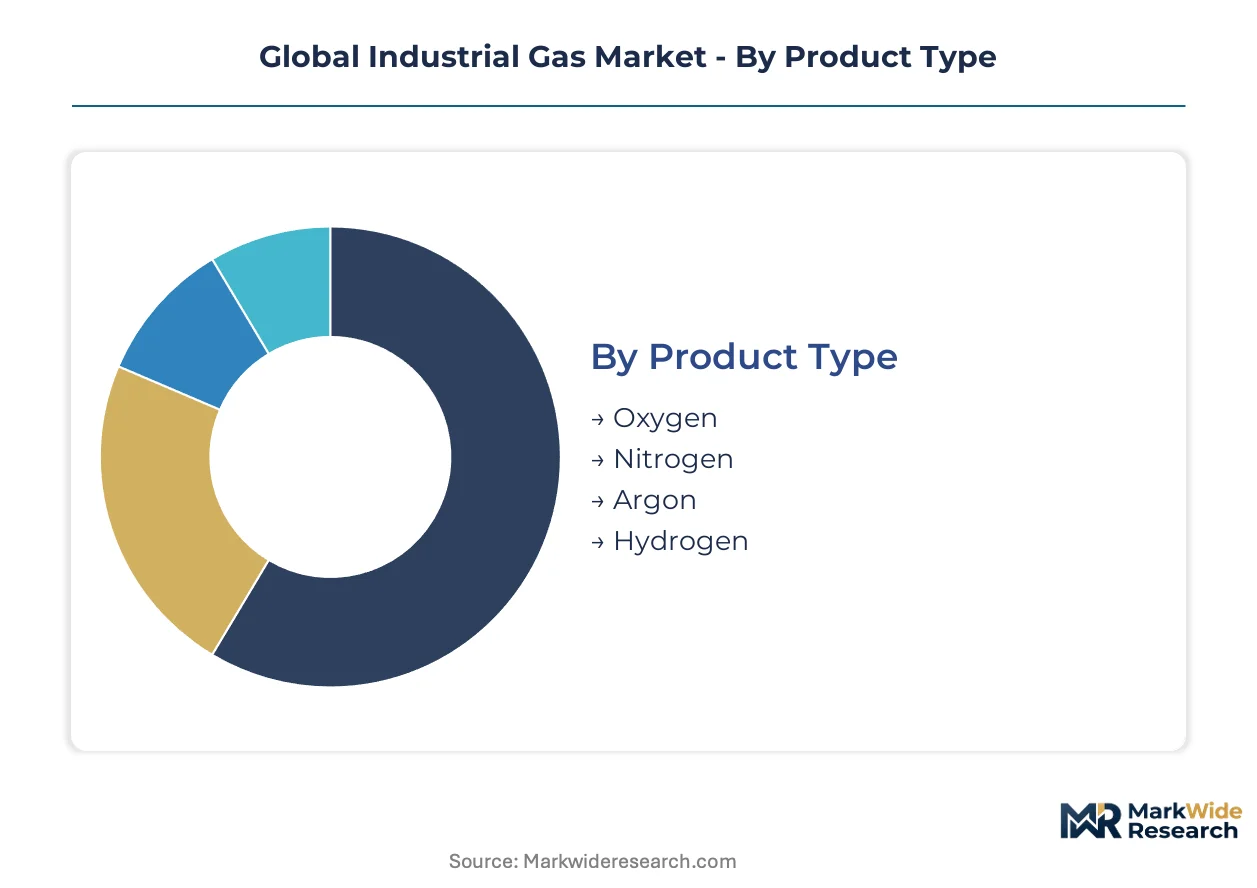
Industrial gas markets fragment across purity grades, delivery logistics, and end-use specifications that dictate equipment investment and contract structures. Understanding segment boundaries reveals where margin pools concentrate and where commoditization pressures dominate procurement.
Product Type:
Oxygen and nitrogen circulate through domestic supply networks anchored to regional air separation clusters, while hydrogen and rare gases cross borders to serve specialized fabrication demand.
- Oxygen:Cryogenic distillation yields standard and high-purity grades for oxyfuel combustion and medical therapy. Steel mills in China and India absorb tonnage-scale volumes for basic oxygen furnace operations, though electric arc furnace conversion is moderating growth in developed markets.
- Nitrogen:Inerting and blanketing applications span food processing to semiconductor cleanrooms. Electronics-grade specifications above 99.9999% purity command premium pricing in Taiwan, South Korea, and Arizona fab clusters where contamination protocols are strictest.
- Argon:Shielding gas for welding and specialty steel production, with laser-grade recovery systems differentiating supply tiers.
- Hydrogen:Refinery desulfurization and emerging ammonia synthesis applications are climbing the fastest as electrolytic production scales in coastal industrial zones.
Oxygen holds the largest share; momentum sits with hydrogen.
Application:
Cost tier stratification separates bulk commodity supply from electronic-grade certification requirements that demand dedicated production assets.
- Metal Manufacturing:Oxygen-fuel cutting and argon-shielded welding consume standard commercial grades through pipeline and bulk delivery modes. Integrated steel producers in Germany and Japan negotiate long-term take-or-pay contracts that lock in decade-spanning volume commitments.
- Chemical Processing:Hydrogen feedstock for ammonia and methanol synthesis, plus nitrogen inerting for hazardous reaction containment. US Gulf Coast and Rotterdam clusters concentrate demand where carbon capture integration is becoming a procurement qualifier.
- Food Packaging:Modified atmosphere systems using nitrogen and carbon dioxide to extend shelf life. Regional dairy and meat processors in Brazil and Australia drive cylinder and microbulk delivery demand.
- Electronics:Ultra-high-purity nitrogen and argon for lithography and etching processes. SEMI certification protocols require 12-18 month qualification periods that favor incumbent suppliers with established fab relationships.
Metal manufacturing commands volume leadership; electronics applications generate the steepest margin expansion.
End User:
Customer type determines contracting sophistication, with healthcare and aerospace specifying certification protocols that exclude commodity suppliers.
- Healthcare:Medical oxygen and nitrous oxide for respiratory therapy and surgical anesthesia. FDA and EMA purity standards shape procurement protocols, with homecare oxygen concentrators displacing cylinder delivery in post-acute settings.
- Oil & Gas:Hydrogen for hydrocracking and desulfurization, plus nitrogen for enhanced oil recovery. Middle Eastern and US Permian Basin operators specify on-site generation to avoid logistics bottlenecks.
- Automotive:Welding shielding gases and heat treatment atmospheres for powertrain manufacturing. Electric vehicle battery cell production is expanding nitrogen demand in gigafactory clusters.
- Aerospace:High-purity nitrogen and helium for fuel tank inerting and leak detection. Launch vehicle propulsion systems in Florida and French Guiana require space-grade certification tiers.
Healthcare maintains the most stable demand profile; aerospace specifications are tightening fastest.
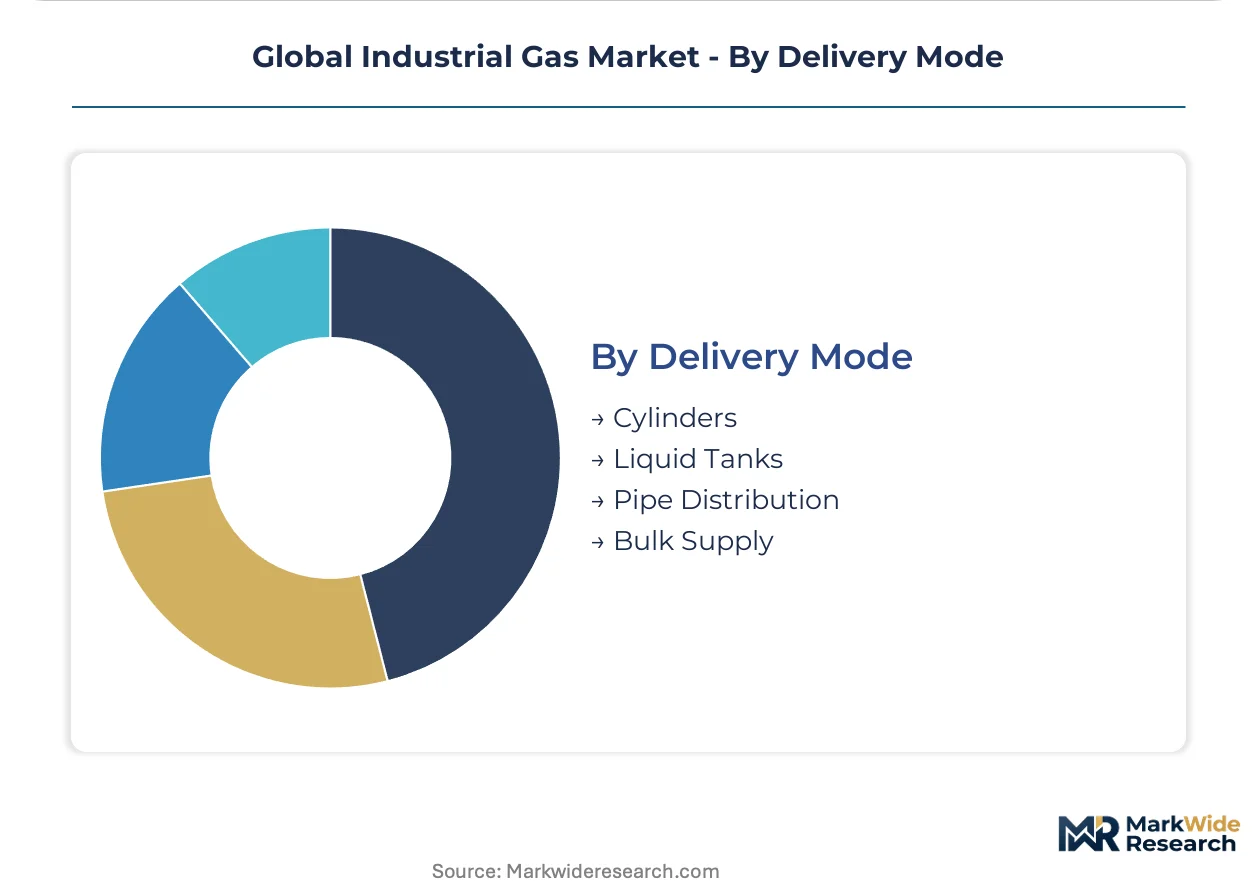
Delivery Mode:
Volume scale and geographic concentration determine whether pipeline, liquid tank, or packaged gas economics prevail.
- Cylinders:Packaged gas for distributed users with intermittent consumption patterns. Welding contractors and small machine shops in fragmented industrial zones rely on distributor networks for oxygen and acetylene supply.
- Liquid Tanks:Cryogenic storage for medium-volume consumers lacking pipeline access. Food processors and electronics subcontractors in Taiwan and Malaysia specify vacuum-insulated vessels for nitrogen security.
- Pipe Distribution:On-site pipeline networks anchored to petrochemical and steel clusters. Air Liquide's Antwerp and Singapore infrastructure exemplifies captive supply arrangements with 15-20 year contract horizons.
- Bulk Supply:Cryogenic tanker delivery for high-volume spot and contract demand. Semiconductor foundries in Dresden and Arizona centralize procurement authority at headquarters level for bulk nitrogen negotiations.
Pipeline distribution captures the most permanent revenue visibility; liquid tank installations are expanding most quickly in emerging manufacturing zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net trade positions in high-purity hydrogen and electronic-grade nitrogen are shifting as coastal industrial clusters in China, the United States, and Germany absorb disproportionate import volumes. Export competitiveness now hinges on carbon intensity of production rather than feedstock proximity alone.
China
Semiconductor fabrication capacity expansion in Shanghai and Hefei is pulling tonnage-scale nitrogen and argon through Yangtze River Delta pipeline networks. MEE enforcement of dual carbon goals is restricting coal-based syngas routes and accelerating electrolytic hydrogen investments in Ningbo and Tianjin clusters. Coastal industrial zones are commissioning carbon capture retrofits to preserve export eligibility under anticipated EU carbon border adjustments.
United States
Hydrogen demand from Gulf Coast refineries and emerging ammonia bunkering projects in Texas is reshaping interregional pipeline flows. EPA Clean Air Act thresholds compel carbon capture deployment or electrolytic alternatives at new production facilities. Arizona semiconductor foundries are centralizing procurement authority for bulk nitrogen supply, locking in decade-spanning take-or-pay contracts with incumbent suppliers.
Germany
Ruhr Valley steel decarbonization and chemical processing clusters in Ludwigshafen anchor pipeline network utilization for oxygen and hydrogen. EU F-Gas Regulation phase-down schedules redirect semiconductor fabs toward reclaimed rare gas alternatives, expanding recovery system deployments in Dresden and Munich. The country's national pharmaceutical regulator enforces EMA-aligned purity standards that shape medical oxygen procurement protocols.
Japan
Extreme ultraviolet lithography tool deployment in Kyushu and Hiroshima fabs requires parts-per-billion contamination limits in nitrogen and argon. METI industrial policy supports domestic rare gas recovery infrastructure to reduce import dependency for semiconductor-grade supply. Chubu and Kansai industrial corridors concentrate demand for high-purity hydrogen in electronics and specialty materials manufacturing.
India
PLI scheme incentives for semiconductor and solar manufacturing in Gujarat and Tamil Nadu are creating first-mover openings for on-site gas supply contracts. BIS certification requirements for industrial gas purity are tightening procurement standards for electronics applications. Mumbai-Pune and Chennai-Bengaluru industrial corridors are attracting liquid tank installation investments to serve medium-volume electronics subcontractors.
Global Industrial Gas Market Competitive Environment
Concentration sits with diversified industrial conglomerates that combine captive air separation capacity with pipeline network ownership across multiple geographies. Three to five integrated operators control the majority of tonnage-scale supply contracts in semiconductor and petrochemical clusters, while regional packagers and distributors serve fragmented welding and medical oxygen demand. Strategic archetypes span integrated majors with on-site infrastructure, regional pipeline operators, and specialty gas distributors with certification expertise. Dominant competitive moves include long-term take-or-pay contracting for fab supply and carbon capture integration for hydrogen cost parity.
Among European-based operators, Linde plc and Air Liquide exemplify the integrated major archetype through pipeline network ownership and on-site supply arrangements. Taiyo Nippon Sanso Corporation represents the Asia-Pacific specialist tier with positioning in rare gas recovery systems. These three names anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals Inc. |
| Taiyo Nippon Sanso Corporation |
| Messer Group GmbH |
| BASF SE |
| SOL Group |
| Iwatani Corporation |
| Matheson Tri-Gas Inc. |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four month delivery bottlenecks for cryogenic air separation units concentrate pricing power with German and Japanese engineering houses, while semiconductor fabs absorb premium markups to secure ultra-high-purity nitrogen ahead of fab ramp schedules. Long-term take-or-pay contracts with decade-spanning terms lock in revenue visibility for pipeline operators, compressing margin pools for spot-market distributors excluded from direct foundry relationships.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across electronic-grade certification, volume scale, and geographic delivery cost. Price differentiation separates SEMI-certified nitrogen for EUV lithography from standard commercial grades used in metal manufacturing. Cost compression in commodity oxygen supply is intensifying because electric arc furnace conversion moderates steel mill demand in developed markets. Welding contractors and small machine shops exhibit the highest price sensitivity, while semiconductor foundries prioritize contamination protocols over unit economics.
Supply Chain Analysis
ASU equipment manufacturing concentrates in Germany and Japan, with rare gas recovery systems and electrolyzer components drawing from specialized engineering capabilities in these markets. Feedstock dependencies rest on natural gas for steam methane reforming, grid electricity for electrolytic hydrogen, and atmospheric air for cryogenic distillation. Single-source vulnerability in cryogenic valve and heat exchanger supply creates chokepoint exposure for capacity expansion timelines. Distribution runs through on-site pipeline networks in petrochemical clusters, liquid tank installations for medium-volume electronics subcontractors, and cylinder networks serving fragmented welding demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial gas market sits in a cyclical recovery phase, with semiconductor capital expenditure cycles and refinery hydrogen demand creating sequential expansion windows across end-use segments.
For Market Incumbents: Secure long-term take-or-pay contracts with Arizona and Dresden semiconductor foundries before competitor capacity comes online, locking in decade-spanning revenue visibility. Deepen backward integration into electrolyzer manufacturing to capture green hydrogen margin expansion as EU carbon border adjustments tighten. Carbon capture integration at US Gulf Coast hydrogen facilities represents a critical defensive lever against unabated production cost advantages. For New Entrants and Emerging Players: Lead with on-site gas supply contracts in Gujarat and Tamil Nadu, where India's PLI scheme incentives are creating first-mover openings before incumbent pipeline networks extend. Target electronics subcontractors in Taiwan and Malaysia with liquid tank installations, bypassing the 12-18 month SEMI certification barriers that protect established fab relationships. A certification-focused go-to-market angle around rare gas recovery systems differentiates positioning against integrated majors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive air separation assets but non-core gas supply operations, particularly in European chemical processing clusters. Over a multi-year holding period, hydrogen infrastructure plays offer structural exposure to ammonia maritime fuel and refinery desulfurization demand. Watch electrolyzer cost curves and EU carbon border adjustment implementation timing as the primary inflection signal for green hydrogen premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Semiconductor foundries in Arizona lock in decade-spanning nitrogen contracts with incumbent suppliers. |
| Backward Integration | Pipeline operators acquire electrolyzer manufacturing capacity to capture green hydrogen margin expansion. |
| Joint Venture | Coastal industrial clusters in Ningbo and Tianjin partner for carbon capture retrofits preserving EU export eligibility. |
| Capacity Expansion | Rare gas recovery system deployments expand in Dresden and Munich under EU F-Gas Regulation phase-down pressure. |
| Green Manufacturing Transition | Proton-exchange membrane electrolyzers displace alkaline systems in Taiwan and South Korea fab specifications. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with plant managers at air separation facilities, procurement leads at downstream semiconductor foundries, and distribution channel partners; and secondary validation through customs and trade data, SEC filings from integrated gas suppliers, and industry association reports from ACC and Cefic. Bottom-up triangulation across regional production hub estimates and top-down cross-checks against end-use demand aggregates ensured analytical consistency.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning purity grade tiers, end-use industries from metal manufacturing to electronics, delivery mode configurations, and regional production clusters. CAGRs were derived from volume trajectory analysis incorporating semiconductor fab buildout schedules, refinery hydrogen demand curves, and steel industry oxygen consumption patterns. Electrolyzer cost evolution and carbon capture deployment rates served as critical forecast sensitivity inputs.
Forecasts assume regulatory continuity in EPA Clean Air Act enforcement, EU F-Gas Regulation phase-down schedules, and China's MEE dual carbon goals; material policy shifts would require re-modeling hydrogen production economics and rare gas recovery investment returns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
Industrial Gases for Metals and Metal Fabrication Market
Industrial Gases
Gas Processing Market
Industrial Gases
LAMEA Industrial Nitrogen Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
US Industrial Gas Regulator Market
Industrial Gases
South-East Asia (SEA) Syngas Market
Industrial Gases
Gas and Liquid Argon Market
Industrial Gases
Commercial Hydrogen Market
Industrial Gases
Neon Gas for Laser Market
Industrial Gases
Welding Gas Market
Industrial Gases
Industrial Hydrogen Market
Industrial Gases
Asia-Pacific Syngas Market
Industrial Gases
Asia-Pacific Industrial Gases Market
Industrial Gases
Helium Market
Industrial Gases
Industrial Nitrogen Market