
 Dielectric Gases Market | 2026-2036
Dielectric Gases Market Size, Share, and Industry Trends Forecast 2026-2036
Dielectric Gases Market Analysis
Fluoronitrile blending technology is rewriting the dielectric gas landscape by enabling SF6-free insulation at comparable breakdown voltages. 3M Company leverages its Novec portfolio to anchor premium positions in eco-efficient switchgear formulations. Linde PLC sustains global supply chain density through captive production of fluorinated gases across multiple continents. Solvay competes on material science depth, specializing in custom gas mixtures for medium-voltage hybrid installations.
Dielectric gases are electrically insulating media with breakdown strengths exceeding that of air, typically comprising sulfur hexafluoride, nitrogen, carbon dioxide, or fluoronitrile compounds formulated to quench arcs and prevent electrical discharge in enclosed equipment. SF6 retains dominance in legacy high-voltage infrastructure despite its potent greenhouse gas profile, while C4F7N blends represent the fastest-growing gas type as OEMs redesign switchgear around lower global-warming-potential chemistries. Application demand concentrates in gas-insulated substations where space constraints and reliability requirements justify premium gas formulations, whereas transformer deployments favor nitrogen-based systems for cost-sensitive utility procurement.
The EU F-Gas Regulation and EPA greenhouse gas reporting requirements are forcing utilities to quantify and phase down SF6 inventories, directly stimulating replacement demand for alternative dielectric media. IEC standards for gas-insulated electrical equipment are tightening purity and handling specifications, raising compliance barriers for regional gas suppliers. Stakeholders must monitor the trajectory of carbon border adjustments and utility decarbonization commitments to anticipate which voltage classes and geographies will convert first.
Market Dynamics
The EU F-Gas Regulation is forcing utilities to retire sulfur hexafluoride installations across high-voltage grids, compressing the timeline for fluoronitrile blend adoption and reshaping supplier-procurement relationships throughout the electrical equipment value chain.
Growth Catalysts
- EU F-Gas Regulation phase-down mandates:Binding reduction targets for fluorinated greenhouse gases are compelling transmission operators in Germany, France, and Italy to accelerate SF6 replacement programs in gas-insulated switchgear.
- Renewable energy integration requirements:Grid modernization programs in Japan and the United States demand upgraded gas-insulated substations capable of handling variable renewable loads with higher switching frequency.
- C4F7N blending technology maturation:OEMs have validated fluoronitrile mixtures at comparable dielectric strength to SF6, removing technical barriers to commercial deployment in medium-voltage hybrid installations.
Market Restraints
- Fluoronitrile production concentration:C4F7N synthesis depends on specialized fluorochemical capabilities concentrated among a limited set of European and North American chemical producers.
- Retrofit cost burden:Existing SF6-insulated switchgear requires complete redesign rather than gas substitution, imposing capital intensity on utilities with extensive installed bases.
- Purity specification stringency:IEC 60376 and 60480 standards for gas-insulated equipment mandate handling protocols that raise compliance barriers for regional gas blenders without certified infrastructure.
Strategic Opportunities
- India transmission expansion:The country's central electricity regulator has approved greenfield ultra-high-voltage corridors where SF6-free specifications are gaining traction in tender requirements.
- Digital gas monitoring integration:Convergence of optical sensing technology with predictive maintenance platforms enables real-time purity tracking, creating service revenue streams for gas suppliers.
- Carbon border adjustment alignment:EU importers of electrical equipment face embedded emissions reporting requirements that favor suppliers with verified low-GWP insulation media.
Industry Challenges
- Fluorochemical handling certification:Technician training for C4F7N blends lags deployment timelines, creating bottlenecks in field service capacity for OEM service networks.
- Legacy equipment compatibility:Hybrid switchgear designs must accommodate both SF6 and alternative gases during transition periods, complicating inventory management for utilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dielectric Gases Market |
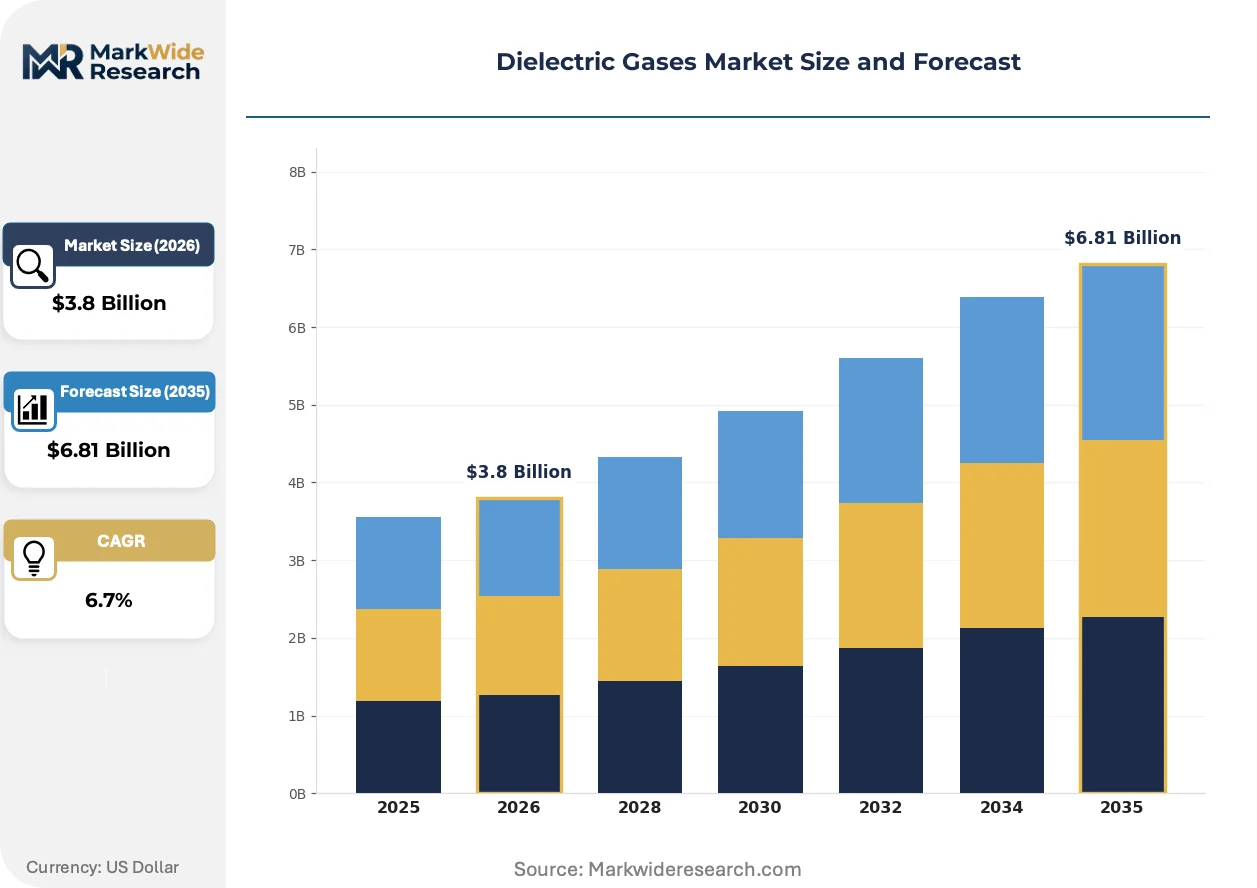
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Gas Type: SF6, N2, CO2, C4F7N Application: Switchgear, Transformers, Gas-Insulated Substations, Capacitors End User: Utilities, Industrial, Commercial, Renewable Energy Technology: High Voltage, Medium Voltage, Low Voltage, Hybrid |
| Companies Covered | 3M Company, Linde PLC, Solvay, Concorde Specialty Gases, KPL International Limited, Matheson Tri-Gas, Messer Group, Kanto Denka Kogyo Co., Ltd, Showa Denko K.K., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dielectric Gases Market Emerging Trajectories
Fluoronitrile formulation advances and regulatory enforcement tightening are converging to accelerate the displacement of legacy insulation chemistries across transmission infrastructure procurement.
Three-dimensional electrode designs optimized for C4F7N-CO2 mixtures are rendering obsolete traditional coaxial geometries engineered around SF6's unique thermodynamic properties. ABB, Siemens, and Mitsubishi Electric have each commercialized compact switchgear platforms exploiting these geometries. The structural consequence is compressing equipment footprints while maintaining equivalent voltage ratings, eliminating the space-efficiency advantage that historically justified SF6 retention.
The EPA's greenhouse gas reporting requirements for electrical equipment owners have tightened leak detection and inventory tracking obligations for utilities operating above 17,820 pounds of SF6 equivalent. Industrial consequence includes mandatory third-party verification of gas handling procedures and accelerated retirement schedules for vintage installations. High-voltage transmission operators in California, Texas, and the Northeast corridor are most affected, responding by embedding SF6-free specifications into new procurement tenders.
Utility procurement departments are consolidating supplier relationships around full-service gas management contracts that bundle supply, recovery, and reclamation. Equipment manufacturers are disintermediating traditional gas distributors by offering captive gas services tied to switchgear sales. This pattern is most visible in German and Japanese markets, where grid operators face the strictest inventory accountability under national implementations of the EU F-Gas Regulation and Japan's fluorocarbon emission control law.
Dielectric Gases Market Segmentation
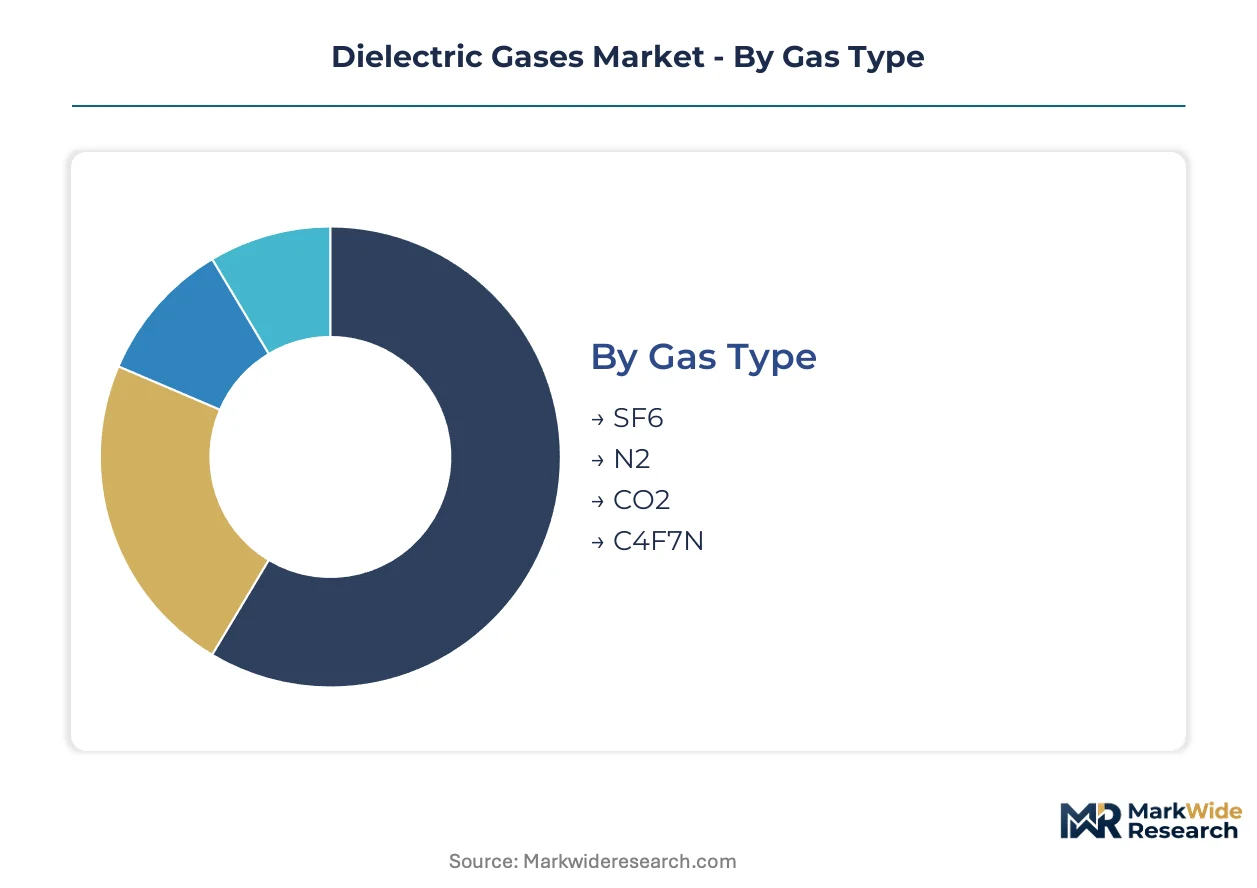
Dielectric gas procurement decisions fragment across voltage ratings, environmental compliance tiers, and equipment lifecycle stages. Understanding these segment boundaries reveals where substitution economics favor C4F7N blends over legacy SF6 infrastructure.
Gas Type:
Cost tier differentiation separates commodity industrial gases from fluoronitrile formulations commanding technical premiums.
- SF6:Sulfur hexafluoride delivers dielectric strength approximately three times air density, enabling compact high-voltage switchgear designs. German and Japanese utilities maintain substantial installed bases despite EU F-Gas Regulation phase-down mandates forcing inventory retirement.
- C4F7N:Fluoronitrile compounds blended with CO2 achieve comparable insulation performance at fractionally reduced global warming potential. OEMs in France and Italy are redesigning medium-voltage platforms around this chemistry to meet binding emissions reduction targets.
- N2:Nitrogen serves cost-sensitive transformer applications where dielectric requirements permit lower breakdown thresholds. Indian power sector procurement favors this specification for distribution infrastructure.
- CO2:Carbon dioxide functions primarily as a carrier gas in C4F7N mixtures rather than standalone insulation. Industrial gas suppliers integrate captive CO2 production to secure blend supply chains.
SF6 holds installed capacity across legacy transmission assets. C4F7N is rotating up the share rankings as tender specifications harden around low-GWP alternatives.
Application:
Application segmentation tracks equipment voltage class and spatial constraints driving gas selection trade-offs.
- Switchgear:Gas-insulated switchgear demands highest dielectric performance where footprint compression justifies premium formulations. California and Texas utilities now embed SF6-free requirements in procurement documents under EPA greenhouse gas reporting obligations.
- Gas-Insulated Substations:GIS installations concentrate in dense urban corridors of Japan and Germany where land scarcity overrides cost sensitivity. METI efficiency standards and national F-Gas implementations accelerate alternative gas validation.
- Transformers:Liquid-immersed and dry-type transformer designs predominantly utilize nitrogen or air insulation. Cost-driven utility procurement in India favors these specifications for greenfield distribution networks.
- Capacitors:Power capacitor applications require specialized gas mixtures for reactive power compensation. Demand concentrates in industrial manufacturing clusters requiring power quality management.
Switchgear commands formulation premiums. Gas-insulated substations are climbing the fastest as urban densification intensifies.
End User:
Customer type segmentation distinguishes regulated utilities from industrial self-generation and commercial facility operators.
- Utilities:Transmission and distribution operators face binding regulatory accountability for SF6 inventory under EU F-Gas Regulation and EPA mandates. German grid operators have consolidated supplier relationships around full-service gas management contracts.
- Renewable Energy:Wind and solar farm developers require switchgear capable of handling variable generation profiles with elevated switching frequency. Japanese offshore wind projects specify C4F7N-compatible equipment to align with national decarbonization commitments.
- Industrial:Heavy manufacturing and petrochemical facilities operate captive substations with shorter depreciation horizons permitting faster technology turnover. Texas and Louisiana industrial corridors show early alternative gas adoption.
- Commercial:Data center and large facility operators prioritize reliability over gas specification, typically deferring to OEM recommendations. Procurement concentrates through equipment manufacturers rather than direct gas sourcing.
Utilities retain volume concentration. Renewable energy developers are expanding most quickly as generation capacity buildouts accelerate.
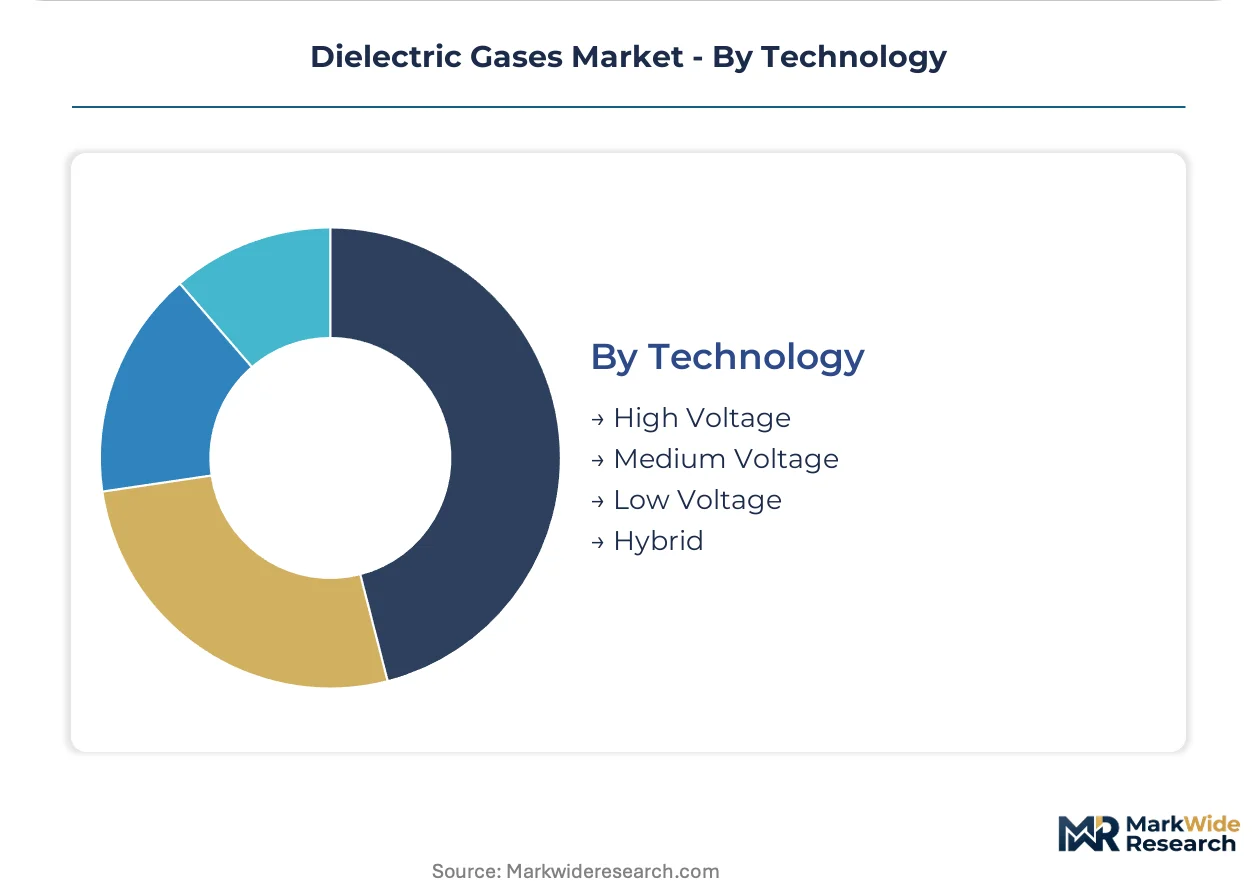
Technology:
Voltage class segmentation determines dielectric stress requirements and corresponding gas formulation complexity.
- High Voltage:Systems above 72.5 kV demand maximum insulation integrity where C4F7N-CO2 mixtures have achieved technical validation. European transmission operators lead deployment as F-Gas Regulation timelines compress.
- Medium Voltage:1-72.5 kV equipment represents the primary commercialization frontier for fluoronitrile blends. OEMs have optimized three-dimensional electrode geometries specifically for these formulations.
- Hybrid:Transitional designs accommodating both SF6 and alternative gases during fleet conversion periods. Japanese utilities favor this approach to manage inventory complexity during regulatory transition.
- Low Voltage:Below 1 kV applications predominantly utilize air or nitrogen insulation with minimal dielectric gas content. Cost minimization drives specification in this tier.
High voltage maintains technology leadership investment. Medium voltage is gaining share fastest as validation completes and production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical producers supply fluoronitrile formulations to European and North American utilities replacing SF6 infrastructure. Japanese gas manufacturers export C4F7N blends to Southeast Asian grid operators modernizing transmission networks.
United States
Texas and California utilities drive demand for alternative dielectric gases in high-voltage corridors. EPA greenhouse gas reporting requirements mandate third-party verification of SF6 handling procedures above threshold quantities. Houston industrial clusters host gas reclamation facilities serving Gulf Coast petrochemical substations.
Germany
Transmission operators in Bavaria and North Rhine-Westphalia accelerate SF6 replacement programs under binding EU F-Gas Regulation targets. The national implementation requires quantified inventory phase-downs across high-voltage switchgear. Siemens Energy anchors fluoronitrile validation programs from Berlin-Brandenburg manufacturing centers.
Japan
Offshore wind developers in Kyushu and Chubu specify C4F7N-compatible equipment for variable generation integration. METI efficiency standards enforce strict emissions accountability for fluorinated gases in electrical equipment. Tokyo-area grid operators consolidate supplier relationships around full-service gas management contracts.
India
Maharashtra and Gujarat transmission utilities evaluate SF6-free specifications for greenfield ultra-high-voltage corridors. The Central Electricity Authority approves tender requirements favoring low-GWP insulation media in new infrastructure. Mumbai industrial clusters pilot nitrogen-based systems for cost-sensitive distribution networks.
France
Électricité de France renovates gas-insulated substations in Île-de-France and Auvergne-Rhône-Alpes under national decarbonization commitments. The EU F-Gas Regulation drives procurement shifts toward fluoronitrile blends in medium-voltage platforms. Lyon-area equipment manufacturers optimize three-dimensional electrode geometries for C4F7N-CO2 mixtures.
Dielectric Gases Market Vendor Landscape
On the supply side, the industry is consolidating around integrated chemical conglomerates with captive fluorochemical production capabilities. Three strategic archetypes dominate: diversified industrial gas majors with global distribution networks, specialty fluorochemical producers with proprietary blend formulations, and regional gas distributors with certified handling infrastructure. Competitive moves center on backward integration into fluoronitrile synthesis and strategic partnerships with OEM switchgear manufacturers.
Within the diversified industrial gas tier, Linde PLC and Messer Group exemplify scale-driven operators leveraging multi-continent production footprints. Solvay occupies a position among specialty fluorochemical formulators, while 3M Company anchors the premium technology licensing segment through its Novec portfolio. Kanto Denka Kogyo Co., Ltd represents Japanese chemical producers with regional supply chain density.
| Leading Market Players |
|---|
| 3M Company |
| Linde PLC |
| Solvay |
| Concorde Specialty Gases |
| KPL International Limited |
| Matheson Tri-Gas |
| Messer Group |
| Kanto Denka Kogyo Co., Ltd |
| Showa Denko K.K. |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on European fluorochemical synthesis determines both three-tier pricing spreads across premium fluoronitrile blends, commodity nitrogen systems, and project-specific custom mixtures, and the elongated supply chain shape anchored in Germany, Belgium, and Japan with captive CO2 production integration.
Pricing Analysis
The technology-generation pricing gap separates legacy SF6 installations, current-generation C4F7N-CO2 blends, and next-generation pure fluoronitrile formulations. Three-tier pricing structure across premium certified blends, standard industrial grades, and economy nitrogen systems dominates procurement, with IEC 60376 certification tier and geographic delivery cost as primary differentiation drivers. Pricing pressure stems from OEM captive gas services disintermediating traditional distributors. Utilities represent the most price-sensitive buyer segment, while Japanese offshore wind developers exhibit lowest sensitivity due to decarbonization commitment premiums.
Supply Chain Analysis
Extended payment terms from German and Japanese chemical producers to OEM switchgear manufacturers stabilize working capital across the value chain. Geographic supply concentrates in Germany, Belgium, and Japan, with raw material dependencies on fluorspar, carbon dioxide feedstock, and specialized fluorination catalysts. Single-source vulnerability characterizes C4F7N synthesis capabilities. Distribution runs through integrated gas management contracts bundling supply, recovery, and reclamation services directly to transmission operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards operators commanding certified fluorochemical handling infrastructure, a capability gap widening as regulatory timelines compress and field service technician training lags deployment schedules.
For Market Incumbents: Entrench fluoronitrile synthesis capacity through backward integration into captive fluorspar processing or strategic tolling agreements with Belgian chemical producers. Accelerate IEC 60480-certified reclamation infrastructure in Texas and California to defend against OEM disintermediation of gas distribution channels. For New Entrants and Emerging Players: Establish a beachhead in India's greenfield ultra-high-voltage corridor procurement, where SF6-free specifications are gaining traction but domestic fluorochemical production remains underdeveloped. Target cost-sensitive nitrogen-based transformer insulation for Maharashtra distribution utilities, leveraging local industrial gas distribution partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a substitution-acceleration phase that favors specialty fluorochemical formulators with validated C4F7N blends over commodity industrial gas majors. Long-term viability hinges on regulatory enforcement durability across the EU F-Gas Regulation and EPA greenhouse gas reporting mandates. Watch Japanese METI efficiency standard tightening as the inflection indicator for Asia-Pacific demand translation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Processing | Captive raw material supply secures C4F7N production margins against commodity volatility. |
| IEC 60480-Certified Reclamation Facility Buildout | Certified gas recovery infrastructure captures utility service contract consolidation in Germany. |
| Long-term Supply Agreement with OEM Switchgear Manufacturers | Embedded gas specifications in ABB and Siemens equipment platforms lock in formulation demand. |
| Joint Venture with Indian Industrial Gas Distributor | Local handling certification bridges CEA tender requirements for greenfield transmission corridors. |
| Green Manufacturing Transition to Low-GWP Production | Carbon border adjustment alignment favors EU importers with verified emission profiles. |
Methodological Framework
A spread of perspectives from fluorochemical plant managers, utility procurement directors at German transmission operators, OEM switchgear platform engineers, and IEC standards committee participants converged on the working assumptions. Primary interview intelligence combined with secondary validation from EU F-Gas Regulation implementation reports, EPA greenhouse gas inventory filings, METI efficiency standard documentation, and customs trade data for fluorinated gas imports. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass gas type tier, application voltage class, end-user regulatory accountability level, and regional decarbonization policy intensity. CAGRs derived from equipment replacement cycle analysis and tender specification evolution. Industry-specific forecast inputs incorporated EU F-Gas Regulation phase-down trajectories and Japanese offshore wind deployment pipelines.
Sensitivities concentrate around regulatory enforcement velocity, fluorochemical production capacity expansion timing, and OEM captive service model adoption rates. Forecasts reflect assumptions on substitution economics and standards harmonization. Macroeconomic contraction, regulatory rollback, or breakthrough solid-state insulation technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Middle East Industrial Gas Market
Industrial Gases
US Industrial Gas Regulator Market
Industrial Gases
Welding Gas Market
Industrial Gases
Gas Sampling Line Market
Industrial Gases
Commercial Hydrogen Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
Middle-East and Africa Syngas Market
Industrial Gases
Carbon Monoxide Market
Industrial Gases
Helium Market
Industrial Gases
High Purity Argon Market
Industrial Gases
Europe Industrial Gases Market
Industrial Gases
Neon Gas for Laser Market
Industrial Gases
Global Rare Gases Market
Industrial Gases
Welding Shielding Gas Market
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
Global Industrial Denox Systems and Services Market