
 Global Sulfur Dioxide Market | 2026-2036
Global Sulfur Dioxide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sulfur Dioxide Market Foresight
Multi-source procurement among sulfur dioxide buyers is hardening as supply security concerns mount. INEOS leverages its integrated petrochemical network to sustain captive sulfur dioxide output across European sites. BASF SE anchors large-scale chemical manufacturing demand through backward integration into sulfur-based intermediates. Grillo-Werke AG specializes in high-purity sulfur dioxide for specialty chemical applications, differentiating against commodity-grade competitors.
Sulfur dioxide is a colorless, pungent gas with the chemical formula SO₂, typically produced through combustion of elemental sulfur or recovery from metal smelting and fossil fuel processing; its primary industrial purpose centers on chemical synthesis, particularly sulfuric acid production, plus bleaching, preservation, and wastewater treatment functions. Liquid sulfur dioxide dominates product-type value pools due to ease of transport and handling density, while gaseous sulfur dioxide competes in on-site chemical manufacturing where pipeline delivery eliminates packaging costs. Chemical manufacturing commands the largest application share, though water treatment segments are gaining traction as municipal infrastructure upgrades expand across developing economies.
EPA standards under the Clean Air Act limit SO₂ stack emissions, compelling smelters and power generators to install flue-gas desulfurization systems that simultaneously constrain and redirect sulfur dioxide supply. REACH registration requirements in Europe govern chemical substance classification, affecting import protocols and product purity thresholds for sulfur dioxide traders. China's MEE enforces dual carbon goals that tighten smelter emissions permits, altering regional production economics. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate supply cost shifts and compliance-driven capacity relocations.
Market Dynamics
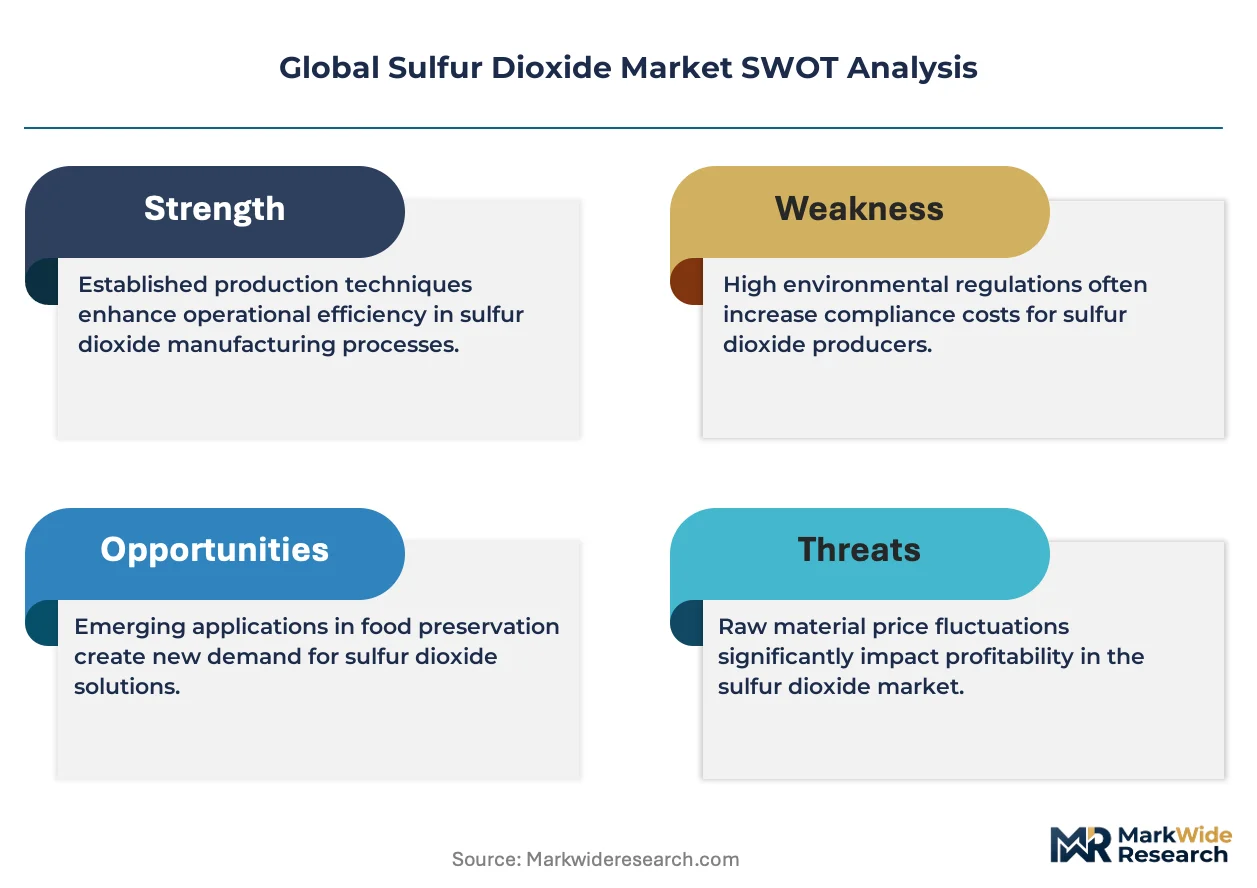
Captive sulfur dioxide generation at integrated petrochemical and smelter complexes is consolidating supply control, reducing merchant market liquidity and reshaping procurement strategies for specialty chemical buyers.
Growth Catalysts
- EU Green Deal emissions frameworks:Industrial operators across Germany and Poland are retrofitting flue-gas desulfurization systems, recovering sulfur dioxide as a saleable byproduct rather than treating it as waste.
- China's refinery capacity expansion:State-owned enterprises are commissioning new catalytic cracking units that generate sulfur dioxide feedstock for captive sulfuric acid production.
- Water treatment infrastructure upgrades:Municipal utilities in Brazil and Indonesia are adopting sulfite-based dechlorination processes, expanding industrial sulfur dioxide offtake.
Market Restraints
- Elemental sulfur price volatility:Sulfur dioxide producers dependent on brimstone combustion face margin compression when sulfur prices spike at Gulf Coast terminals.
- Merchant supply concentration:A handful of integrated petrochemical complexes in the US Gulf Coast and Rotterdam harbor control bulk liquid sulfur dioxide distribution.
- Carbon capture substitution:Amine-based scrubbing systems for carbon dioxide removal are displacing sulfur dioxide-based chemical absorption in select refinery applications.
Strategic Opportunities
- India's specialty chemical manufacturing:Contract research and manufacturing organizations near Hyderabad and Ahmedabad are sourcing high-purity sulfur dioxide for pharmaceutical intermediate synthesis.
- Biogas upgrading mandates:Germany's F-Gas Regulation is accelerating demand for sulfur dioxide in hydrogen sulfide removal from anaerobic digestion output.
- Pipeline distribution networks:Industrial gas operators are constructing dedicated sulfur dioxide pipelines to serve chemical manufacturing clusters in China's Shandong province.
Industry Challenges
- Process safety certification:Toxic gas handling protocols under OSHA Process Safety Management require specialized engineering audits that extend facility commissioning timelines.
- Legacy inventory system integration:Chemical manufacturers with SAP or Oracle ERP deployments face data migration complexity when connecting to sulfur dioxide supplier telemetry systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sulfur Dioxide Market |
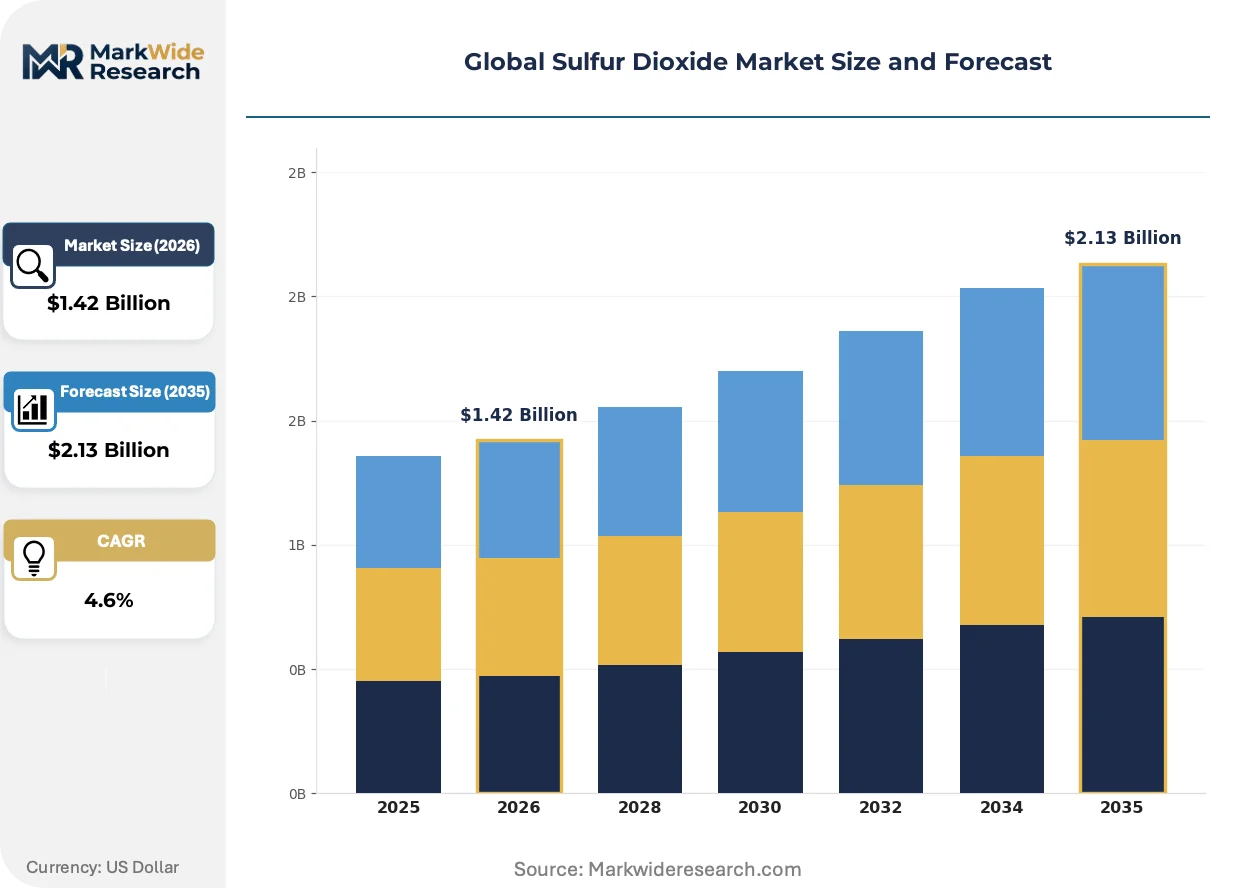
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Sulfur Dioxide, Gaseous Sulfur Dioxide, Sulfur Dioxide Tablets, Sulfur Dioxide Gas Cylinders Application: Food Preservation, Water Treatment, Chemical Manufacturing, Pulp & Paper Processing, Refrigeration, Metal Refining End User: Wine Producers, Beverage Industry, Paper Mills, Mining Companies, Agriculture Sector Packaging Type: Steel Drums, Cylinders, Bulk Tanks, Compressed Gas Containers |
| Companies Covered | Aarti Industries Ltd., Boliden Group, ESSECO Srl, INEOS, Sumitomo Seika Chemicals Co., Ltd., Grillo-Werke AG, BASF SE, Arkema S.A., PVS Chemicals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sulfur Dioxide Market Shifts & Advancements
Process intensification and emissions recovery technologies are compressing production economics while regulatory tightening in major supply jurisdictions is forcing capital redeployment toward cleaner generation pathways.
Membrane-based sulfur dioxide recovery from smelter off-gases is overtaking traditional amine scrubbing in copper and zinc processing facilities. Chilean and Peruvian mining conglomerates are piloting polymeric membrane modules that cut energy consumption by half. This technology is overtaking conventional absorption columns in new smelter builds, compressing the addressable market for chemical solvent suppliers.
REACH registration requirements for sulfur dioxide classification are tightening purity documentation and import inspection protocols at Rotterdam and Antwerp terminals. ECHA's updated substance evaluation criteria now mandate full supply chain traceability for non-EU origin material. Specialty chemical manufacturers in the Netherlands and Belgium are responding by qualifying domestic recovery sources over merchant imports.
Multi-year offtake agreements with fixed-volume escalators are displacing spot procurement for chemical manufacturing buyers. Large sulfuric acid producers in the US Gulf Coast are locking in pipeline-delivered supply from integrated refinery complexes, squeezing independent distributors from the value chain. This pattern is most visible in Texas and Louisiana, where backward-integrated buyers now control over half of regional consumption.
Global Sulfur Dioxide Market Segmentation
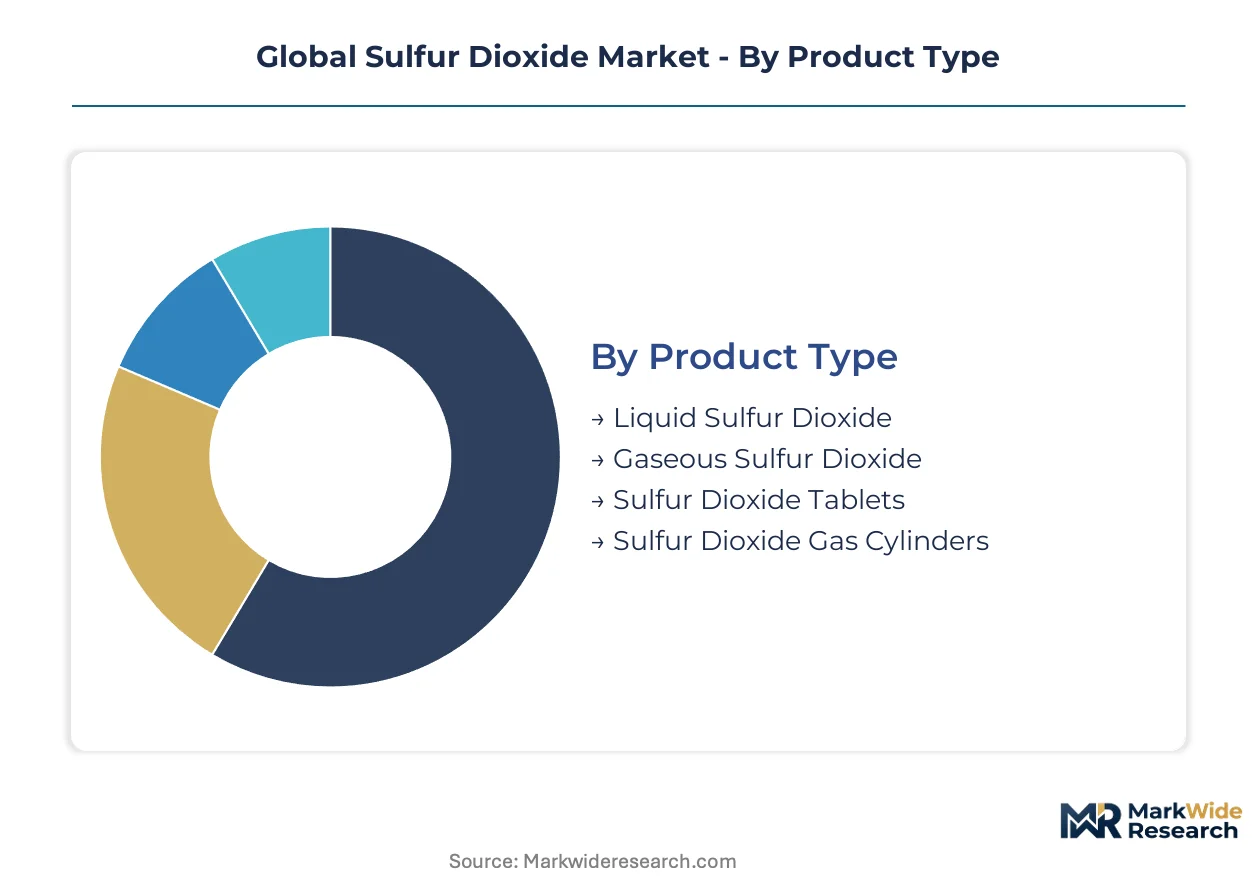
Sulfur dioxide procurement strategies diverge sharply across physical forms and purity grades. Regulatory certification burdens—EPA, REACH, and China's MEE compliance—determine viable supplier pools for each segment, creating tiered market access barriers that reshape competitive positioning.
Product Type:
REACH registration and EPA Toxic Substances Control Act filings impose distinct documentation loads across physical states, with liquid and gaseous forms facing the heaviest purity verification protocols.
- Liquid Sulfur Dioxide:Refrigerated or pressurized liquid stored at -10°C to ambient temperatures enables dense transport economics for intercontinental shipping. Chemical manufacturing clusters in Texas and Rotterdam harbor dominate offtake, driven by sulfuric acid producers seeking pipeline-fed supply security.
- Gaseous Sulfur Dioxide:Direct pipeline delivery eliminates packaging and handling costs for integrated petrochemical complexes. Captive generation at refinery and smelter sites is displacing merchant supply across China's Shandong province and the US Gulf Coast.
- Sulfur Dioxide Tablets:Solid-state formulation for controlled-release applications in food preservation and laboratory settings.
- Sulfur Dioxide Gas Cylinders:High-pressure containment for specialty chemical synthesis and analytical calibration standards.
Leading the category by volume: Liquid Sulfur Dioxide. Growing fastest: Gaseous Sulfur Dioxide.
Application:
Cost tier stratification separates commodity-scale chemical manufacturing from premium-priced specialty applications requiring pharmaceutical-grade certification.
- Chemical Manufacturing:Feedstock for sulfuric acid, sulfite salts, and sulfur-based intermediates. Integrated producers in Germany and Poland leverage flue-gas desulfurization recovery to offset raw material costs under EU Green Deal frameworks.
- Water Treatment:Sulfite-based dechlorination and oxygen scavenging for municipal utilities. Brazil and Indonesia infrastructure upgrades are expanding industrial offtake beyond traditional chemical buyers.
- Food Preservation:Antimicrobial and antioxidant functions in wine and dried fruit processing.
- Pulp & Paper Processing:Bleaching and chemical recovery in kraft mill operations.
- Refrigeration:Legacy application in industrial cooling systems, now declining amid synthetic refrigerant substitution.
- Metal Refining:Copper and zinc smelter off-gas recovery yields captive sulfur dioxide for acid production.
Highest volume concentration: Chemical Manufacturing. Steepest expansion trajectory: Water Treatment.
End User:
Customer type determines procurement modality—captive generation for mining and paper, merchant supply for fragmented agriculture and beverage segments.
- Mining Companies:Copper, zinc, and nickel smelters generate sulfur dioxide as process byproduct, feeding captive sulfuric acid plants. Chilean and Peruvian conglomerates are piloting membrane recovery technologies to upgrade off-gas utilization.
- Paper Mills:Kraft process chemical recovery loops consume sulfur dioxide for lignin extraction and pulping operations.
- Wine Producers:Sulfur dioxide addition controls fermentation and oxidation in cellar operations.
- Beverage Industry:Bottled water and soft drink manufacturers use sulfite compounds for preservation.
- Agriculture Sector:Fumigation and pesticide intermediate applications across grain storage and vineyard management.
Dominant procurement scale: Mining Companies. Fastest-growing demand profile: Agriculture Sector.
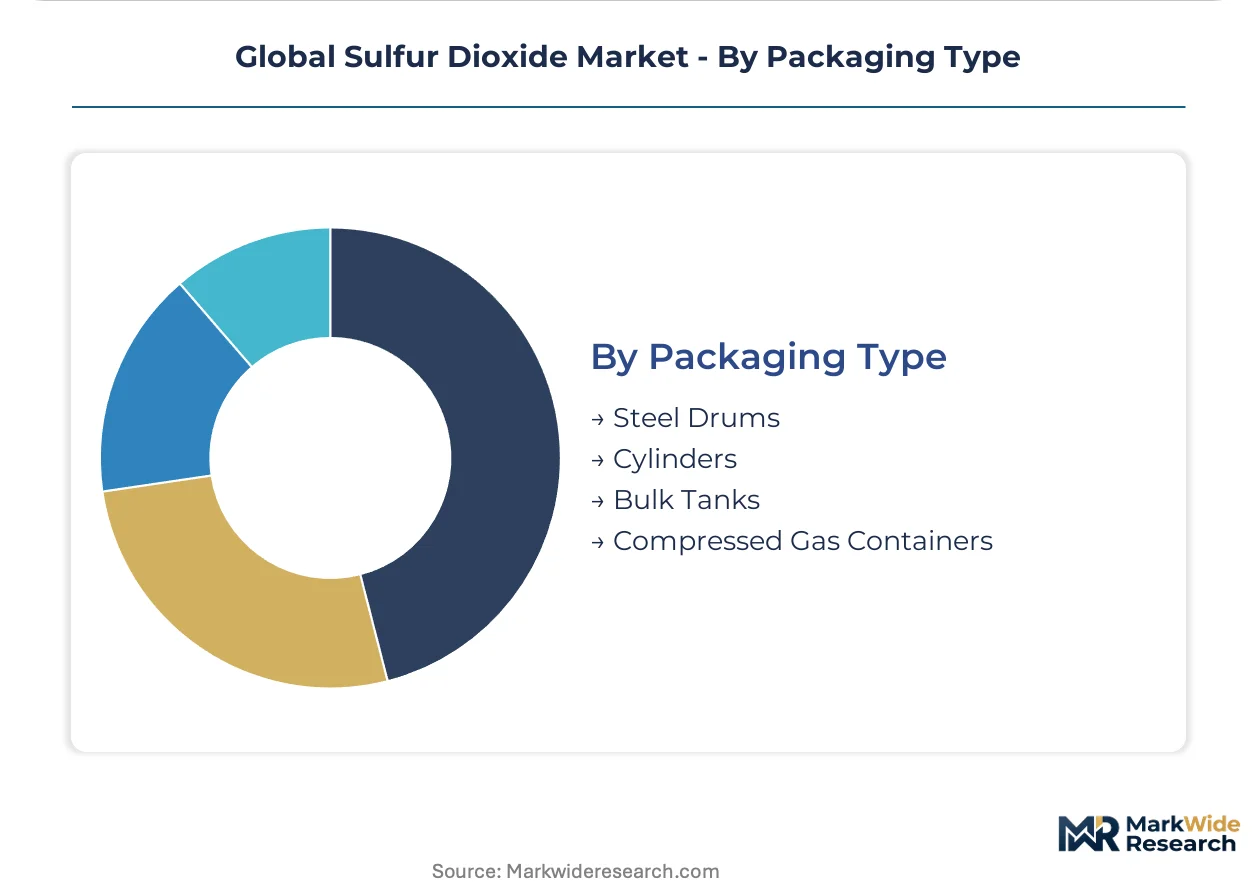
Packaging Type:
Supply chain configuration and customer scale dictate container selection, with bulk infrastructure investments concentrating in coastal chemical clusters.
- Bulk Tanks:Cryogenic and pressurized storage for high-volume chemical manufacturing sites. Pipeline interconnections at Rotterdam and Antwerp terminals enable just-in-time delivery to integrated sulfuric acid plants.
- Cylinders:Standardized high-pressure containment for specialty chemical and laboratory applications.
- Steel Drums:Intermediate liquid containment for regional distribution to smaller industrial consumers.
- Compressed Gas Containers:Portable supply for field applications and remote site operations.
Volume leadership: Bulk Tanks. Gaining share fastest: Cylinders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Elemental sulfur supply from Gulf Coast terminals and Canadian oil sands operations anchors North American production economics. Refinery and smelter complexes in Texas and Louisiana generate captive sulfur dioxide for regional chemical manufacturing. European producers leverage flue-gas desulfurization recovery under EU Green Deal frameworks to offset raw material costs.
United States
Petrochemical complexes along the Texas and Louisiana Gulf Coast generate sulfur dioxide as refinery byproduct for captive sulfuric acid production. EPA Clean Air Act standards compel smelters and power generators to install flue-gas desulfurization systems that recover saleable sulfur dioxide. Houston and Beaumont industrial clusters host pipeline distribution networks serving integrated chemical manufacturers.
Germany
Industrial operators in the Rhine-Ruhr and Saxony regions retrofit flue-gas desulfurization systems to recover sulfur dioxide as feedstock rather than waste. EU Green Deal emissions frameworks and REACH registration requirements tighten purity documentation for chemical substance classification. BASF SE at Ludwigshafen anchors large-scale demand through backward integration into sulfur-based intermediates.
China
State-owned enterprises commission catalytic cracking units at expanding refineries in Shandong and Jiangsu provinces to generate captive sulfur dioxide feedstock. MEE enforces dual carbon goals that tighten smelter emissions permits and alter regional production economics. Chemical manufacturing clusters in Shandong province attract dedicated pipeline distribution networks from industrial gas operators.
India
Contract research and manufacturing organizations near Hyderabad and Ahmedabad source high-purity sulfur dioxide for pharmaceutical intermediate synthesis. BIS certification requirements and DGFT import protocols govern chemical substance standards for specialty chemical applications. Gujarat's specialty chemical corridor concentrates demand from agrochemical and pharmaceutical manufacturers.
Chile
Copper and zinc mining conglomerates pilot membrane-based sulfur dioxide recovery from smelter off-gases to upgrade utilization efficiency. National mining regulators enforce emissions standards that accelerate technology substitution for conventional absorption columns. Antofagasta and Santiago industrial zones concentrate smelter capacity generating captive acid plant feedstock.
Global Sulfur Dioxide Market Competitive Landscape
Global majors compete with regional champions across captive generation and merchant supply modalities. The vendor base stratifies into integrated petrochemical operators, specialty chemical specialists, and mining-smelter conglomerates with acid plant integration. Three archetypes dominate: backward-integrated refiners controlling pipeline distribution, high-purity specialists serving pharmaceutical intermediates, and mining operators monetizing smelter off-gas recovery. Competitive moves center on multi-year offtake agreements with volume escalators and membrane technology licensing for emissions recovery.
Within the integrated petrochemical tier, INEOS exemplifies European network leverage across multiple production sites. BASF SE occupies a position as a chemical manufacturing anchor through upstream control over sulfur-based intermediates. Grillo-Werke AG represents the high-purity specialist archetype for specialty chemical applications, differentiating against commodity-grade competitors. These three companies illustrate the strategic segmentation between scale-driven integration and purity-driven specialization.
| Leading Market Players |
|---|
| Aarti Industries Ltd. |
| Boliden Group |
| ESSECO Srl |
| INEOS |
| Sumitomo Seika Chemicals Co., Ltd. |
| Grillo-Werke AG |
| BASF SE |
| Arkema S.A. |
| PVS Chemicals Inc. |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade certification against commodity-grade supply creates a bifurcated cost structure that simultaneously stratifies buyer procurement budgets and compresses distribution margins across liquid and gaseous sulfur dioxide channels. EPA and REACH compliance documentation adds tiered verification costs that stack onto elemental sulfur feedstock volatility, forcing specialty chemical buyers to qualify domestic recovery sources over volatile merchant imports.
Pricing Analysis
Service bundling separates pipeline-delivered supply with integrated technical support from unbundled spot market transactions requiring independent logistics coordination. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial-grade levels reflects purity certification and documentation burden rather than volume scale alone. Cost compression in technical-grade segments is intensifying because membrane-based recovery technologies cut smelter off-gas processing expenses. Fragmented agriculture and beverage buyers exhibit highest price sensitivity, while pharmaceutical contract manufacturers absorb premium pricing for supply security.
Supply Chain Analysis
China's MEE domestic-content mandates for smelter emissions recovery equipment are reshaping sourcing patterns for regional acid plant operators. Merchant supply concentrates in the United States, Germany, and China, where integrated petrochemical and refinery complexes generate captive sulfur dioxide. Production draws from elemental sulfur combustion at Gulf Coast terminals and Canadian oil sands operations, plus metal smelting off-gas recovery. Single-source vulnerability runs through Rotterdam and Houston pipeline distribution nodes serving integrated sulfuric acid manufacturers. Distribution runs through bulk tank interconnections at coastal chemical clusters, with cylinder supply gaining share in specialty applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane-based sulfur dioxide recovery is displacing conventional amine scrubbing in copper and zinc processing, compressing technology licensing windows for incumbent equipment suppliers while opening retrofit opportunities for engineering specialists.
For Market Incumbents: Lock in multi-year offtake agreements with volume escalators before carbon capture substitution accelerates in refinery applications. BASF SE and INEOS should deepen backward integration into sulfur-based intermediates to defend margin position against merchant supply concentration. Prioritize membrane technology licensing to Chilean and Peruvian mining conglomerates piloting polymeric modules. For New Entrants and Emerging Players: Specialty pharmaceutical contract manufacturers near Hyderabad and Ahmedabad represent the most penetrable buyer archetype for high-purity sulfur dioxide supply. India's BIS certification requirements create a documentation moat that favors domestic qualification over established import channels. Target biogas upgrading mandates under Germany's F-Gas Regulation as a regulatory-tethered entry point with embedded demand visibility. For Investors and Strategic Acquirers: Re-rating potential sits with high-purity specialists given REACH registration tightening and ECHA supply chain traceability mandates expanding documentation moats. Long-term viability across the analysis window favors membrane technology licensors and pipeline distribution operators in China's Shandong province over conventional absorption column suppliers. Watch for MEE dual carbon goal enforcement intensity as the inflection signal for regional production economics.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Licensing | Chilean mining pilots cut energy consumption by half versus conventional absorption columns. |
| Pipeline Distribution Expansion | Shandong province networks eliminate packaging costs for integrated chemical manufacturers. |
| Backward Integration | BASF SE at Ludwigshafen anchors demand through upstream control over sulfur intermediates. |
| Multi-year Offtake Agreements | US Gulf Coast sulfuric acid producers lock in supply security against merchant concentration. |
| REACH Registration Investment | Dutch and Belgian specialty manufacturers qualify domestic recovery sources over imports. |
Research Methodology
Multi-period observation of smelter emissions recovery adoption rates, refinery capacity commissioning timelines, and municipal water treatment infrastructure budgets anchored the trend analysis, supplemented by interviews with plant managers at integrated petrochemical complexes, procurement leads at specialty chemical manufacturers, distribution channel partners in Rotterdam and Houston, and technical R&D directors at membrane technology developers. Secondary validation drew from EPA Clean Air Act enforcement data, ECHA substance evaluation updates, China's MEE emissions permit disclosures, customs and trade flow records, and SEC 10-K filings from disclosed chemical manufacturers. Bottom-up volume modeling triangulated against top-down macroeconomic demand indicators.
Segment-weighting across product type, application, end user, and packaging format dimensions structured the analytical framework, with additional granularity for purity grade certification tiers. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory phase-in schedules and technology substitution curves. Forecast inputs incorporated elemental sulfur price volatility at Gulf Coast terminals, EU Green Deal retrofit capital deployment patterns, and India's PLI scheme incentives for specialty chemical manufacturing.
Revisions become necessary when EPA enforcement intensity shifts, REACH substance evaluation criteria expand, or membrane recovery technology achieves cost parity with amine scrubbing across copper and zinc processing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Gas Processing Market
Industrial Gases
LAMEA Industrial Nitrogen Market
Industrial Gases
Welding Shielding Gas Market
Industrial Gases
Sulfur Recovery Tail Gas Analyzer Market
Industrial Gases
Krypton Gas Market
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market
Industrial Gases
Global Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
Welding Gas Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
Europe Specialty Gas Market
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
North America Syngas Market
Industrial Gases
Gas Sampling Line Market