
 North America and Europe Metal Powder Market | 2026-2036
North America and Europe Metal Powder Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Metal Powder Market Intelligence
The end-use application mix for metal powders is pivoting from conventional powder metallurgy towards additive manufacturing, particularly for aerospace and medical device applications. GKN Powder Metallurgy leverages its automotive sector dominance to expand into 3D printing materials. Sandvik AB specializes in high-performance alloys for demanding European industrial sectors. Carpenter Technology Corporation differentiates through its development of specialized powders for critical components in the North American aerospace market.
Metal powders are finely divided metallic particles, produced via atomization, with controlled particle size and shape. They serve as raw material for fabricating solid metal parts through sintering or additive manufacturing. Stainless steel powders hold a large share from their use in automotive manufacturing. Titanium powders are expanding rapidly, driven by their application in 3D printing for aerospace and medical implants in both North America and Europe.
The European Union's REACH regulation governs the chemical safety of metal powders, requiring extensive documentation for market access. In the United States, the FAA imposes stringent material qualification standards for powders used in flight-critical aerospace components. These regulatory hurdles create high barriers to entry for new suppliers. Navigating these distinct North American and European compliance frameworks is a critical success factor for material producers.
Market Dynamics
The convergence of advanced additive manufacturing technologies with aerospace and automotive sector demands for lightweight, high-strength components is the central force shaping the metal powder market. This is accelerating the transition from powders for conventional metallurgy to highly specialized materials engineered for 3D printing processes.
Growth Catalysts
- Titanium Powder Demand:Rapid adoption in 3D printing for aerospace structural components and custom medical implants in North America and Europe drives expansion for high-purity titanium and its alloys.
- EU Industrial Strategy:European Union policies encouraging strategic autonomy and reshoring of critical supply chains create a favorable environment for domestic production of high-performance metal powders, reducing reliance on external sources.
- Automotive Lightweighting:The push for vehicle efficiency and electrification in the German automotive industry stimulates demand for aluminum and advanced steel powders used in producing lighter, complex parts via powder metallurgy and binder jetting.
Market Restraints
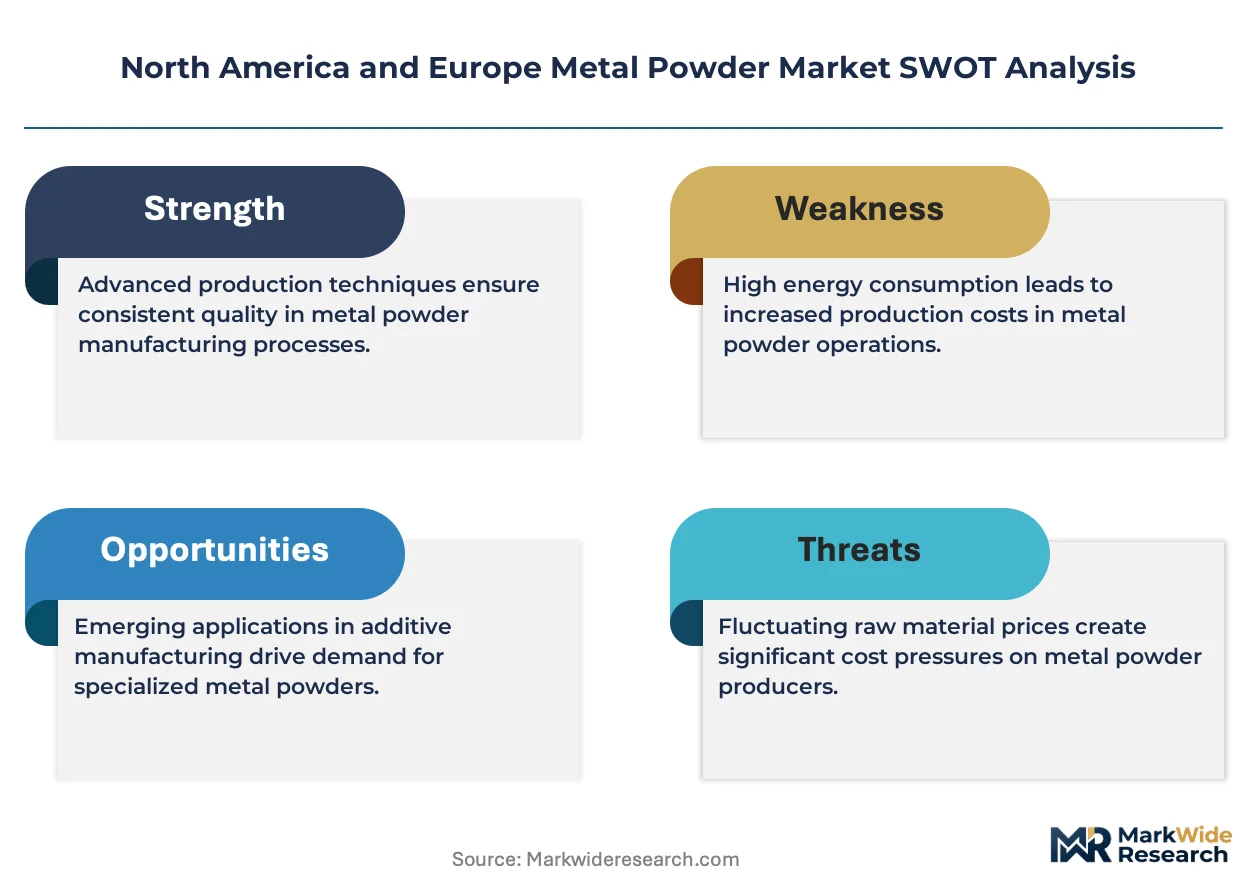
- Energy Cost Volatility:The energy-intensive nature of gas and water atomization processes makes powder production costs highly sensitive to fluctuating electricity and natural gas prices, particularly impacting producer margins in Europe.
- Dual Regulatory Burden:Navigating the distinct and complex requirements of both the EU's REACH framework for chemical safety and the FAA's stringent material qualification protocols in the US creates significant compliance costs.
- Powder Quality Consistency:Achieving perfect sphericity and a narrow particle size distribution consistently across large batches remains a technical challenge, impacting final part quality and process repeatability in additive manufacturing.
Strategic Opportunities
- New Energy Applications:Development of specialized nickel-based and corrosion-resistant powders for components in hydrogen electrolysis, fuel cells, and next-generation nuclear reactors presents a new growth frontier beyond established sectors.
- AI in Process Control:Integrating artificial intelligence and machine learning into atomization control systems allows for the creation of novel alloys and custom powder characteristics tailored to specific additive manufacturing processes and applications.
- Eastern European Expansion:Underpenetrated industrial markets in countries like Poland and the Czech Republic offer opportunities for suppliers to support the growing automotive and manufacturing sectors with localized production and technical support.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of metallurgists and process engineers with dual expertise in powder production and additive manufacturing machine qualification slows down new material development and application validation.
- Capital-Intensive Production:Building new atomization facilities, especially for reactive metals like titanium and aluminum alloys that require controlled inert environments, demands substantial capital investment, limiting new market entrants.
- Standardization Gaps:A lack of universally accepted standards for powder characterization, testing, and handling across different 3D printing platforms complicates material sourcing and qualification for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Metal Powder Market |
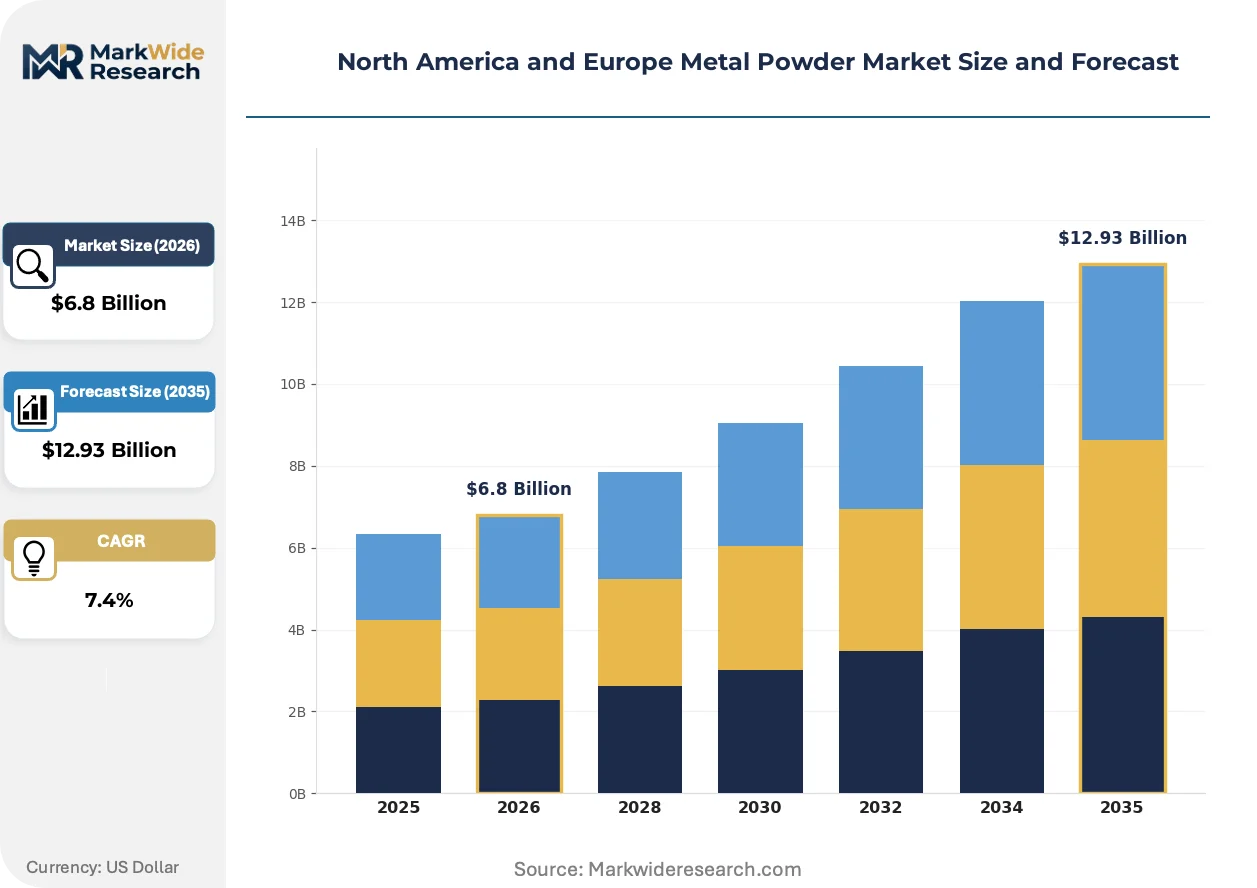
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Aluminum, Copper, Titanium Application: 3D Printing, Aerospace Components, Automotive Manufacturing, Tooling End User: Aerospace, Automotive, Medical Devices, Consumer Electronics Technology: Additive Manufacturing, Powder Metallurgy, Metal Injection Molding, Sintering |
| Companies Covered | Rio Tinto Metal Powders, ATI Inc., Sandvik AB, Kymera International, Praxair Surface Technologies, Höganäs AB, Carpenter Technology Corporation, Plansee SE, GKN Powder Metallurgy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Metal Powder Market Strategic Shifts & Innovations
The market's evolution is defined by a move away from commodity materials toward highly engineered powders. This shift is driven by the specific demands of advanced manufacturing processes, where material properties directly determine final component performance and certification pathways in regulated North American and European industries.
Modular atomization systems enable on-demand, localized powder production for research or small-batch manufacturing. Aerospace and medical device firms in the United States and Germany are installing these smaller-scale units to accelerate material development. This technology is decentralizing powder production from a few large facilities, giving end-users greater control over their material supply chain and intellectual property.
The European Union's REACH regulation mandates comprehensive chemical safety data for substances, including metal powders. This creates a significant compliance hurdle, requiring extensive testing and documentation for market access in Europe. Specialty alloy powders with complex chemistries are most affected, forcing producers to either invest in costly registrations or consolidate their product offerings.
Buyers in critical sectors are changing their purchasing behavior from a focus on price-per-kilogram to a total-cost model that includes material qualification support. This disrupts traditional distribution channels that compete on volume, favoring producers who provide integrated technical services. This trend is most visible in the North American aerospace sector, where powder certification is inseparable from the material itself.
North America and Europe Metal Powder Market Segmentation
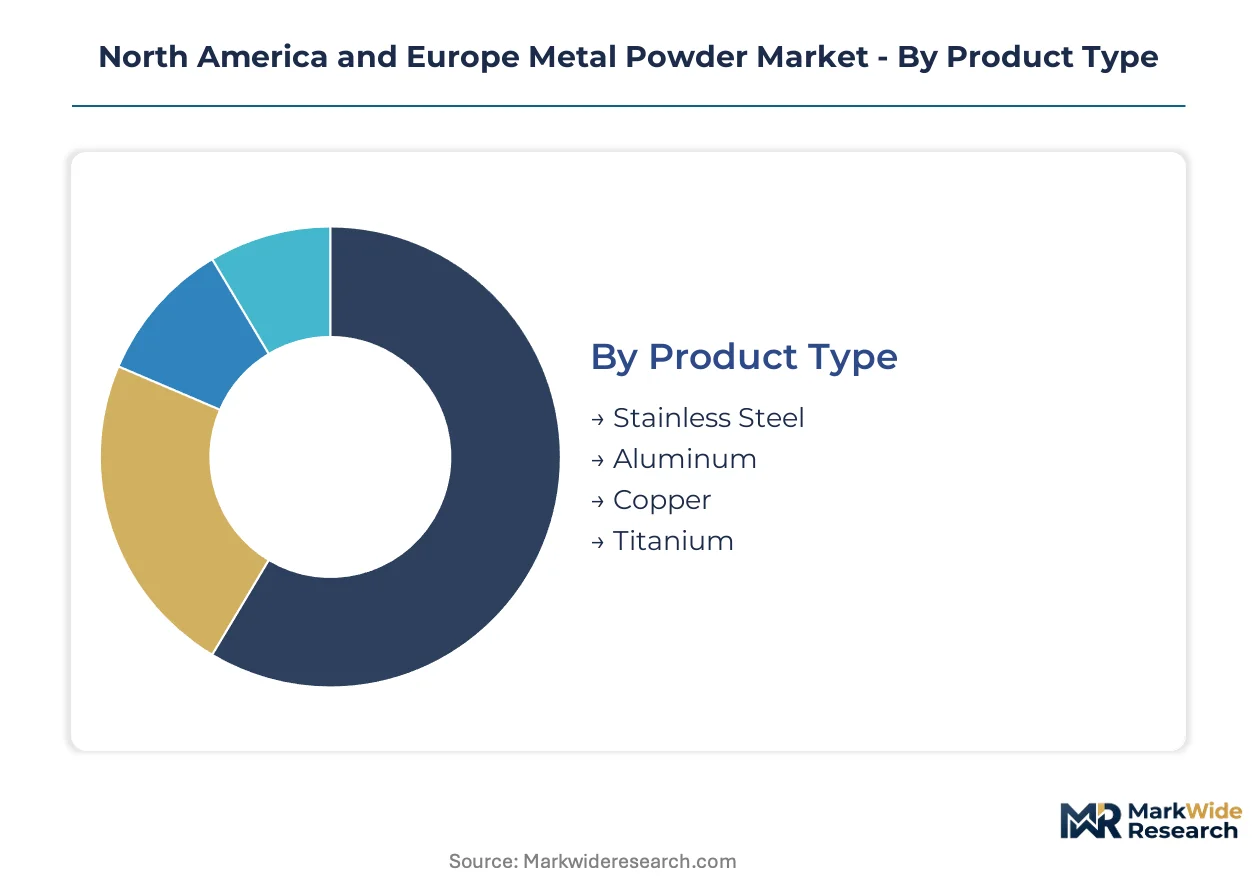
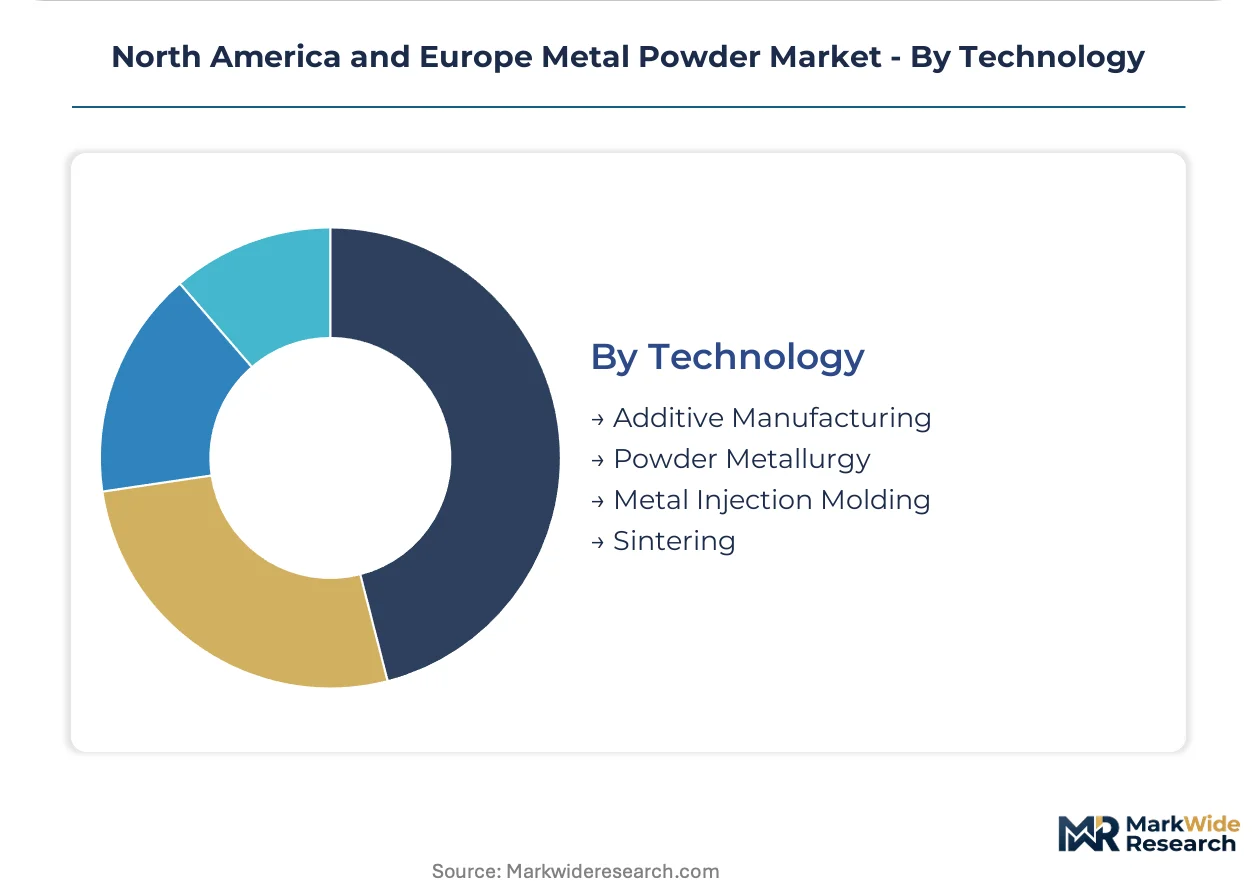
Understanding the segmentation of the North America and Europe metal powder market is crucial for identifying areas of concentrated demand and technological shifts. This analysis categorizes the market by product type, application, end user, and technology, revealing distinct drivers and market dynamics within each segment.
Product Type:
The product type segmentation differentiates between high-volume, cost-sensitive materials and lower-volume, high-performance alloys commanding a premium in North America and Europe.
- Titanium:These high-purity, lightweight, and corrosion-resistant powders are critical for advanced applications. Demand concentrates in aerospace 3D printing and medical implants across both North America and Europe, driven by their superior strength-to-weight ratio.
- Stainless Steel:Iron-based alloys with chromium, stainless steel powders offer good corrosion resistance and mechanical properties. They hold a large share in automotive manufacturing, particularly in Germany, and general industrial applications due to their cost-effectiveness and versatility.
- Aluminum:Lightweight aluminum powders find increasing use in automotive lightweighting initiatives across Europe.
- Copper:Highly conductive copper powders are essential for electrical components and thermal management applications.
Mature deployment sits with Stainless Steel. Newer deployment is concentrated in Titanium.
Application:
The application categories highlight distinct functional uses for metal powders across various manufacturing processes.
- 3D Printing:This application enables the creation of complex geometries and offers material efficiency through layer-by-layer construction. Demand is high in aerospace and medical device sectors across North America and Europe, driven by design freedom and rapid prototyping capabilities.
- Aerospace Components:Metal powders are used for flight-critical parts requiring high-performance alloys and stringent material properties. The US and German aerospace industries are key consumers, seeking lightweighting and structural integrity.
- Automotive Manufacturing:Metal powders enable the production of complex, lightweight parts for European vehicles.
- Tooling:Specialized powders create durable molds, dies, and cutting tools for industrial use.
3D Printing represents the fastest-growing trajectory in this market.
End User:
End user segmentation reveals the primary industries consuming metal powders for their specific product needs.
- Aerospace:This sector utilizes metal powders for aircraft engines, structural components, and landing gear, requiring exceptional performance and stringent certification. Major consumers include the US, Germany, and France, prioritizing lightweighting and structural integrity.
- Medical Devices:Powders are crucial for implants, surgical instruments, and prosthetics, demanding biocompatibility and customization. Germany and the US are significant markets for these specialized applications.
- Automotive:Vehicle manufacturers in Germany utilize powders for lightweight engine and structural parts.
- Consumer Electronics:Powders find use in heat sinks, connectors, and casings for electronic devices.
Aerospace and Medical Devices are driving significant innovation in powder specifications.
Technology:
Technology segmentation delineates between established powder fabrication methods and newer, advanced processes.
- Additive Manufacturing:This transformative technology involves layer-by-layer construction to produce complex geometries. It sees high demand in aerospace and medical sectors throughout North America and Europe, driven by design freedom and part consolidation.
- Powder Metallurgy:This traditional method involves the compaction and sintering of powders into solid parts. It remains cost-effective for high-volume production, with significant use in automotive and industrial machinery sectors, particularly in Germany.
- Metal Injection Molding:This process forms complex, small metal components with high precision.
- Sintering:A heat treatment process densifies compacted metal powders into solid objects.
Additive Manufacturing is rapidly gaining share from conventional powder metallurgy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's initiatives, such as the EU Industrial Strategy, actively foster strategic autonomy in critical material supply chains. This policy framework encourages domestic production of high-performance metal powders across member states. Such strategic focus helps concentrate manufacturing capabilities and research efforts within designated industrial clusters, fostering innovation and reducing external dependencies.
Germany
German industrial demand for metal powders centers on automotive lightweighting and precision engineering. The EU's REACH regulation mandates chemical safety documentation for market access. The Stuttgart region, a hub for automotive and engineering, drives innovation in advanced steel and aluminum powders for vehicle electrification.
United States
The United States sees strong demand for metal powders in aerospace structural components and medical implants. The FAA imposes stringent material qualification standards for flight-critical aerospace parts. Ohio's aerospace corridor, including Cleveland and Dayton, concentrates research and production for specialized titanium and nickel superalloys.
France
French demand for metal powders is significant in aerospace engine components and high-performance industrial alloys. National policies aligned with the EU Green Deal promote sustainable manufacturing practices for metal powder production. Toulouse, a major aerospace center, focuses on developing specialized titanium and nickel-based powders for advanced aircraft applications.
Poland
Polish industrial growth stimulates demand for metal powders, particularly in its expanding automotive sector and general manufacturing. EU cohesion funds support modernization and capacity building in manufacturing, including metal powder processing. The Silesia region, a traditional industrial heartland, sees investment in localized production of cost-effective stainless steel powders.
North America and Europe Metal Powder Market Key Industry Players
Top-tier vendors anchor the premium segment, specializing in high-performance alloys for critical applications, while mid-sized specialists focus on niche markets. The market structure exhibits a tiered consolidation, with a few large global players and numerous regional or product-specific firms. Strategic archetypes include integrated material producers, specialized additive manufacturing powder suppliers, and traditional powder metallurgy providers. Dominant competitive moves involve capacity expansion for reactive metals and strategic partnerships to co-develop application-specific materials.
Specialized additive manufacturing powder suppliers, such as Sweden-based Sandvik AB, exemplify the focus on high-performance alloys for demanding European industrial sectors. United States-based Carpenter Technology Corporation represents a key player in developing specialized powders for critical components within the North American aerospace market, emphasizing stringent material qualification. Meanwhile, Germany-headquartered GKN Powder Metallurgy occupies a strong position by leveraging its automotive sector dominance to expand into 3D printing materials and advanced powder metallurgy applications.
| Leading Market Players |
|---|
| Rio Tinto Metal Powders |
| ATI Inc. |
| Sandvik AB |
| Kymera International |
| Praxair Surface Technologies |
| Höganäs AB |
| Carpenter Technology Corporation |
| Plansee SE |
| GKN Powder Metallurgy |
| Others |
Cost & Logistics Intelligence
Energy costs, particularly from fluctuating natural gas prices, directly influence the atomization process, passing through to final metal powder pricing for specialized aerospace and medical applications.
Pricing Analysis
Premium pricing for short lead times characterizes the specialized metal powder market, particularly for high-purity titanium powders required by aerospace manufacturers. The dominant pricing model involves contract-based long-term offtake for critical components, with spot markets for more commodity-grade stainless steel. Price differentiation stems from stringent material qualification levels, such as FAA standards, and precise particle size distribution. Pricing softness reflects high energy cost volatility impacting European producers. Automotive manufacturers exhibit the most price sensitivity, while aerospace and medical device firms prioritize performance over cost.
Supply Chain Analysis
High-purity raw material supply for titanium and nickel alloys largely rests on established mining operations in Australia and Canada, with processing concentrated in the United States and Europe. Geographic supply concentration for advanced powders is strong in Germany, the US, and Sweden. Key dependencies include titanium sponge and high-grade nickel ingots. A structural risk involves single-source vulnerability for ultra-high purity feedstock. Direct sales from powder producers to aerospace and medical OEMs represent the dominant distribution model for specialized materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America and Europe metal powder market remains supply-constrained, with limited atomization capacity for reactive metals like titanium propping up premium pricing for critical applications.
For Market Incumbents:Extend material qualification efforts across new additive manufacturing platforms to counter emerging powder chemistries. Consolidate smaller regional producers to gain market share and control specialized feedstock supply. The threat of new, lower-cost atomization technologies from Asia could challenge established pricing. Investment in advanced process control for consistent powder quality remains a critical lever.
For New Entrants and Emerging Players:Enter via modular atomization systems targeting niche applications in specific industrial clusters. Focus on developing specialized corrosion-resistant powders for new energy applications like hydrogen electrolysis. The medical device sector in Germany and the US offers the most penetrable application area. A go-to-market angle emphasizing rapid customization and localized technical support will be effective.
For Investors and Strategic Acquirers:The successful commercialization of advanced binder jetting technologies is the leading indicator that the metal powder market will sustain high growth over the next decade. Investors should target specialized additive manufacturing powder suppliers with strong R&D pipelines. This market offers long-term viability driven by aerospace and medical innovation. Watch for increased M&A activity among mid-sized firms as a signal of market maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Reactive Metals | This initiative addresses the high demand for titanium and nickel powders in aerospace component manufacturing. |
| AI-driven Process Optimization | Integrating AI into atomization control systems enhances powder quality and enables novel alloy development for 3D printing. |
| Strategic Partnerships with OEMs | Collaborating with automotive and aerospace OEMs ensures co-development of application-specific materials and secures future demand. |
| Localized European Production | Establishing facilities in Eastern Europe supports growing automotive sectors and reduces reliance on external supply chains. |
| Material Qualification Investment | Investing in FAA and REACH compliance strengthens market access and differentiates products for critical North American and European applications. |
Research Approach
Independent corroboration across industry association reports, regulatory body publications, and company financial disclosures underwrites the qualitative findings and quantitative projections. Primary interviews engaged metallurgists, additive manufacturing engineers, procurement leads at aerospace OEMs, and medical device developers. This approach combined top-down market sizing with bottom-up validation from key stakeholders, ensuring robust data triangulation.
The forecast framework anchored the projection horizon to historical performance benchmarks and recent market shifts, establishing a consistent analytical baseline. Segmentation dimensions modeled include product type, application, end-user, technology, and regional industrial output. Compound annual growth rates were derived from a multi-factor regression analysis, incorporating economic indicators and technology adoption curves. Key inputs included aerospace production forecasts and automotive lightweighting targets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant energy price fluctuations or unforeseen regulatory changes. These forecasts reflect assumptions regarding technological advancements and market adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Grain Oriented Electrical Steel Market
Metals
Beryllium Copper for Industrial Equipment Market
Metals
Global Oxygen-Free Copper Market
Metals
Copper and Copper Alloy Scrap and Recycling Market
Metals
Finished Steel Products Market
Metals
Global Brass Rods Market
Metals
Titanium Powder Market
Metals
Titanium Mill Products Market
Metals
US and Mexico Stainless Steel Market
Metals
Ferrosilicon Market
Metals
High Purity Aluminium Market
Metals
Hafnium Foil Market
Metals
Aluminium Forging Market
Metals
Galvanized Steel Coil Market
Metals
Silver Enamel Market
Metals
Zinc Plating Market