
 High Performance Liquid Chromatography (HPLC) Market | 2026-2036
High Performance Liquid Chromatography (HPLC) Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Liquid Chromatography (HPLC) Market Intelligence
The EU Green Deal's chemical sustainability benchmarks are repositioning instrument procurement criteria toward energy-efficient systems and reduced solvent consumption. Waters Corporation leverages its mass spectrometry integration expertise to anchor high-end pharmaceutical workflows. Agilent Technologies, Inc. competes across the full stack with modular platforms that sustain replacement revenue streams. Thermo Fisher Scientific Inc. dominates service contracts through its global field engineer network.
High performance liquid chromatography separates, identifies, and quantifies components in liquid mixtures by pumping pressurized solvent through a packed column at flow rates typically between 0.1 and 10 mL per minute, with ultraviolet or mass spectrometric detection resolving compounds at nanogram sensitivity. Its primary purpose spans pharmaceutical impurity profiling, environmental contaminant detection, and food safety verification. Reverse phase technology leads volume due to its versatility with aqueous samples and small-molecule pharmaceuticals. Pharmaceutical analysis commands the largest application share, though biotechnology demand for monoclonal antibody characterization is expanding fastest. Contract research organizations represent a concentrated end-user segment where instrument uptime and regulatory compliance drive purchasing decisions.
The FDA enforces current Good Manufacturing Practice guidelines that mandate validated HPLC methods for batch release testing, while the EMA's ICH Q2(R1) revision tightens analytical performance criteria for European market authorization. EPA Method 525 and related drinking water protocols in the United States compel environmental laboratories to maintain dual-detector configurations for pesticide monitoring. Stakeholders must weigh total cost of ownership against evolving regulatory detection limits when planning capital deployment cycles.
Market Dynamics
The FDA's tightened bioanalytical method validation guidance and the EU Green Deal's chemical sustainability benchmarks are simultaneously elevating detection thresholds and redefining procurement criteria, forcing manufacturers to reconcile precision demands with solvent reduction mandates.
Growth Catalysts
- Biologics characterization surge:Monoclonal antibody pipelines at Boston-Cambridge and Rhine-Main clusters are expanding quality control budgets for impurity profiling.
- EPA Method 525 mandates:United States environmental laboratories must maintain dual-detector configurations for pesticide monitoring in drinking water protocols.
- Mass spectrometry integration:Ultraviolet detection systems are yielding to hyphenated LC-MS platforms that resolve compounds at nanogram sensitivity.
Market Restraints
- Helium supply volatility:Mass spectrometry carrier gas costs fluctuate with Qatar and Algeria export disruptions, compressing operating margins.
- Column manufacturing concentration:Specialized silica packing production clusters in Germany and Japan create single-source vulnerabilities.
- ICH Q2(R1) compliance friction:EMA's revised analytical performance criteria extend European market authorization timelines for method transfers.
Strategic Opportunities
- India CDMO expansion:Contract development and manufacturing organizations near Hyderabad and Ahmedabad seek validated HPLC methods for export compliance.
- Cell and gene therapy analytics:Viral vector titer determination and empty-full capsid ratio analysis demand specialized column chemistries.
- Digital twin integration:Predictive maintenance algorithms linked to instrument telemetry reduce unplanned downtime in 24/7 contract research operations.
Industry Challenges
- Field service engineer scarcity:Mass spectrometry troubleshooting expertise concentrates at OEM headquarters, extending mean time to repair in secondary markets.
- Legacy data migration:21 CFR Part 11 compliance requires revalidation of historical chromatograms when transitioning between software platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Liquid Chromatography (HPLC) Market |
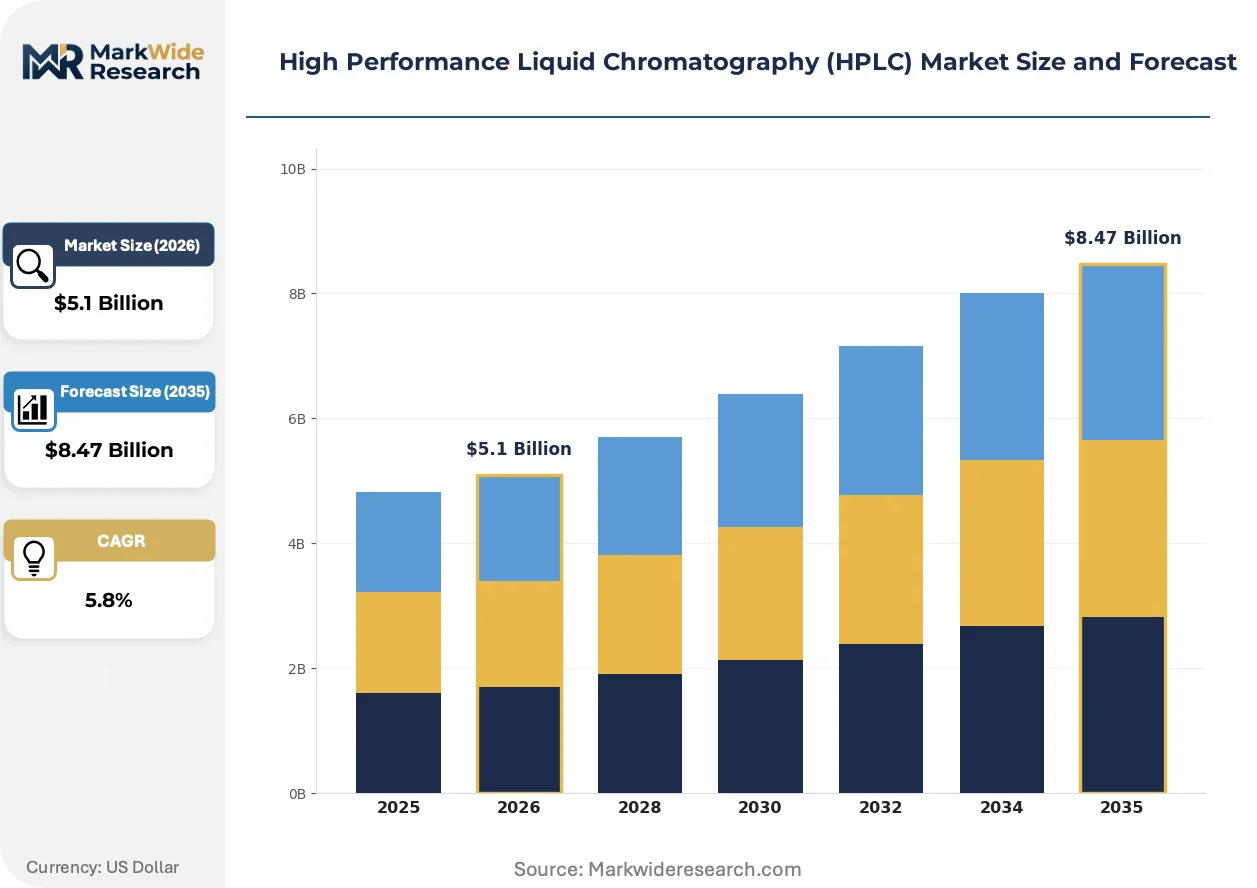
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $8.47 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Systems, Columns, Detectors, Pumps, Autosamplers Technology: Ion Exchange, Size Exclusion, Reverse Phase, Normal Phase, Affinity, Chiral Application: Pharmaceutical Analysis, Food Testing, Environmental Monitoring, Chemical Research, Biotechnology, Cosmetics Quality Control End User: Contract Research Organizations, Academic Institutions, Regulatory Laboratories, Food & Beverage Firms, Chemical Manufacturers |
| Companies Covered | Shimadzu Corporation, Merck KGaA, Waters Corporation, Hitachi High-Tech Corporation, Phenomenex, Inc., Agilent Technologies, Inc., PerkinElmer, Inc., JASCO Corporation, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Liquid Chromatography (HPLC) Market Strategic Shifts & Innovations
Instrument architectures are converging around modularity and predictive connectivity, while detection sensitivity thresholds compress and procurement models favor operational expenditure over capital deployment.
Ultra-high performance liquid chromatography is consolidating pharmaceutical impurity profiling workflows. Large-molecule developers at United States and German biotech clusters are retiring conventional HPLC systems for sub-2-micron particle columns that slash run times by half. This consolidation is compressing the installed base of mid-tier instruments while elevating service contract values.
REACH authorization requirements for acetonitrile are forcing solvent recovery system adoption. European environmental and pharmaceutical laboratories must document closed-loop handling to maintain operating permits. Germany's chemical sector is responding with on-site distillation units that reduce virgin solvent purchases.
After-sales service unbundling is fragmenting traditional OEM revenue streams. Third-party validation specialists in Massachusetts and Bavaria now compete for compliance documentation contracts previously captured by instrument manufacturers. This disintermediation is most visible among contract research organizations with multi-vendor fleets seeking vendor-agnostic uptime guarantees.
High Performance Liquid Chromatography (HPLC) Market Segmentation
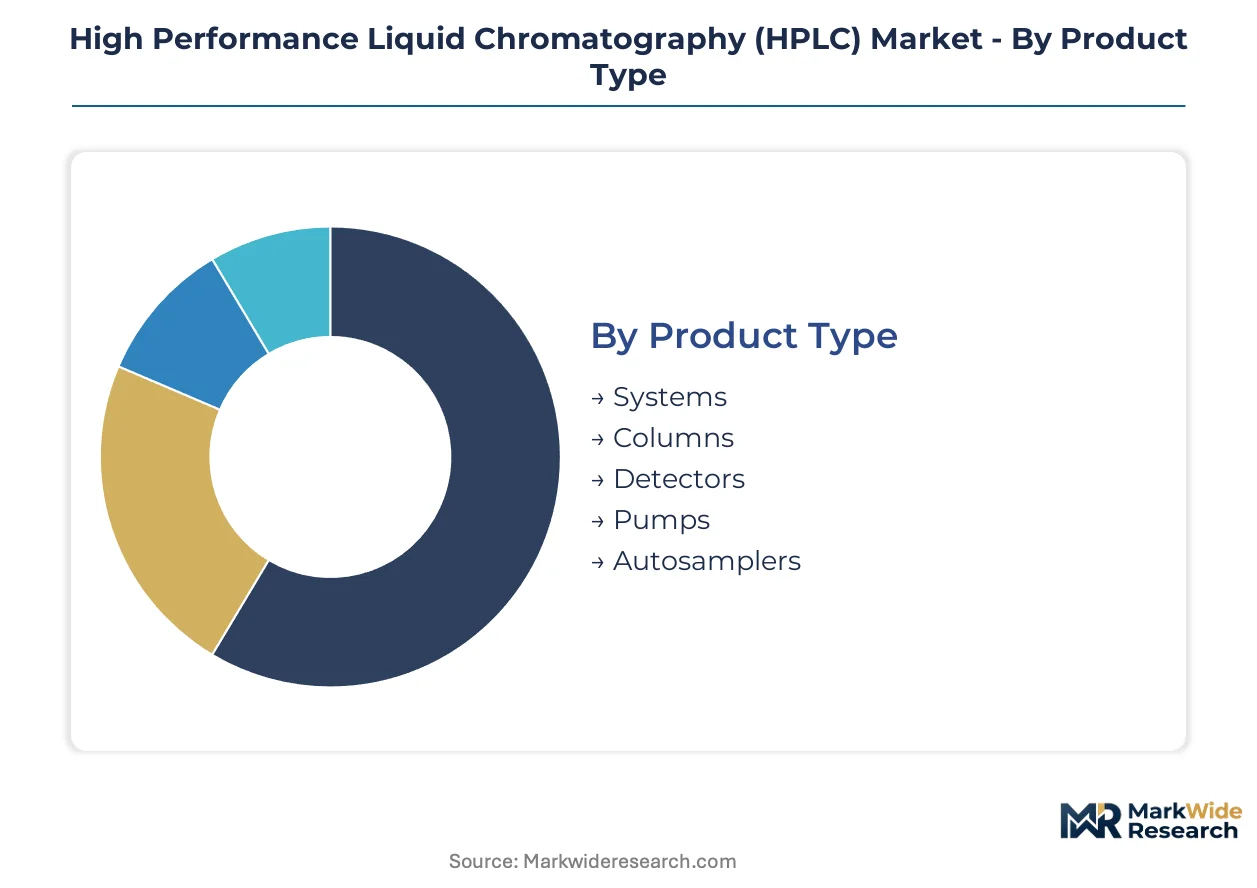
HPLC procurement decisions fragment across four intersecting dimensions, with regulatory validation requirements and total cost of ownership driving divergence between premium pharmaceutical workflows and routine quality control operations. Understanding segment-specific certification burdens and replacement cycles anchors capital planning for instrument fleets.
Product Type:
Systems carry the heaviest FDA 21 CFR Part 11 and EU GMP Annex 11 validation burdens, while consumables face REACH chemical authorization pressures that reshape sourcing economics.
- Systems:Integrated platforms combining solvent delivery, column housing, and detection modules require installation qualification and operational qualification documentation for pharmaceutical release testing. Boston-Cambridge biotech clusters and Rhine-Main pharmaceutical corridors prioritize these for monoclonal antibody impurity profiling under tightened FDA bioanalytical guidance.
- Columns:Silica-based and polymeric stationary phases determine separation efficiency, with sub-2-micron particle formats commanding premium positioning for UHPLC workflows. German and Japanese manufacturing concentration creates supply vulnerabilities for specialized chiral and affinity chemistries.
- Detectors:Photodiode array and mass spectrometry interfaces resolve compounds at nanogram sensitivity.
- Pumps:Binary and quaternary solvent delivery systems maintain precision at flow rates between 0.1 and 10 mL per minute.
- Autosamplers:Temperature-controlled sample handling modules reduce degradation for biologics analysis.
Systems sit at the top of the volume ranking, with columns climbing the fastest as UHPLC adoption accelerates replacement cycles.
Technology:
Method transfer complexity and solvent consumption profiles separate high-throughput pharmaceutical platforms from niche analytical techniques.
- Reverse Phase:C18 and C8 bonded silica dominates aqueous sample compatibility, anchoring small-molecule pharmaceutical workflows. The technology's versatility across pH ranges and buffer systems sustains its installed base dominance in United States and European quality control laboratories.
- Size Exclusion:Porous stationary phases separate macromolecules by hydrodynamic volume, enabling monoclonal antibody aggregate detection and viral vector titer determination. Cell and gene therapy developers at Massachusetts and Bavaria clusters are expanding capacity for empty-full capsid ratio analysis.
- Ion Exchange:Charged surface chemistries resolve proteins and nucleic acids based on electrostatic interactions.
- Normal Phase:Polar stationary phases with nonpolar mobile phases address lipid and carbohydrate separations.
- Affinity:Biospecific ligand coatings enable selective capture of antibodies and recombinant proteins.
- Chiral:Enantioselective stationary phases separate optical isomers for pharmaceutical stereochemistry verification.
Reverse Phase holds the largest installed base, while size exclusion gains share fastest from biologics pipeline expansion.
Application:
Detection threshold mandates from EPA, FDA, and EMA segment workflows by validation rigor and instrumentation tier.
- Pharmaceutical Analysis:Impurity profiling and batch release testing under ICH Q3A and Q3B guidelines demand validated methods with documented linearity, accuracy, and precision. Contract research organizations in New Jersey and Switzerland maintain dual-detector configurations to satisfy both FDA and EMA submission requirements.
- Biotechnology:Monoclonal antibody characterization and gene therapy analytics require specialized column chemistries and mass spectrometry hyphenation. The segment's method development complexity drives premium service contract attachment rates.
- Environmental Monitoring:EPA Method 525 and related drinking water protocols compel pesticide residue detection.
- Food Testing:Mycotoxin and additive verification aligns with FSSAI and FDA food safety regulations.
- Chemical Research:Synthetic route monitoring and catalyst screening support process development.
- Cosmetics Quality Control:Preservative and allergen detection follows EU Cosmetics Regulation testing schedules.
Pharmaceutical analysis leads by revenue concentration, with biotechnology expanding most quickly from cell therapy commercialization.
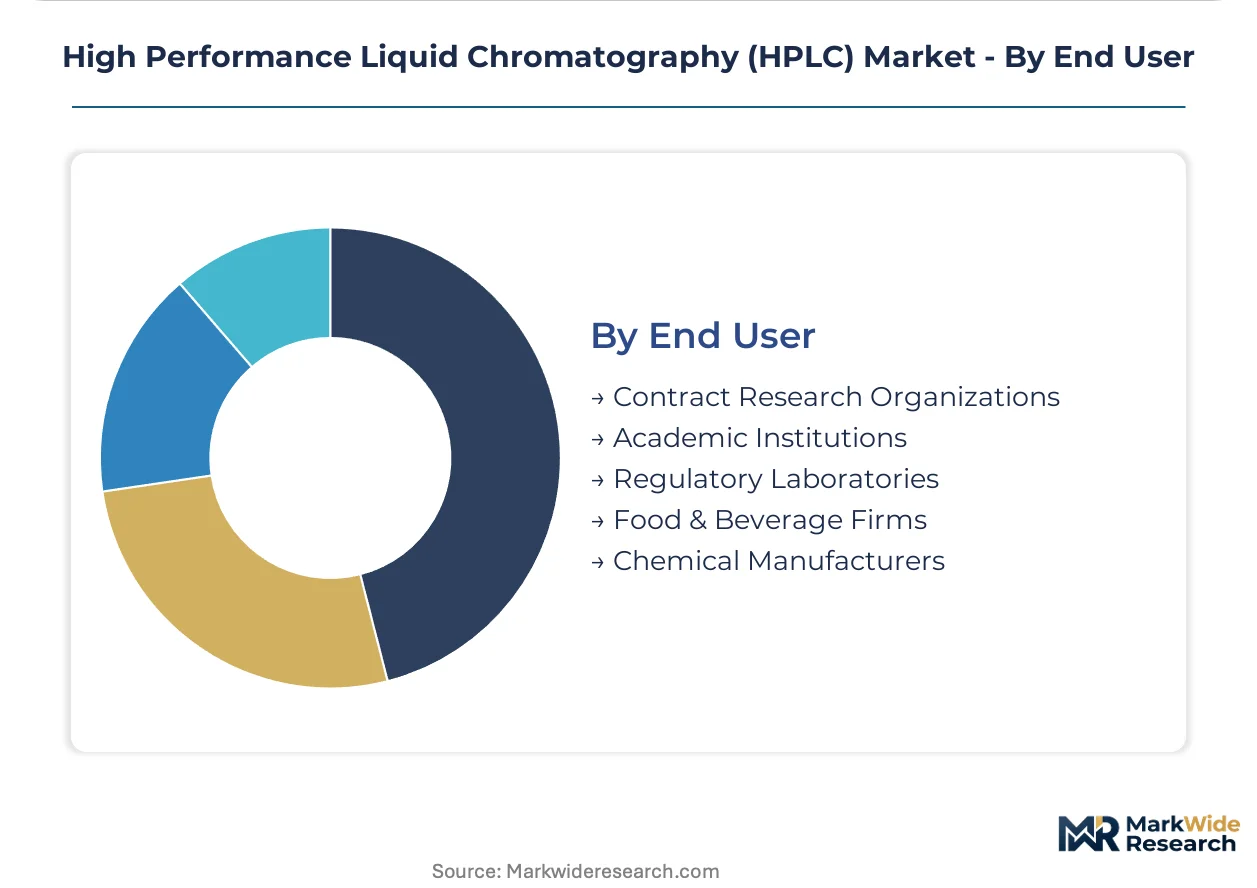
End User:
Capital deployment models and compliance documentation needs separate outsourced service providers from captive analytical operations.
- Contract Research Organizations:Multi-vendor instrument fleets and 24/7 uptime requirements drive vendor-agnostic service contracts and predictive maintenance adoption. Massachusetts and Bavaria validation specialists now compete for compliance documentation previously captured by OEMs.
- Regulatory Laboratories:Government reference labs enforce standardized methods with extended instrument lifecycles.
- Academic Institutions:Grant-funded research programs prioritize modular platforms with flexible detection options.
- Food & Beverage Firms:In-house quality control balances throughput against capital constraints.
- Chemical Manufacturers:Process analytical technology integration supports real-time release testing.
Contract research organizations dominate premium system procurement, with regulatory laboratories showing steepest replacement backlog from deferred capital cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chromatography specialists concentrate in Germany's chemical engineering corridor and Massachusetts' biotech belt, anchoring method development expertise for pharmaceutical and environmental applications.
United States
EPA Method 525 mandates compel environmental laboratories toward dual-detector configurations for drinking water pesticide monitoring. The FDA's tightened bioanalytical guidance elevates validation documentation burdens for contract research organizations. Boston-Cambridge biotech clusters drive monoclonal antibody impurity profiling demand with expanded quality control budgets.
Germany
REACH authorization requirements for acetonitrile force solvent recovery system adoption across pharmaceutical and environmental laboratories. The EU Green Deal's chemical sustainability benchmarks reposition procurement criteria toward energy-efficient systems. Rhine-Main pharmaceutical corridors prioritize validated HPLC methods for batch release testing under EMA ICH Q2(R1) revisions.
Japan
Specialized silica packing production clusters create supply vulnerabilities for chiral and affinity column chemistries. METI standards guide analytical instrument export compliance for Asian contract manufacturing markets. Tokyo-Yokohama metropolitan areas anchor precision pump manufacturing for UHPLC workflows.
India
Contract development and manufacturing organizations near Hyderabad and Ahmedabad seek validated HPLC methods for FDA and EMA export compliance. CDSCO alignment with ICH quality guidelines accelerates method transfer standardization. Gujarat's pharmaceutical manufacturing belt expands quality control capacity for generic drug exports.
Switzerland
Swissmedic's analytical performance criteria tighten method validation requirements for European market authorization. Precision instrument engineering concentrates around Basel's pharmaceutical research corridor. Geneva-based contract research organizations maintain multi-vendor fleets for regulatory submission flexibility.
High Performance Liquid Chromatography (HPLC) Market Key Industry Players
Capital-heavy producers compete with asset-light designers across instrument architectures and consumables chemistries. The vendor base stratifies between integrated platform specialists and modular component suppliers. Three archetypes dominate: mass spectrometry-anchored workflow integrators, full-stack modular platform providers, and column chemistry specialists. Consolidation pressure concentrates in service contract unbundling and third-party validation competition.
Among precision instrument manufacturers, Waters Corporation, Agilent Technologies, Inc., and Thermo Fisher Scientific Inc. occupy distinct positioning vectors. Waters exemplifies mass spectrometry integration expertise for high-end pharmaceutical workflows. Agilent represents full-stack modular competition sustaining replacement revenue streams. Thermo Fisher anchors service contract dominance through global field engineer networks.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Merck KGaA |
| Waters Corporation |
| Hitachi High-Tech Corporation |
| Phenomenex, Inc. |
| Agilent Technologies, Inc. |
| PerkinElmer, Inc. |
| JASCO Corporation |
| Thermo Fisher Scientific Inc. |
| Others |
Cost & Logistics Intelligence
Contract research organizations with multi-vendor instrument fleets command substantial negotiating leverage, compressing service contract margins and accelerating the shift toward operational expenditure models for HPLC procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated LC-MS platforms from modular UHPLC systems and entry-level quality control units. Price differentiation hinges on FDA 21 CFR Part 11 validation documentation and mass spectrometry hyphenation capability. Cost compression in the standard tier is intensifying because third-party validation specialists in Massachusetts and Bavaria now undercut OEM service rates. Academic institutions exhibit the highest price sensitivity, while Boston-Cambridge biotech clusters prioritize detection sensitivity over capital outlay.
Supply Chain Analysis
Direct-to-OEM channels handle pharmaceutical manufacturer demand, while distributor networks serve environmental laboratories and academic buyers. Specialized silica packing production draws from Germany and Japan, creating single-source vulnerabilities for chiral and affinity column chemistries. High-purity acetonitrile and helium carrier gas represent critical input dependencies. Tariff exposure on precision pump assemblies from Tokyo-Yokohama manufacturing clusters threatens margin stability for mid-tier instrument suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HPLC market functions as a regulatory compounder where FDA bioanalytical method validation guidance revisions and EMA ICH Q2(R1) updates continuously expand compliance documentation requirements.
For Market Incumbents: To counter third-party validation specialist encroachment on service contract revenue, anchor customer relationships through predictive maintenance algorithm integration and captive supply of specialized column chemistries for cell and gene therapy applications. Deepen backward integration into sub-2-micron particle manufacturing to secure UHPLC workflow margins. For New Entrants and Emerging Players: Capture the India CDMO expansion wave near Hyderabad and Ahmedabad by offering validated method transfer packages that accelerate FDA and EMA export compliance timelines. Target solvent recovery system bundling to differentiate against established OEMs in European environmental laboratory procurement. For Investors and Strategic Acquirers: Precision instrument manufacturers with mass spectrometry integration expertise are the most active acquirer in this space, seeking column chemistry specialists to complete workflow portfolios. The long-term viability window favors asset-light designers with modular platforms over capital-heavy integrated system producers. Monitor helium supply contract renegotiation patterns as an inflection indicator for mass spectrometry carrier gas cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Mass Spectrometry Hyphenation | LC-MS integration commands premium positioning in Boston-Cambridge biotech impurity profiling workflows. |
| Solvent Recovery System Adoption | REACH acetonitrile authorization mandates force closed-loop handling investments across German laboratories. |
| Digital Twin Integration | Predictive maintenance algorithms reduce unplanned downtime for 24/7 contract research operations. |
| Specialized Column Chemistry Development | Empty-full capsid ratio analysis for viral vectors requires proprietary stationary phase formulations. |
| Third-Party Validation Specialization | Vendor-agnostic compliance documentation competes for OEM service contract revenue in multi-vendor fleets. |
Research Approach
Multiple input streams — regulatory affairs directors at pharmaceutical manufacturers, field service engineers at precision instrument OEMs, procurement leads at contract research organizations, and environmental laboratory managers — were reconciled against FDA guidance documents, EMA ICH submissions, EPA Method 525 protocols, and instrument manufacturer SEC filings. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates across the analysis window.
Historical shipment data cross-referenced against expert panel assessments anchored the analytical framework throughout the projection horizon. Segmentation dimensions spanned product type, technology platform, application workflow, and end-user procurement model. CAGRs derived from instrument replacement cycle analysis, biologics pipeline expansion rates, and regulatory detection threshold tightening trajectories.
Regulatory timeline delays, helium supply export disruptions, and biologics pipeline attrition are the dominant revision risks to forecast assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Bitumen and Asphalt Testing Services Market
Testing Equipment
Laboratory Filtration Equipment and Supplies Market
Testing Equipment
Hydrogen Gas Analyzers Market
Testing Equipment
Flammability Tester Market
Testing Equipment
Water Penetration Tester Market
Testing Equipment
Leather Testing Machine Market
Testing Equipment
Europe Process Analytics Market
Testing Equipment
Global Laboratory Analytical Instruments and Consumables Market
Testing Equipment
Oxidation Stability Analyzer Market
Testing Equipment
Reagent Filling Systems Market
Testing Equipment
North America Dissolved Gas Analyzer Market
Testing Equipment
Brittleness Tester Market
Testing Equipment
Global Liquid Chromatography Instruments Market
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market