
 North America Dissolved Gas Analyzer Market | 2026-2036
North America Dissolved Gas Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dissolved Gas Analyzer Market Analytics
IEEE-compliant diagnostic tiers is reorganizing procurement patterns across the North America Dissolved Gas Analyzer Market, pushing utilities toward higher-accuracy chromatography-based systems. General Electric Company leverages its embedded utility relationships to sustain long-term service contracts in power generation applications. Qualitrol Company LLC specializes in online monitor integration, anchoring its position within transformer asset management programs. Siemens competes through technology leadership in optical sensing architectures for dissolved hydrogen detection.
A dissolved gas analyzer detects and quantifies gases—hydrogen, methane, ethane, ethylene, acetylene, carbon monoxide, and carbon dioxide—dissolved in transformer insulating oil, typically achieving detection thresholds below one part per million through gas chromatography or photoacoustic spectroscopy. The instrument enables predictive maintenance by identifying thermal and electrical fault precursors before catastrophic equipment failure. Online monitors command premium positioning due to continuous data streams that integrate with SCADA and enterprise asset management platforms, while portable analyzers serve routine field audits and emergency response protocols. Laboratory analyzers retain dominance in forensic diagnostics and arbitration testing where full chromatographic separation remains mandatory. Chromatography technology leads in precision-critical installations, though optical sensors gain traction in distributed monitoring networks where reduced maintenance intervals offset marginally lower specificity.
The Institute of Electrical and Electronics Engineers C57.104 standard governs dissolved gas interpretation thresholds across the United States, while provincial utilities in Canada reference CSA C50 standards for oil-filled equipment monitoring. The Environmental Protection Agency enforces polychlorinated biphenyl handling protocols that shape analyzer deployment during transformer decommissioning and retrofill operations. Stakeholders must weigh capital intensity against outage cost avoidance as grid hardening investments and renewable interconnection requirements expand the addressable installed base of monitored transformers.
Market Dynamics
The IEEE C57.104 standard revision is compressing procurement cycles across the North America Dissolved Gas Analyzer Market, mandating real-time fault detection capabilities that favor online monitor architectures over legacy laboratory systems. Utilities now face capital allocation trade-offs between chromatography precision and optical sensor maintenance economics.
Growth Catalysts
- Grid Modernization Mandates:FERC Order 2222 implementation in the United States is accelerating distributed energy resource interconnection, requiring continuous transformer monitoring at renewable integration points.
- CSA C50 Compliance:Canadian provincial utilities in Ontario and British Columbia are expanding dissolved gas analysis programs to meet stricter oil-filled equipment reliability standards.
- Photoacoustic Spectroscopy:This optical detection method is reducing calibration intervals, enabling cost-effective deployment across rural substation networks previously served by portable units.
Market Restraints
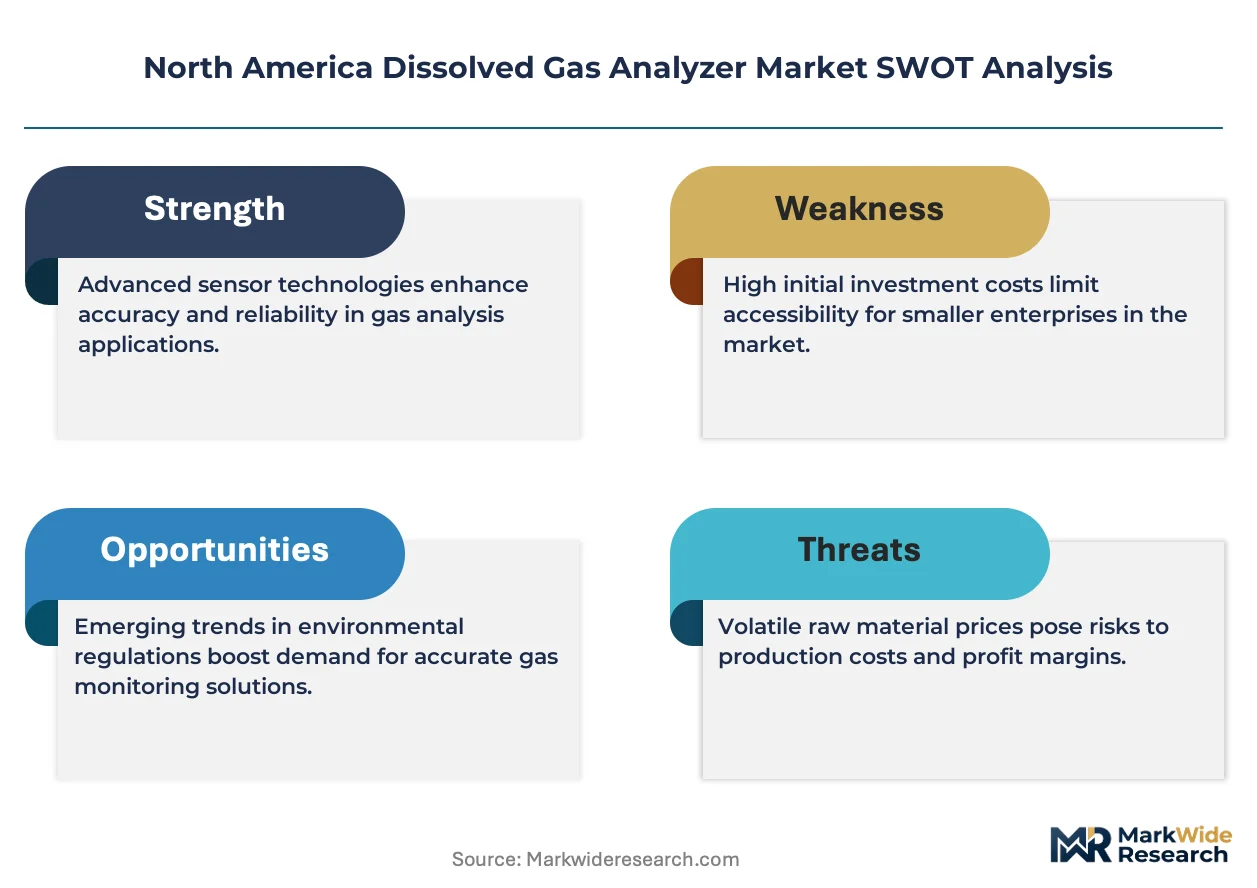
- Helium Supply Concentration:Gas chromatography systems depend on helium carrier gas, with North American supply concentrated in Wyoming and Texas extraction fields subject to export quota volatility.
- Capital Intensity Thresholds:Online monitor installations require SCADA integration and civil works, pricing out municipal utilities with sub-50 MVA transformer fleets.
- Optical Specificity Limitations:Photoacoustic sensors cannot resolve individual hydrocarbon ratios below IEEE diagnostic tier thresholds, restricting their use in forensic arbitration applications.
Strategic Opportunities
- Texas ERCOT Grid Expansion:Interconnection queue backlogs are creating demand for temporary monitoring solutions during transformer commissioning phases.
- California SB 100 Compliance:The state's renewable portfolio standard is forcing investor-owned utilities to monitor aging transformer assets serving solar and wind farms.
- Edge Computing Convergence:Onboard analytics combining dissolved gas data with thermal imaging is enabling predictive models that reduce false-positive maintenance dispatches.
Industry Challenges
- Chromatography Technician Scarcity:Field maintenance of gas separation columns requires specialized training that utility workforces lack, forcing reliance on OEM service contracts.
- Legacy SCADA Integration:DNP3 protocol mapping between new optical monitors and 1990s-era control systems demands custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dissolved Gas Analyzer Market |
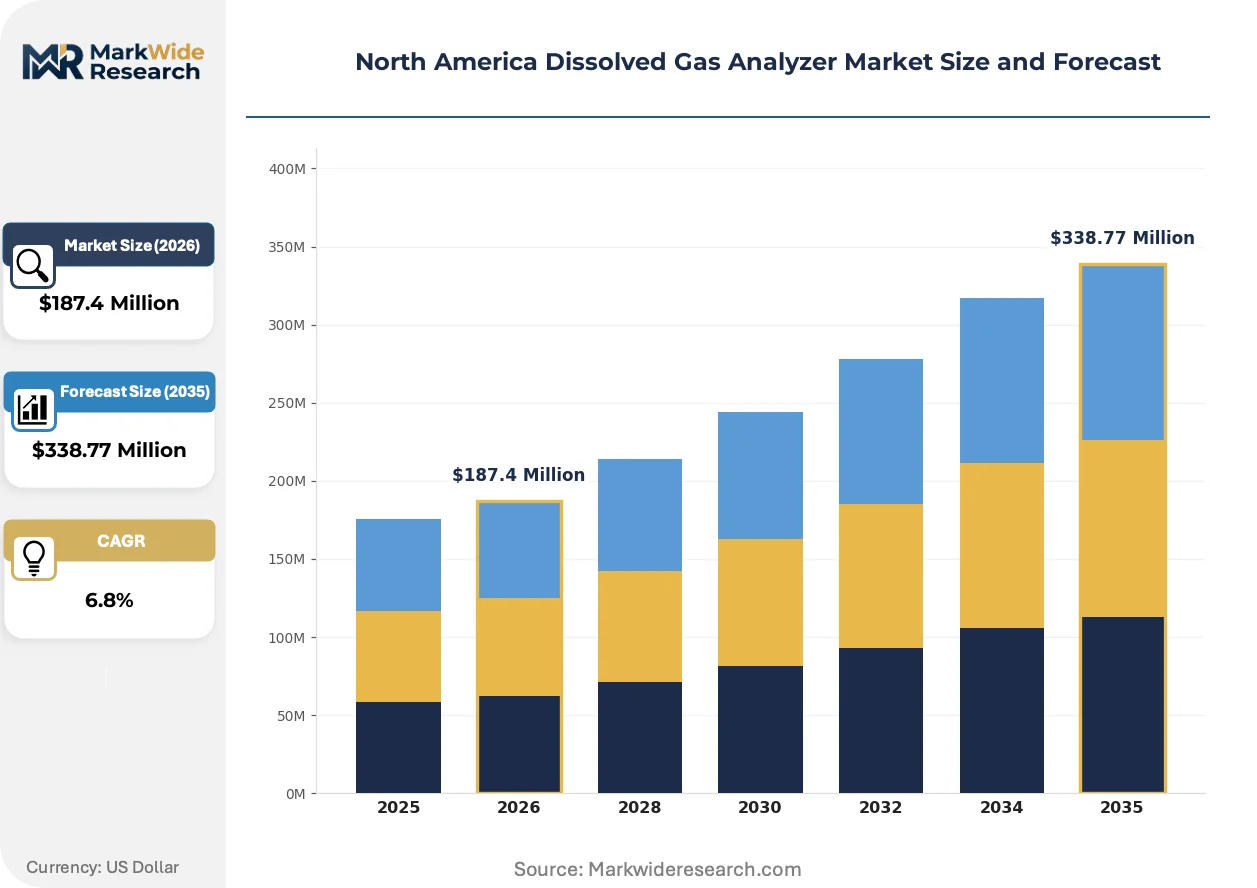
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Laboratory Analyzers, Online Monitors, Field Analyzers Technology: Membrane Contactors, Optical Sensors, Electrochemical Sensors, Chromatography End User: Utility Companies, Industrial Plants, Research Laboratories, Environmental Agencies Application: Water Treatment, Power Generation, Oil & Gas, Environmental Monitoring |
| Companies Covered | Doble Engineering Company, General Electric Company, Qualitrol Company LLC, SDMyers, Vaisala, Weidmann Electrical Technology AG, Advanced Energy Industries, Inc., Siemens, Hitachi Energy Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dissolved Gas Analyzer Market Evolving Landscape
Sensor miniaturization and edge analytics are restructuring how dissolved gas data flows from transformer assets to enterprise decision systems. The market is witnessing a fundamental shift from laboratory-centric diagnostics to continuous field intelligence.
MEMS-based hydrogen sensors are displacing traditional thermal conductivity detectors in distributed monitoring networks. Midwestern utilities with extensive rural substation footprints are deploying these solid-state devices at one-third the installed cost of chromatography systems. The technology is displacing centralized laboratory workflows by enabling immediate fault classification without oil sample transport.
The EPA's updated polychlorinated biphenyl handling regulations are mandating sealed sampling systems during transformer retrofill operations. This industrial consequence is forcing analyzer manufacturers to redesign portable unit interfaces for containment compatibility. Decommissioning contractors in the Great Lakes region are most affected, retrofitting legacy equipment with closed-loop extraction hardware.
Performance-based service contracts are replacing traditional capital purchase models among large investor-owned utilities. Equipment vendors now retain analyzer ownership, charging per-monitored-asset fees that align costs with reliability outcomes. This shift is most visible in California, where PG&E and Southern California Edison have consolidated multi-year agreements covering thousands of transformer units.
North America Dissolved Gas Analyzer Market Segmentation
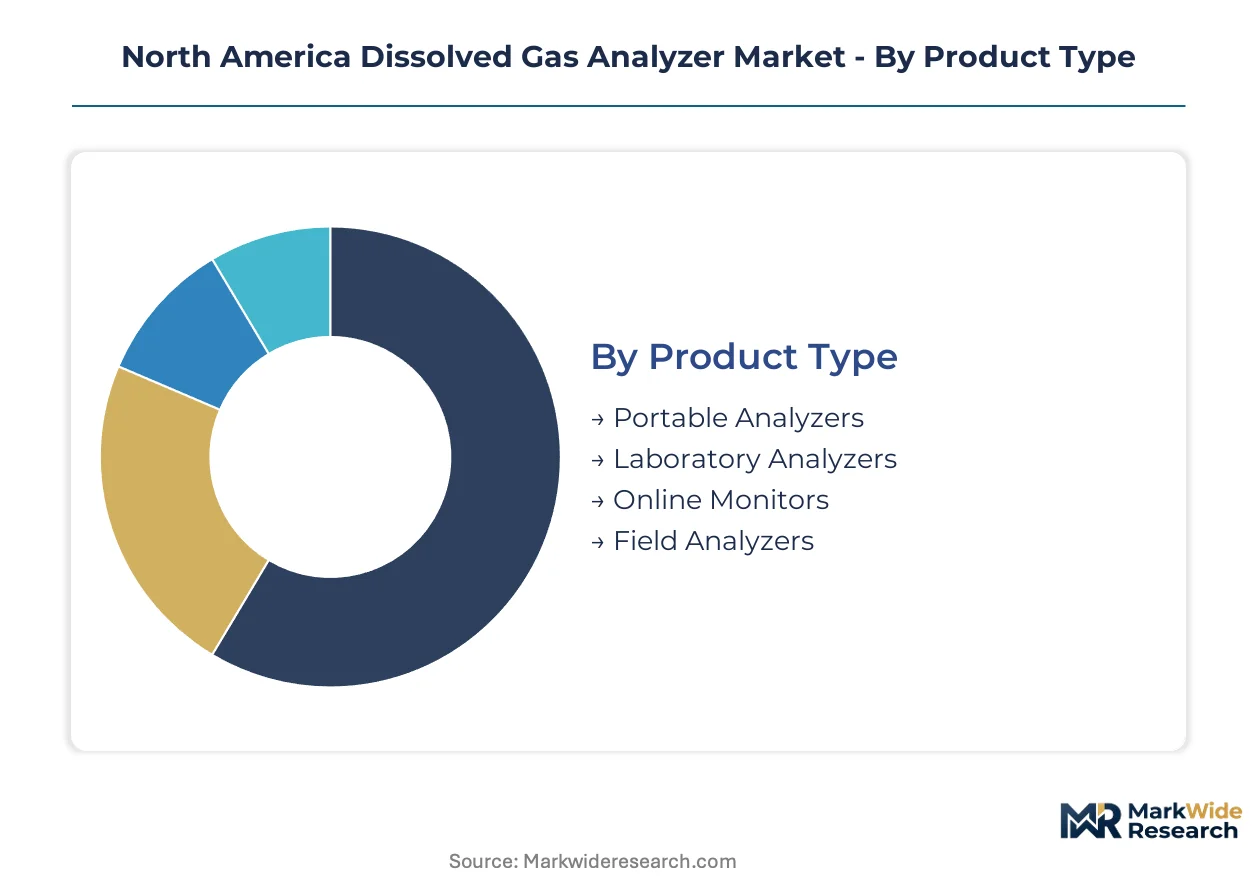
Dissolved gas analyzer procurement patterns diverge sharply across deployment contexts, with utility asset management programs driving specifications toward continuous monitoring architectures while industrial users prioritize field portability and rapid response capabilities.
Product Type:
Optical sensing technologies are displacing chromatography systems in the most price-sensitive substation tiers, compressing margins for traditional laboratory-grade equipment while elevating total cost-of-ownership calculations for online monitor deployments.
- Portable Analyzers:Battery-powered units with gas extraction modules and integrated thermal conductivity detection enable emergency response teams to classify transformer fault severity within 15 minutes of site arrival. Demand concentrates among municipal utilities in the Great Plains states where transformer density does not justify fixed infrastructure investments, though calibration drift in extreme temperature conditions limits deployment confidence.
- Online Monitors:Permanently installed systems with continuous oil circulation loops stream dissolved gas data directly to SCADA historians and enterprise asset management platforms. Texas and California investor-owned utilities anchor procurement volumes as FERC Order 2222 interconnection mandates and SB 100 renewable integration requirements force real-time visibility over aging transformer fleets serving solar and wind generation clusters.
- Laboratory Analyzers:Benchtop chromatography systems with full hydrocarbon separation capabilities serve forensic diagnostics and arbitration testing where IEEE C57.104 diagnostic tier compliance demands precise gas ratio quantification.
- Field Analyzers:Ruggedized transportable units bridge portable convenience with laboratory-grade precision for contractor-led transformer commissioning and warranty validation programs.
Online monitors anchor the volume base while portable analyzers gain share at the steepest rate as rural cooperative utilities defer capital-intensive fixed installations.
Technology:
Helium supply volatility from Wyoming and Texas extraction fields is forcing procurement committees to reevaluate carrier gas dependence across their analyzer fleets.
- Chromatography:Gas separation columns with flame ionization or thermal conductivity detection achieve sub-ppm detection thresholds for all seven fault gases specified in IEEE C57.104. Ontario and British Columbia provincial utilities specify these systems for critical transformer assets above 100 MVA rating, though specialized technician scarcity forces reliance on OEM service contracts that inflate lifecycle costs.
- Optical Sensors:Photoacoustic spectroscopy and infrared absorption architectures eliminate consumable carrier gases while reducing calibration intervals to annual cycles. Midwestern utilities with extensive rural substation footprints are deploying these solid-state devices across distributed monitoring networks where maintenance access constraints previously favored centralized laboratory workflows.
- Membrane Contactors:Hydrophobic membrane modules extract dissolved gases into sweep gas streams for external sensor analysis, enabling modular retrofit of existing transformer oil circulation systems.
- Electrochemical Sensors:Solid-state hydrogen-specific detectors with MEMS fabrication achieve lowest-in-class unit economics for single-gas fault precursor monitoring in secondary distribution transformers.
Chromatography retains the premium tier while optical sensors climb the fastest as photoacoustic detection thresholds approach laboratory-grade specifications.
End User:
Performance-based contracting structures are reallocating equipment ownership risk from capital budgets to operational expenditure lines among the largest transformer fleet operators.
- Utility Companies:Investor-owned and municipal electric utilities operate dissolved gas analysis programs spanning generation step-up transformers, transmission grid assets, and distribution substations. California PG&E and Southern California Edison have consolidated multi-year service agreements covering thousands of monitored units, with vendors retaining analyzer ownership and charging per-asset reliability fees.
- Industrial Plants:Refineries, petrochemical complexes, and heavy manufacturing facilities deploy portable and online systems for captive power generation assets and process-critical transformer units where unplanned outage costs exceed analyzer capital expenditure by orders of magnitude.
- Research Laboratories:University and national laboratory facilities utilize laboratory-grade chromatography for transformer insulation material research, alternative dielectric fluid evaluation, and forensic failure investigation supporting insurance and litigation proceedings.
- Environmental Agencies:State and federal environmental regulators deploy portable analyzers during transformer decommissioning and retrofill operations to verify PCB contamination levels and compliance with EPA handling protocols.
Utility companies dominate installed base volume while industrial plants expand most quickly as manufacturing reshoring intensifies captive power reliability requirements.
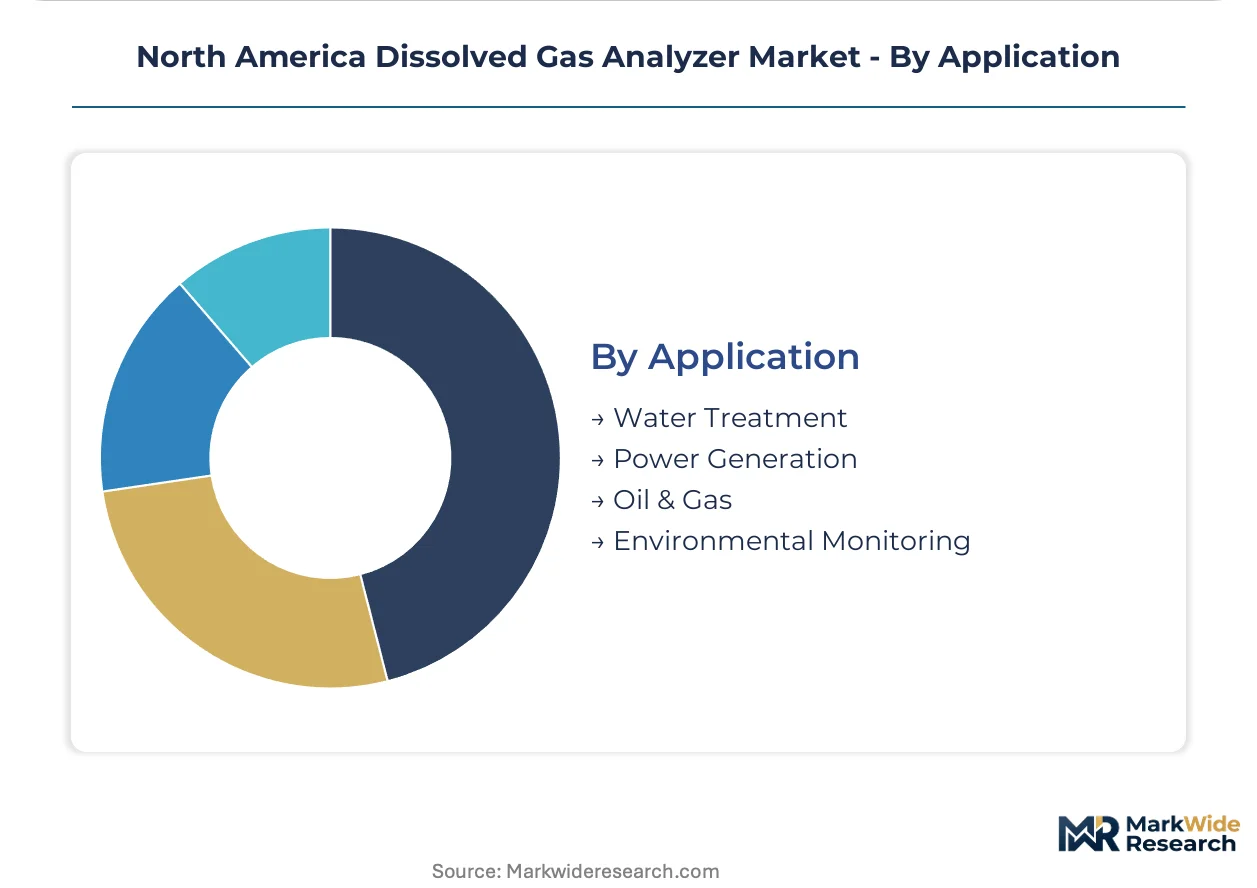
Application:
Renewable interconnection mandates are redefining transformer monitoring intensity across transmission and distribution voltage classes.
- Power Generation:Generator step-up transformers and intertie autotransformers require continuous dissolved gas monitoring to manage cycling thermal stress from renewable generation variability. Texas ERCOT queue backlogs are creating demand for temporary monitoring solutions during extended commissioning phases for solar and wind farm interconnects.
- Oil & Gas:Upstream production facilities, midstream pipeline compressor stations, and downstream refinery complexes rely on dissolved gas analysis for process transformer protection in hazardous classification environments where conventional monitoring architectures face installation constraints.
- Water Treatment:Municipal and industrial water treatment plants utilize dissolved gas analyzers for dissolved oxygen and nitrogen monitoring in process water systems, though this application represents a distinct equipment category with limited technology overlap to transformer oil analysis.
- Environmental Monitoring:Groundwater and surface water dissolved gas analysis supports watershed protection and contamination source identification programs, again utilizing distinct sensor configurations from power sector transformer monitoring equipment.
Power generation anchors category volume while oil and gas applications gain share fastest as electrification of production facilities expands transformer fleet monitoring requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America Dissolved Gas Analyzer Market operates with the United States as a net importer of specialized chromatography components and helium carrier gas, while Canada maintains equipment manufacturing capabilities serving provincial utility programs. Cross-border service integration shapes competitive dynamics across the region.
United States
FERC Order 2222 implementation accelerates distributed energy resource interconnection, forcing continuous transformer monitoring at solar and wind integration points. The Environmental Protection Agency enforces polychlorinated biphenyl handling protocols during decommissioning operations. Texas ERCOT grid expansion and California SB 100 compliance drive concentrated demand in Houston and Los Angeles metropolitan clusters.
Canada
Provincial utilities in Ontario and British Columbia expand dissolved gas analysis programs to meet CSA C50 oil-filled equipment reliability standards. Hydro One and BC Hydro procurement frameworks favor performance-based service contracts over capital purchases. Toronto and Vancouver anchor equipment deployment, with rural substation networks in the Prairie Provinces adopting photoacoustic spectroscopy for maintenance access constraints.
Mexico
Comisión Federal de Electricidad modernization initiatives create demand for portable analyzers in transmission grid reinforcement projects. The Secretaría de Energía mandates enhanced asset monitoring for renewable interconnection agreements. Monterrey and Mexico City concentrate deployment activity, with northern border states adopting cross-compatible SCADA protocols for grid synchronization with Texas utilities.
North America Dissolved Gas Analyzer Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and service contract structures, creating a tiered competitive landscape where scale advantages meet application-specific expertise. The vendor base separates into chromatography precision providers, optical sensing innovators, and integrated asset management platforms. Strategic archetypes include utility-embedded incumbents, technology-focused disruptors, and regional service integrators. Dominant competitive moves center on multi-year performance contracts and edge analytics convergence with thermal monitoring systems.
Among diversified electrical equipment manufacturers, General Electric Company and Siemens occupy positions spanning generation, transmission, and distribution applications. Qualitrol Company LLC exemplifies the specialist archetype with focused online monitor integration capabilities. These three entities represent contrasting strategic postures: broad portfolio leverage against concentrated diagnostic expertise.
| Leading Market Players |
|---|
| Doble Engineering Company |
| General Electric Company |
| Qualitrol Company LLC |
| SDMyers |
| Vaisala |
| Weidmann Electrical Technology AG |
| Advanced Energy Industries, Inc. |
| Siemens |
| Hitachi Energy Ltd. |
| Others |
Value Network & Pricing Analysis
Photoacoustic spectroscopy displacement of chromatography systems redraws procurement economics across the North America Dissolved Gas Analyzer Market, collapsing maintenance cost structures while redistributing supplier power toward solid-state component manufacturers in the United States and Canada.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with chromatography-based laboratory systems commanding certification-grade premiums against photoacoustic alternatives. Price differentiation rests on IEEE C57.104 diagnostic tier compliance and OEM service contract bundling, with municipal utilities exhibiting acute price sensitivity versus investor-owned utilities absorbing lifecycle-cost premiums. Cost compression in the portable analyzer tier is intensifying because MEMS-based hydrogen sensors erode thermal conductivity detector margins.
Supply Chain Analysis
Helium extraction concentration in Wyoming and Texas fields creates a chokepoint that constrains chromatography system availability and inflates carrier gas procurement costs for utilities maintaining legacy fleets. Component sourcing draws from United States optical sensor fabs, Canadian membrane contactor specialists, and German gas separation column manufacturers. Single-source vulnerability in helium supply chains threatens analyzer production continuity. Distribution runs through authorized OEM service networks and direct utility procurement channels, with performance-based contracts shifting inventory risk to vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Dissolved Gas Analyzer Market structures as a service-attach opportunity where multi-year performance contracts expand faster than hardware shipments, with per-asset reliability fees now exceeding 40% of vendor revenue pools among California and Texas utilities.
For Market Incumbents: Secure long-term calibration service agreements before photoacoustic sensor standardization erodes chromatography maintenance revenue streams. Deepen backward integration into MEMS hydrogen sensor fabrication to capture margin from emerging optical architectures. Lock in exclusive SCADA integration partnerships with investor-owned utilities to create switching costs against modular competitors. For New Entrants and Emerging Players: IEEE C57.104 certification fast-tracks open regulatory pathways for photoacoustic systems targeting rural cooperative utilities in the Great Plains and Prairie Provinces. Municipal utilities with sub-50 MVA transformer fleets represent the most penetrable segment, lacking capital budgets for online monitor installations. Pursue equipment-as-a-service models that eliminate upfront capital barriers and align vendor incentives with reliability outcomes. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed diagnostic equipment platforms seeking add-on acquisitions in edge analytics and thermal monitoring convergence. The 5-10 year viability window favors vendors with installed bases exceeding 10,000 monitored transformer assets capable of generating recurring calibration and software upgrade revenue. Watch FERC interconnection queue clearance rates as the signal indicating temporary monitoring demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Service Contract Expansion | PG&E and Southern California Edison consolidation creates template for per-asset pricing across investor-owned utilities. |
| Edge Analytics Platform Integration | Onboard dissolved gas-thermal imaging fusion reduces false-positive maintenance dispatches for ERCOT grid operators. |
| Photoacoustic Sensor Manufacturing Scale-Up | Domestic MEMS fab investment eliminates helium dependency and compresses rural substation deployment costs. |
| SCADA Protocol Standardization Partnership | DNP3 middleware development with 1990s-era control systems unlocks retrofit opportunities in legacy utility infrastructure. |
| Helium Recovery and Recycling Infrastructure | Wyoming and Texas extraction field partnerships secure carrier gas supply continuity for chromatography maintenance revenue. |
Research Methodology
A standing panel of utility asset management directors, transformer maintenance engineers, OEM service contract managers, and provincial regulatory affairs leads provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation against FERC filings, EPA enforcement databases, IEEE standards documentation, and utility procurement records. Bottom-up transformer fleet enumeration triangulated against top-down equipment vendor shipment estimates to establish market sizing boundaries.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product architecture, detection technology, end-user category, and application voltage class. CAGRs derived from transformer installation growth rates, renewable interconnection mandates, and equipment replacement cycles. Forecast inputs incorporated CSA C50 compliance timelines, helium supply elasticity estimates, and photoacoustic detection threshold improvement trajectories.
The analysis sits within stated boundaries; outcomes outside sustained grid modernization investment levels or helium supply disruption scenarios would require recalibration. Forecasts reflect documented assumptions regarding IEEE standard adoption rates and utility capital allocation priorities. Practitioners should keep alternative scenarios live as FERC Order 2222 implementation pace and provincial regulatory enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
Cyclic Corrosion Test Chamber Market
Testing Equipment
Ammonia Testing Market
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
Benchtop Density Meter for Solids Market
Testing Equipment
Global Liquid Chromatography Systems Market
Testing Equipment
Hydrogen Peroxide Measurement Market
Testing Equipment
Chromatography Accessories and Consumables Market
Testing Equipment
Rheometer Market
Testing Equipment
Global Lab Supplies Market
Testing Equipment
Global Chromatography Instrumentation Market
Testing Equipment
Piping Hydro Testing Market
Testing Equipment
Wood Moisture Tester Market
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Leather Testing Machine Market
Testing Equipment
Sample Preparation Market