
 High Performance Foam Market | 2026-2036
High Performance Foam Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Foam Market Outlook
Polymer chemist and process engineering talent scarcity is bifurcating the competitive landscape between integrated material science platforms and specialized foam converters. Huntsman Corporation leverages its upstream polyurethane systems expertise to control formulation IP and captive feedstock supply. BASF SE anchors European demand through its Ludwigshafen integrated site and technical service density. Zotefoams plc specializes in nitrogen-expanded cellular structures for aerospace and medical grades where purity standards exclude conventional blowing agents.
High performance foam denotes engineered cellular polymers with controlled density below 300 kg/m³, compressive strength exceeding 200 kPa, and thermal stability above 120°C, manufactured via supercritical gas foaming or reactive extrusion to deliver energy absorption, insulation, or structural core functions. Polyurethane foam dominates current volume owing to its versatility across automotive seating and construction insulation, though margin pools concentrate in specialty polyethylene foam grades for medical packaging and athletic equipment. Polypropylene foam represents the fastest-growing structural category as electric vehicle battery pack manufacturers seek thermoplastic recyclability and crash-energy management in a single material platform.
REACH registration requirements and the EU F-Gas Regulation constrain blowing agent chemistry selections, while FDA biocompatibility standards govern medical-grade foam qualification pathways in the United States. ECHA substance-of-very-high-concern listings are accelerating reformulation cycles among European producers, effectively raising barriers for non-integrated compounders lacking toxicology and regulatory affairs capacity. Stakeholders must monitor polymer feedstock cost volatility alongside evolving circular-economy mandates that will determine which foam chemistries retain license to operate in key end-use segments.
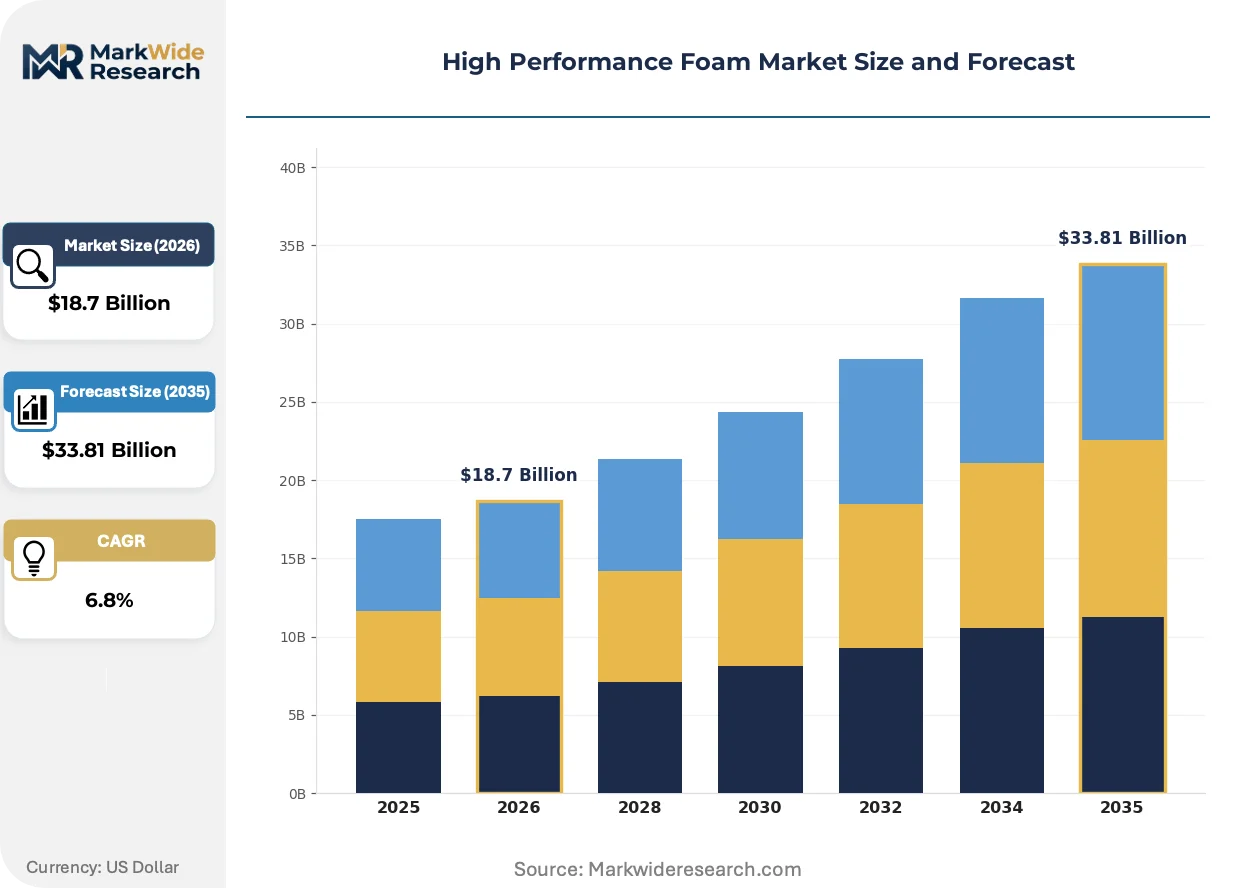
Market Dynamics
Electric vehicle battery pack architectures are rewriting material specifications across the high performance foam supply chain, forcing converters to reconcile thermoplastic recyclability mandates with crash-energy absorption performance in a single polymer platform.
Growth Catalysts
- REACH SVHC Listings:ECHA substance-of-very-high-concern designations are accelerating reformulation cycles among European compounders, creating replacement demand for compliant blowing agent systems and purified feedstock grades.
- Aerospace Lightweighting:Commercial aviation OEMs are expanding nitrogen-expanded cellular core adoption to meet FAA fuel efficiency certification thresholds for next-generation narrow-body programs.
- Medical Packaging Purity Standards:FDA biocompatibility qualification pathways for implant-contact foams are concentrating margin pools in supercritical gas foaming capacity that excludes residual blowing agent contamination.
Market Restraints
- Feedstock Cost Volatility:Polyurethane system house margins remain exposed to isocyanate and polyol price swings driven by European natural gas benchmark fluctuations and Asian aromatic supply disruptions.
- Blowing Agent Chemistry Constraints:EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon options faster than hydro-olefin alternatives achieve cost parity at commercial scale.
- Specialized Talent Scarcity:Polymer chemist and process engineering expertise sufficient for supercritical gas foaming scale-up concentrates in Ludwigshafen, Basel, and Houston corridor employers.
Strategic Opportunities
- Indian Electric Vehicle Localization:PLI scheme incentives for battery pack manufacturing in Tamil Nadu and Gujarat are creating first-mover openings for polypropylene structural foam qualification with domestic OEMs.
- Construction Thermal Retrofit Mandates:EU Green Deal building renovation wave regulations are expanding specification volume for phenolic and PIR high-performance insulation boards in German and French municipal housing stock.
- Supercritical CO₂ Extrusion Convergence:Nitrogen gas foaming expertise from aerospace grades is migrating into athletic equipment and medical packaging via shared equipment platforms and process IP licensing.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA biocompatibility, REACH registration, and MDR technical documentation requirements are extending medical-grade foam qualification cycles beyond typical automotive program windows.
- Circular-Economy Integration Complexity:Mechanical recycling infrastructure for cross-linked polyethylene and polyurethane foams remains underdeveloped, forcing producers to fund pilot chemical recycling partnerships without guaranteed offtake volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Foam Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Polyethylene Foam, Polypropylene Foam, PVC Foam Application: Aerospace, Automotive, Packaging, Construction End User: Manufacturers, Retailers, Distributors, Consumers Distribution Channel: Online, Offline, Direct Sales, Wholesale |
| Companies Covered | Huntsman Corporation, Armacell International S.A., BASF SE, Zotefoams plc, Rogers Corporation, Dow Inc., Arkema S.A., Recticel N.V., Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Foam Market Strategic Shifts
Material science platforms are fragmenting along purity-grade lines as end-use specifications diverge between commodity construction insulation and certified medical-device foams requiring toxicology dossier support.
Supercritical nitrogen gas foaming is decomposing the conventional blowing agent supply chain by eliminating residual chemical contamination risks in aerospace and medical grades. Tier-one suppliers in Toulouse and Hamburg are qualifying nitrogen-expanded polyimide and PEEK foams for primary structural cores. This process chemistry is decomposing demand for hydrocarbon and hydrofluorocarbon blowing agents in segments where outgassing specifications exclude conventional alternatives.
EU F-Gas Regulation phase-down schedules are compressing hydrofluorocarbon availability for polyurethane foam production faster than hydro-olefin substitutes achieve formulation stability at industrial scale. System houses with captive hydro-olefin supply agreements are securing preferential allocation from construction insulation customers facing 2027 compliance deadlines. German and Benelux producers are accelerating retrofit investments to maintain license-to-operate under tightening GWP-weighted quota systems.
Automotive OEMs are consolidating foam supply relationships around integrated material science platforms capable of simultaneous battery pack thermal runaway containment and crash-structure energy management. Tier-one seating and interior suppliers are losing specification influence as cell manufacturers and OEM chassis engineers co-develop polypropylene foam core designs. This consolidation pattern is most visible in Stuttgart, Munich, and Shanghai engineering centers where platform decisions precede component sourcing.
High Performance Foam Market Segmentation
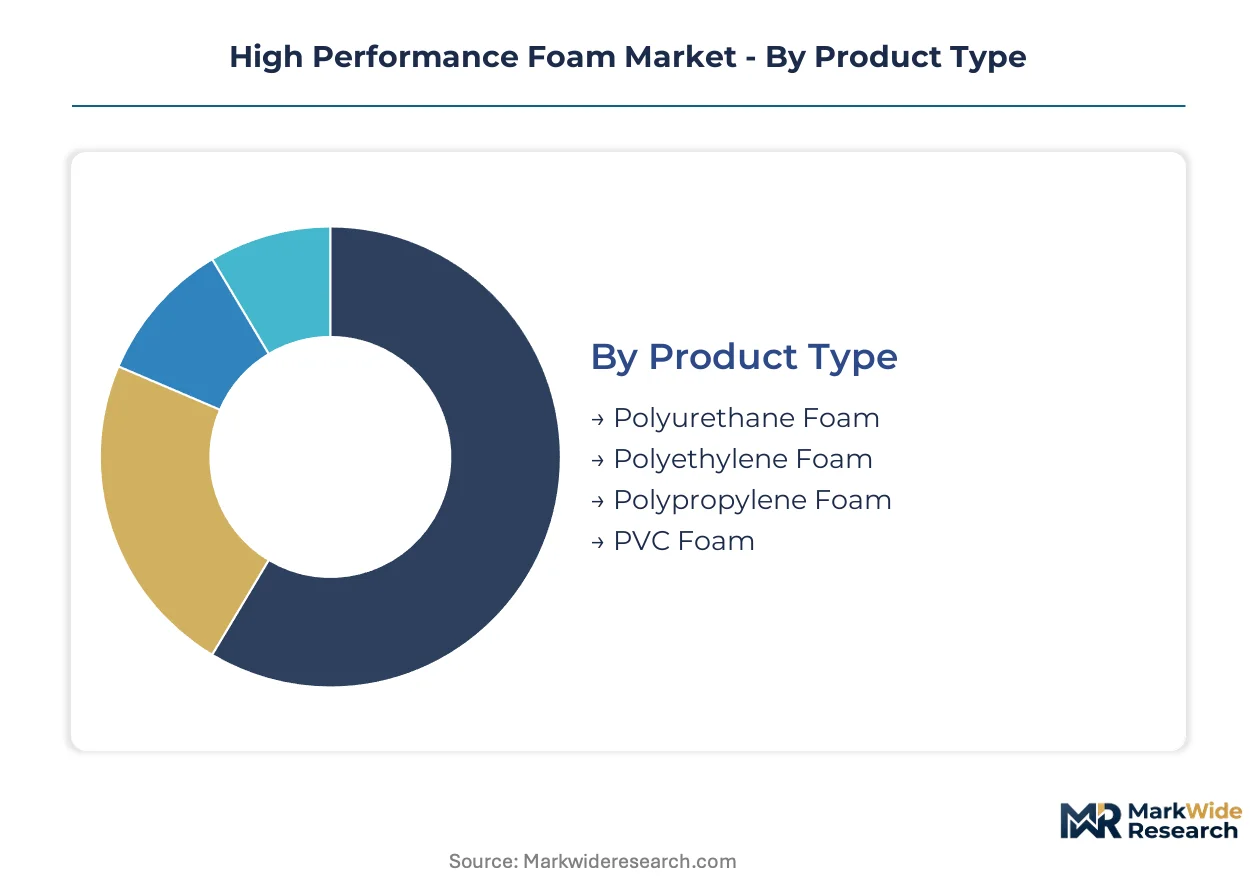
High performance foam markets fragment along purity-grade lines where medical-device certification commands premium multiples over construction commodity grades. Specification divergence between nitrogen-expanded aerospace cores and conventional blown insulation is widening the competitive moat between integrated material science platforms and compounders lacking toxicology dossier capacity.
Product Type:
Margin pools concentrate in specialty polyethylene and polypropylene grades where supercritical gas foaming excludes conventional blowing agent competition.
- Polyurethane Foam:Reactive extrusion of isocyanate-polyol systems delivers versatile density control across automotive seating and construction insulation. Current volume leadership rests with German system houses supplying Ludwigshafen-anchored OEMs facing F-Gas Regulation compliance deadlines.
- Polypropylene Foam:Thermoplastic cellular structures offer crash-energy absorption combined with mechanical recyclability for electric vehicle battery pack architectures. Stuttgart and Shanghai engineering centers are consolidating specification authority around this chemistry for platform decisions.
- Polyethylene Foam:Cross-linked nitrogen-expanded grades dominate medical packaging and athletic equipment where FDA biocompatibility pathways exclude residual contamination.
- PVC Foam:Rigid cellular cores serve marine and wind blade applications with established supply chains through Benelux converters.
The dominant share belongs to polyurethane foam, while polypropylene foam is closing the gap fastest through electric vehicle platform adoption.
Application:
Volume distribution tracks end-use certification burden, with aerospace and medical segments capturing disproportionate margin despite smaller tonnage.
- Aerospace:Nitrogen-expanded polyimide and PEEK structural cores meet FAA fuel efficiency thresholds for narrow-body programs. Toulouse and Hamburg tier-one suppliers are qualifying primary load-bearing applications.
- Automotive:Battery pack thermal runaway containment and crash-structure energy management are consolidating supply relationships around integrated platforms. OEM chassis engineers in Munich now precede component sourcing decisions.
- Packaging:Medical-grade supercritical foaming capacity serves implant-contact applications with toxicology dossier requirements.
- Construction:Phenolic and PIR insulation boards face EU Green Deal retrofit mandates across German and French municipal housing stock.
Aerospace commands the steepest pricing tier, though automotive is expanding most quickly through electric vehicle localization.
End User:
Procurement authority concentrates with manufacturers possessing in-house material science capability to navigate multi-jurisdiction certification timelines.
- Manufacturers:Tier-one automotive seating suppliers and aerospace converters with captive formulation IP and regulatory affairs capacity.
- Retailers:Athletic equipment and consumer goods channels sourcing certified foam components through distributor networks.
- Distributors:Construction insulation wholesalers managing inventory exposure to isocyanate price volatility.
- Consumers:Direct procurement limited to specialty medical and recreational applications with low volume.
Manufacturers retain specification control, while distributors are gaining influence fastest through inventory financing capabilities.
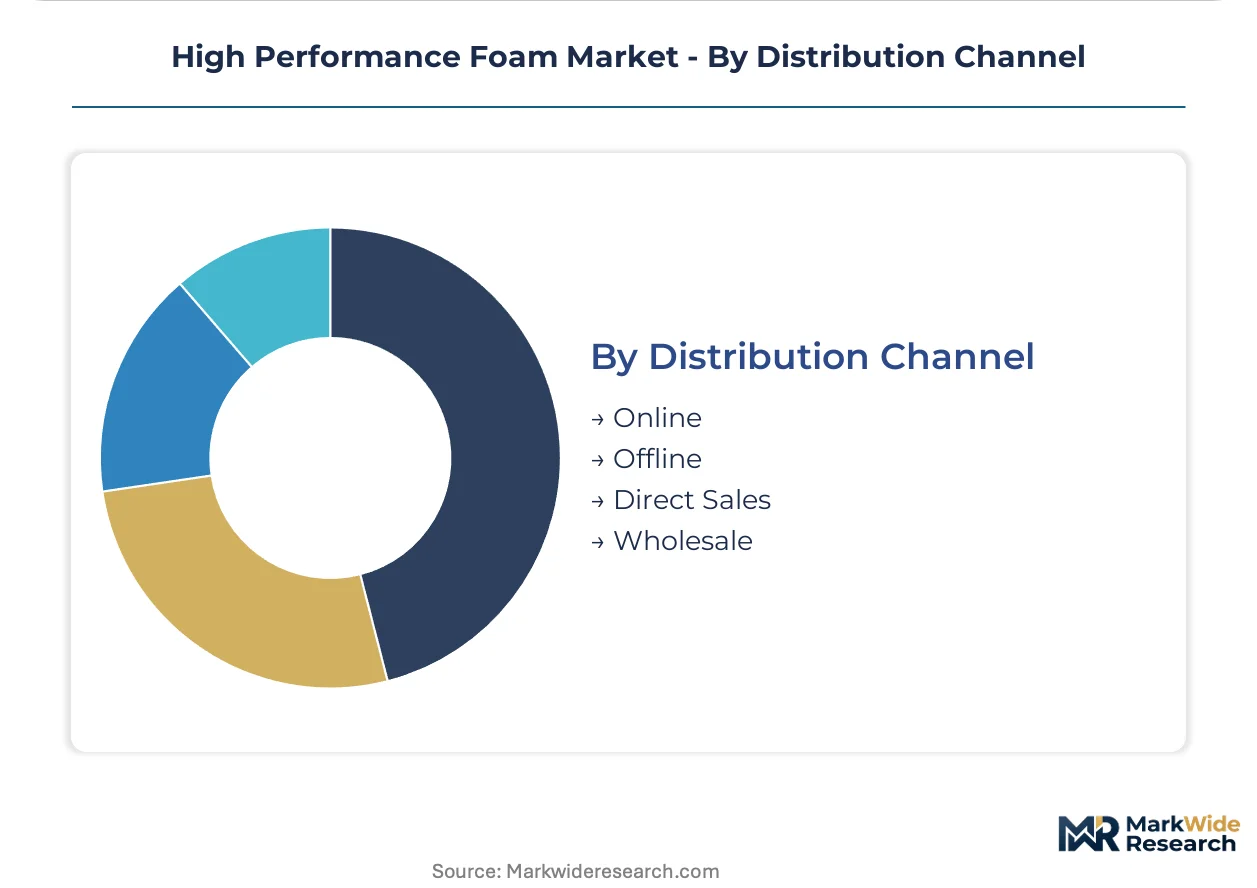
Distribution Channel:
Channel selection follows certification complexity, with direct relationships dominating medical and aerospace grades.
- Direct Sales:Technical service density from integrated material science platforms supports co-development programs with OEM engineering centers.
- Wholesale:Construction insulation volume moves through regional distributors with REACH registration documentation.
- Online:Standardized grades for athletic equipment and consumer packaging with established specifications.
- Offline:Traditional distributor relationships serving smaller converters lacking regulatory affairs capacity.
Direct sales anchors the highest-value transactions, while online channels are climbing the fastest for commoditized grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA substance-of-very-high-concern listings anchor European regulatory gravity, forcing reformulation cycles that concentrate specification authority in integrated material science platforms across Germany, the United States, China, India, and Japan.
Germany
Automotive OEMs in Stuttgart and Munich drive polypropylene foam qualification for electric vehicle battery architectures. EU F-Gas Regulation phase-down schedules accelerate hydro-olefin blowing agent transitions among Ludwigshafen-anchored system houses. REACH compliance documentation concentrates procurement relationships around producers with captive toxicology capacity.
United States
FAA fuel efficiency certification thresholds expand nitrogen-expanded structural core adoption for next-generation narrow-body programs. FDA biocompatibility standards govern medical-grade foam qualification pathways, concentrating margin pools in supercritical gas foaming capacity. Aerospace tier-one suppliers in Seattle and Wichita qualify primary load-bearing cellular structures.
China
Dual carbon goals and MIIT industrial policy accelerate thermoplastic foam substitution for cross-linked chemistries in automotive applications. NMPA medical device regulations create parallel qualification pathways for implant-contact foam grades. Yangtze River Delta manufacturing clusters integrate supercritical CO₂ extrusion for export-grade medical packaging.
India
PLI scheme incentives for battery pack manufacturing in Tamil Nadu and Gujarat create first-mover openings for polypropylene structural foam qualification with domestic OEMs. CDSCO medical device regulations establish biocompatibility frameworks for nitrogen-expanded grades. Automotive engineering centers in Pune and Chennai consolidate material specification authority.
Japan
METI carbon neutrality roadmaps drive phenolic and PIR insulation board specification for building energy efficiency mandates. PMDA pharmaceutical regulations govern medical-grade foam import substitution programs. Osaka-based converters develop nitrogen-expanded grades for regional aerospace supply chains.
High Performance Foam Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where integrated material science platforms command premium segments while specialized converters serve volume construction applications. The market fragments along purity-grade lines, with supercritical gas foaming capacity concentrating among upstream polyurethane system houses and nitrogen-expansion specialists. Three archetypes dominate: Ludwigshafen-anchored chemical conglomerates with captive feedstock supply, nitrogen-expansion specialists serving aerospace and medical purity tiers, and regional foam converters lacking regulatory affairs capacity. Competitive moves center on hydro-olefin blowing agent supply agreements and supercritical extrusion technology licensing.
Among European-anchored chemical conglomerates, BASF SE and Covestro AG exemplify integrated platform strategies combining upstream polyurethane systems with technical service density. Zotefoams plc occupies a specialist position in nitrogen-expanded cellular structures where purity standards exclude conventional alternatives. These three companies represent the competitive spectrum from commodity volume leadership to premium-grade specialization.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Armacell International S.A. |
| BASF SE |
| Zotefoams plc |
| Rogers Corporation |
| Dow Inc. |
| Arkema S.A. |
| Recticel N.V. |
| Covestro AG |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Ludwigshafen-anchored system houses and German automotive OEMs lock in isocyanate supply access while capping price volatility exposure through the EU F-Gas Regulation transition window. These contracts bundle technical service density with volume commitments, embedding formulation IP support into unit economics.
Pricing Analysis
Price spreads between German medical-grade nitrogen-expanded foam and Chinese commodity polyurethane insulation exceed threefold, reflecting certification burden divergence. Three-tier pricing structure across aerospace-qualified, automotive-specified, and construction-commodity levels tracks ECHA compliance documentation costs. Pricing pressure stems from hydro-olefin blowing agent supply scarcity ahead of 2027 GWP-weighted quota enforcement. Automotive battery pack manufacturers show lowest price sensitivity due to crash-performance liability exposure, while construction distributors face margin compression from spot-indexed polyol procurement.
Supply Chain Analysis
Inventory cycles for medical-grade supercritical gas foaming capacity extend to six months given qualification documentation requirements. Supply concentrates in Germany, China, and the United States, with Ludwigshafen and Shanghai anchoring polyurethane systems and Yangtze River Delta clusters dominating export-grade medical packaging. Feedstock dependence on Asian aromatic supply and European natural gas benchmarks creates margin vulnerability. Single-source risk concentrates in hydro-olefin blowing agent production where capacity expansion lags F-Gas phase-down schedules. Distribution runs through direct technical service relationships for aerospace and medical tiers, with regional wholesalers handling construction insulation volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service attach rates for formulation co-development and regulatory dossier support are expanding faster than base material volume, creating recurring revenue layers that compound account stickiness. This service-attach dynamic repositions compounders as compliance partners rather than commodity suppliers.
For Market Incumbents: Shield margin pools in medical-grade nitrogen-expansion capacity through preemptive toxicology dossier investment ahead of ECHA SVHC listing expansions. Prioritize backward integration into hydro-olefin blowing agent supply to secure preferential allocation during EU F-Gas quota compression. Lock in automotive platform engineering relationships before cell manufacturers consolidate specification authority around integrated material science platforms. For New Entrants and Emerging Players: Regulatory affairs outsourcing gaps among mid-tier European foam converters present white-space entry points where incumbents under-serve compliance documentation. Target Indian battery pack manufacturing clusters in Tamil Nadu and Gujarat where PLI scheme localization creates first-mover qualification windows with domestic OEMs. Lead with supercritical CO₂ extrusion technology licensing to bypass captive formulation IP barriers. For Investors and Strategic Acquirers: Capital is best deployed toward nitrogen-expansion specialists with aerospace medical-grade purity positioning and underexploited athletic equipment licensing potential. Long-term viability hinges on circular-economy chemistry selection where thermoplastic recyclability mandates displace cross-linked alternatives. Monitor ECHA substance-of-very-high-concern listing velocity as inflection indicator for reformulation cycle intensity and replacement demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydro-Olefin Supply | Secures preferential blowing agent allocation under tightening EU F-Gas Regulation GWP quotas. |
| Supercritical Gas Foaming Capacity Expansion | Captures medical and aerospace margin pools where FDA and FAA certification excludes conventional alternatives. |
| Regulatory Affairs Service Layer Development | Transforms transactional supply relationships into recurring REACH and MDR compliance partnerships. |
| Indian Manufacturing Footprint Establishment | Positions for PLI scheme battery pack localization demand in Tamil Nadu and Gujarat clusters. |
| Chemical Recycling Partnership Investment | Addresses circular-economy mandates for cross-linked polyethylene and polyurethane foam recovery. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of ECHA substance registration databases, EU customs trade flows, and SEC filings from listed chemical conglomerates. Interviews with polyurethane system house technical directors, automotive OEM chassis engineers, medical device packaging procurement leads, and aerospace tier-one supplier quality managers informed demand-side validation. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include foam chemistry type, purity grade tier, end-use certification burden, and geographic regulatory cluster. CAGRs derived from elasticity-adjusted demand projections incorporating electric vehicle platform adoption curves and building retrofit mandate enforcement schedules. Forecast inputs incorporate REACH SVHC listing velocity, F-Gas Regulation phase-down compliance timelines, and MIIT industrial policy implementation pace.
Forecasts assume regulatory continuity in EU REACH and F-Gas regimes, US FDA biocompatibility pathways, and China MIIT dual carbon enforcement; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Hydrotalcite Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
Resin Capsule Market
Specialty Compounds
Ready Mix Joint Compound Market
Specialty Compounds
Polypropylene Compounds Market
Specialty Compounds
Thioglycolate Market
Specialty Compounds
Silicone Masterbatches Market
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
Global Sulfur Hexafluoride Market
Specialty Compounds
Chromatography Silica Resins Market
Specialty Compounds
Potassium Derivatives Market
Specialty Compounds
Saudi Arabia Collagen Market
Specialty Compounds
Collagen Hydrolysates Market
Specialty Compounds
Solketal Market
Specialty Compounds
United States Caustic Potash Market
Specialty Compounds
Sodium Stannate Market