
 Global Laboratory Analytical Instruments and Consumables Market | 2026-2036
Global Laboratory Analytical Instruments and Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laboratory Analytical Instruments and Consumables Market Foresight
Pharma-grade analytical specifications are redrawing competitive boundaries in laboratory instrumentation. Thermo Fisher Scientific Inc. leverages its captive consumables revenue to sustain pricing power across chromatography workflows. Danaher Corp. anchors its position through diagnostics-to-research vertical integration, while Agilent Technologies Inc. specializes in mass spectrometry platforms for regulated pharmaceutical environments.
Laboratory analytical instruments and consumables encompass precision measurement systems and single-use components that detect, quantify, and characterize chemical and biological samples at detection limits ranging from parts-per-billion to single-molecule sensitivity, serving quality assurance and research discovery across life sciences and materials science. Chromatographs and mass spectrometry systems command the largest installed base and highest replacement value, while consumables kits generate recurring revenue streams that often exceed initial instrument margins over a five-to-seven-year ownership cycle. Spectrometers and fluorescence spectroscopy platforms compete in environmental testing and food quality applications where portable and benchtop formats are displacing centralized lab workflows.
FDA 21 CFR Part 11, EMA GMP Annex 11, and ISO/IEC 17025 shape instrument software validation, electronic record integrity, and calibration traceability requirements that vendors must embed to maintain market access. China's NMPA and Japan's PMDA impose parallel data-integrity standards that foreign manufacturers navigate through localized compliance engineering. Stakeholders must monitor how AI-enabled analytical software triggers new regulatory scrutiny from the FDA and EU AI Act before committing to platform refresh timelines.
Market Dynamics
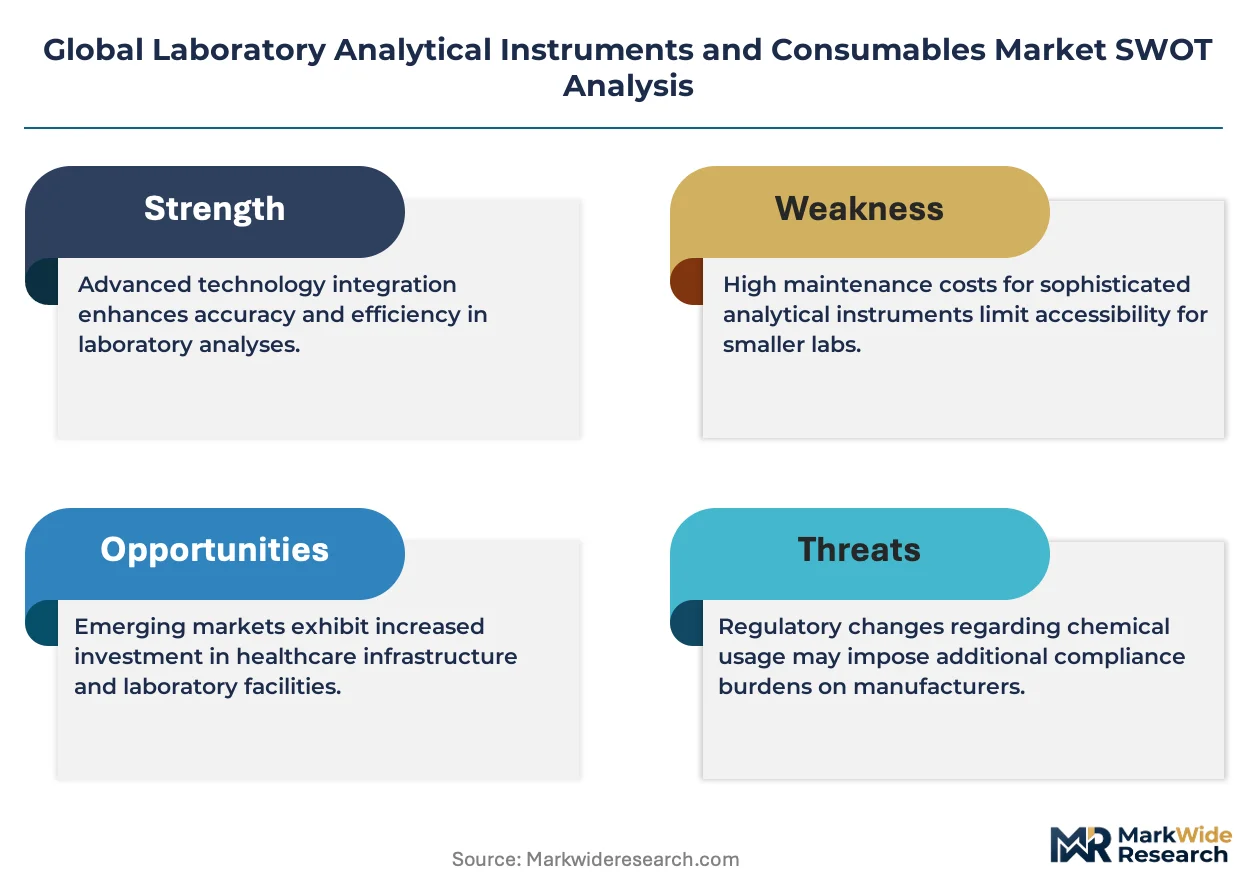
Regulatory data-integrity mandates from FDA, EMA, and PMDA are forcing pharmaceutical laboratories into accelerated instrument replacement cycles, compressing the traditional seven-year ownership horizon for chromatography and mass spectrometry platforms.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic record integrity requirements drive validation-ready instrument procurement across United States pharmaceutical quality control labs.
- Biopharma R&D clusters:Concentrated investment in monoclonal antibody and cell therapy development sustains demand for high-sensitivity mass spectrometry in Boston, San Francisco, and Basel.
- Consumables recurring revenue:Single-use chromatography columns and ionization sources generate predictable replacement demand that outpaces instrument sales volatility.
Market Restraints
- Helium supply concentration:United States Bureau of Land Management and Qatar helium reserves create input cost volatility for gas chromatography operations.
- High-field magnet scarcity:Superconducting niobium-titanium supply bottlenecks from Japanese and European foundries constrain NMR system production capacity.
- ISO/IEC 17025 accreditation timelines:Extended calibration traceability documentation requirements delay laboratory commissioning and revenue recognition.
Strategic Opportunities
- India CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Bengaluru seek qualified analytical instrumentation under CDSCO quality mandates.
- AI-enabled spectral interpretation:Machine learning algorithms for compound identification converge with cloud-based data management to reduce skilled analyst dependency.
- EU AI Act compliance engineering:Validated artificial intelligence modules for chromatographic peak integration create premium pricing tier for European pharmaceutical buyers.
Industry Challenges
- Mass spectrometry service engineering:Vacuum system and ion source maintenance expertise concentrates at OEM facilities, extending instrument downtime for remote laboratories.
- LIMS-CDS integration complexity:Chromatography data system connectivity with legacy laboratory information management systems requires costly custom validation protocols.
- Cross-platform method transfer:Analytical method migration between vendor ecosystems demands extensive equivalency studies under ICH Q2(R1) guidelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laboratory Analytical Instruments and Consumables Market |
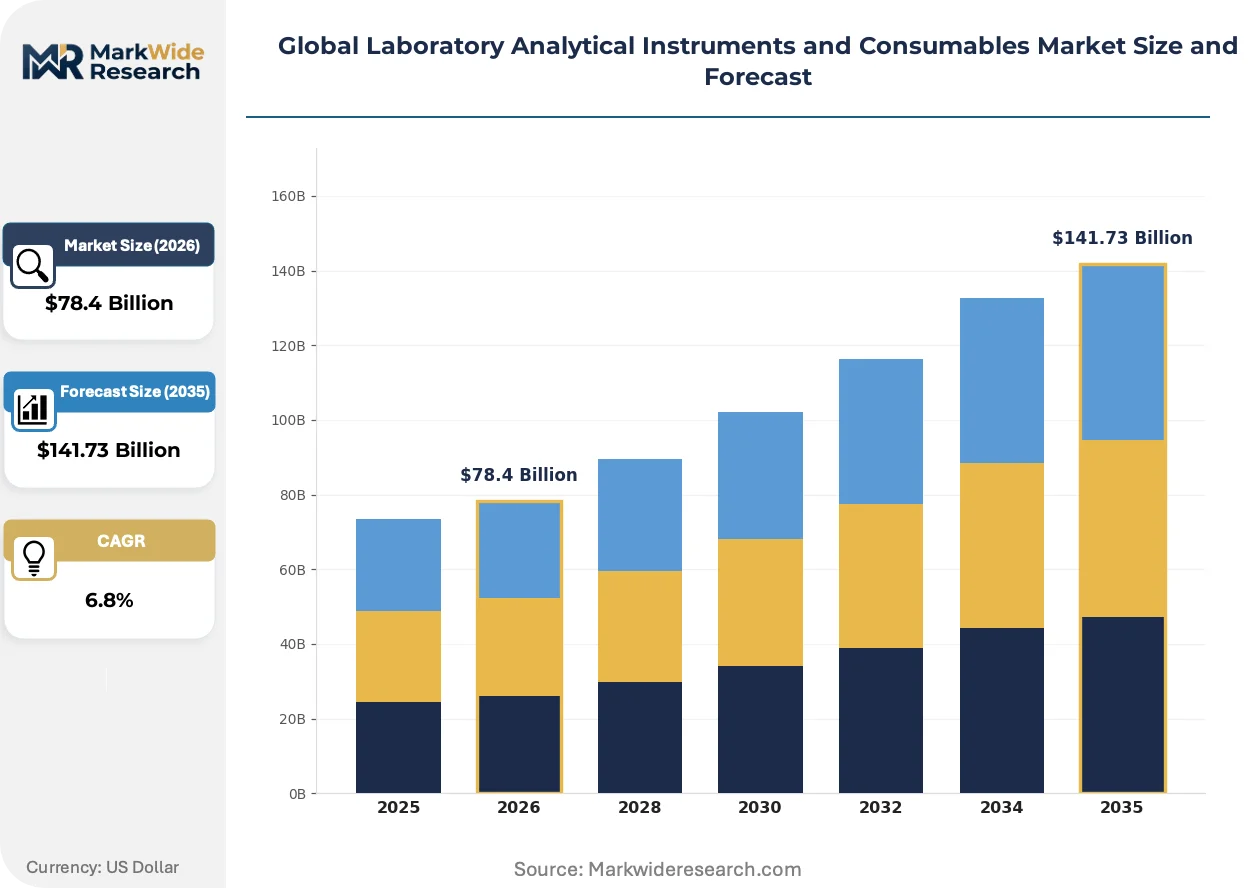
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromatographs, Spectrometers, Microscopes, Centrifuges, Consumables Kits Technology: Mass Spectrometry, Atomic Absorption, UV-Visible, NMR, Fluorescence Spectroscopy Application Area: Pharmaceutical Testing, Forensic Analysis, Food Quality, Environmental Testing, Chemical Synthesis End User: Research Institutions, Quality Control Labs, Government Agencies, Academic Labs, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies Inc., Danaher Corp., Shimadzu Corp., PerkinElmer US LLC, Waters Corp., Merck KGaA, Bruker Corp., Bio-Rad Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laboratory Analytical Instruments and Consumables Market Shifts & Advancements
Miniaturization and intelligence embedding are redrawing the boundary between centralized analytical laboratories and distributed testing nodes. Three developments merit particular attention.
Microfluidic sample preparation is decomposing the traditional chromatography workflow into modular, cartridge-based units. Environmental testing laboratories in Germany and the Netherlands are adopting these platforms for rapid field deployment. The technology is decomposing capital expenditure into consumable-per-test economics that favor decentralized regulatory monitoring networks.
EMA's updated GMP Annex 11 guidance on computerized systems intensifies software validation requirements for electronic batch records. Pharmaceutical manufacturers must demonstrate algorithmic transparency in chromatographic integration methods. European quality control departments are responding by demanding vendor-supplied validation documentation packages that accelerate regulatory inspection readiness.
Service contract unbundling is fragmenting the traditional instrument procurement model. Large pharmaceutical buyers in the United States now separate hardware acquisition from maintenance and software support, tendering each element to specialized providers. This pattern is most visible among top-20 biopharma companies seeking to optimize total cost of ownership across multi-vendor instrument fleets.
Global Laboratory Analytical Instruments and Consumables Market Segmentation
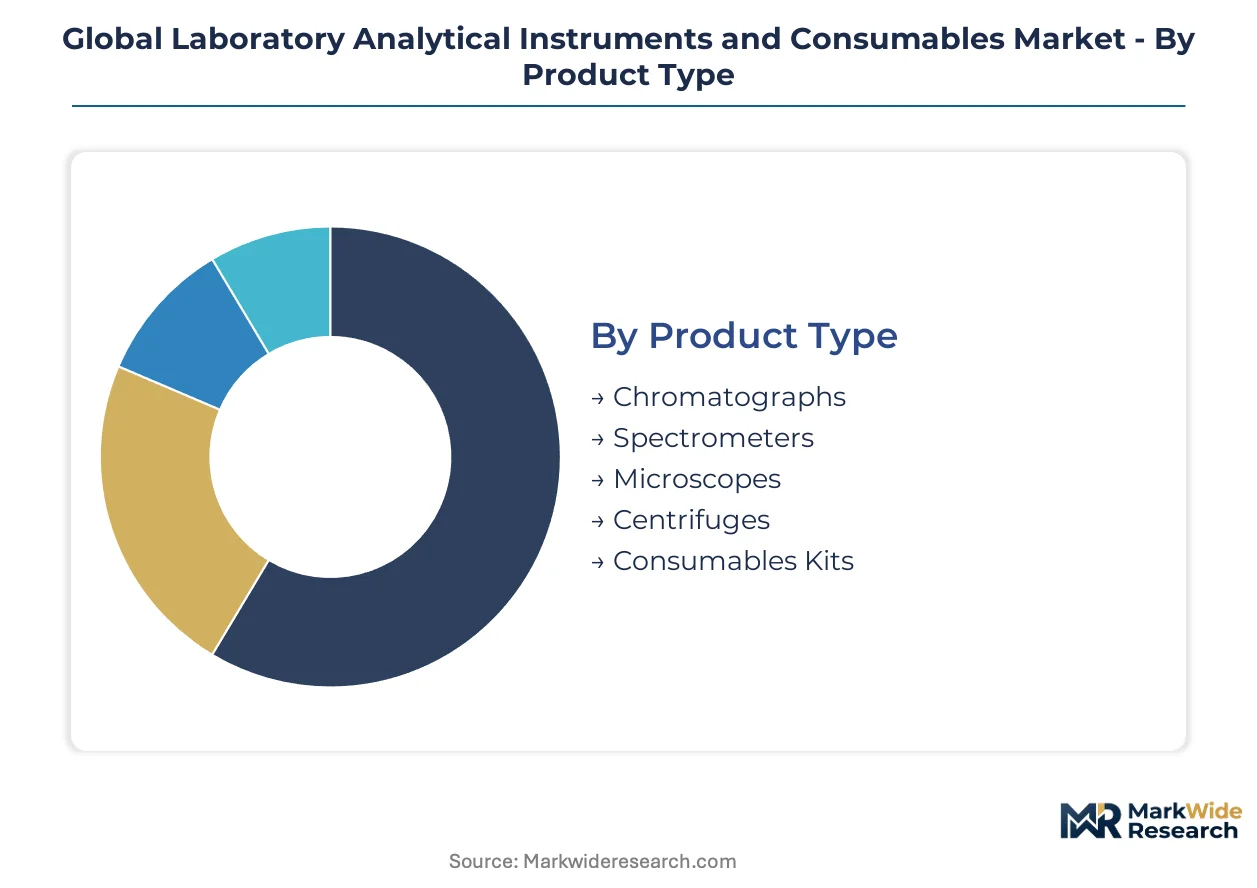
Segmentation reveals how procurement authority and workflow requirements fragment demand across the laboratory analytical instruments and consumables market. Understanding these divisions exposes which customer types prioritize capital expenditure versus recurring consumables spend, and which applications impose the strictest regulatory validation burdens.
Product Type:
Channel mix varies sharply by product economics: capital-intensive platforms deploy through direct OEM sales with embedded service contracts, while consumables flow through distribution partnerships and e-procurement portals.
- Chromatographs:Systems separate complex mixtures into individual components for quantitative analysis. HPLC and GC platforms dominate pharmaceutical quality control labs in Germany and the United States as FDA 21 CFR Part 11 and EMA GMP Annex 11 tighten electronic record requirements.
- Consumables Kits:Single-use columns, vials, and ionization sources generate recurring revenue streams that exceed initial instrument margins over ownership cycles. Demand concentrates at biopharma clusters in Boston and Basel where high-throughput screening drives replacement frequency.
- Spectrometers:Optical and infrared systems serve materials characterization and environmental compliance testing.
- Microscopes:Electron and confocal platforms anchor cell biology and nanomaterials research workflows.
- Centrifuges:Sample preparation equipment spans clinical diagnostics and industrial biotechnology applications.
By volume, consumables kits lead. By growth pace, chromatographs are climbing the fastest.
Technology:
Cost tier stratification separates premium detection platforms from benchtop workhorses, with superconducting magnet and vacuum system scarcity pushing high-field systems into extended lead times.
- Mass Spectrometry:Ionization and detection systems identify compounds at parts-per-billion sensitivity. Triple-quadrupole and Orbitrap configurations anchor proteomics and metabolomics workflows at research institutions in Cambridge, Massachusetts and Heidelberg.
- NMR:Nuclear magnetic resonance spectroscopy requires superconducting niobium-titanium magnets from Japanese and European foundries, constraining production capacity and extending delivery timelines for structural biology applications.
- UV-Visible:Workhorse spectrophotometers dominate routine quality control and teaching laboratories.
- Atomic Absorption:Elemental analysis systems serve environmental heavy metals testing and food safety screening.
- Fluorescence Spectroscopy:High-sensitivity detection platforms support molecular interaction studies and clinical immunoassays.
By installed base, UV-Visible systems dominate. By expansion trajectory, mass spectrometry is gaining share fastest.
Application Area:
Customer type determines validation intensity: pharmaceutical testing demands FDA-submittable documentation packages, while academic research tolerates configurable, unvalidated platforms.
- Pharmaceutical Testing:Regulatory compliance drives instrument procurement with embedded software validation and calibration traceability. Quality control departments at Merck KGaA in Darmstadt and Pfizer in Groton require vendor-supplied IQ/OQ/PQ documentation under ICH Q2(R1) guidelines.
- Environmental Testing:Field-deployable and portable formats displace centralized lab workflows for water and air quality monitoring. German and Dutch environmental agencies adopt microfluidic cartridge systems for rapid contaminant detection.
- Food Quality:Pesticide residue and authenticity testing sustains demand for chromatography-mass spectrometry hyphenated systems.
- Forensic Analysis:Toxicology and DNA identification applications require chain-of-custody documentation and validated methods.
- Chemical Synthesis:Reaction monitoring and purity verification support process development in agrochemical and specialty chemical sectors.
By revenue concentration, pharmaceutical testing leads. By deployment velocity, environmental testing is expanding most quickly.
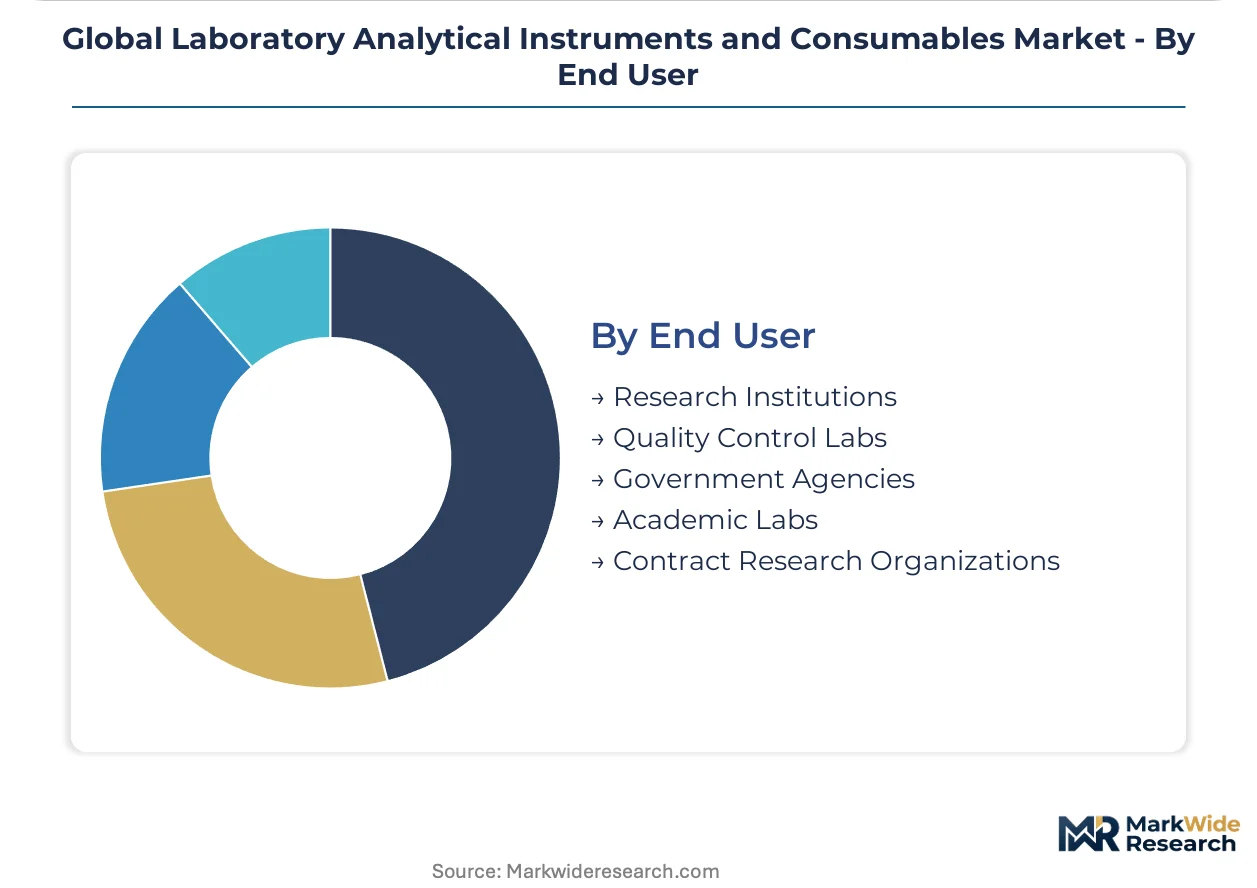
End User:
Procurement authority fragments across budget holders: research institutions optimize for technical specifications, while quality control labs prioritize regulatory compliance and total cost of ownership.
- Quality Control Labs:Pharmaceutical manufacturing quality units demand validated platforms with audit-ready documentation. FDA inspection readiness drives replacement cycles at Eli Lilly in Indianapolis and Roche in Basel.
- Contract Research Organizations:CDMOs in Hyderabad and Bengaluru seek qualified analytical instrumentation under CDSCO quality mandates to serve global pharmaceutical outsourcing contracts.
- Research Institutions:NIH-funded centers and Max Planck Institutes prioritize sensitivity and flexibility over regulatory validation.
- Academic Labs:Teaching and principal investigator grants sustain entry-level and refurbished instrument demand.
- Government Agencies:National metrology institutes and environmental regulators anchor reference standard development and proficiency testing.
By instrument value, quality control labs lead. By procurement volume growth, contract research organizations are ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instrument manufacturing concentrates among German precision engineering clusters, Japanese electronics corridors, and United States biopharma hubs, with each geography anchoring distinct technology tiers and regulatory compliance specializations.
United States
FDA 21 CFR Part 11 enforcement drives quality control labs at Pfizer in Groton and Eli Lilly in Indianapolis toward validated chromatography platforms with embedded electronic record systems. Boston and San Francisco biopharma clusters sustain demand for high-sensitivity mass spectrometry in monoclonal antibody development.
Germany
EMA GMP Annex 11 updates on computerized systems force Merck KGaA in Darmstadt and Roche in Basel-adjacent facilities to refresh instrument fleets with vendor-supplied validation documentation. Environmental testing laboratories in the Netherlands and Germany adopt microfluidic cartridge systems for rapid field contaminant detection.
China
NMPA data-integrity standards parallel to FDA requirements push pharmaceutical quality control departments in Shanghai and Suzhou toward imported platforms with localized compliance engineering. Government-funded research institutions in Beijing anchor replacement cycles for nuclear magnetic resonance systems despite superconducting magnet supply constraints.
Japan
PMDA tightening of drug approval submission requirements compiles pharmaceutical testing laboratories in Osaka and Tokyo to expand procurement of mass spectrometry and chromatography systems. METI-supported research programs sustain demand for advanced analytical platforms at national universities.
India
CDSCO quality mandates for contract development and manufacturing organizations drive analytical instrumentation procurement in Hyderabad and Bengaluru CDMO clusters. Global pharmaceutical outsourcing contracts require qualified platforms that satisfy both domestic regulators and FDA inspection readiness standards.
Global Laboratory Analytical Instruments and Consumables Market Competitive Landscape
Concentration sits with diversified life sciences conglomerates and precision instrumentation specialists. The vendor base stratifies across three tiers: full-platform providers with captive consumables revenue, technology-focused specialists in detection systems, and regional fabricators serving price-sensitive academic markets. Dominant competitive moves include diagnostics-to-research vertical integration and service contract unbundling that fragments traditional instrument procurement models.
Within the full-platform tier, Thermo Fisher Scientific Inc. and Danaher Corp. exemplify conglomerate structures spanning instruments through consumables. Agilent Technologies Inc. occupies a specialist position in mass spectrometry platforms for regulated pharmaceutical environments. Shimadzu Corp. anchors the Japanese precision instrumentation archetype with concentrated vacuum and optics engineering capabilities.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| Danaher Corp. |
| Shimadzu Corp. |
| PerkinElmer US LLC |
| Waters Corp. |
| Merck KGaA |
| Bruker Corp. |
| Bio-Rad Laboratories Inc. |
| Others |
Supply & Pricing Matrix
Ninety-to-120-day lead times for superconducting niobium-titanium magnets from Japanese and European foundries concentrate pricing power with upstream material suppliers, while downstream instrument manufacturers pass scarcity premiums through to pharmaceutical quality control labs in Germany and the United States.
Pricing Analysis
FDA 21 CFR Part 11 dictates the pricing tier structure across validation-ready chromatography and mass spectrometry platforms. Three-tier pricing structure across premium, standard, and economy levels separates FDA-submittable documentation packages from configurable research-grade systems. Cost compression in the economy tier is intensifying because academic buyers in India and Brazil face funding constraints. Contract research organizations in Hyderabad exhibit highest price sensitivity, while quality control labs at Merck KGaA and Roche prioritize compliance over unit cost.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for vacuum system components arriving from Japanese precision engineering clusters. Manufacturing concentrates in Germany, Japan, and the United States, with superconducting magnet production drawing from niobium-titanium foundries in Japan and niobium mining operations in Brazil. Single-source vulnerability sits with helium refining capacity concentrated at the United States Bureau of Land Management and Qatar reserves. Distribution runs through direct OEM sales for capital platforms and e-procurement portals for consumables kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laboratory analytical instruments market functions as a defensive-moat story where regulatory entrenchment creates switching costs that lock pharmaceutical buyers into validated vendor ecosystems for seven-to-ten-year ownership cycles.
For Market Incumbents: Secure captive consumables revenue through proprietary column chemistries and ionization source designs that tether pharmaceutical customers to recurring replacement schedules. Deepen backward integration into superconducting magnet supply through long-term offtake agreements with Japanese foundries, insulating production capacity from emerging entrant price aggression.
For New Entrants and Emerging Players: Differentiate on AI-enabled spectral interpretation modules that reduce skilled analyst dependency for environmental testing laboratories in Germany and the Netherlands. Target microfluidic cartridge systems for field-deployable contaminant detection where regulatory validation requirements remain less stringent than pharmaceutical quality control.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue compounding play because consumables kits generate predictable replacement demand that outpaces instrument sales volatility. Focus acquisition screening on specialized mass spectrometry software developers with validated chromatographic peak integration algorithms. Monitor FDA guidance documents on AI-enabled analytical software as the critical inflection signal for platform refresh timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Consumables Revenue Capture | Proprietary column chemistries lock pharmaceutical customers into recurring replacement schedules at Thermo Fisher and Waters. |
| AI Module Validation | FDA-submittable spectral interpretation algorithms create premium pricing tier for European buyers under EU AI Act compliance requirements. |
| Magnet Supply Securement | Long-term niobium-titanium offtake agreements with Japanese foundries insulate NMR production from input cost volatility. |
| CDMO Market Entry | Qualified instrumentation platforms for Hyderabad and Bengaluru contract manufacturers satisfy CDSCO and FDA dual-mandate inspection readiness. |
| Service Contract Unbundling | Separate hardware, maintenance, and software support tenders optimize total cost of ownership for top-20 biopharma multi-vendor fleets. |
Research Methodology
Operator-level perspectives from quality control lab managers, regulatory affairs specialists at pharmaceutical manufacturers, chromatography data system engineers, and aftermarket service technicians anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 483 inspection observations, EMA GMP inspection deficiency databases, ISO/IEC 17025 accreditation body reports, and instrument procurement records from NIH-funded research centers. Bottom-up demand modeling from individual laboratory replacement cycles triangulated against top-down market sizing from OEM revenue disclosures.
Sensitivity analysis tested forecast robustness across helium price volatility scenarios, superconducting magnet delivery timeline variations, and regulatory inspection intensity assumptions. Segmentation dimensions spanned product type, detection technology, application area, end-user procurement authority, and regional regulatory cluster. CAGRs derived from instrument replacement cycle compression rates and consumables attach ratios across the projection horizon. Industry-specific inputs included pharmaceutical pipeline stage distributions and environmental monitoring network expansion commitments.
Material uncertainties — regulatory AI guidance revisions, helium reserve privatization policy shifts, and superconducting material substitution breakthroughs — sit outside the modeled envelope. Forecasts reflect documented assumptions about inspection readiness-driven replacement urgency and consumables pricing power persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Microplastics Particle Size and Shape Characterization Systems Market
Testing Equipment
Paper Tester Market
Testing Equipment
Global Lab Supplies Market
Testing Equipment
Chemisorption Analyzer Market
Testing Equipment
Wood Moisture Tester Market
Testing Equipment
Particle Size Analysis Market
Testing Equipment
Chemical Reaction Monitoring Equipment Market
Testing Equipment
Durability Testing Systems Market
Testing Equipment
Benchtop Density Meter for Solids Market
Testing Equipment
Global Liquid Process Analyzer Market
Testing Equipment
Water Penetration Tester Market
Testing Equipment
Americas Testing, Inspection and Certification (TIC) Market
Testing Equipment
Water Analysis Instruments Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Nitrogen Tester Market
Testing Equipment
Cyclic Corrosion Test Chamber Market