
 PFAS Ultra-Trace Water Analysis Test Instruments Market | 2026-2036
PFAS Ultra-Trace Water Analysis Test Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
PFAS Ultra-Trace Water Analysis Test Instruments Market Insights
Asset-light leasing and performance-based service contracts are reshaping competitive dynamics in PFAS instrumentation, lowering capital barriers for mid-sized laboratories. Waters Corporation leverages its installed base of chromatography systems to anchor recurring revenue through consumables and service agreements. Agilent Technologies competes by extending its LC-MS portfolio into compact footprints suited for decentralized water quality monitoring. PerkinElmer differentiates through specialized application workflows that reduce method development time for emerging PFAS chemistries.
PFAS ultra-trace water analysis test instruments detect per- and polyfluoroalkyl substances at concentrations below ten nanograms per liter using tandem mass spectrometry coupled with solid-phase extraction. These systems serve regulatory compliance, environmental remediation, and public health protection by quantifying persistent fluorinated compounds in potable and environmental water matrices. Mass spectrometers command the dominant share of product value due to their unmatched selectivity for complex PFAS homolog identification. Tandem mass spectrometry leads technology adoption as laboratories standardize on EPA Method 1633 and analogous multi-analyte protocols.
The EPA Office of Water enforces progressively lower maximum contaminant levels under the Safe Drinking Water Act, directly mandating instrument sensitivity upgrades across certified laboratories. ISO 21675 and EPA Method 1633 establish analytical performance benchmarks that determine product qualification for regulatory reporting. State-level enforcement variations in California, Michigan, and North Carolina create fragmented procurement requirements that manufacturers must navigate. Stakeholders should monitor emerging state-level PFAS legislation and corresponding method updates to anticipate replacement cycles and certification investments.
Market Dynamics
EPA Method 1633 implementation is compressing instrument replacement cycles as certified laboratories race to achieve sub-ten-parts-per-trillion detection thresholds before enforcement deadlines. The regulatory ratchet is forcing capital redeployment from legacy single-quadrupole systems toward tandem mass spectrometry platforms with solid-phase extraction front ends.
Growth Catalysts
- EPA Safe Drinking Water Act enforcement:Maximum contaminant level reductions mandate sensitivity upgrades across municipal water utilities in the United States, accelerating instrument procurement timelines.
- Tandem mass spectrometry standardization:ISO 21675 adoption in Germany, Japan, and Australia creates harmonized qualification pathways that reduce vendor certification friction.
- Environmental remediation liability:Industrial site operators in Michigan and North Carolina face state-level PFAS cleanup mandates that expand third-party testing demand.
Market Restraints
- Helium supply volatility:Mass spectrometer consumables depend on concentrated extraction from natural gas fields in Qatar and the United States, creating input cost unpredictability.
- Technical detection floor:Current solid-phase extraction workflows struggle with short-chain PFAS recovery below five parts per trillion, limiting regulatory compliance scope.
- Regulatory fragmentation:California's unique notification thresholds diverge from federal EPA standards, forcing manufacturers to maintain parallel certification tracks.
Strategic Opportunities
- Decentralized monitoring networks:Compact LC-MS footprints enable deployment at wastewater treatment plants in Australia bypassing centralized laboratory bottlenecks.
- EU Green Deal alignment:ECHA restriction proposals on PFAS manufacture create downstream testing mandates for imported goods entering European ports.
- Artificial intelligence integration:Machine learning algorithms are hybridizing with chromatographic data processing to automate peak identification in complex water matrices.
Industry Challenges
- Mass spectrometry operator scarcity:Tandem LC-MS method development requires specialized analytical chemistry expertise that outpaces university training pipeline output.
- Legacy system integration:Laboratory information management systems at municipal utilities resist seamless data export to new EPA-compliant reporting formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PFAS Ultra-Trace Water Analysis Test Instruments Market |
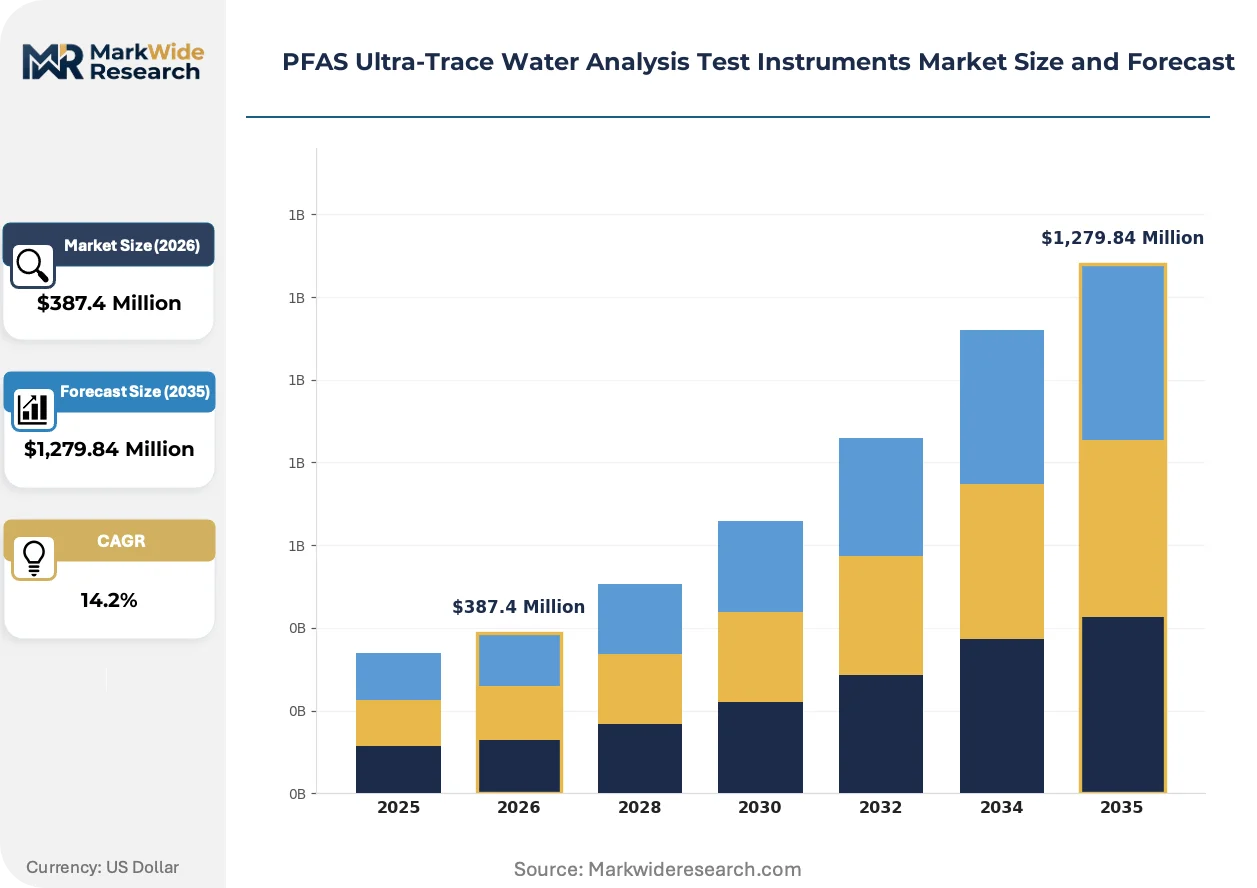
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $1,279.84 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mass Spectrometers, Chromatographs, Spectrophotometers, Sensors, Electrochemical Analyzers Technology: Liquid Chromatography, Gas Chromatography, Tandem Mass Spectrometry, Ion Mobility Spectrometry, Capillary Electrophoresis Application: Environmental Monitoring, Industrial Effluent Testing, Drinking Water Quality, Wastewater Treatment, Research Laboratories End User: Water Treatment Facilities, Analytical Laboratories, Regulatory Agencies, Academic Institutions, Private Testing Firms |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Waters Corporation, SCIEX, Shimadzu Corporation, Bruker, PerkinElmer, JEOL, Hitachi High-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PFAS Ultra-Trace Water Analysis Test Instruments Market Trends and Innovations
Instrumentation architecture is converging around modular platforms that separate sample preparation from detection, enabling field-deployable configurations that challenge centralized laboratory dominance. This structural shift is compressing the traditional value chain while opening new service revenue models.
Triple-quadrupole mass spectrometry is hybridizing with automated solid-phase extraction to reduce manual sample handling in high-throughput environmental laboratories. Municipal utilities in the United States are adopting these integrated workflows to meet EPA Method 1633 throughput requirements. The technology is compressing per-sample analysis costs while raising capital barriers for smaller testing facilities.
ECHA's proposed PFAS restriction under REACH is forcing industrial chemical manufacturers to establish comprehensive environmental monitoring programs across European manufacturing sites. The regulation mandates supply-chain-wide contamination assessment that extends testing demand upstream from wastewater discharge points. German industrial laboratories are responding by expanding LC-MS capacity ahead of anticipated enforcement timelines.
Performance-based service contracts are displacing outright instrument purchases among mid-sized environmental testing firms in Australia and Japan. Leasing structures bundle maintenance, consumables, and method validation into predictable operational expenditures. This procurement evolution is most visible in the Asia-Pacific region where capital constraints meet tightening regulatory deadlines.
PFAS Ultra-Trace Water Analysis Test Instruments Market Segmentation
Segmentation in PFAS instrumentation reveals divergent service intensity and capital commitment profiles across customer types. Laboratories running EPA Method 1633 demand continuous calibration support and consumable replenishment that reshape vendor economics. Understanding these structural differences enables targeted positioning for recurring revenue capture versus one-time equipment sales.
Product Type:
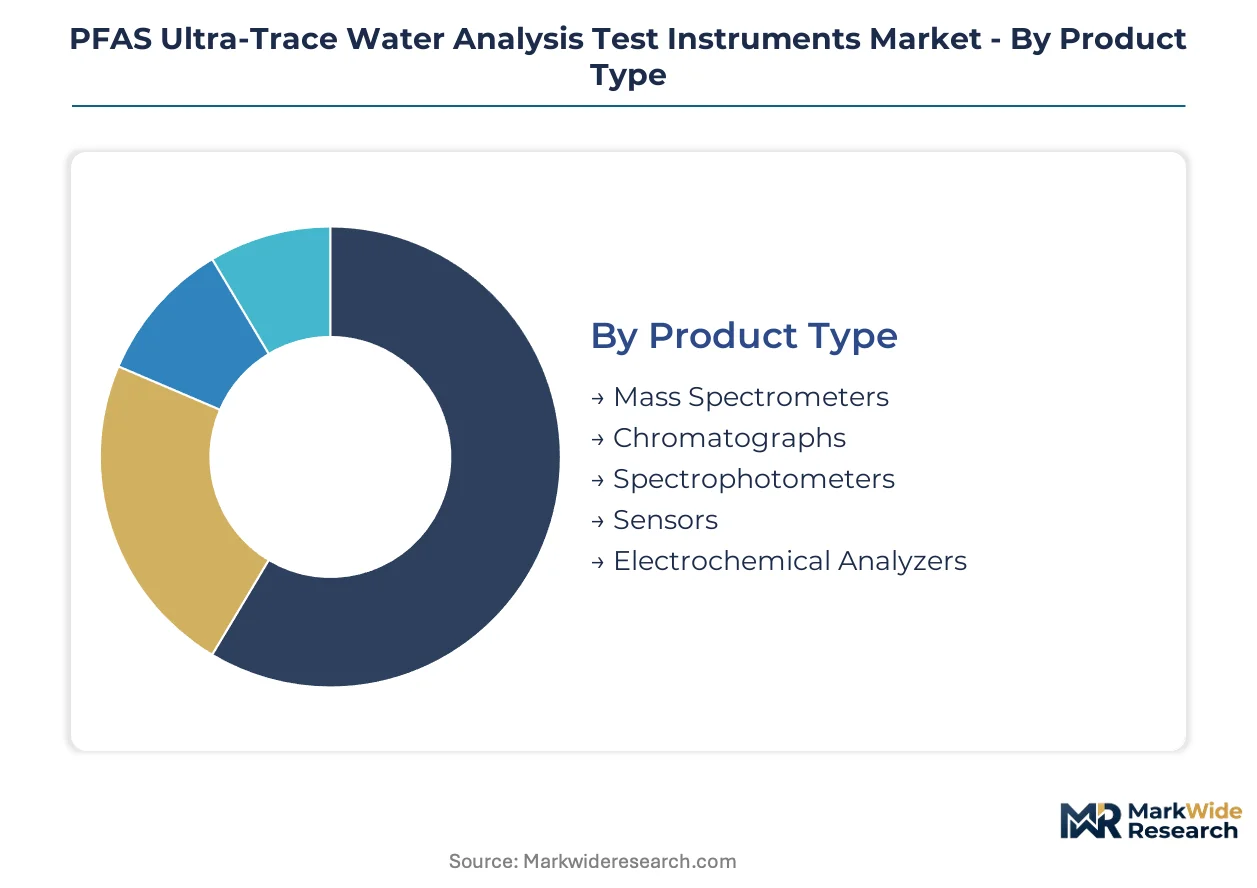
After-sales service intensity varies dramatically across instrument categories, with mass spectrometry platforms generating three to five times the annual service contract value of electrochemical alternatives.
- Mass Spectrometers:Triple-quadrupole and high-resolution platforms dominate regulatory compliance workflows through unmatched selectivity for PFAS homolog identification. Municipal utilities in the United States concentrate procurement here as EPA maximum contaminant level enforcement tightens detection requirements. Service contracts typically exceed fifteen percent of instrument value annually.
- Chromatographs:Liquid chromatography systems serve as front-end separation engines paired with mass spectrometry detection in integrated workflows. Demand clusters at environmental remediation sites in Michigan and North Carolina where state-level cleanup mandates expand third-party testing capacity. These systems require less intensive field service than mass spectrometry platforms.
- Spectrophotometers:UV-Vis and fluorescence instruments support screening applications at water treatment facilities with moderate sensitivity requirements.
- Sensors:Field-deployable electrochemical and optical sensors enable continuous monitoring at wastewater treatment plant outfalls in Australia.
- Electrochemical Analyzers:Portable voltammetric systems serve rapid on-site assessment needs with minimal maintenance overhead.
By volume, sensors lead deployment counts. By growth pace, mass spectrometry platforms are expanding most quickly.
Technology:
Technology selection directly determines capital expenditure tiers and operator skill requirements, with tandem mass spectrometry commanding premium positioning against chromatographic alternatives.
- Tandem Mass Spectrometry:LC-MS/MS platforms deliver sub-ten-parts-per-trillion detection thresholds mandated by EPA Method 1633 and ISO 21675. German industrial laboratories are standardizing on these systems ahead of ECHA restriction proposal enforcement. Method development complexity sustains high-margin service agreements.
- Liquid Chromatography:HPLC and UHPLC systems separate PFAS mixtures prior to detection, serving both standalone screening and coupled mass spectrometry workflows. Academic institutions in Japan deploy these for emerging PFAS chemistry research with moderate throughput demands. Lower capital barriers support broader laboratory adoption.
- Gas Chromatography:GC methods address volatile fluorinated compound fractions in industrial effluent matrices.
- Ion Mobility Spectrometry:IMS platforms enable rapid field screening with reduced sample preparation at decentralized monitoring stations.
- Capillary Electrophoresis:CE separations serve specialized research applications requiring extreme resolution of PFAS structural isomers.
Tandem mass spectrometry captures the dominant revenue share. Ion mobility spectrometry is gaining share fastest through portability advantages.
Application:
Application context shapes procurement urgency and budget source, with regulatory compliance mandates driving faster replacement cycles than discretionary research spending.
- Drinking Water Quality:Municipal utilities face direct EPA Safe Drinking Water Act enforcement with hard deadlines for sensitivity upgrades. California's unique notification thresholds create additional certification complexity beyond federal standards. Capital budgets here prioritize proven regulatory acceptance over experimental technology.
- Environmental Monitoring:Surface water and groundwater assessment programs expand across industrial corridors with legacy contamination. Site operators in North Carolina face state-level liability frameworks that accelerate third-party testing procurement. Contract laboratories serving this segment emphasize rapid turnaround over absolute detection limits.
- Industrial Effluent Testing:Manufacturing discharge monitoring grows under tightening permit conditions at European and Asia-Pacific facilities.
- Wastewater Treatment:Plant operators deploy in-process analyzers to optimize treatment efficiency and demonstrate compliance.
- Research Laboratories:Academic and government research programs explore emerging PFAS chemistries and fate-and-transport behavior with flexible funding timelines.
Drinking water quality commands the largest absolute spending. Environmental monitoring shows the steepest expansion trajectory.
End User:
End-user category determines purchasing authority structure and total cost of ownership sensitivity, with regulatory agencies imposing qualification standards that cascade through commercial laboratories.
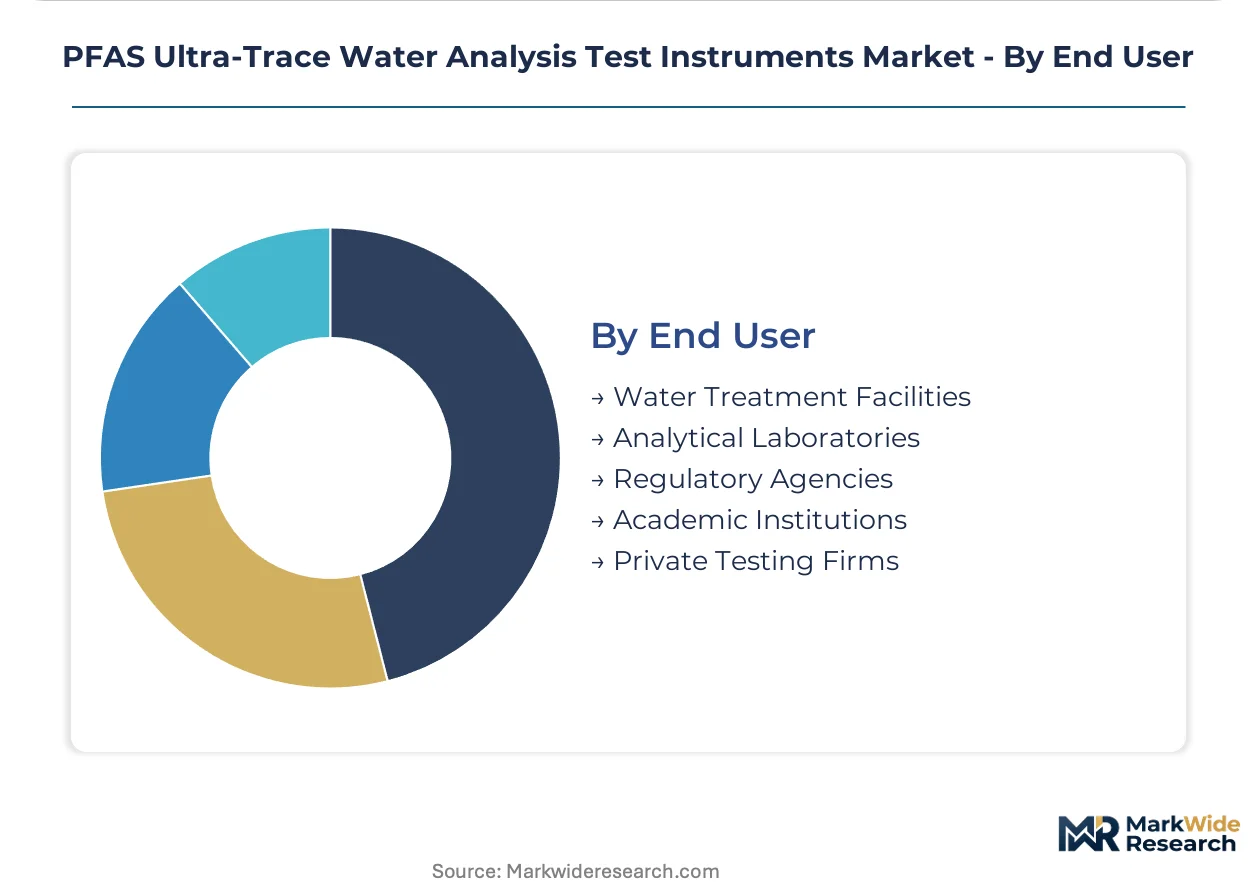
- Analytical Laboratories:Commercial testing firms serve multiple client categories with ISO 17025 accreditation requirements driving instrument selection. Mid-sized environmental laboratories in Australia are shifting toward performance-based service contracts to reduce capital barriers. These customers prioritize throughput optimization and multi-analyte protocol flexibility.
- Water Treatment Facilities:Municipal utilities operate with public procurement rules and fixed capital cycles that favor established vendor relationships. United States facilities are replacing legacy single-quadrupole systems under EPA enforcement pressure. In-house analytical capacity decisions balance against third-party laboratory outsourcing economics.
- Regulatory Agencies:Government reference laboratories set certification standards and conduct enforcement sampling with method development responsibilities.
- Academic Institutions:University research programs pursue emerging PFAS chemistry with grant-funded instrument acquisitions and graduate student labor.
- Private Testing Firms:Specialized consultancies serve industrial site operators with rapid response and litigation support capabilities.
Analytical laboratories represent the largest installed base. Water treatment facilities are climbing the fastest as municipal compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in analytical instrumentation reveal concentrated manufacturing in Germany, the United States, and Japan, while Australia and emerging Asian laboratories drive import demand for sub-ten-parts-per-trillion detection capability.
United States
Municipal water utilities across Michigan and North Carolina are accelerating capital redeployment toward tandem mass spectrometry platforms. The EPA Office of Water enforces progressively lower maximum contaminant levels under the Safe Drinking Water Act, compressing instrument replacement cycles. Industrial site operators in these states face state-level cleanup mandates that expand third-party testing demand beyond federal baselines.
Germany
Industrial laboratories are standardizing on LC-MS/MS systems ahead of anticipated ECHA restriction proposal enforcement under REACH. The country's national chemical regulator is mandating supply-chain-wide contamination assessment that extends testing demand upstream from wastewater discharge points. Manufacturing clusters in Bavaria and North Rhine-Westphalia are responding by expanding analytical capacity ahead of compliance deadlines.
Japan
Academic institutions deploy liquid chromatography systems for emerging PFAS chemistry research with moderate throughput demands. METI guidelines on environmental monitoring are harmonizing with ISO 21675 adoption to create qualification pathways that reduce vendor certification friction. Research corridors in Kanto and Kansai regions prioritize method development for novel fluorinated compound identification.
Australia
Mid-sized environmental laboratories are shifting toward performance-based service contracts to reduce capital barriers. TGA-aligned water quality standards are tightening detection requirements for wastewater treatment plant operators. Queensland and New South Wales facilities are deploying compact LC-MS footprints at decentralized monitoring stations to bypass centralized laboratory bottlenecks.
Canada
Health Canada reference laboratories are setting certification standards for PFAS analysis in potable water matrices. The country's national environmental regulator is conducting enforcement sampling with method development responsibilities that cascade through commercial laboratories. Ontario and British Columbia water authorities are replacing legacy single-quadrupole systems under federal enforcement pressure.
PFAS Ultra-Trace Water Analysis Test Instruments Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform providers that bundle sample preparation with detection hardware. Chromatography specialists and mass spectrometry pure-plays occupy distinct tier positions based on recurring revenue intensity. Three strategic archetypes dominate: full-stack analytical platform vendors, consumables-centric service integrators, and compact footprint specialists targeting decentralized deployment. Competitive moves center on strategic partnerships for method validation bundling and vertical integration into solid-phase extraction consumables.
Among United States-based platform vendors, Thermo Fisher Scientific and Agilent Technologies exemplify the full-stack archetype through chromatography-mass spectrometry integration. Waters Corporation occupies a position within the consumables-centric tier, leveraging installed base anchoring for recurring revenue capture. These three companies represent divergent responses to the shift toward performance-based service contracts and asset-light leasing structures reshaping procurement patterns across municipal utilities and mid-sized environmental laboratories.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Waters Corporation |
| SCIEX |
| Shimadzu Corporation |
| Bruker |
| PerkinElmer |
| JEOL |
| Hitachi High-Tech |
| Others |
Pricing and Supply Chain Analysis
Bavarian manufacturing clusters anchor precision engineering capacity for mass spectrometry ion source components, concentrating supply-side leverage among German and Japanese detector module suppliers. This geographic concentration amplifies pricing power for triple-quadrupole subassemblies while compressing margins for downstream system integrators competing on EPA Method 1633 certification bundles.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that bundle consumables, calibration support, and method validation into predictable operational expenditures. Price differentiation rests on certification grade—EPA 1633-qualified platforms command substantial premiums over ISO 21675-aligned alternatives—and after-sales service intensity. Cost compression in mid-tier chromatography systems is intensifying because Australian and Japanese laboratories are shifting toward performance-based leasing. Municipal utilities in the United States show lowest price sensitivity due to federal enforcement deadlines, while mid-sized environmental testing firms in Australia exhibit highest sensitivity to capital outlay structures.
Supply Chain Analysis
Export-control restrictions on high-resolution mass spectrometry components limit technology flows from United States and German manufacturing hubs to certain end-user categories. Geographic supply concentrates in Germany, the United States, and Japan for precision ion optics and detector assemblies, with helium gas extraction from Qatar and United States natural gas fields feeding plasma source consumables. Supply chain risk centers on single-source vulnerability for superconducting magnet wire in high-resolution platforms. Distribution runs through authorized service integrators that bundle installation qualification with regulatory certification support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as EPA enforcement deadlines force capital redeployment from legacy single-quadrupole systems toward tandem mass spectrometry platforms.
For Market Incumbents: Insulate recurring revenue streams by deepening captive supply of solid-phase extraction consumables and calibration reference standards. Lock in municipal utility replacement cycles through multi-year service contracts that bundle EPA 1633 method validation. Defend against compact LC-MS entrants by accelerating field-deployable configurations for decentralized Australian monitoring networks.
For New Entrants and Emerging Players: Southeast Asian industrial corridors present underpenetrated demand for third-party PFAS testing services as ECHA-aligned import screening tightens at European ports. Target mid-sized Australian environmental laboratories with asset-light leasing structures that bypass capital budget constraints. Lead with AI-augmented data processing to differentiate peak identification capabilities in complex water matrices.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because persistent EPA maximum contaminant level ratchets create non-discretionary replacement demand regardless of macroeconomic conditions. Prioritize acquisition targets with installed base anchoring in United States municipal utilities and proprietary consumables portfolios. Monitor ECHA restriction proposal enforcement timelines as the key inflection signal for European capacity expansion decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Consumables Portfolio Expansion | Captures recurring revenue from EPA 1633 calibration standards and SPE cartridge replenishment cycles. |
| Field-Deployable LC-MS Miniaturization | Enables Queensland wastewater plants to bypass centralized laboratory bottlenecks under TGA-aligned standards. |
| AI-Augmented Peak Identification | Reduces operator dependency for tandem mass spectrometry method development in Japanese academic laboratories. |
| Performance-Based Service Contract Rollout | Converts Australian mid-sized environmental firms from capital expenditure to operational expenditure procurement. |
| Regulatory Certification Pre-Positioning | Secures EPA and ISO 21675 qualification ahead of Michigan and North Carolina state-level enforcement deadlines. |
Research Methodology
Desk research of EPA enforcement guidance documents, ISO 21675 technical specifications, and ECHA restriction proposal drafts preceded structured interviews with analytical laboratory directors, municipal utility procurement officers, mass spectrometry service engineers, and environmental remediation project managers. Secondary validation drew from customs trade data for chromatography system imports, SEC 10-K instrument revenue disclosures, and Health Canada reference method publications. Bottom-up instrument shipment estimates triangulated against top-down spending projections from municipal capital budget disclosures.
The analytical framework held EPA maximum contaminant level enforcement timelines fixed while varying state-level notification threshold adoption rates across California, Michigan, and North Carolina. Segmentation modeling spanned product type, technology platform, application context, and end-user purchasing authority structure. CAGRs were derived from instrument replacement cycle compression analysis and consumables attach-rate trajectories. Helium supply volatility and short-chain PFAS recovery limitations were incorporated as scenario-weighted demand modifiers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by compact LC-MS specialists or AI-native data processing entrants would shift outcomes. Material shifts in EPA enforcement deferrals, ECHA restriction proposal scope, or helium supply nationalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market
Testing Equipment
Global Chiral Chromatography Column Market
Testing Equipment
Hydrogen Gas Analyzers Market
Testing Equipment
Fugitive Emissions Detection and Quantification Test Systems Market
Testing Equipment
Rubber Testing Equipment Market
Testing Equipment
US Eddy-Current Testing Market
Testing Equipment
Paper Moisture Meter Market
Testing Equipment
Gas Chromatography Columns Market
Testing Equipment
Clean-Up Gel Permeation Chromatography Market
Testing Equipment
North America Dissolved Gas Analyzer Market
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
Global Adsorption Equipment Market
Testing Equipment
Global Insulation Testers Market
Testing Equipment
Viscometer Market
Testing Equipment
Analytical Gel Permeation Chromatography Market
Testing Equipment
Digital Shore Durometer Market