
 Global Liquid Chromatography Instruments Market | 2026-2036
Global Liquid Chromatography Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liquid Chromatography Instruments Market Foresight
The capital-intensity gap between mass-market vendors and precision-focused specialists is collapsing as modular detector architectures lower entry barriers. Agilent Technologies leverages its ion mobility quadrupole platforms to sustain premium positioning in biopharma method development. Waters Corporation anchors North American demand through its ACQUITY UPLC ecosystem, while Thermo Fisher Scientific competes on consumables bundling and service contracts.
Liquid chromatography instruments separate dissolved mixtures via stationary-phase columns under pressurized solvent flow, with typical systems operating at 6,000–15,000 psi for UPLC configurations and 1,000–6,000 psi for conventional HPLC. These instruments quantify molecular identity and purity across drug development, food contaminant screening, and environmental pollutant detection workflows. High-performance liquid chromatography occupies the largest installed base due to decades of validated pharmacopeial methods, though ultra-performance liquid chromatography segments attract the fastest replacement demand as labs seek reduced solvent consumption and higher throughput. Gradient technology leads in complex sample profiling applications where mobile-phase composition shifts during elution, while preparative chromatography commands disproportionate margin pools through specialized column packing and scale-up consulting services.
FDA bioanalytical method validation guidelines, EMA ICH Q2(R1) revisions, and China's NMPA pharmacopeia updates collectively tighten quantification thresholds and force instrument recertification. These frameworks shape demand by mandating enhanced sensitivity specifications and traceable calibration protocols that obsolete legacy systems. Stakeholders must monitor evolving regulatory divergence between jurisdictions to anticipate which detector configurations and software validation packages will unlock market access.
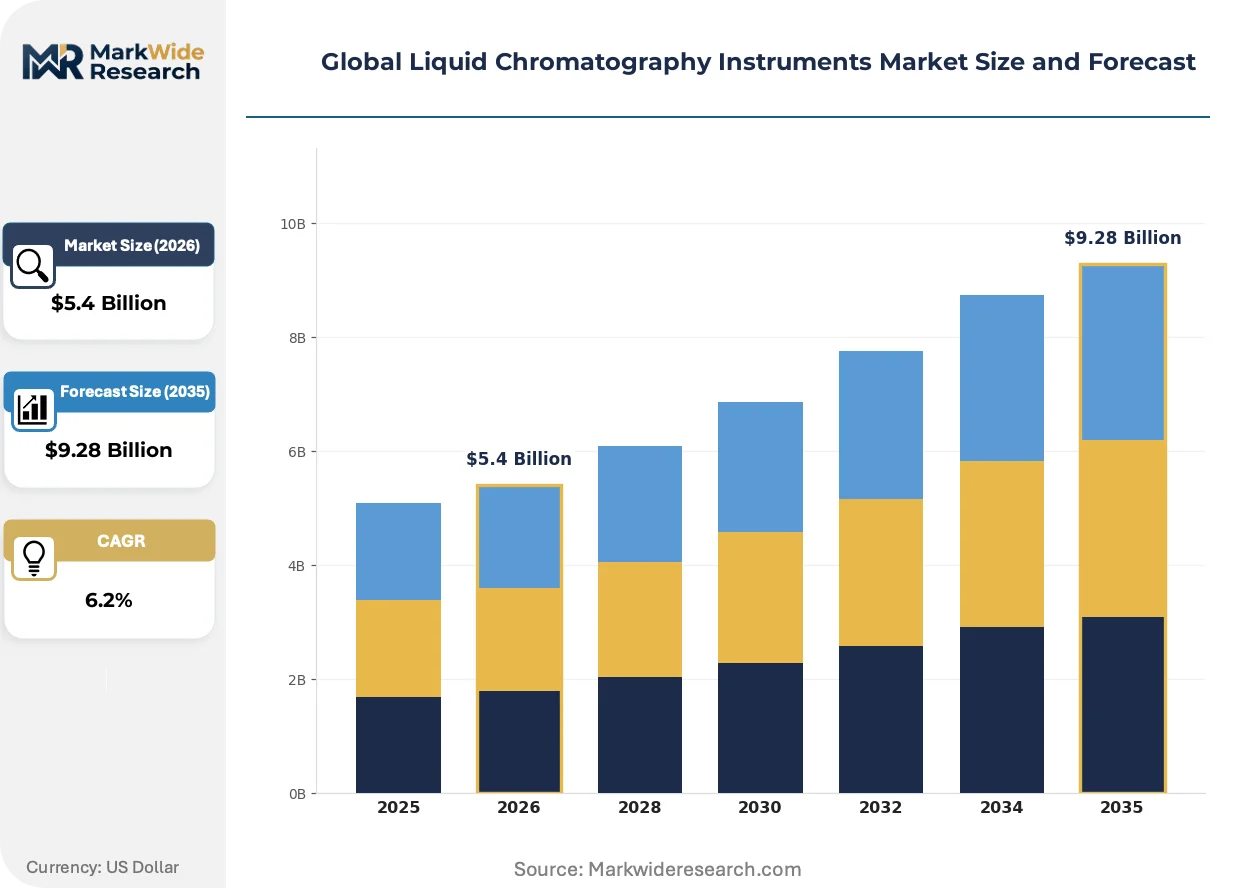
Market Dynamics
Modular detector architectures are collapsing the capital-intensity gap between mass-market vendors and precision-focused specialists, forcing incumbents to defend premium positioning through software ecosystems and consumables lock-in rather than hardware differentiation alone.
Growth Catalysts
- FDA Bioanalytical Method Validation Guidelines:Tightening detection thresholds for monoclonal antibody characterization are compressing replacement cycles as labs recertify systems to meet enhanced sensitivity specifications.
- Biopharma R&D Concentration:The United States, Germany, and China host the largest pharmaceutical development footprints, concentrating procurement of ultra-performance systems in these three markets.
- Solvent Consumption Reduction:UPLC configurations operating at 6,000–15,000 psi deliver higher throughput with reduced mobile-phase volumes, driving upgrade demand from legacy HPLC installations.
Market Restraints
- Helium Supply Volatility:Chromatography-grade helium shortages and price spikes constrain gas-dependent detection methods, particularly affecting mass spectrometry coupling configurations.
- Column Packing Concentration:Specialized stationary-phase manufacturing concentrates among a handful of European and Japanese suppliers, creating input bottlenecks for preparative chromatography scale-up.
- Legacy Method Inertia:Decades of validated pharmacopeial methods lock installed HPLC bases into extended depreciation cycles, delaying UPLC conversion in quality control environments.
Strategic Opportunities
- India CDMO Expansion:Contract development and manufacturing organizations in India are building analytical capabilities to serve export markets, creating greenfield instrument demand outside established pharma clusters.
- Continuous Manufacturing Integration:Process analytical technology mandates from FDA and EMA are driving real-time chromatography deployment at production scale rather than offline testing.
- AI-Assisted Method Development:Machine learning algorithms for gradient optimization and peak identification are converging with hardware platforms, enabling differentiated software-subscription revenue streams.
Industry Challenges
- Metrology Talent Scarcity:Qualified technicians for traceable calibration protocol execution remain scarce in emerging biopharma clusters, extending installation and qualification timelines.
- Multi-Vendor Integration Complexity:Labs running mixed fleets of Agilent, Waters, and Thermo Fisher systems face data architecture fragmentation that complicates enterprise-wide compliance reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liquid Chromatography Instruments Market |
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Performance Liquid Chromatography, Ultra-Performance Liquid Chromatography, Ion Chromatography, Affinity Chromatography, Size Exclusion Chromatography Technology: Gradient, Isocratic, Preparative, Analytical, Flash Application: Pharmaceutical Testing, Food Safety Analysis, Environmental Monitoring, Petrochemical Analysis, Biotechnology Research End User: Research Institutes, Contract Manufacturing Organizations, Academic Laboratories, Quality Control Labs, Biotech Companies |
| Companies Covered | Shimadzu Corporation, Bio-Rad Laboratories Inc., Waters Corporation, Merck KGaA, Hitachi High-Tech Corporation, Agilent Technologies, PerkinElmer Inc., Bruker Corporation, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liquid Chromatography Instruments Market Shifts & Advancements
Detector modularity and software-defined architectures are actively reshaping competitive boundaries in liquid chromatography, enabling specialist vendors to challenge integrated platform incumbents through targeted performance optimization rather than full-system replication.
Microfluidic chip-based separation technology is fragmenting the sample preparation and injection workflow. Biotech method development groups in Boston and Basel are piloting these systems for high-throughput screening applications. The technology is fragmenting the traditional value chain by displacing manual sample handling steps with automated micro-liter precision, compressing the addressable market for standalone autosampler modules.
EMA ICH Q2(R1) revisions and China's NMPA pharmacopeia updates are tightening quantification thresholds in parallel with FDA guidance. These frameworks mandate enhanced sensitivity specifications and traceable calibration protocols that obsolete legacy systems unable to meet new detection limits. Biopharma quality control labs in Germany and China are responding with accelerated recertification budgets and detector upgrade roadmaps.
Service contract unbundling is emerging as a procurement pattern among mid-sized contract research organizations. These buyers are separating hardware acquisition from maintenance agreements, sourcing third-party qualification and repair services through specialized metrology providers rather than OEM channels. The shift is most visible in the United States, where CROs in Research Triangle Park and San Diego are building in-house service capabilities to reduce total cost of ownership.
Global Liquid Chromatography Instruments Market Segmentation
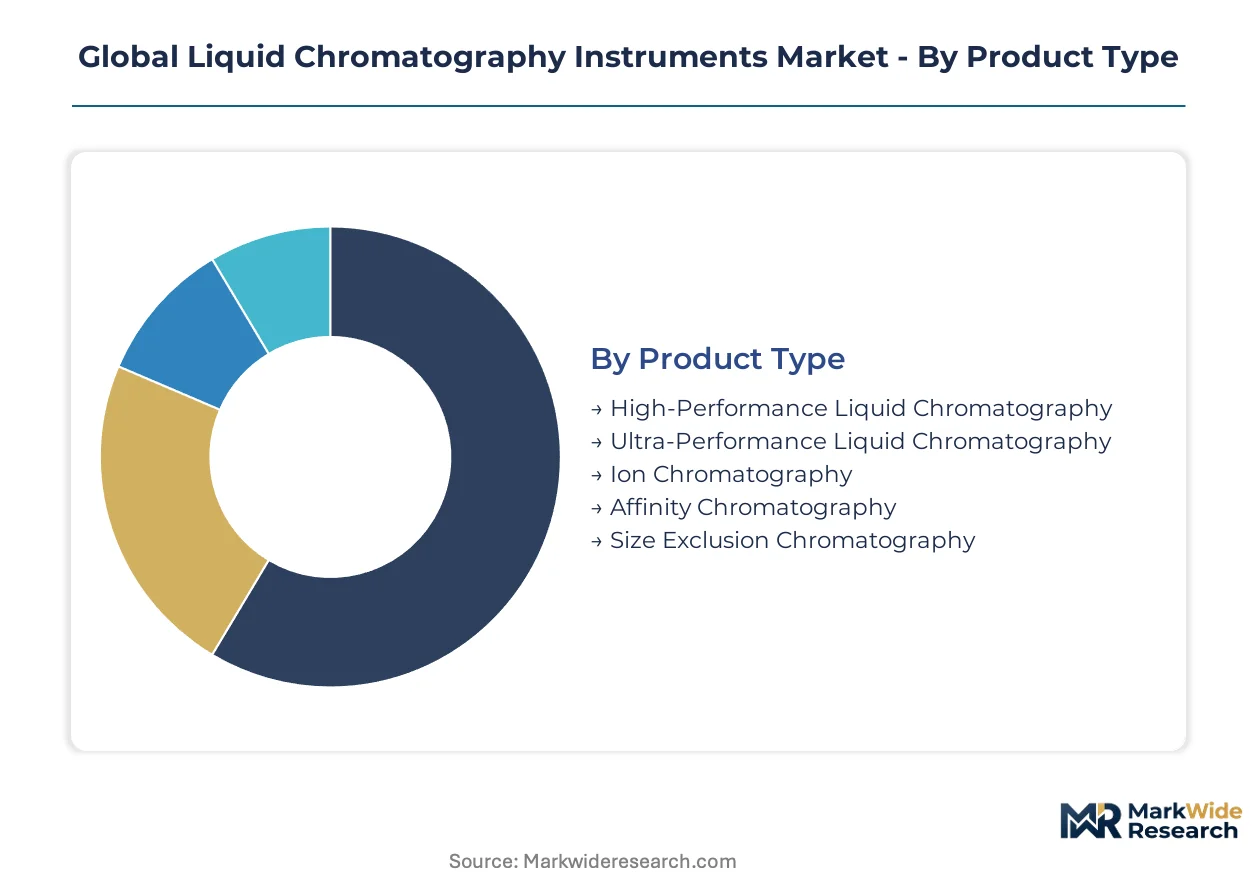
Segmentation in liquid chromatography instruments reveals distinct margin architectures across product generations and end-use contexts. Procurement patterns diverge sharply between regulated pharmaceutical environments and exploratory research settings, with each segment demanding tailored detector configurations and software validation packages.
Product Type:
Margin pools concentrate in ultra-performance systems where solvent reduction capabilities and throughput advantages command pricing premiums over legacy platforms.
- High-Performance Liquid Chromatography:Conventional HPLC systems operate at 1,000–6,000 psi with decades of validated pharmacopeial methods supporting installed bases. Quality control labs in Germany and the United States extend depreciation cycles due to method lock-in, though FDA bioanalytical guideline revisions are forcing selective upgrades.
- Ultra-Performance Liquid Chromatography:UPLC configurations generate disproportionate margins through 6,000–15,000 psi operation and reduced mobile-phase consumption. Biotech companies in Boston and Basel are prioritizing these systems for monoclonal antibody characterization workflows.
- Ion Chromatography:Specialized for ionic species separation with conductivity detection, serving environmental monitoring agencies and power plant water analysis.
- Affinity Chromatography:Purification-focused systems exploiting biomolecular binding specificity, concentrated in bioprocessing scale-up applications.
- Size Exclusion Chromatography:Molecular weight fractionation for protein aggregation studies and polymer characterization, prevalent in academic structural biology labs.
The dominant share belongs to High-Performance Liquid Chromatography, while Ultra-Performance Liquid Chromatography is closing the gap fastest.
Technology:
Technology selection tracks sample complexity, with gradient methods capturing premium pricing for multi-component separations and isocratic retaining cost-sensitive routine applications.
- Gradient:Mobile-phase composition shifts during elution enable complex sample profiling. Pharmaceutical method development groups in China and Germany are standardizing gradient-capable systems to meet tightened EMA and NMPA quantification thresholds.
- Preparative:Scale-up purification commands specialized column packing and consulting service bundles. European and Japanese suppliers dominate stationary-phase manufacturing, creating input bottlenecks for kilogram-scale biopharma production.
- Isocratic:Constant mobile-phase composition for routine quality control, retaining installed base in generic pharmaceutical testing.
- Analytical:Small-scale quantification workflows, standard in contract research organizations across Research Triangle Park and San Diego.
- Flash:Rapid preparative separation for synthetic chemistry route scouting, concentrated in medicinal chemistry departments.
Gradient technology holds the largest revenue footprint, though Preparative systems deliver the highest per-unit margins through consumables and service attachment.
Application:
Application segmentation reflects regulatory intensity, with pharmaceutical testing absorbing compliance-driven replacement cycles and food safety responding to emerging contaminant detection mandates.
- Pharmaceutical Testing:Bioanalytical method validation for drug development and quality control. FDA, EMA, and China's NMPA pharmacopeia updates collectively obsolete legacy systems unable to meet enhanced sensitivity specifications.
- Environmental Monitoring:Pollutant detection for water and air matrices. EPA and MEE regulatory frameworks in the United States and China are expanding analyte lists, driving detector sensitivity upgrades.
- Food Safety Analysis:Contaminant screening for pesticides, mycotoxins, and veterinary residues. FSSAI in India and EFSA in Europe are tightening maximum residue limits, forcing method recertification.
- Petrochemical Analysis:Hydrocarbon characterization for refinery process control, concentrated in Texas and Saudi Arabia production clusters.
- Biotechnology Research:Exploratory protein and nucleic acid analysis, prevalent in academic and startup laboratory settings with flexible procurement budgets.
Pharmaceutical Testing anchors volume demand, while Environmental Monitoring is expanding most quickly on regulatory list expansion.
End User:
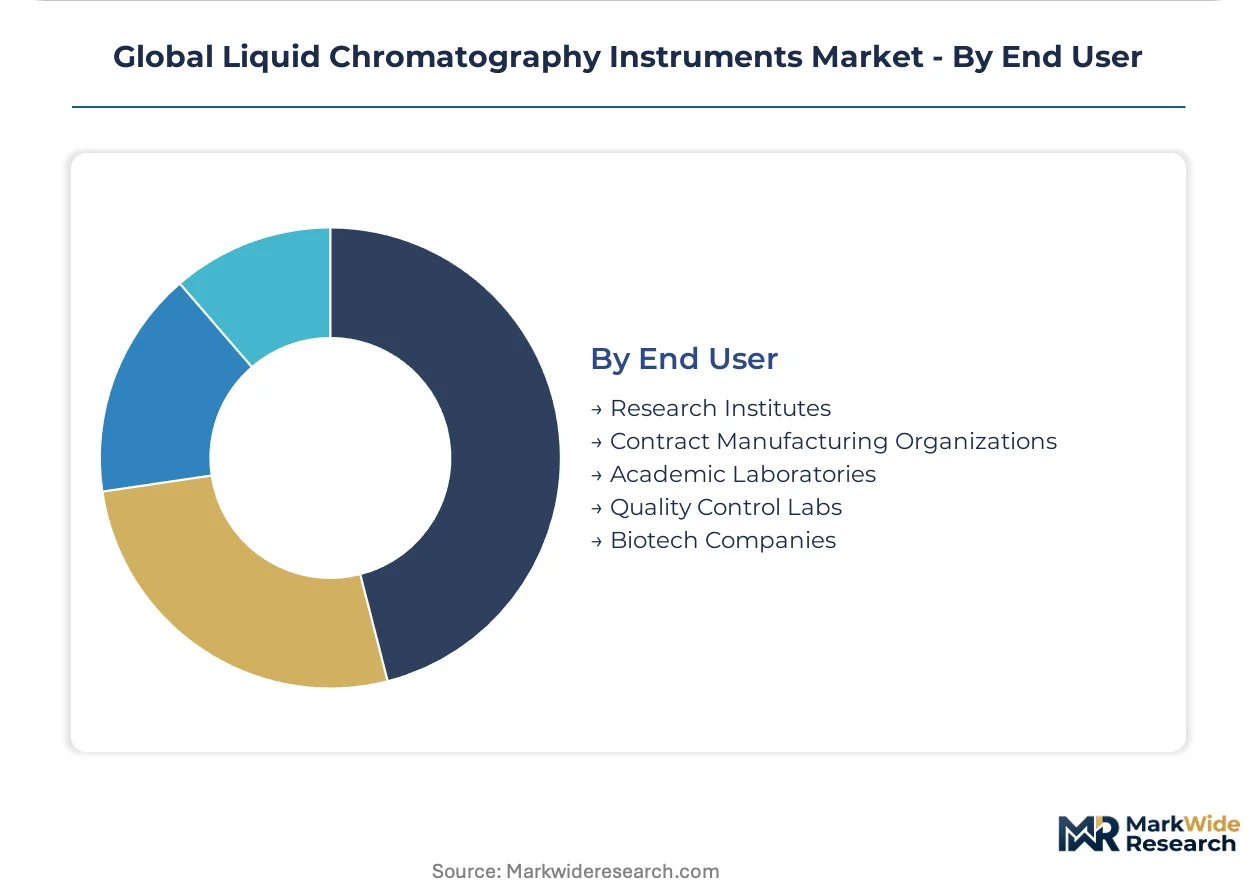
End-user segmentation reveals procurement fragmentation, with biotech companies prioritizing performance specifications and contract manufacturers optimizing total cost of ownership.
- Biotech Companies:Method development for therapeutic candidates, with Boston and Basel clusters driving ultra-performance system adoption for monoclonal antibody workflows.
- Contract Manufacturing Organizations:India CDMOs are building analytical capabilities for export markets, creating greenfield demand outside established pharma clusters with unbundled service procurement.
- Research Institutes:Exploratory applications with flexible method development requirements and grant-funded capital cycles.
- Academic Laboratories:Training and fundamental research with price-sensitive procurement and shared core facility models.
- Quality Control Labs:Routine testing with method validation inertia, extending replacement timelines unless regulatory mandates intervene.
Biotech Companies command the highest per-site spending, while Contract Manufacturing Organizations are climbing the fastest on geographic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian CDMOs exhibit the highest price elasticity, unbundling service contracts to minimize total cost of ownership, while German biotech clusters absorb premium UPLC pricing without procurement friction. Chinese NMPA pharmacopeia updates and FDA bioanalytical guidelines are compressing replacement cycles unevenly across jurisdictions.
United States
FDA bioanalytical method validation guidelines are forcing biopharma labs in Boston and San Diego to recertify systems for monoclonal antibody characterization. The agency's tightened detection thresholds obsolete legacy HPLC installations in quality control environments. Research Triangle Park CROs are pioneering unbundled service procurement, separating hardware acquisition from third-party metrology contracts.
Germany
EMA ICH Q2(R1) revisions mandate enhanced sensitivity specifications that accelerate UPLC adoption in Basel-proximate biotech clusters. German quality control labs extend depreciation cycles less than other European peers due to regulatory stringency. Bavarian pharmaceutical method development groups standardize gradient-capable systems to meet traceable calibration protocols.
China
NMPA pharmacopeia updates are obsoleting installed bases unable to meet new quantification thresholds in Shanghai and Suzhou pharmaceutical corridors. MEE regulatory frameworks expand environmental monitoring analyte lists, driving detector sensitivity upgrades beyond pharma applications. Yangtze River Delta biotech companies prioritize ultra-performance systems for export-market compliance.
India
CDSCO export requirements and FSSAI maximum residue limit tightening are building analytical capabilities in Hyderabad and Ahmedabad manufacturing clusters. Indian contract manufacturers exhibit the most aggressive service contract unbundling, sourcing third-party qualification to reduce total cost of ownership. Greenfield instrument demand concentrates outside established pharma corridors as CDMOs expand.
Japan
PMDA alignment with ICH Q2(R1) standards forces recertification timelines comparable to European regulators in Tokyo and Osaka biopharma centers. METI-supported continuous manufacturing initiatives drive real-time chromatography deployment at production scale. Domestic instrument demand concentrates in Kansai chemical and pharmaceutical production clusters seeking process analytical technology integration.
Global Liquid Chromatography Instruments Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with modular detector architectures collapsing historical capital-intensity gaps between mass-market vendors and precision-focused specialists. Three strategic archetypes dominate: integrated platform incumbents defending premium positioning through software ecosystems and consumables lock-in; precision-focused specialists leveraging targeted performance optimization; and scale-driven manufacturers competing on total cost of ownership. Competitive moves concentrate on M&A for detector technology access and strategic partnerships for continuous manufacturing integration.
Among integrated platform incumbents, Agilent Technologies and Waters Corporation exemplify the premium-tier defense archetype through ion mobility quadrupole platforms and UPLC ecosystem anchoring respectively. Thermo Fisher Scientific occupies a position emphasizing consumables bundling and service contract penetration. Shimadzu Corporation represents the scale-driven Japanese manufacturing archetype with broad analytical instrumentation portfolios. These three companies collectively illustrate how hardware differentiation alone has become insufficient for margin defense.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Bio-Rad Laboratories Inc. |
| Waters Corporation |
| Merck KGaA |
| Hitachi High-Tech Corporation |
| Agilent Technologies |
| PerkinElmer Inc. |
| Bruker Corporation |
| Thermo Fisher Scientific Inc. |
| Others |
Supply & Pricing Matrix
Long-term consumables contracts anchor both supply security and price predictability for biopharma buyers, locking OEM service revenues across depreciation-extended instrument lifecycles while exposing vendors to margin compression when third-party qualification providers undercut maintenance bundling.
Pricing Analysis
Service contract tiers drive lifetime value capture, with multi-year validation and calibration packages generating recurring revenue that exceeds initial hardware margins. Three-tier pricing structure across premium, standard, and economy levels segments buyers by regulatory stringency and throughput requirements. Pricing pressure stems from Indian CDMOs aggressively unbundling maintenance agreements to reduce total cost of ownership. Contract research organizations exhibit highest price sensitivity, while Basel-proximate biotech clusters absorb premium UPLC pricing without procurement friction.
Supply Chain Analysis
Specialized stationary-phase manufacturing concentrates among German, Japanese, and Swiss suppliers, creating input bottlenecks for preparative chromatography scale-up. Chromatography-grade helium draws from U.S. and Qatari production clusters, with gas-dependent mass spectrometry coupling configurations exposed to commodity volatility. Single-source vulnerability runs through column packing chemistry for kilogram-scale bioproduction. Distribution feeds from regional OEM hubs in Massachusetts, Bavaria, and Shanghai into biopharma manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics is reshaping competitive boundaries as modular detector architectures erode hardware-based moats and software ecosystems become the primary defensibility mechanism for incumbents.
For Market Incumbents: Secure consumables lock-in through proprietary column chemistries and closed detector interfaces to defend against third-party service unbundling. Deepen backward integration into specialized stationary-phase manufacturing to reduce exposure to European and Japanese supplier concentration. Prioritize software validation package certification for FDA bioanalytical guideline compliance to maintain premium positioning.
For New Entrants and Emerging Players: Differentiate on AI-assisted method development modules that compress gradient optimization timelines for biotech method development groups. Target India CDMO greenfield procurement with unbundled hardware and third-party qualification service partnerships. Pursue microfluidic chip-based separation pilots with Boston and Basel high-throughput screening labs as reference accounts.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision-focused specialists with detector technology IP and embedded software subscription streams. Long-term viability favors vendors with continuous manufacturing integration capabilities aligned with FDA and EMA process analytical technology mandates. Monitor helium supply contract restructuring as an inflection signal for mass spectrometry coupling configuration demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Detector Technology Acquisition | Modular architectures collapse capital barriers for specialist entrants challenging integrated platforms. |
| Continuous Manufacturing Partnership | FDA process analytical technology mandates drive real-time chromatography deployment at production scale. |
| AI Method Development Platform Launch | Machine learning gradient optimization enables differentiated software-subscription revenue streams. |
| Service Contract Unbundling Response | Third-party qualification growth in U.S. CROs threatens OEM maintenance revenue attachment rates. |
| Helium-Independent Detection Investment | Supply volatility constrains gas-dependent mass spectrometry coupling configurations. |
Research Methodology
Cross-validation between primary interviews with biopharma analytical directors, regulatory affairs leads, CDMO procurement officers, and aftermarket service heads anchors the qualitative findings against secondary sources including FDA bioanalytical guidance documents, EMA ICH Q2(R1) submissions, NMPA pharmacopeia updates, and SEC instrument manufacturer filings. Bottom-up installed base modeling triangulates against top-down market sizing across product type, technology, application, and end-user segmentation dimensions.
Sensitivity analysis tests forecast robustness across regulatory timeline scenarios, helium price volatility bands, and UPLC conversion rate assumptions throughout the projection horizon. Segmentation modeling incorporates instrument generation, pressure specification tier, detection modality, and geographic regulatory cluster. CAGRs derive from replacement cycle compression analysis tied to FDA, EMA, and NMPA guideline revision timelines, cross-referenced with biopharma R&D footprint expansion in Boston, Basel, and Shanghai corridors.
The analysis sits within stated boundaries; outcomes outside sustained regulatory tightening or helium supply stabilization would require recalibration. Forecasts reflect documented assumptions regarding method validation inertia in quality control environments and CDMO geographic expansion trajectories. Practitioners should keep alternative scenarios live as bioanalytical guideline convergence and continuous manufacturing adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Digital Shore Durometer Market
Testing Equipment
Nitrogen Tester Market
Testing Equipment
Global Liquid Process Analyzer Market
Testing Equipment
Glass Testing Equipment Market
Testing Equipment
Global Chromatography Instrumentation Market
Testing Equipment
Chemical Detector Market
Testing Equipment
Supercritical Fluid Chromatography Market
Testing Equipment
Chemical Warfare Agent Detectors Market
Testing Equipment
In-Line UV-Vis Spectroscopy Market
Testing Equipment
Global Insulation Testers Market
Testing Equipment
Continuous Flow Analyzer Market
Testing Equipment
Lubricant Testing Machine Market
Testing Equipment
Paper Tester Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Flammability Tester Market
Testing Equipment
2D Chromatography Market