
 Flammability Tester Market | 2026-2036
Flammability Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Flammability Tester Market Foresight
German testing equipment manufacturing is decoupling from generic safety instrument production. SGS SA leverages its global laboratory network to anchor premium calibration services. Intertek Group plc competes through specialized fire testing protocols for aerospace and automotive clients.
A flammability tester measures ignition resistance, flame spread rate, and smoke emission characteristics of materials under controlled thermal exposure, typically operating between ambient temperature and 1,200°C with precision tolerances of ±2°C. These instruments serve manufacturers and certification bodies seeking compliance with product safety codes before market entry. Horizontal flame testers dominate volume demand across textile and plastic component testing, while computerized analysis technology captures expanding margin pools as laboratories automate pass-fail determination and data traceability. Smoke density testers represent the fastest-growing product category, driven by tightened building material regulations in high-rise construction markets.
The U.S. Consumer Product Safety Commission, the EU Construction Products Regulation, and China's GB standards collectively mandate flammability certification for textiles, electronics housings, and interior building materials, creating baseline demand that equipment vendors cannot access without validated test protocols. ASTM E84, ISO 5659, and EN 13501 shape product design specifications and create regional compatibility requirements that influence purchasing decisions. Stakeholders must monitor evolving harmonization between national fire test methods and the emerging EU Digital Product Passport requirements that will demand machine-readable compliance documentation.
Market Dynamics
Automotive electrification and battery thermal runaway testing are compressing equipment procurement cycles as manufacturers face new material validation requirements for electric vehicle battery enclosures and interior components.
Growth Catalysts
- EU Construction Products Regulation:Mandatory fire classification of building materials under EN 13501 is forcing construction product manufacturers to maintain in-house testing capabilities or secure third-party laboratory partnerships.
- Textile flame retardancy mandates:Upholstery and bedding manufacturers in residential and hospitality sectors must certify products to 16 CFR Part 1633 and similar protocols before commercial distribution.
- High-rise construction density:Urban vertical development in China and the United Arab Emirates is accelerating smoke density tester deployment for facade and insulation material approval.
Market Restraints
- Precision sensor supply concentration:High-temperature thermocouples and optical flame detectors rely heavily on Japanese and German component suppliers, creating vulnerability to export control disruptions.
- Capital intensity of multi-protocol systems:Integrated testers capable of ASTM E84, ISO 5659, and EN 13501 protocols require substantial upfront investment that mid-sized laboratories cannot amortize.
- Calibration service bottlenecks:Accredited reference material providers are concentrated in Western Europe and the United States, extending recertification lead times for Asian and Middle Eastern facilities.
Strategic Opportunities
- India laboratory infrastructure expansion:BIS mandatory certification for electrical goods and building materials is creating demand for localized flammability testing capacity as domestic manufacturing scales under PLI schemes.
- Digital Product Passport alignment:EU regulatory frameworks will require machine-readable fire safety documentation, opening software and automated reporting integration services.
- Battery thermal propagation testing:Lithium-ion cell manufacturers need specialized abuse testing chambers that simulate cascading failure modes beyond standard material flammability protocols.
Industry Challenges
- Cross-protocol technician expertise:Operators must master divergent sample preparation and ignition source configurations across ASTM, ISO, and GB standard families, extending training timelines.
- Legacy equipment retrofit complexity:Older horizontal flame chambers lack data acquisition architectures compatible with modern laboratory information management systems, forcing expensive replacement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flammability Tester Market |
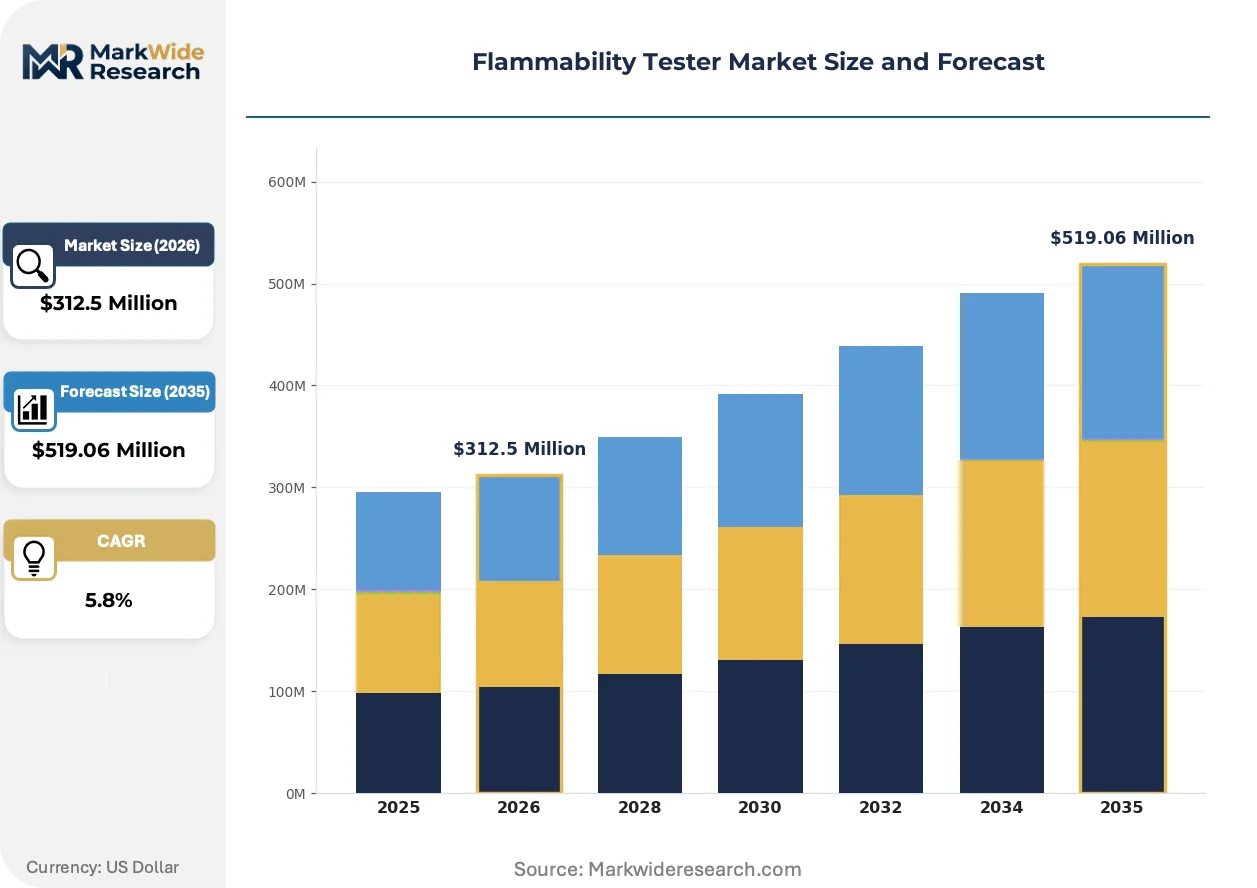
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Flame Tester, Vertical Flame Tester, Glow Wire Tester, Ignitability Tester, Smoke Density Tester Technology: Infrared Detection, Thermocouple Sensors, Laser Ignition, Computerized Analysis, Manual Observation Application: Textile Testing, Plastic Components, Electronic Devices, Building Materials, Aerospace Components End User: Quality Control Labs, Certification Agencies, Research Institutions, Manufacturing Units, Safety Compliance Consultants |
| Companies Covered | SGS SA, Intertek Group plc, UL LLC, Bureau Veritas, TÜV SÜD AG, Applus+ Laboratories, Element Materials Technology, Eurofins Scientific SE, Fire Testing Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flammability Tester Market Shifts & Advancements
Instrumentation manufacturers are embedding artificial intelligence and machine-readable compliance documentation into testing workflows, shifting competitive advantage from hardware precision to integrated data ecosystems.
Computerized flame spread analysis is electrifying laboratory throughput by replacing manual visual assessment with high-speed imaging and algorithmic pass-fail determination. Third-party certification bodies in Germany and the United States are deploying these systems to reduce technician subjectivity and accelerate client turnaround. The technology is compressing pricing power for basic horizontal flame testers while expanding margin capture in premium automated segments.
REACH restriction proposals on halogenated flame retardants are forcing material suppliers to reformulate polymers and textiles with alternative chemistries that require retesting under modified protocols. European manufacturers of furniture and electronics housings must validate new compound flammability profiles before regulatory deadlines. This regulatory churn is sustaining replacement demand for testing services even as underlying product volumes stabilize.
Buyers are unbundling equipment procurement from mandatory service contracts, pressuring vendors to compete on transparent calibration and maintenance pricing. Large textile and automotive manufacturers in China and Germany now source testers and post-warranty support from separate providers. This disintermediation is most pronounced among multinational corporations with centralized laboratory networks that can negotiate volume-based service agreements independent of initial capital expenditure.
Flammability Tester Market Segmentation
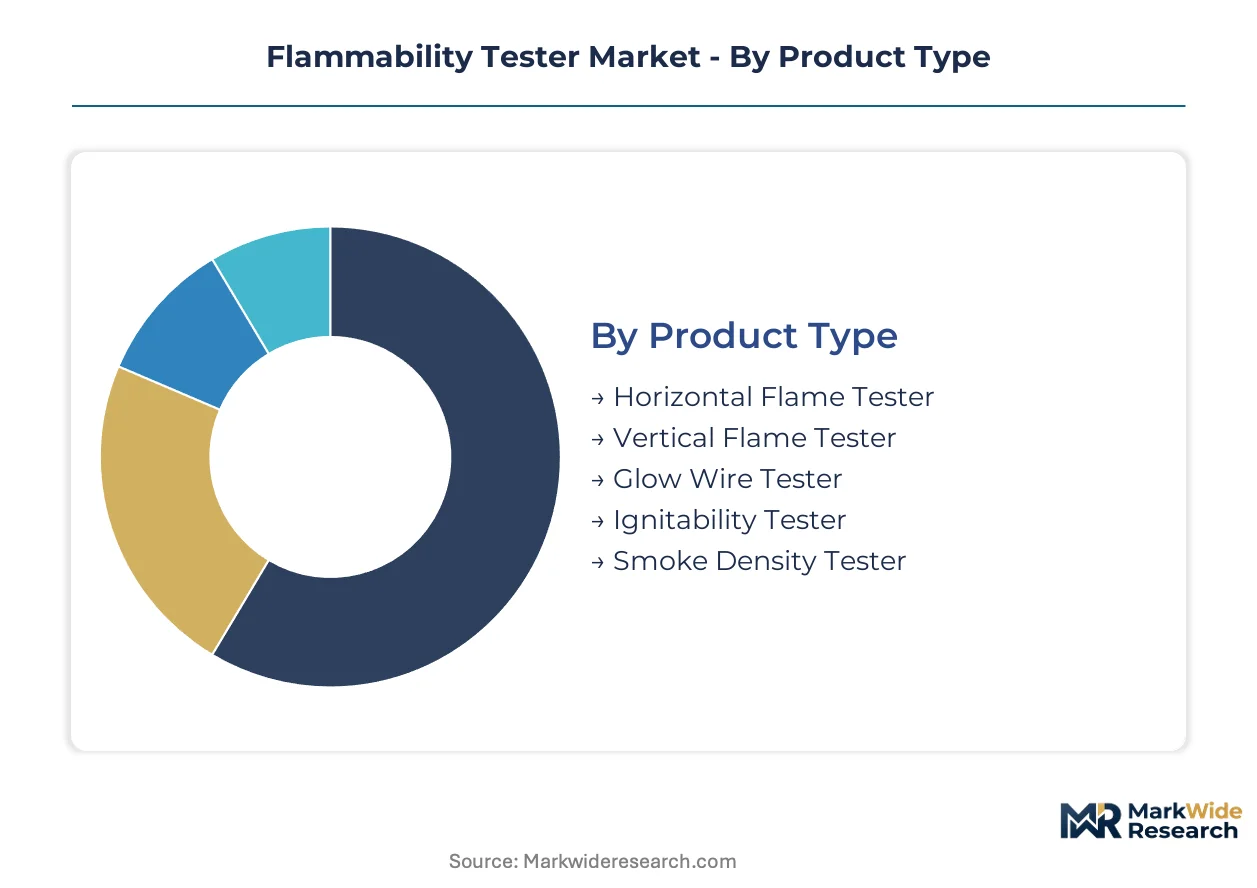
Flammability testing equipment segments diverge sharply by capital requirements and regulatory complexity. Procurement patterns cluster around protocol-specific validation needs rather than generic safety instrumentation, with automated systems commanding premium positioning against manual alternatives.
Product Type:
Horizontal flame chambers require the lowest upfront capital outlay among major product categories, while multi-protocol integrated systems demand substantial laboratory infrastructure investment.
- Horizontal Flame Tester:Standardized chambers for textile and plastic component evaluation dominate procurement volumes across quality control laboratories. Chinese textile exporters and German automotive suppliers deploy these units most intensively to satisfy 16 CFR Part 1610 and ISO 6941 protocols.
- Smoke Density Tester:Optical measurement systems for particulate emission quantification during material combustion attract the steepest investment escalation. High-rise construction markets in the United Arab Emirates and China mandate these units for facade material approval under EN 13501 and GB 8624.
- Vertical Flame Tester:Wall-mounted ignition resistance evaluation for apparel and upholstery fabrics.
- Glow Wire Tester:Simulated overheating contact assessment for electrical appliance housings.
- Ignitability Tester:Pilot flame exposure systems for building material surface flammability classification.
Most installed capacity flows through horizontal flame testers. Expansion is steepest in smoke density testers.
Technology:
Sensor architecture determines both precision tolerances and long-term calibration burden, with thermocouple-dependent systems presenting higher lifecycle costs than optical alternatives.
- Computerized Analysis:High-speed imaging with algorithmic pass-fail determination eliminates technician subjectivity in flame spread assessment. German certification bodies and U.S. automotive laboratories prioritize these systems to compress client turnaround timelines and satisfy audit trail requirements.
- Infrared Detection:Non-contact temperature mapping enables continuous thermal profiling without sensor degradation. Aerospace material validation facilities in France and Japan specify infrared architectures for carbon fiber composite testing where thermocouple contact would compromise sample integrity.
- Thermocouple Sensors:Direct-contact temperature measurement with ±2°C precision tolerance.
- Laser Ignition:Focused energy delivery for controlled ignition source standardization.
- Manual Observation:Visual assessment protocols requiring trained technician certification.
Computerized analysis systems gain share fastest in premium laboratory segments. Manual observation persists only in budget-constrained certification environments.
Application:
End-use sector dictates protocol multiplicity, with building materials requiring the broadest standard coverage and electronics focusing on narrow thermal runaway simulation.
- Building Materials:Comprehensive fire classification testing spans insulation, facade, and interior finish categories under divergent national regimes. Construction product manufacturers in Germany and China maintain the densest installed base to satisfy EN 13501 and GB 8624 mandatory classification.
- Electronic Devices:Battery enclosure and housing material validation concentrates demand among lithium-ion cell producers. Electric vehicle battery manufacturers in South Korea and the United States commission specialized abuse testing chambers beyond standard flammability protocols.
- Textile Testing:Upholstery, apparel, and bedding flame resistance certification.
- Plastic Components:Automotive interior and electrical housing material validation.
- Aerospace Components:Cabin material fire, smoke, and toxicity compliance testing.
Building materials absorb the largest share of multi-protocol system investment. Electronic device testing climbs fastest as electrification accelerates material validation cycles.
End User:
Customer type shapes procurement autonomy, with centralized manufacturing networks favoring in-house laboratory buildout while fragmented suppliers rely on third-party certification partnerships.
- Quality Control Labs:In-house testing facilities at textile, automotive, and electronics manufacturers. Large Chinese and German manufacturing groups deploy the most extensive captive laboratory networks to compress certification lead times and protect proprietary formulation data.
- Certification Agencies:Independent third-party validation services for market entry documentation. SGS and Intertek laboratory networks anchor premium service positioning through accredited protocol coverage across multiple jurisdictions.
- Research Institutions:University and government laboratory facilities for standard development and material science investigation.
- Manufacturing Units:Production floor quality assurance with simplified pass-fail instrumentation.
- Safety Compliance Consultants:Advisory services bundling testing coordination with regulatory interpretation.
Quality control laboratories command the densest equipment concentration. Certification agencies drive the fastest upgrade cycles as regulatory harmonization demands expanded protocol coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating testing capacity to jurisdictions where compliance costs diverge from enforcement intensity, creating arbitrage opportunities for laboratories serving export markets. This geographic repositioning concentrates investment in countries with dense industrial clusters and harmonized certification protocols.
United States
Electric vehicle battery manufacturers in Michigan and California are commissioning thermal runaway testing chambers beyond standard material protocols. The U.S. Consumer Product Safety Commission enforces 16 CFR Part 1633 for bedding and upholstery certification. Detroit's automotive corridor and Silicon Valley's electronics cluster absorb the densest concentration of in-house quality control laboratories.
Germany
Construction product manufacturers maintain extensive captive testing networks to satisfy EN 13501 fire classification mandates with compressed lead times. The EU Construction Products Regulation mandates machine-readable compliance documentation through emerging Digital Product Passport frameworks. Bavaria's industrial belt and North Rhine-Westphalia's chemical corridor host the most accredited third-party laboratory partnerships.
China
Textile exporters in Zhejiang and Guangdong provinces deploy horizontal flame testers intensively for 16 CFR Part 1610 and ISO 6941 protocol compliance. GB standards for building materials and electrical goods mandate flammability certification through BIS-aligned mandatory certification schemes. The Yangtze River Delta and Pearl River Delta concentrate both manufacturing volume and testing infrastructure investment.
India
Domestic manufacturing scaling under PLI schemes is driving localized flammability testing capacity for electrical goods and building materials. BIS mandatory certification requirements are forcing importers and domestic producers to establish accredited laboratory relationships. Maharashtra's industrial corridor and Gujarat's chemical hubs are attracting certification agency expansion and equipment procurement.
United Arab Emirates
High-rise construction density in Dubai and Abu Dhabi is accelerating smoke density tester deployment for facade and insulation material approval. Local regulators enforce GB 8624 and EN 13501-aligned protocols for tall building safety certification. The Emirates' urban vertical development corridor represents the fastest-growing demand pocket for optical particulate emission measurement systems.
Flammability Tester Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue automated data integration and software-enabled compliance documentation. The vendor base stratifies between precision hardware fabricators and service-anchored certification networks. Three archetypes dominate: multinational testing conglomerates with accredited laboratory networks, specialized instrumentation manufacturers with protocol-specific expertise, and regional system integrators serving cost-sensitive procurement segments. Competitive dynamics center on geographic expansion of calibration service coverage and backward integration into sensor component supply.
Within the certification-network tier, SGS SA and Intertek Group plc exemplify service-anchored positioning through global laboratory footprints and premium calibration offerings. Bureau Veritas occupies a position bridging third-party validation and equipment specification consulting. These entities represent the demand aggregation function that shapes equipment procurement specifications across multinational manufacturing clients.
| Leading Market Players |
|---|
| SGS SA |
| Intertek Group plc |
| UL LLC |
| Bureau Veritas |
| TÜV SÜD AG |
| Applus+ Laboratories |
| Element Materials Technology |
| Eurofins Scientific SE |
| Fire Testing Technology |
| Others |
Supply & Pricing Matrix
EU Digital Product Passport mandates gate qualified supply and premium-tier pricing access for flammability testing equipment, as machine-readable compliance documentation requirements concentrate procurement among vendors with integrated software architectures and accredited calibration networks.
Pricing Analysis
Distributor margins compress pricing power for mid-tier instrumentation, while direct-to-OEM relationships secure volume discounts for multinational manufacturing groups. Three-tier pricing structure across premium, standard, and economy levels stratifies by protocol multiplicity and after-sales bundling, with computerized analysis systems commanding substantial premiums over manual observation units. Pricing pressure stems from buyer unbundling of equipment and service contracts, as large Chinese and German textile manufacturers now source calibration independently. Quality control laboratories exhibit highest price sensitivity due to capital intensity, whereas certification agencies prioritize protocol coverage over unit cost.
Supply Chain Analysis
Freight costs for precision optical components and high-temperature sensors elevate landed costs for Asian and Middle Eastern laboratories sourcing from German and Japanese component fabricators. Thermocouple production concentrates in Japan and Germany, while optical flame detector supply anchors in German precision engineering clusters and specialized Japanese sensor manufacturers. Supply chain risk centers on export control exposure for high-precision thermal measurement components. Distribution runs through accredited laboratory networks and specialized instrumentation distributors serving regional manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flammability testing equipment procurement functions as a geographic-arbitrage play, as Indian laboratories under BIS mandatory certification face lower compliance costs than European facilities under EN 13501 while serving equivalent export validation requirements.
For Market Incumbents: Hedge against disintermediation pressure by deepening backward integration into sensor component supply and securing captive calibration material production in Western Europe. Certification agencies like SGS and Intertek threaten equipment vendors through service-anchored bundling. Vertical integration into high-temperature thermocouple fabrication defends margin position.
For New Entrants and Emerging Players: AI-enabled flame spread analysis offers technology-first wedge into premium laboratory segments where algorithmic pass-fail determination displaces manual technician assessment. Battery thermal propagation testing for South Korean and US electric vehicle manufacturers represents the most penetrable white-space target. Go-to-market through software integration partnerships with existing horizontal flame chamber installed bases.
For Investors and Strategic Acquirers: Roll-up economics work for regional certification agencies because BIS expansion in India and PLI-driven manufacturing scaling create fragmented laboratory networks requiring consolidation. Long-term viability hinges on digital compliance documentation capabilities. Acquisition target archetype: accredited third-party laboratories with EN 13501 and GB 8624 protocol coverage. Signal to watch: EU Digital Product Passport implementation timeline acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Components | Mitigates Japanese and German supply concentration for high-temperature thermocouples. |
| Software-Enabled Compliance Documentation | Aligns with EU Digital Product Passport machine-readable fire safety requirements. |
| Battery Thermal Runaway Chamber Development | Captures electric vehicle battery enclosure validation demand from South Korean cell producers. |
| Accredited Laboratory Network Expansion | SGS and Intertek leverage global footprint to anchor premium calibration service positioning. |
| India Localization Partnership | BIS mandatory certification creates demand for domestic flammability testing capacity under PLI schemes. |
Research Methodology
Bottom-up quality control laboratory modeling reconciled against top-down certification agency capacity tracking forms the analytical core of this study. Primary interviews with laboratory directors, equipment procurement managers at textile and automotive manufacturers, calibration service heads, and regulatory compliance officers combined with secondary validation from ASTM and ISO standard documentation, EU Construction Products Regulation filings, and BIS certification databases. Trade data from customs records and SEC filings of listed testing conglomerates provided supply-side triangulation.
Input-output matrices mapped equipment procurement volumes against end-use sector growth trajectories across the projection horizon. Segmentation dimensions modeled include product type, sensor technology architecture, application sector, and end-user category. CAGRs derived from regression analysis of historical procurement patterns and regulatory mandate implementation schedules. Forecast inputs incorporated electric vehicle production scaling and high-rise construction density projections for smoke density tester demand.
The model holds under stable regulatory harmonization between ASTM, ISO, and GB standard families; deviation in EU Digital Product Passport implementation scope or REACH restriction acceleration on halogenated flame retardants would shift replacement demand timing. Forecasts reflect documented assumptions on technician training timelines and calibration service capacity expansion. A model refresh is warranted upon material change in battery thermal runaway testing protocol standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Gold Tester Market
Testing Equipment
Chromatography Systems Market
Testing Equipment
Magnesium Testing Reagents Market
Testing Equipment
Chemical Warfare Agent Detectors Market
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Global Online Coal Ash Analyzers Market
Testing Equipment
Global Film Thickness Measurement Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Water Testing Equipment Market
Testing Equipment
Global Silica Analyzer Market
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Global Laboratory Analytical Instruments and Consumables Market
Testing Equipment
Supercritical Fluid Chromatography Market
Testing Equipment
Gas Chromatography Columns Market
Testing Equipment
Flash Point Apparatus Market
Testing Equipment
Geochemical Services Market