
 Reagent Filling Systems Market | 2026-2036
Reagent Filling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Reagent Filling Systems Market Analytics
Market Context with Strategic Players
Germany is fragmenting its reagent filling systems supply base as domestic biotech demand outpaces legacy equipment capacity. Thermo Fisher Scientific leverages integrated automation platforms to anchor large-scale diagnostic production across European contract manufacturers. Sartorius AG specializes in single-use filling assemblies that reduce cross-contamination risk in multi-product facilities. Eppendorf AG competes on precision dosing modules for research-scale reagent preparation, sustaining strong positioning in academic and institutional channels.
Technical Definition and Structural Segments
Reagent filling systems constitute precision liquid handling equipment engineered to dispense chemical, biological, or diagnostic reagents into vials, cartridges, or microplates with volumetric accuracy typically within ±1% and contamination control meeting ISO 5–7 cleanroom specifications. These systems serve pharmaceutical production, diagnostic assay manufacturing, and research workflows where batch consistency and regulatory traceability determine product viability. Fully automatic fillers command the dominant margin pool as pharmaceutical producers prioritize throughput and audit-ready documentation over capital cost savings. Positive displacement technology leads growth among technology segments because piston-driven mechanisms handle viscous protein reagents and shear-sensitive cell culture media that peristaltic pumps damage. Manual fillers occupy a shrinking but defended niche in early-stage research institutes where protocol flexibility outweighs speed requirements.
Regulatory Framework and Forward Outlook
EMA's In Vitro Diagnostic Regulation and REACH chemical compliance frameworks reshape equipment specifications across European manufacturing facilities, forcing upgrades to materials of construction and cleaning validation protocols. FDA 21 CFR Part 11 and EU GMP Annex 1 requirements on data integrity and aseptic processing drive demand for filling systems with embedded electronic batch records and isolator integration. Switzerland's Swissmedic maintains alignment with EMA standards while imposing additional notification requirements on reagent handling equipment used in clinical diagnostic kits. Stakeholders must monitor how evolving pharmacopoeial standards for extractables and leachables testing reshape material selection for fluid contact surfaces in next-generation systems.
Market Dynamics
Positive displacement technology is displacing gravity-based filling across high-value pharmaceutical production lines, forcing incumbent equipment suppliers to reengineer core pump architectures and recalibrate service revenue models around precision dosing modules.
Growth Catalysts
- EMA IVDR compliance deadlines:Diagnostic manufacturers in Germany and the Netherlands are retrofitting filling lines to meet traceability and batch documentation requirements, creating replacement demand for automated systems with embedded electronic records.
- Single-use assembly adoption:Multi-product biotech facilities in Switzerland are specifying disposable fluid path components to eliminate cross-contamination risks between monoclonal antibody and cell therapy production campaigns.
- PCR and ELISA workflow standardization:Biotechnology clusters across Basel and Leiden are tightening volumetric accuracy specifications to ±0.5% for molecular diagnostic reagents, accelerating equipment upgrade cycles in contract manufacturing organizations.
Market Restraints
- Stainless steel component cost volatility:Aseptic-grade 316L tubing and forged pump housings face price pressure from energy-intensive European metallurgy, compressing margins for mid-tier system integrators.
- Cleanroom construction bottlenecks:Qualified isolator enclosure suppliers concentrate in southern Germany and northern Italy, extending delivery timelines for complete filling lines by eight to fourteen months.
- Peristaltic pump persistence in research scale:Academic institutes resist capital outlays for positive displacement systems where protocol flexibility outweighs shear-sensitivity concerns for standard buffer formulations.
Strategic Opportunities
- Gene therapy viral vector filling:Swiss and German CDMOs are commissioning dedicated lines for AAV and lentiviral suspensions, opening demand for ultra-gentle piston pumps with validated low-shear profiles.
- EU Green Deal material incentives:REACH-compliant fluoropolymer alternatives to PTFE are qualifying for accelerated regulatory review, rewarding early adopters with reduced extractables testing burdens.
- Point-of-care diagnostic cartridge miniaturization:Microfluidic filling applications for lateral flow and molecular POC devices are migrating from manual pipetting to automated nanoliter dispensers in Dutch medtech manufacturing parks.
Industry Challenges
- Mechatronics engineering scarcity:Precision motion control specialists capable of integrating servo-driven piston mechanisms with real-time feedback loops command premium compensation in Basel and Munich labor markets.
- IQ/OQ/PQ validation backlog:Contract manufacturers face compressed timelines to qualify new filling equipment under EU GMP Annex 1 while maintaining existing production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reagent Filling Systems Market |
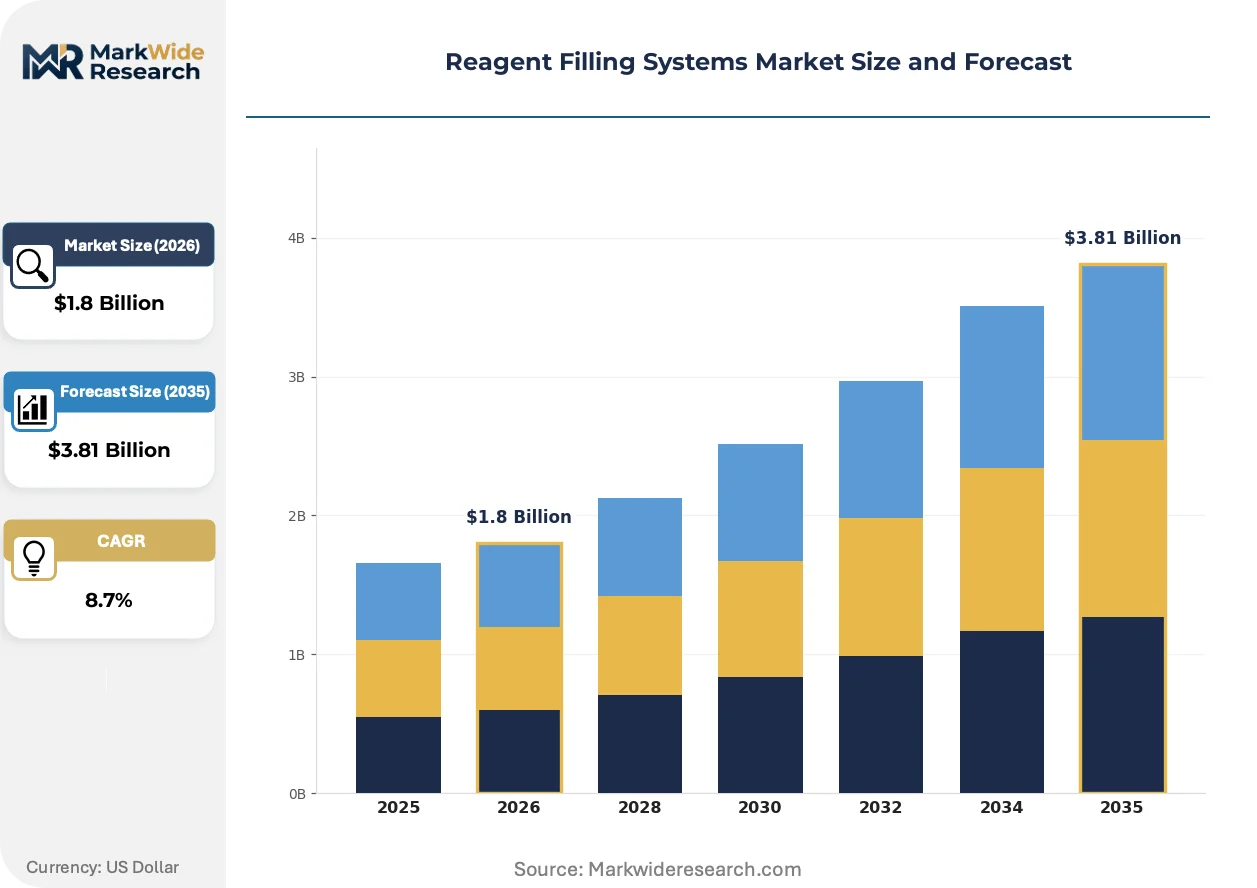
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Fillers, Semi-Automatic Fillers, Fully Automatic Fillers, Multi-Head Fillers Application: Diagnostic Laboratories, Pharmaceutical Production, Research Institutes, Quality Control Technology: Gravity Fillers, Positive Displacement Fillers, Volumetric Fillers, Peristaltic Fillers End User: Biotechnology Companies, Contract Packaging Firms, Medical Device Manufacturers, Academic Institutions |
| Companies Covered | Thermo Fisher Scientific, Sartorius AG, Eppendorf AG, Hamilton Company, Bio-Rad Laboratories, Nichrome Packaging Solutions, Robert Bosch, Cozzoli Machine, National Oilwell Varco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reagent Filling Systems Market Evolving Landscape
Embedded sensor networks and machine learning algorithms are transforming how filling systems self-optimize, shifting competitive advantage from mechanical precision to predictive process control and adaptive dosing calibration.
Smart pump architectures with integrated load cells and flow sensors are digitizing real-time volumetric verification, replacing post-fill gravimetric checks. Large-scale diagnostic producers in Germany are deploying these systems to compress batch release timelines. The technology is digitizing quality assurance workflows by enabling continuous process verification rather than discrete sampling protocols.
REACH chemical compliance frameworks are mandating comprehensive extractables and leachables profiling for all fluid-contact materials, forcing suppliers to retire legacy elastomer formulations. Equipment manufacturers must now submit migration data packages to ECHA before placing systems into GMP environments. This regulatory pressure is concentrating procurement decisions on suppliers with pre-validated material libraries, disadvantaging smaller integrators without in-house toxicology resources.
Service contract unbundling is fragmenting how buyers acquire operational support, with large pharmaceutical groups insourcing routine maintenance while outsourcing specialized calibration to OEM-certified technicians. This bifurcation is compressing aftermarket revenue for traditional full-service providers. The pattern is most pronounced in Swiss biotech clusters where facilities employ dedicated metrology teams but lack piston seal replacement expertise.
Reagent Filling Systems Market Segmentation
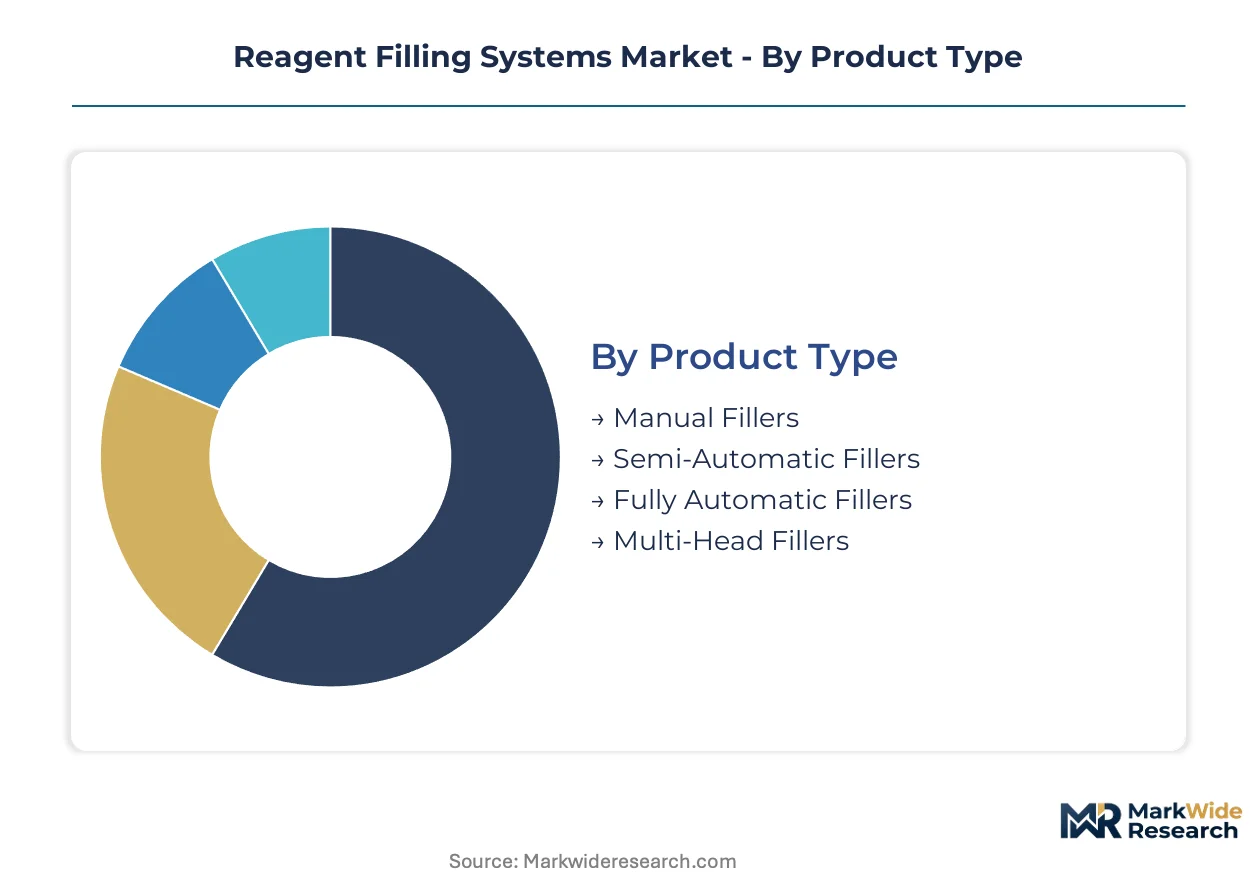
Reagent filling systems fragment across four structural dimensions that determine equipment specifications, validation burdens, and procurement authority. Product type governs capital intensity and throughput ceilings. Application dictates contamination control tiers and regulatory traceability requirements. Technology selection hinges on shear sensitivity and viscosity profiles of target reagents. End user category shapes purchasing timelines and service contract structures.
Product Type:
Equipment automation tiers map directly to batch scale and documentation rigor demanded by end-use environments.
- Fully Automatic Fillers:Integrated systems with servo-driven piston mechanisms and embedded electronic batch records achieve volumetric accuracy within ±0.5% for pharmaceutical production. German diagnostic manufacturers prioritize these systems to compress EMA IVDR compliance timelines and eliminate manual transcription errors in audit trails.
- Semi-Automatic Fillers:Operator-assisted stations combine programmable logic controllers with manual loading operations, occupying the mid-tier for contract packaging firms handling multiple reagent formats. Dutch CDMOs specify these for campaign-based monoclonal antibody filling where product changeover frequency exceeds fully automated line economics.
- Manual Fillers:Benchtop dispensers with graduated syringe or pipette-based mechanisms serve early-stage research protocols requiring protocol flexibility over throughput.
- Multi-Head Fillers:Parallel dispensing architectures with four to sixteen nozzles synchronize filling cycles for high-volume diagnostic cartridge manufacturing.
The dominant share belongs to Fully Automatic Fillers, while Semi-Automatic Fillers are closing the gap fastest as multi-product facilities seek campaign flexibility without full automation capital outlays.
Application:
End-use environments stratify by contamination risk tiers, batch documentation depth, and cleanroom integration requirements.
- Pharmaceutical Production:Aseptic filling lines for injectable reagents and biologics operate under EU GMP Annex 1 isolator enclosures with continuous environmental monitoring. Swiss biotech clusters demand these systems for gene therapy viral vector manufacturing where endotoxin limits and particulate specifications are most stringent.
- Diagnostic Laboratories:High-throughput filling for PCR master mixes and ELISA reagent kits requires traceable batch records under EMA IVDR and Swissmedic notification frameworks. Automated systems with barcode verification and automated label application dominate replacement cycles in German reference laboratories.
- Research Institutes:Protocol-flexible filling stations accommodate experimental scale and variable container formats without validation overhead.
- Quality Control:Analytical reference standard preparation demands gravimetric verification and certified volumetric traceability for pharmacopoeial compliance.
Pharmaceutical Production commands the dominant share, while Diagnostic Laboratories are expanding most quickly as IVDR compliance deadlines force equipment refresh cycles.
Technology:
Pump mechanisms differentiate by shear tolerance, viscosity range, and precision maintenance over extended production runs.
- Positive Displacement Fillers:Piston-driven systems with ceramic or stainless steel cylinders handle protein reagents and cell culture media without shear damage. These mechanisms displace peristaltic alternatives in Basel and Munich biotech manufacturing where product value justifies precision capital investment.
- Peristaltic Fillers:Tubing-based pumping with disposable fluid paths persists in academic settings and early-phase research where capital constraints outweigh shear sensitivity concerns for standard buffer formulations.
- Gravity Fillers:Head-pressure dispensing without moving parts serves low-viscosity aqueous reagents in cost-sensitive quality control applications.
- Volumetric Fillers:Time-pressure or mass-flow systems with Coriolis sensors achieve intermediate precision for diagnostic reagents with moderate viscosity ranges.
Positive Displacement Fillers hold the dominant share, while Volumetric Fillers are gaining share fastest as microfluidic applications demand intermediate precision without full piston system cost.
End User:
Buyer categories separate by in-house technical capabilities, validation timelines, and service contract preferences.
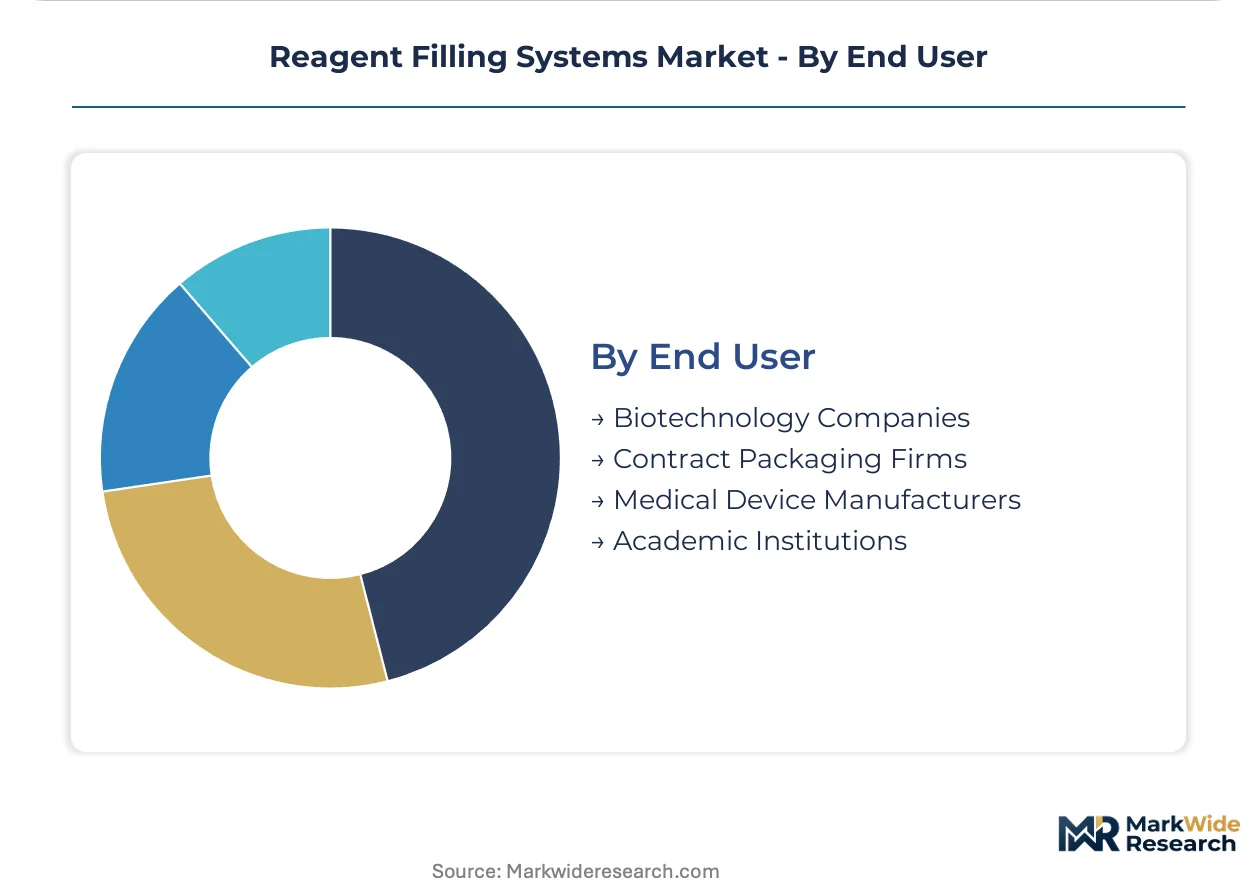
- Biotechnology Companies:Integrated drug developers and gene therapy specialists specify single-use fluid path assemblies to eliminate cross-contamination between monoclonal antibody and cell therapy campaigns. Swiss and German facilities concentrate procurement authority with engineering teams capable of IQ/OQ/PQ execution.
- Contract Packaging Firms:Multi-client CDMOs prioritize rapid format changeover and modular isolator configurations to accommodate diverse reagent portfolios with compressed campaign timelines.
- Medical Device Manufacturers:Lateral flow and molecular POC cartridge producers in Dutch medtech parks specify nanoliter dispensers for microfluidic channel filling.
- Academic Institutions:Research universities and institutes resist capital outlays for positive displacement systems where protocol flexibility outweighs standardization imperatives.
Biotechnology Companies command the dominant share, while Contract Packaging Firms are climbing the fastest as manufacturing outsourcing concentrates in European biotech clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA anchors European demand through IVDR compliance deadlines that force diagnostic manufacturers across Germany, Switzerland, and the Netherlands to accelerate equipment replacement cycles.
Germany
Diagnostic laboratories in Munich and Hamburg are retrofitting filling lines to meet EMA traceability requirements. The country's national pharmaceutical regulator enforces EU GMP Annex 1 standards for aseptic processing. Bavaria's biotech manufacturing corridor around Munich concentrates procurement of fully automatic systems with embedded electronic batch records.
Switzerland
Gene therapy CDMOs in Basel are commissioning dedicated filling lines for viral vector suspensions. Swissmedic maintains alignment with EMA standards while imposing additional notification requirements on clinical diagnostic equipment. The Basel biotech cluster drives demand for ultra-gentle piston pumps with validated low-shear profiles.
Netherlands
Contract manufacturers in Leiden are tightening volumetric accuracy specifications to ±0.5% for molecular diagnostic reagents. REACH chemical compliance frameworks mandate extractables testing for all fluid-contact materials. Dutch medtech parks around Eindhoven are migrating microfluidic filling from manual pipetting to automated nanoliter dispensers.
United States
Pharmaceutical producers in Massachusetts and North Carolina are upgrading isolator-integrated filling systems to satisfy FDA 21 CFR Part 11 data integrity requirements. The FDA's emphasis on electronic batch records drives replacement of legacy gravity-based equipment. Boston's biotech corridor concentrates demand for single-use fluid path assemblies that eliminate cross-contamination risks.
China
Domestic biotech facilities in Shanghai and Suzhou are importing precision dosing modules to meet NMPA standards for injectable biologics. The national medical products administration tightens contamination control specifications for cell therapy manufacturing. The Yangtze River Delta biotech cluster is localizing supply chains for positive displacement pump components.
Reagent Filling Systems Market Competitive Landscape
Capability concentration sits with precision engineering specialists; scale advantage sits with diversified life science conglomerates. The market structures around three tiers: integrated automation platforms, single-use assembly specialists, and precision dosing module providers. Consolidation pressure favors players with pre-validated material libraries and in-house IQ/OQ/PQ execution capabilities. Dominant competitive moves include portfolio diversification into gene therapy applications and strategic partnerships with isolator enclosure suppliers.
Among diversified life science conglomerates, Thermo Fisher Scientific anchors the integrated automation platform tier. Sartorius AG and Eppendorf AG occupy positions within the German precision engineering cluster, representing contrasting archetypes of single-use assembly specialization versus research-scale precision dosing. These three exemplify how European engineering heritage combines with pharmaceutical regulatory proximity to shape competitive positioning.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Sartorius AG |
| Eppendorf AG |
| Hamilton Company |
| Bio-Rad Laboratories |
| Nichrome Packaging Solutions |
| Robert Bosch |
| Cozzoli Machine |
| National Oilwell Varco |
| Others |
Value Network & Pricing Analysis
Precision motion control component suppliers cluster in southern Germany and northern Italy, anchoring margin capture upstream while system integrators downstream face compressed economics on mid-tier equipment lines. This geographic concentration of mechatronics engineering capability creates asymmetric pricing power that favors OEMs with captive sourcing relationships over smaller integrators exposed to spot procurement.
Pricing Analysis
Price spreads between Swiss precision-engineered systems and Asian-imported alternatives exceed threefold at equivalent throughput specifications. Three-tier pricing structure across premium, standard, and economy levels separates isolator-integrated pharmaceutical lines from research-scale benchtop units. Cost compression in mid-tier semi-automatic systems is intensifying because contract manufacturers prioritize campaign flexibility over capital intensity. Academic institutions exhibit highest price sensitivity, while gene therapy CDMOs demonstrate lowest sensitivity due to product value justification.
Supply Chain Analysis
Tariff exposure between precision component suppliers in Germany and system assemblers in Switzerland dominates supply chain risk calculus for European biotech equipment procurement. Manufacturing draws from specialized pump housing foundries in Italy, ceramic cylinder suppliers in Germany, and fluoropolymer seal manufacturers in France. Single-source vulnerability concentrates in qualified isolator enclosure providers located exclusively in southern Germany and northern Italy. Distribution runs through OEM direct sales for pharmaceutical accounts and specialized life science distributors for research-scale buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reagent filling systems market is cycling through an equipment replacement wave as EMA IVDR compliance deadlines force diagnostic manufacturers to retire legacy gravity-based lines. This regulatory-driven refresh cycle creates defensive opportunity for incumbents with pre-validated material libraries and pre-positioned service infrastructure.
For Market Incumbents: Harden competitive moats by deepening backward integration into ceramic piston manufacturing to secure supply continuity against Italian foundry bottlenecks. Accelerate certification investment for REACH-compliant fluoropolymer alternatives to PTFE, creating switching costs for customers facing extractables testing burdens. Gene therapy viral vector applications represent the most defensible expansion vector given shear-sensitivity requirements that peristaltic alternatives cannot satisfy.
For New Entrants and Emerging Players: Mid-scale contract packaging firms in the Netherlands represent the most penetrable entry point, as these buyers prioritize rapid format changeover over isolator integration and accept higher service intensity in exchange of lower capital outlays. Automated nanoliter dispensers for point-of-care diagnostic cartridge manufacturing in Dutch medtech parks offer second-mover opportunity where precision requirements are tightening but incumbent positioning remains fluid. A calibration-service-first go-to-market model builds relationships before capital equipment commitment.
For Investors and Strategic Acquirers: Capital is best deployed toward precision dosing module specialists with validated low-shear pump architectures and in-house IQ/OQ/PQ execution capabilities that pharmaceutical producers increasingly require. Long-term viability across the analysis window rests on regulatory proximity to EMA and FDA frameworks rather than cost-position alone. The signal to watch as inflection indicator is consolidation activity among isolator enclosure suppliers, as captive access to qualified enclosure manufacturing represents the binding constraint on system delivery timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Integration Partnership | Qualified enclosure access from southern German suppliers compresses system delivery timelines for pharmaceutical producers. |
| Single-Use Fluid Path Expansion | Disposable assembly qualification reduces cross-contamination risk for multi-product biotech facilities in Swiss clusters. |
| Embedded Sensor Network Deployment | Real-time volumetric verification with load cells and flow sensors digitizes quality assurance for German diagnostic manufacturers. |
| REACH-Compliant Material Qualification | Fluoropolymer alternatives to PTFE with pre-submitted ECHA migration data packages accelerate customer regulatory approval. |
| Gene Therapy Application Engineering | Ultra-gentle piston validation for AAV and lentiviral suspensions opens dedicated line demand from Basel CDMOs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with diagnostic laboratory directors, pharmaceutical manufacturing engineers, contract manufacturing procurement leads, and precision equipment service technicians. Secondary validation drew from EMA IVDR guidance documents, FDA 21 CFR Part 11 compliance frameworks, EU GMP Annex 1 technical interpretations, and Swissmedic notification requirements. Bottom-up equipment shipment analysis was triangulated against top-down pharmaceutical and diagnostic manufacturing capacity expansion tracking.
Calibration against historical replacement cycles informed the projection framework across the modeling period. Segmentation dimensions included automation tier, pump technology mechanism, end-use application environment, and geographic regulatory cluster. CAGRs were derived from equipment replacement velocity analysis tied to compliance deadline phasing. Industry-specific forecast inputs incorporated cleanroom construction pipeline data and precision motion control engineering labor market tightness in Basel and Munich.
Stress conditions across stainless steel component cost volatility, cleanroom construction timeline extension, and peristaltic pump persistence in research segments were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EMA IVDR enforcement consistency and REACH chemical compliance evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Oxidation Stability Analyzer Market
Testing Equipment
Global Silica Analyzer Market
Testing Equipment
Test Point Hoses Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Ambient Temperature Gel Permeation Chromatography Market
Testing Equipment
2D Chromatography Market
Testing Equipment
Solar Testing Equipment Market
Testing Equipment
Lubricant Testing Machine Market
Testing Equipment
Dynamic Vapor Sorption Analyzer Market
Testing Equipment
Viscometer Market
Testing Equipment
Chemical Detector Market
Testing Equipment
Flash Point Apparatus Market
Testing Equipment
Particle Size Analysis Market
Testing Equipment
Total Reflection X Ray Fluorescence (TXRF) Spectrometer Market
Testing Equipment
Gas Calorimeter Market
Testing Equipment
Chromatography Systems Market