
 Laboratory Filtration Equipment and Supplies Market | 2026-2036
Laboratory Filtration Equipment and Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Filtration Equipment and Supplies Market Outlook
Membrane pore-size standardization is narrowing the gap between research-grade and GMP-compliant filtration platforms. Thermo Fisher Scientific leverages its vertically integrated bioproduction portfolio to control upstream filter supply chains. Sartorius AG anchors European demand through specialized single-use assemblies for cell-culture clarification. Danaher Corporation competes across diagnostics and bioprocess segments with membrane portfolios spanning sterile to depth filtration.
Laboratory filtration equipment and supplies encompass membrane filters, syringe filters, cartridges, and vacuum filtration systems engineered from polyethersulfone, polyvinylidene fluoride, or regenerated cellulose matrices with pore ratings from 0.1 to 5.0 micrometers, designed to remove particulates, microorganisms, or aggregates from liquid and gas streams in analytical and production workflows. Membrane filters capture the largest margin pool where biopharma sterile processing demands 0.22-micron absolute ratings and integrity-test documentation. Syringe filters sustain steady replacement-cycle revenue from HPLC and sample-preparation labs requiring low-extractable, certified disposable formats. Environmental testing and food-safety laboratories drive particle-removal and clarification applications with escalating regulatory sample-throughput requirements.
FDA 21 CFR Part 211, EMA GMP Annex 1, and ISO 13485 quality-system standards shape filter validation protocols, extractables testing, and supplier-audit obligations for sterile drug manufacturers. The EPA and WHO drinking-water and analytical-method guidelines extend demand for certified membrane products in environmental and public-health laboratories. Stakeholders must monitor evolving regulatory harmonization between US and European sterile-processing standards to anticipate qualification-cost shifts and supplier-consolidation pressures.
Market Dynamics
Single-use filtration architectures are displacing stainless-steel systems as biopharmaceutical manufacturers retool for modular, campaign-based manufacturing. This shift compresses validation timelines while fragmenting supplier relationships across membrane, housing, and integrity-test equipment vendors.
Growth Catalysts
- FDA 21 CFR Part 211 sterile-processing mandates:Biologics manufacturers must demonstrate filter integrity with documented test protocols, forcing replacement of legacy depth-filtration trains.
- Cell-culture clarification workflows:Viral vector production for gene therapies demands absolute-rated membranes with low protein-binding polyethersulfone matrices.
- German bioproduction cluster expansion:mRNA vaccine manufacturing infrastructure in Marburg and Dresden drives concentrated procurement of GMP-certified single-use assemblies.
Market Restraints
- Specialty polymer supply concentration:Polyvinylidene fluoride resin production concentrates among three chemical conglomerates, exposing membrane manufacturers to feedstock allocation volatility.
- Extractables validation burden:EMA GMP Annex 1 requires comprehensive chemical characterization studies that extend qualification timelines by 12-18 months for new filter formats.
- Reusable system residual value:Contract development and manufacturing organizations retain stainless-steel filtration skids to service legacy small-molecule clients, slowing single-use conversion.
Strategic Opportunities
- Continuous bioprocessing adoption:Perfusion cell-culture systems require integrated filtration-concentration loops that bypass traditional batch clarification entirely.
- Point-of-care diagnostic manufacturing:Microfluidic cartridge producers in South Korea seek membrane-integrated consumables with sub-micron precision.
- EPA drinking-water method updates:Revised analytical protocols for PFAS and microplastics mandate certified membrane products for environmental testing laboratories.
Industry Challenges
- Integrity-test technician certification:Bubble-point and diffusion-test operators require specialized training that outpaces vocational program output in key manufacturing regions.
- Legacy equipment interoperability:Single-use filtration manifolds must interface with existing stainless-steel vessel geometries without triggering requalification of entire production trains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Filtration Equipment and Supplies Market |
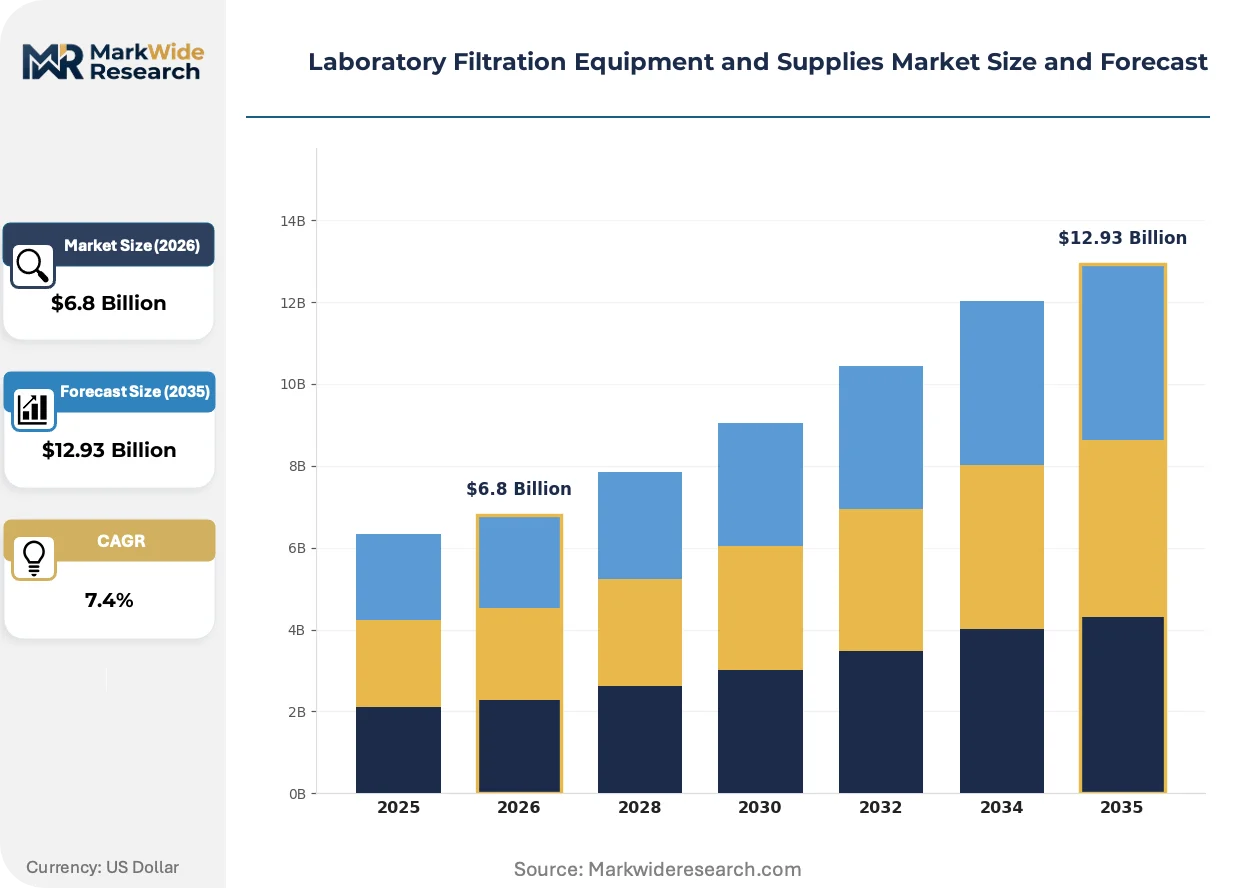
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filters, Syringe Filters, Cartridges, Vacuum Filters End User: Pharmaceuticals, Biotechnology, Environmental Testing, Food & Beverage Application: Microbial Retention, Particle Removal, Sterilization, Clarification Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Thermo Fisher Scientific Inc., 3M, Sartorius AG, Pall Corporation, Cytiva, Danaher Corporation, Repligen Corporation, MilliporeSigma, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Filtration Equipment and Supplies Market Strategic Shifts
Filter performance verification is migrating from offline laboratory testing to in-line sensor integration, collapsing the feedback loop between filtration operation and batch-release decisions. This convergence of membrane engineering with process analytical technology redefines how manufacturers guarantee sterile boundaries.
Automated bubble-point integrity testers equipped with pressure-decay algorithms and electronic batch records are digitizing compliance documentation for biopharmaceutical sterile processing. Contract manufacturers in Ireland and Singapore deploy these systems to eliminate manual transcription errors during filter qualification. The technology is digitizing audit trails while compressing batch-review timelines from days to hours.
EMA's revised GMP Annex 1, effective August 2022, mandates contamination-control strategies with formal risk assessments for filtration-critical control points. Sterile drug manufacturers must now document filter selection rationale, sterilization method validation, and integrity-test frequency in site master files. Small-molecule injectable producers in Italy and Spain face the steepest compliance ramps where legacy documentation practices prove inadequate.
Consolidated procurement contracts now bundle membrane filters with integrity-test equipment and consumable replenishment under multi-year service agreements. Large biopharmaceutical sponsors in Massachusetts and California negotiate these arrangements to lock in supply security and standardize operator training across global manufacturing networks. This model displaces spot purchasing through distribution intermediaries, concentrating purchasing power among vertically integrated filtration suppliers.
Laboratory Filtration Equipment and Supplies Market Segmentation
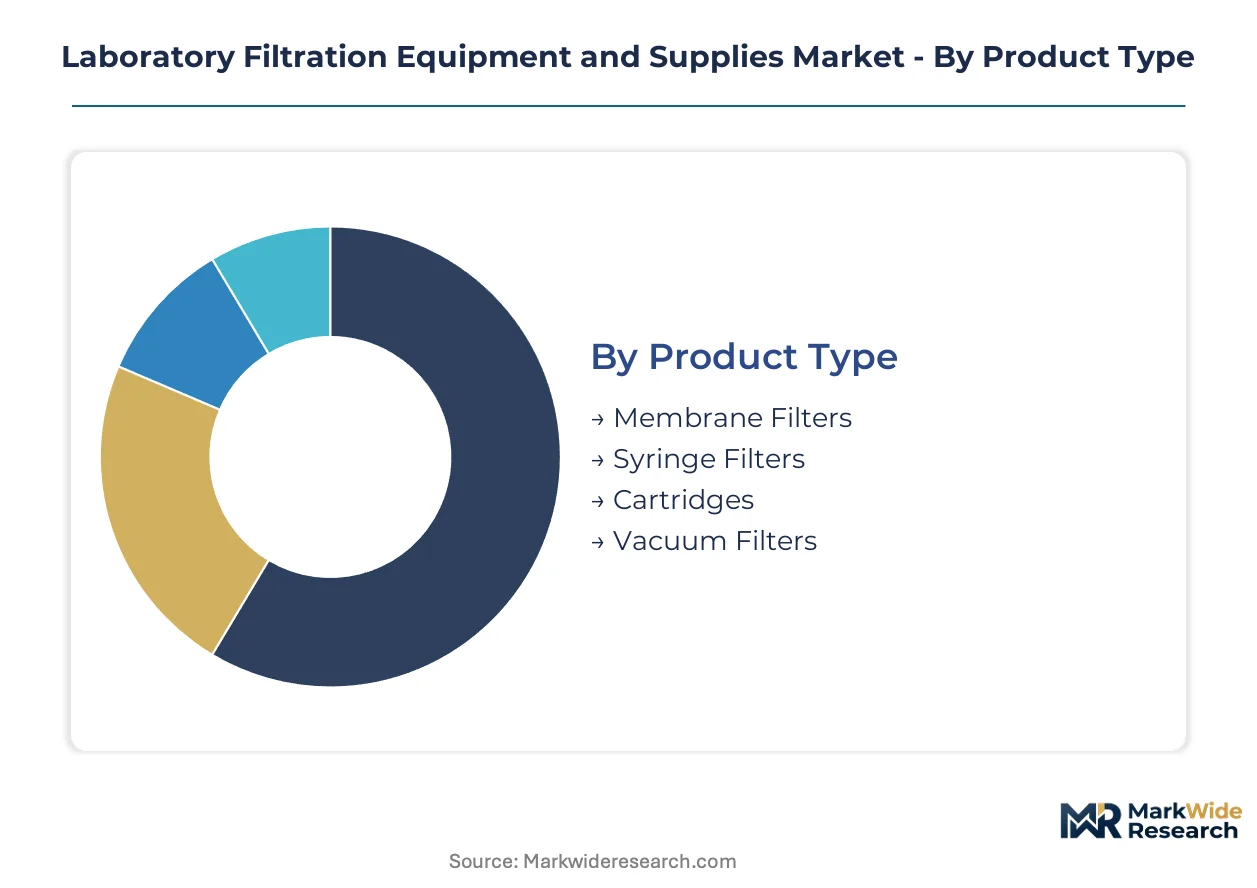
Segmentation in laboratory filtration reveals distinct replacement cycles and margin profiles across product architectures. Pharmaceutical procurement patterns diverge sharply from environmental testing workflows, forcing suppliers to maintain parallel supply chains with incompatible certification requirements.
Product Type:
Membrane filters turn over fastest in bioprocess campaigns while vacuum systems persist for years; syringe filters occupy the middle ground with predictable batch-driven replacement.
- Membrane Filters:Engineered from polyethersulfone, polyvinylidene fluoride, or regenerated cellulose matrices with pore ratings from 0.1 to 5.0 micrometers. German mRNA vaccine manufacturers in Marburg and Dresden drive concentrated procurement of GMP-certified single-use membrane assemblies with 0.22-micron absolute ratings and mandatory integrity-test documentation.
- Syringe Filters:Low-extractable certified disposable formats designed for HPLC and sample-preparation workflows. Environmental testing laboratories in Massachusetts and California sustain steady replacement-cycle revenue through escalating regulatory sample-throughput requirements.
- Cartridges:Depth-filtration and pleated configurations for high-volume bioprocess clarification with validated extractables profiles.
- Vacuum Filters:Reusable glass or polycarbonate housings with replaceable membrane inserts for bulk sample processing in academic and government research settings.
Membrane filters dominate installed base. Syringe filters are where expansion concentrates.
End User:
Cost tiers stratify sharply between validated biopharma supply and commodity environmental testing procurement, with biotechnology occupying the premium middle ground.
- Pharmaceuticals:Sterile drug manufacturers face FDA 21 CFR Part 211 and EMA GMP Annex 1 mandates requiring documented filter integrity protocols, forcing replacement of legacy depth-filtration trains with validated single-use architectures.
- Biotechnology:Viral vector production for gene therapies demands absolute-rated membranes with low protein-binding polyethersulfone matrices and comprehensive extractables characterization studies extending qualification timelines.
- Environmental Testing:EPA drinking-water method updates for PFAS and microplastics mandate certified membrane products with batch-specific performance documentation.
- Food & Beverage:Microbiological safety testing drives particle-removal applications with ISO-compliant filtration workflows.
Pharmaceuticals command premium pricing tiers. Environmental testing is climbing the fastest on regulatory method expansion.
Application:
Volume concentration aligns with sterility assurance requirements, where microbial retention commands exhaustive validation and particle removal operates on functional performance alone.
- Microbial Retention:Absolute-rated 0.22-micron or 0.45-micron membranes with bubble-point and diffusion-test validation for sterile boundary assurance in injectable drug manufacturing.
- Particle Removal:Depth filters and nominal-rated membranes for clarification workflows where functional performance rather than sterility assurance drives specification.
- Sterilization:Steam-in-place or gamma-irradiatable filtration trains with validated sterilization method documentation in site master files.
- Clarification:Cell-culture harvest and upstream processing applications requiring low-binding surfaces for high-yield biologic recovery.
Microbial retention dominates installed base. Clarification is where expansion concentrates on perfusion system adoption.
Distribution Channel:
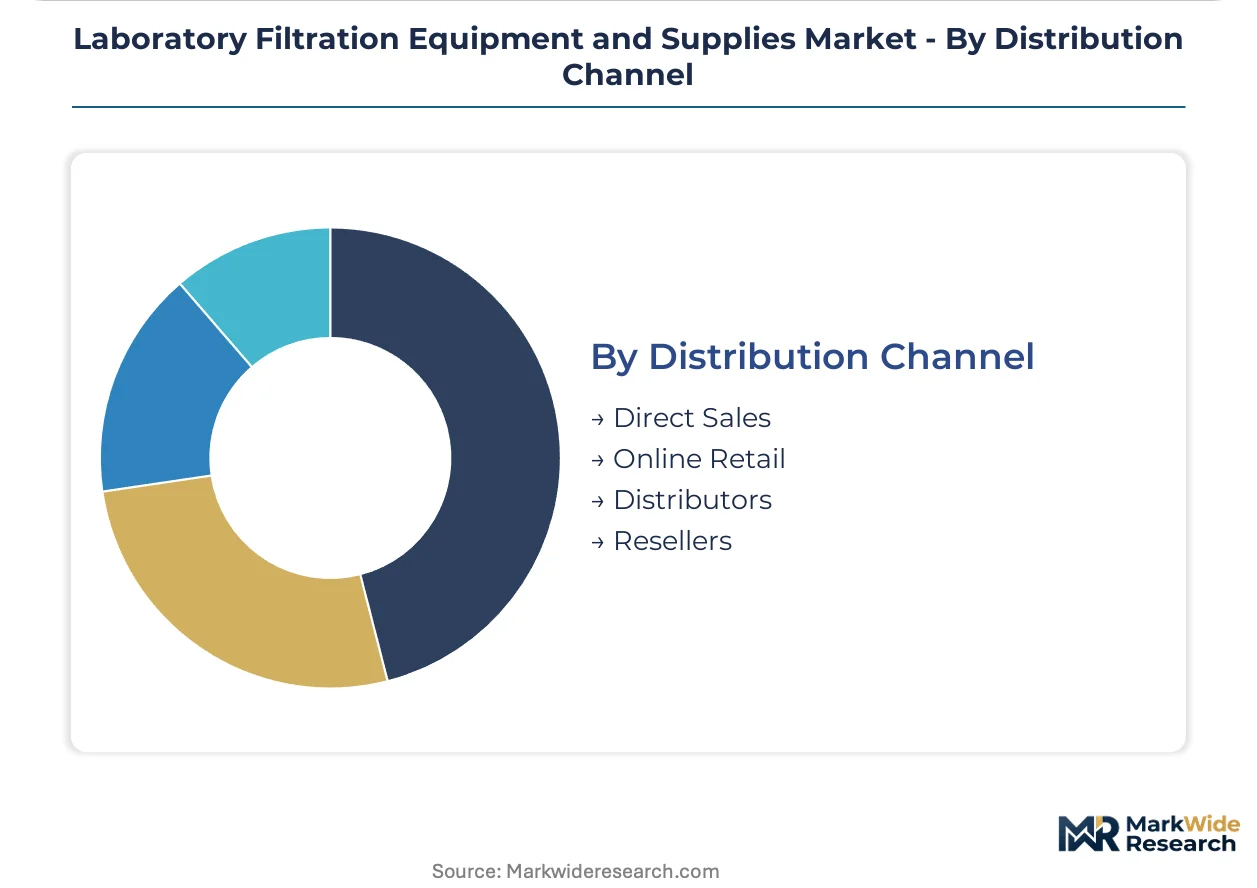
Customer type determines channel economics, with direct sales capturing enterprise biopharma contracts and online retail fragmenting academic and small-lab procurement.
- Direct Sales:Multi-year service agreements bundling membrane filters with integrity-test equipment and consumable replenishment, negotiated by large biopharmaceutical sponsors to lock in supply security.
- Distributors:Regional inventory positioning for environmental testing and food-safety laboratories requiring rapid turnaround on certified membrane products.
- Online Retail:E-commerce platforms serving academic researchers and small diagnostic manufacturers with catalog-standard syringe filters and vacuum filtration consumables.
- Resellers:Value-added integrators configuring filtration manifolds for interoperability with legacy stainless-steel vessel geometries.
Direct sales dominate installed base. Online retail is gaining share fastest on small-lab digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German membrane manufacturers supply single-use filtration assemblies to biopharma facilities in Massachusetts and California, while Chinese producers dominate cost-sensitive environmental testing consumables for Southeast Asian laboratories.
United States
FDA 21 CFR Part 211 sterile-processing mandates compel biologics manufacturers in Massachusetts to replace legacy depth-filtration trains with validated single-use architectures requiring documented integrity-test protocols. Greater Boston hosts concentrated gene-therapy manufacturing infrastructure driving procurement of absolute-rated polyethersulfone membranes.
Germany
EMA GMP Annex 1 contamination-control strategies force sterile drug manufacturers to document filter selection rationale and sterilization validation in site master files. The Marburg and Dresden mRNA vaccine clusters anchor European demand for GMP-certified single-use membrane assemblies with mandatory extractables characterization.
China
NMPA bioprocessing guidelines and dual carbon goals accelerate domestic substitution of imported filtration consumables in cell-culture clarification workflows. Yangtze River Delta biopharma parks in Shanghai and Suzhou expand perfusion system adoption requiring integrated filtration-concentration loops.
Japan
PMDA quality-system standards shape validation protocols for sterile boundary assurance in injectable drug manufacturing. Osaka-Kobe pharmaceutical corridors sustain demand for low-extractable syringe filters in high-throughput HPLC sample-preparation workflows.
South Korea
MFDS regulatory harmonization with FDA standards enables domestic filter manufacturers to supply microfluidic cartridge producers seeking membrane-integrated consumables with sub-micron precision. Seoul Capital Area diagnostic manufacturers drive point-of-care filtration component procurement.
Laboratory Filtration Equipment and Supplies Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated filtration specialists capable of bundling membrane products with integrity-test equipment and validation services. Three strategic archetypes dominate: diversified life-science conglomerates with captive bioprocess portfolios, specialized membrane engineering firms with polymer science depth, and contract manufacturers leveraging geographic cost advantages. Competitive moves concentrate on multi-year service agreements locking in supply security and backward integration into specialty polymer resin sourcing.
Among diversified life-science conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify the integrated-platform archetype, while Sartorius AG occupies a position within the specialized membrane engineering tier. These three anchors represent distinct competitive vectors: conglomerate scale and cross-selling leverage versus focused polymer science expertise versus European regulatory proximity.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| 3M |
| Sartorius AG |
| Pall Corporation |
| Cytiva |
| Danaher Corporation |
| Repligen Corporation |
| MilliporeSigma |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
German and Japanese polymer resin manufacturers control polyethersulfone and polyvinylidene fluoride feedstock supply, concentrating margin capture upstream of membrane filter assembly while biopharmaceutical buyers absorb premium pricing for GMP-certified single-use architectures with mandatory integrity-test documentation.
Pricing Analysis
Prior-generation stainless-steel filtration skids trade at depreciation-driven residual values, current-generation single-use membrane assemblies command three-tier pricing structure across premium, standard, and economy levels, and next-generation integrated filtration-concentration loops for perfusion systems carry technology-premium markups. Price differentiation rests on FDA 21 CFR Part 211 certification tier and volume scale under multi-year service agreements. Pricing pressure stems from specialty polymer feedstock allocation volatility as three chemical conglomerates dominate resin production. Environmental testing laboratories exhibit highest price sensitivity due to commodity procurement patterns, while gene-therapy manufacturers show lowest sensitivity given sterility-assurance imperatives.
Supply Chain Analysis
Contract manufacturers in Ireland and Singapore hold concentrated capacity for automated bubble-point integrity tester assembly and single-use manifold configuration. Membrane manufacturing concentrates in Germany, the United States, and China, with Chinese producers dominating cost-sensitive environmental testing consumables. Raw material dependencies center on polyethersulfone resin, polyvinylidene fluoride polymer, and regenerated cellulose matrices. Single-source vulnerability in specialty polymer feedstock exposes membrane manufacturers to allocation disruptions. Distribution runs through direct sales for enterprise biopharma contracts, regional distributors for environmental testing laboratories, and online retail for academic researchers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as consolidated procurement contracts bundle membrane filters with integrity-test equipment and validation services, creating interoperability lock-in that favors vertically integrated suppliers with captive polymer science capabilities.
For Market Incumbents: Harden supply security through backward integration into polyethersulfone and polyvinylidene fluoride resin sourcing, eliminating feedstock allocation vulnerability to the three dominant chemical conglomerates. Expand GMP-certified single-use assembly capacity in the Marburg and Dresden clusters to capture mRNA vaccine manufacturing procurement. Anchor customer relationships through multi-year service agreements bundling membrane products with integrity-test equipment and operator training standardization. For New Entrants and Emerging Players: Southeast Asian environmental testing laboratories represent underpenetrated demand for certified membrane products with batch-specific performance documentation at price points below German and US incumbents. Target microfluidic cartridge producers in South Korea seeking membrane-integrated consumables with sub-micron precision for point-of-care diagnostic manufacturing. Pursue regulatory harmonization with FDA 21 CFR Part 211 protocols as the primary go-to-market angle for biopharma qualification. For Investors and Strategic Acquirers: Capital is best deployed toward specialized membrane engineering firms with polymer science depth and established extractables characterization capabilities, as EMA GMP Annex 1 mandates extend qualification timelines and raise barriers to new filter format entry. Long-term viability favors suppliers capable of bundling membrane products with process analytical technology integration and automated compliance documentation. Monitor integrity-test technician certification program output as an inflection indicator for operational scalability constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Polymer Resin Sourcing | Eliminates feedstock allocation volatility from three dominant chemical conglomerates controlling polyethersulfone and polyvinylidene fluoride supply. |
| Multi-Year Service Agreement Expansion | Locks in supply security for Massachusetts and California biopharmaceutical sponsors while displacing spot purchasing through distribution intermediaries. |
| Automated Compliance Documentation Development | Compresses batch-review timelines from days to hours for Irish and Singaporean contract manufacturers deploying electronic batch records. |
| Perfusion System Filtration-Concentration Loop Integration | Captures continuous bioprocessing adoption bypassing traditional batch clarification in Yangtze River Delta biopharma parks. |
| Extractables Characterization Capability Investment | Addresses EMA GMP Annex 1 mandates requiring comprehensive chemical characterization studies extending qualification timelines by 12-18 months. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with membrane engineering directors, bioprocess procurement leads at pharmaceutical manufacturers, regulatory affairs specialists, and integrity-test equipment operators; and secondary validation through FDA 21 CFR Part 211 guidance documents, EMA GMP Annex 1 revision texts, EPA drinking-water method updates, ISO 13485 quality-system standards, and SEC filings from diversified life-science conglomerates. Bottom-up triangulation across product-type installed bases and top-down validation against end-user procurement patterns ensured cross-verification.
Forecast inputs considered membrane filter replacement cycles, syringe filter batch-driven demand, vacuum system persistence in academic settings, and single-use architecture conversion rates across biopharmaceutical manufacturing. Segmentation dimensions spanned product architecture, end-user certification tier, application sterility-assurance requirement, and distribution channel structure. CAGRs were derived from regression analysis of historical procurement data projected across the analysis window, incorporating German mRNA vaccine cluster expansion, Chinese domestic substitution acceleration, and EPA method update implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by membrane engineering specialists or sudden specialty polymer feedstock reallocation by chemical conglomerates would shift outcomes. Quarterly review of integrity-test technician certification program output, EMA GMP Annex 1 enforcement variance across member states, and NMPA bioprocessing guideline revision cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Residue Testing Market
Testing Equipment
US Eddy-Current Testing Market
Testing Equipment
Binary High Pressure Gradient Liquid Chromatography System Market
Testing Equipment
Global Chromatography Instruments Market
Testing Equipment
Rheometer Market
Testing Equipment
Fibrin Degradation Product (Fndp) Assays Market
Testing Equipment
Automated Solid Phase Extraction Systems Market
Testing Equipment
Grease Analyzer Market
Testing Equipment
Flammability Tester Market
Testing Equipment
Gold Tester Market
Testing Equipment
Global Liquid Chromatography Instruments Market
Testing Equipment
Wood Moisture Tester Market
Testing Equipment
Cone Calorimeter Market
Testing Equipment
Brittleness Tester Market
Testing Equipment
Sand Testing Equipments Market
Testing Equipment
Sample Preparation Market