
 United States Automotive OEM Coatings Market | 2026-2036
United States Automotive OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
United States Automotive OEM Coatings Market Analytics
Skilled applicator labor availability is reorganizing how OEM coating lines operate across the United States. PPG Industries sustains broad manufacturing scale across multiple substrate technologies. Axalta Coating Systems specializes in dedicated automotive refinish and OEM integrated solutions. BASF SE anchors its position through deep R&D intensity in resin chemistry and color matching systems.
United States Automotive OEM Coatings are formulated systems comprising pigmented base coats, transparent clear coats, adhesion-promoting primers, and functional specialty layers, typically applied through robotic electrostatic spray or dip-coating processes at film builds between 25 and 150 microns to provide corrosion protection, aesthetic finish, and durability for vehicle bodies. Waterborne technology leads in new line installations due to EPA VOC compliance requirements, while UV-cured coatings represent the fastest-growing technology segment for electric vehicle battery enclosure applications. Clear coat formulations command concentrated margin pools because of their optical performance specifications and weathering resistance demands.
EPA, OSHA, and California Air Resources Board frameworks govern volatile organic compound limits, workplace exposure thresholds, and regional air quality standards that directly determine coating formulation eligibility and application equipment investments. Tier-1 suppliers and manufacturers must validate product performance against these overlapping standards before production line qualification. Stakeholders should monitor how emerging per- and polyfluoroalkyl substance restrictions may force reformulation cycles across corrosion-resistant primer categories.
Market Dynamics
Waterborne coating technology transitions are compressing capital allocation cycles across United States automotive OEM coating lines as EPA VOC mandates force simultaneous equipment replacement and formulation redevelopment.
Growth Catalysts
- EPA VOC Compliance Deadlines:Federal emission limits are accelerating waterborne system adoption across new line installations and retrofit projects.
- Electric Vehicle Substrate Requirements:Battery enclosure manufacturers specify UV-cured functional coatings for thermal management and dielectric protection.
- Michigan-Ohio-Tennessee Manufacturing Corridors:Concentrated OEM assembly capacity generates localized demand density for integrated coating supply.
Market Restraints
- Titanium Dioxide Feedstock Volatility:Pigment cost swings compress margin stability for white and light-tone base coat formulations.
- Applicator Labor Pool Contraction:Skilled electrostatic spray technicians are concentrating in specific metropolitan manufacturing zones, creating regional supply bottlenecks.
- California Air Resources Board Regional Preemption:Stricter-than-federal standards fragment formulation portfolios and increase compliance complexity for national suppliers.
Strategic Opportunities
- UV-Cured Battery Enclosure Coatings:Electric vehicle thermal management applications represent underpenetrated specification territory with high technical barriers.
- Infrared Reflective Pigment Systems:Dark-color exterior finishes that reduce cabin thermal load are gaining specification traction in sun-belt assembly plants.
- Tennessee-Kentucky Corridor Expansion:New OEM capacity announcements in this region are outpacing established coating infrastructure deployment.
Industry Challenges
- Robotic Application Programming Expertise:Electrostatic spray path optimization for complex vehicle geometries requires specialized simulation and commissioning capabilities that outpace training pipeline output.
- Per- and Polyfluoroalkyl Substance Reformulation Cycles:Anticipated restrictions on corrosion-resistant primer chemistries are forcing premature R&D redirection before current generation products reach amortization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Automotive OEM Coatings Market |
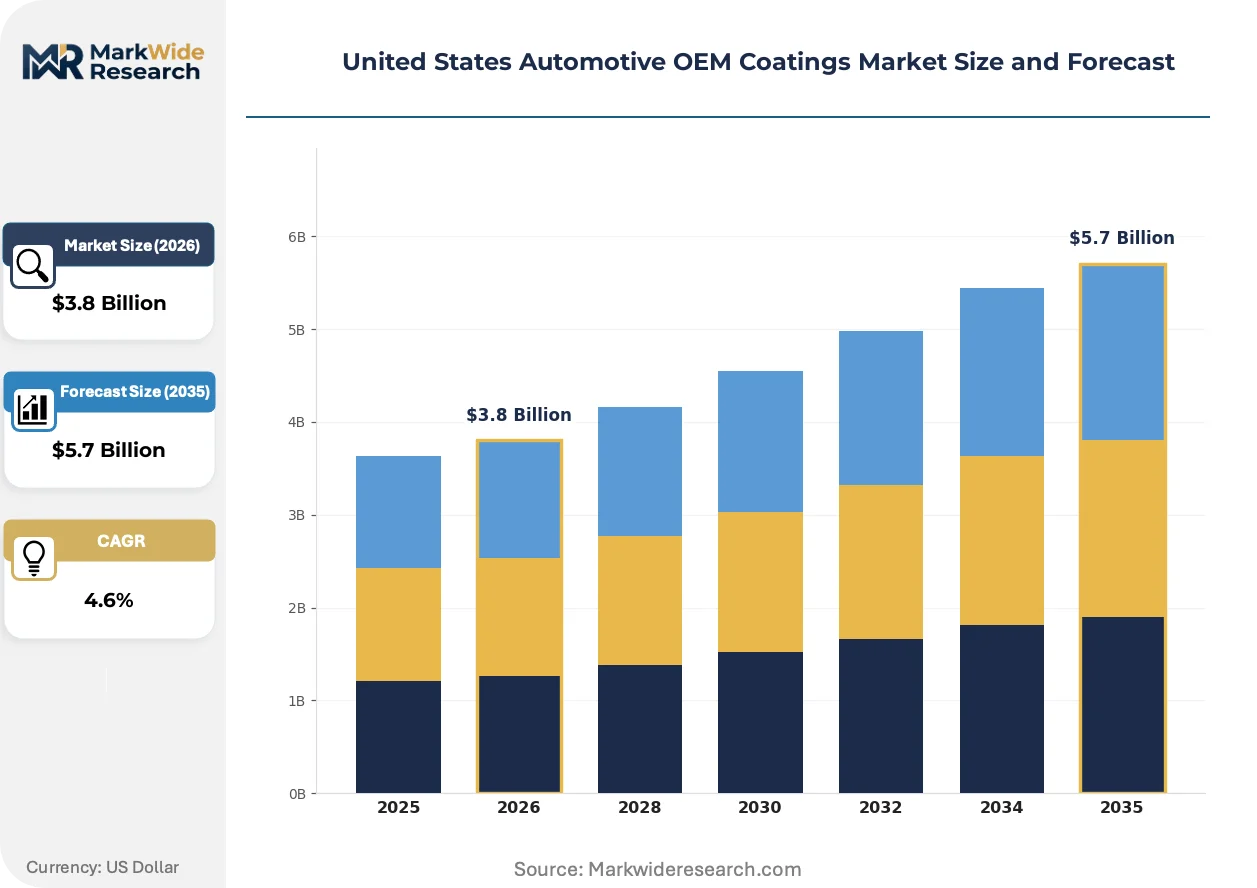
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Coat, Clear Coat, Primer Coat, Specialty Coatings Application: Passenger Vehicles, Light Commercial Vehicles, Heavy Trucks, Electric Vehicles Technology: Waterborne, Solventborne, Powder Coatings, UV-Cured Coatings End User: Tier-1 Suppliers, Manufacturers, Distributors, Aftermarket Providers |
| Companies Covered | PPG Industries Inc, BASF SE, Axalta Coating Systems, Akzo Nobel NV, The Sherwin-Williams Company, RPM International Inc, Nippon Paint Holdings Co Ltd, Kansai Paint Co Ltd, KCC Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Automotive OEM Coatings Market Evolving Landscape
Coating specification authority is migrating from OEM central engineering to tier-1 subsystem suppliers, fragmenting traditional volume commitments and accelerating formulation customization cycles.
UV-cured functional coatings for electric vehicle battery enclosures are bifurcating the protective coatings segment. Battery thermal management system manufacturers specify these chemistries for dielectric insulation and rapid processing compatibility. The technology is compressing conventional bake-cure process equipment investments while enabling in-line integration with battery pack assembly sequences.
EPA and California Air Resources Board overlapping enforcement frameworks are tightening volatile organic compound limits for primer and base coat categories. Tier-1 suppliers must validate products against dual compliance thresholds before production line qualification. Michigan and Ohio coating operations face accelerated capital deployment timelines to meet staggered regulatory phase-ins.
Specification authority decentralization is redistributing procurement influence across tier-1 subsystem integrators. Traditional OEM central engineering volume commitments are fragmenting into program-specific formulation agreements. This pattern concentrates in Tennessee and Kentucky corridor facilities where new electric vehicle platforms emphasize supplier-direct material qualification.
United States Automotive OEM Coatings Market Segmentation
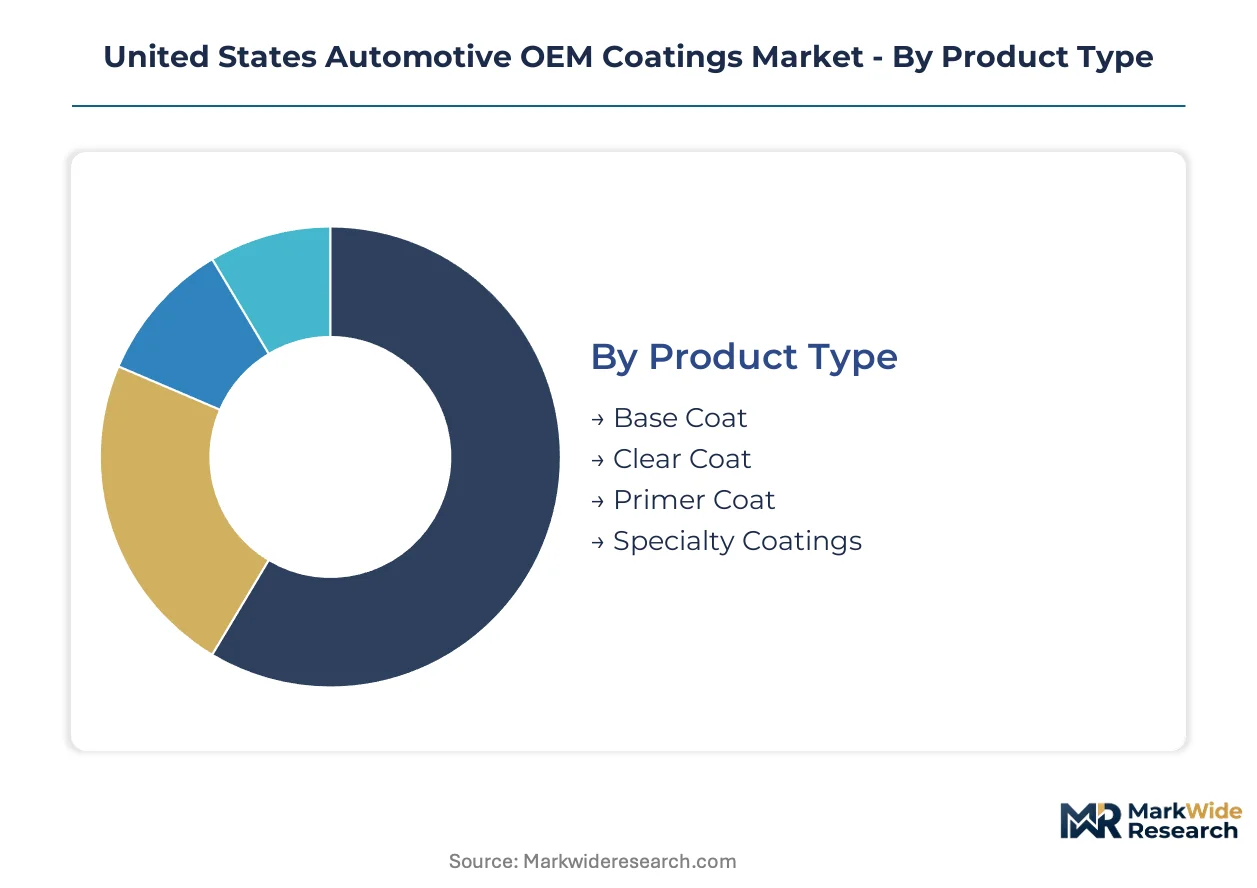
Coating specification authority is fragmenting across tier-1 subsystem suppliers, forcing suppliers to maintain parallel formulation portfolios for each segment interface. Understanding how product types, applications, technologies, and procurement channels diverge reveals where capital allocation and R&D resources face the greatest substitution pressure.
Product Type:
Waterborne clear coat formulations are displacing solventborne alternatives in new line installations, creating substitution pressure concentrated in high-gloss exterior finish specifications.
- Base Coat:Pigmented layers provide color and aesthetic definition through metallic, pearlescent, or solid-tone formulations. Demand concentrates in Michigan and Ohio assembly corridors where OEM central engineering retains specification authority over exterior color programs.
- Clear Coat:Transparent top layers deliver gloss retention, scratch resistance, and UV protection through polyurethane or acrylic-urethane chemistries. Tennessee-Kentucky corridor plants are specifying premium weathering grades for electric vehicle exterior programs, driving formulation upgrades.
- Primer Coat:Adhesion-promoting and corrosion-resistant underlayers applied to bare metal or plastic substrates.
- Specialty Coatings:Functional layers including anti-chip, sound-dampening, and battery enclosure thermal management systems.
Clear coat anchors the volume base while specialty coatings gain share at the steepest rate.
Application:
Electric vehicle platforms are reordering application priorities, with battery enclosure coatings commanding development resources previously allocated to traditional body-in-white finishes.
- Passenger Vehicles:Sedans, SUVs, and crossovers constitute the core volume segment with multi-layer coating sequences spanning primer, base, and clear coat applications. Ohio and Michigan facilities process the highest coating volumes for this category.
- Electric Vehicles:Battery electric and plug-in hybrid platforms require specialized thermal management coatings for enclosures, plus lightweight substrate-compatible primers for aluminum-intensive body structures. UV-cured functional coatings are expanding most quickly in this segment.
- Light Commercial Vehicles:Pickup trucks and delivery vans with durability-focused specifications and simplified color palettes.
- Heavy Trucks:Class 8 commercial vehicles with extended corrosion warranty requirements and fleet-specific color standardization.
Passenger vehicles anchor the volume base while electric vehicles gain share at the steepest rate.
Technology:
Capital equipment lifecycles are compressing as EPA VOC mandates force premature solventborne line obsolescence before depreciation schedules complete.
- Waterborne:Water-based resin systems with low volatile organic compound emissions, now standard for new OEM line installations. Michigan and Ohio retrofit projects are converting solventborne capacity to meet EPA compliance deadlines.
- UV-Cured Coatings:Photoinitiator-activated systems curing in seconds under ultraviolet exposure, specified for battery enclosure applications where thermal sensitivity prohibits bake ovens. Tennessee corridor plants are integrating these lines with battery pack assembly sequences.
- Solventborne:Traditional solvent-based systems facing phased capacity retirement across federal and California regulatory jurisdictions.
- Powder Coatings:Dry film applications primarily specified for underbody and wheel well corrosion protection.
Waterborne technology anchors the volume base while UV-cured coatings gain share at the steepest rate.
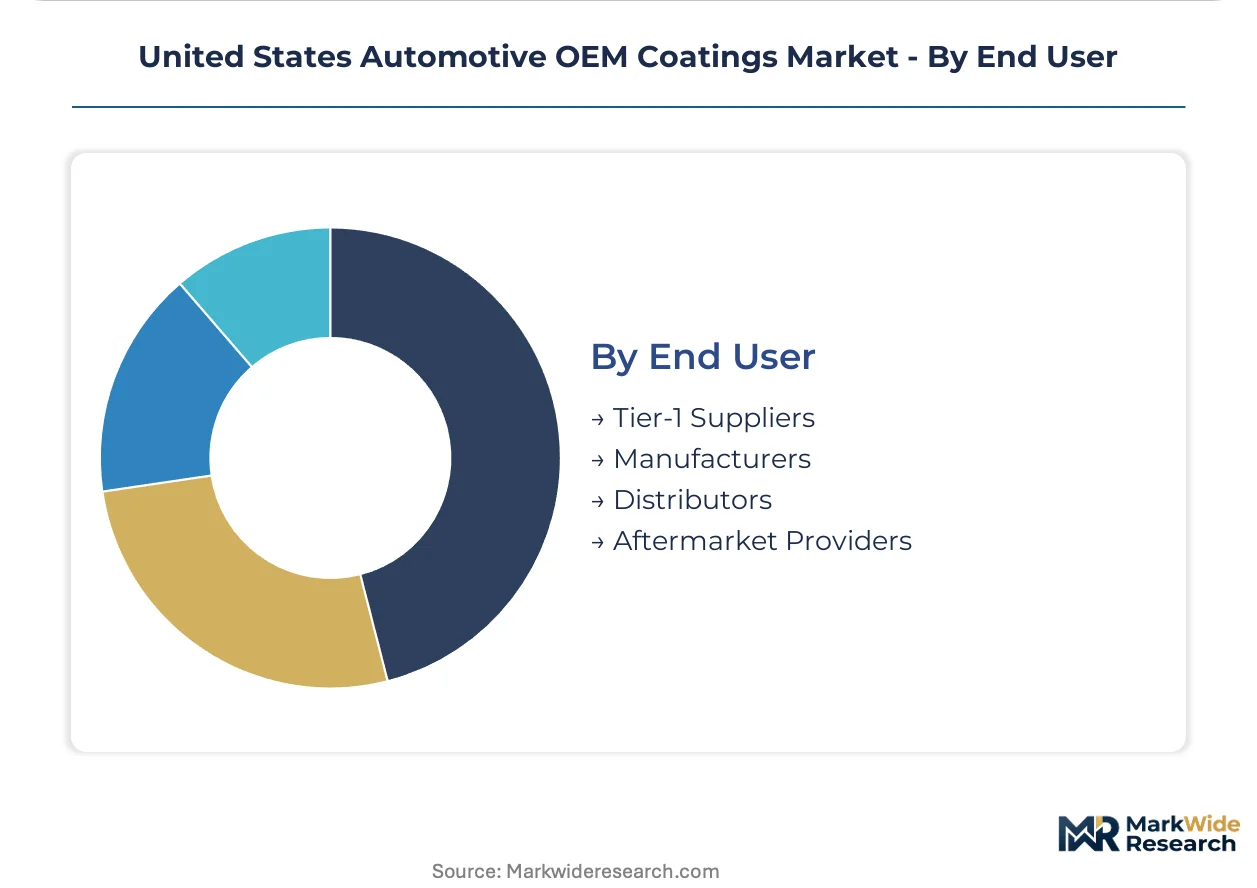
End User:
Procurement influence is migrating from OEM central engineering to tier-1 subsystem integrators, fragmenting traditional volume commitments into program-specific agreements.
- Tier-1 Suppliers:Subsystem integrators including bumper, battery enclosure, and closure panel manufacturers with direct coating specification authority. Kentucky and Tennessee electric vehicle supply bases are accelerating this decentralization pattern.
- Manufacturers:OEM-owned and operated coating facilities retaining control over exterior body-in-white finish programs.
- Distributors:Regional coating material logistics providers serving smaller tier-2 and tier-3 component suppliers.
- Aftermarket Providers:Refinish and repair coating suppliers operating outside OEM new vehicle production channels.
Manufacturers anchor the volume base while tier-1 suppliers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coating consumption patterns diverge sharply across United States manufacturing corridors, with Michigan and Ohio facilities prioritizing high-volume waterborne conversions while Tennessee-Kentucky plants pioneer UV-cured battery enclosure specifications.
Michigan
Detroit-area assembly plants drive the highest coating volume density for traditional passenger vehicle programs. EPA VOC compliance deadlines are accelerating solventborne line retirements before full depreciation. Grand Rapids and Lansing coating operations face compressed capital deployment timelines to meet staggered regulatory phase-ins.
Ohio
Ohio's automotive corridor processes substantial exterior finish volumes for SUV and crossover platforms. OSHA workplace exposure thresholds govern electrostatic spray booth configurations across Cleveland and Toledo facilities. Cincinnati-area suppliers are retrofitting lines for waterborne clear coat specifications demanded by electric vehicle programs.
Tennessee
Nashville and Chattanooga assembly plants are outpacing established coating infrastructure deployment with new electric vehicle capacity announcements. California Air Resources Board regional preemption creates formulation complexity for suppliers serving multi-state OEM networks. Memphis logistics hubs concentrate distributor activity for tier-2 component suppliers.
Kentucky
Louisville and Bowling Green facilities anchor battery enclosure coating demand for thermal management applications. The state's electric vehicle supply base accelerates procurement decentralization toward tier-1 subsystem integrators. Northern Kentucky coating operations integrate UV-cured lines directly with battery pack assembly sequences.
United States Automotive OEM Coatings Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated resin chemistry and color matching capabilities commanding premium positioning in OEM qualification cycles. The upper tier maintains parallel formulation portfolios across waterborne, UV-cured, and solventborne technologies to serve fragmented specification authority. Three archetypes dominate: diversified chemical conglomerates with captive resin production, dedicated automotive coating specialists with integrated refinish-OEM platforms, and Asia-Pacific scale players leveraging parent-company raw material integration. Competitive moves concentrate on regulatory-driven formulation redevelopment and geographic proximity to emerging Tennessee-Kentucky corridor capacity.
Within the integrated chemical tier, PPG Industries Inc and BASF SE exemplify scale-driven positioning across multiple substrate technologies and regulatory jurisdictions. Axalta Coating Systems occupies a specialist position, representing the dedicated automotive coating archetype with focused OEM-refinish integration. These three companies anchor the competitive structure through distinct capability emphases rather than overlapping strategic postures.
| Leading Market Players |
|---|
| PPG Industries Inc |
| BASF SE |
| Axalta Coating Systems |
| Akzo Nobel NV |
| The Sherwin-Williams Company |
| RPM International Inc |
| Nippon Paint Holdings Co Ltd |
| Kansai Paint Co Ltd |
| KCC Corporation |
| Others |
Value Network & Pricing Analysis
EPA VOC compliance deadlines and California Air Resources Board regional preemption gate both supplier qualification and price differentiation simultaneously, forcing coating manufacturers to absorb dual-certification costs while OEMs extract volume concessions for waterborne system conversions.
Pricing Analysis
Long-term offtake agreements dominate coating procurement between major OEMs and integrated suppliers, with spot purchasing limited to emergency formulation adjustments and specialty color matching. Price differentiation stems from certification tier—EPA-compliant waterborne systems command premiums over legacy solventborne—and volume scale, with Michigan-Ohio corridor plants leveraging multi-year commitments. Cost compression in base coat formulations is intensifying because titanium dioxide feedstock volatility erodes margin stability. Tier-2 component suppliers exhibit highest price sensitivity due to limited formulation switching costs, while electric vehicle programs show lowest sensitivity given thermal management performance requirements.
Supply Chain Analysis
Germany, Japan, and the United States anchor resin chemistry and pigment manufacturing for automotive OEM coatings. Raw material dependencies center on titanium dioxide from chloride-process facilities, aliphatic isocyanates for polyurethane clear coats, and specialty photoinitiators for UV-cured battery enclosure systems. Tariff exposure on Chinese titanium dioxide feedstock creates margin pressure for white-tone formulations. Distribution runs through integrated supplier direct-to-plant delivery networks, with regional distributor hubs serving tier-2 and tier-3 component manufacturers in Tennessee and Kentucky corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne technology substitution threatens solventborne incumbents before full depreciation cycles complete, compressing the window for margin recovery on stranded capacity investments.
For Market Incumbents: Compound technical service capabilities around robotic electrostatic spray programming to lock in OEM line commissioning contracts and defend against emerging UV-cured specialists. Prioritize backward integration into captive resin production for waterborne clear coat formulations, securing supply continuity as EPA compliance deadlines accelerate. Battery enclosure thermal management coatings represent the fastest-growing specification territory where incumbents must preempt specialty entrants.
For New Entrants and Emerging Players: Tier-1 subsystem integrator technical support gaps—particularly in Kentucky and Tennessee battery pack assembly sequences—offer white-space entry where incumbent response times lag electric vehicle platform ramps. UV-cured functional coatings for thermal management applications remain underpenetrated with high technical barriers protecting early movers. Direct qualification with battery enclosure manufacturers bypasses OEM central engineering gatekeepers, enabling faster specification adoption.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed automotive coating specialists lacking integrated resin production, presenting consolidation targets for chemical conglomerates seeking geographic proximity to Tennessee-Kentucky corridor capacity. Long-term viability hinges on waterborne technology transition completion and UV-cured battery enclosure penetration rates. Watch for EPA per- and polyfluoroalkyl substance restriction announcements as inflection indicators forcing premature R&D redirection across corrosion-resistant primer categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Line Conversion | EPA VOC compliance deadlines in Michigan and Ohio force capital redeployment before depreciation completion. |
| UV-Cured Battery Enclosure Capacity | Tennessee-Kentucky corridor electric vehicle plants integrate thermal management coating with pack assembly sequences. |
| Resin Chemistry Backward Integration | Captive polyurethane and acrylic-urethane production secures clear coat margin pools against feedstock volatility. |
| Robotic Spray Programming Services | Electrostatic path optimization expertise locks in OEM line commissioning contracts against specialty competitors. |
| Tier-1 Subsystem Direct Qualification | Procurement decentralization enables specification bypass of OEM central engineering for faster market access. |
Research Methodology
A spread of perspectives from OEM platform engineers, tier-1 supplier procurement leads, coating plant managers, and aftermarket distributors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against EPA regulatory filings, California Air Resources Board enforcement data, SEC 10-K disclosures from listed coating manufacturers, and vehicle production databases tracking Michigan-Ohio-Tennessee-Kentucky corridor capacity. Bottom-up volume estimates triangulated against top-down market sizing from raw material consumption patterns.
Segmentation dimensions modeled span coating product type, vehicle propulsion architecture, application technology, and procurement channel across the analysis window. CAGRs derived from regression analysis of historical installation rates, regulatory phase-in schedules, and electric vehicle platform announcement pipelines. Forecast inputs incorporated EPA VOC compliance deadline acceleration scenarios and UV-cured battery enclosure specification adoption curves.
Forecasts assume regulatory continuity in EPA and California Air Resources Board frameworks; material policy shifts would require re-modeling around accelerated per- and polyfluoroalkyl substance restrictions or federal preemption of state standards. Recalibration cycles align with material shifts in electric vehicle production capacity announcements and tier-1 supplier procurement decentralization patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Transparent Conductive Coatings Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
E-Coat Market
Coatings
In-Mold Coatings Market
Coatings
Diamond-Like Carbon Coatings Market
Coatings
Morocco Automotive OEM Coatings Market
Coatings
Gelcoat Market
Coatings
Global Flat Glass Coatings Market
Coatings
Noise and Vibration Coatings Market
Coatings
Asia-Pacific Flat Glass Coating Market
Coatings
Plasma Impulse Chemical Vapor Deposition (PICVD) Coating Market
Coatings
Cool Roof Coatings Market
Coatings
Anti-Microbial Coatings Market
Coatings
Waterborne Wood Coatings Market
Coatings
Epoxy Powder Coatings Market