
 Bitumen and Asphalt Testing Services Market | 2026-2036
Bitumen and Asphalt Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Bitumen and Asphalt Testing Services Market Outlook
Modular service bundling is hardening as the dominant procurement pattern across infrastructure testing programs. SGS SA leverages its global laboratory network to anchor multi-year pavement performance contracts. Bureau Veritas competes through specialized field testing capabilities in hot-mix asphalt validation. Intertek Group plc differentiates by integrating quality control with real-time pavement management systems.
Bitumen and asphalt testing services encompass laboratory and field-based analytical procedures that measure rheological properties, mechanical stability, and durability performance of petroleum-derived binders and their mixtures. These services evaluate parameters such as penetration grade, elastic recovery percentage, and Marshall stability quotient to ensure compliance with specified engineering standards for load-bearing surfaces. Laboratory testing dominates revenue contribution due to capital-intensive equipment requirements and accreditation barriers. Marshall Stability Test demand is accelerating fastest among methods, driven by airport runway and heavy-duty highway specifications. Paving applications occupy the largest share of testing volume, though seal coating programs for asset preservation are gaining share in mature road networks.
The Federal Highway Administration enforces Superpave binder grading protocols through state DOT adoption, directly shaping laboratory testing demand across the United States. ASTM International and AASHTO standards govern test methodologies, creating compliance-driven recurring revenue for accredited providers. India's Ministry of Road Transport and Highways mandates third-party quality assurance through its national highway development framework. Stakeholders must monitor evolving polymer-modified binder specifications and carbon-intensity disclosure requirements that will reshape service portfolios and capital allocation priorities.
Market Dynamics
Third-party testing mandates from highway authorities are restructuring service procurement, compressing contract cycles and elevating accreditation requirements for laboratory networks serving infrastructure programs.
Growth Catalysts
- Superpave Performance-Graded Binder Specifications:US state DOTs enforce rigorous rheological testing protocols that generate recurring laboratory demand for asphalt binder characterization.
- Warm-Mix Asphalt Adoption:Reduced production temperatures require modified Marshall stability validation and specialized field density verification protocols.
- India's IRC and MORTH Guidelines:National highway development frameworks mandate independent quality assurance for bitumen supply chains and pavement construction.
Market Restraints
- Capital-Intensive Equipment Requirements:Dynamic shear rheometers and bending beam rheometers demand substantial upfront investment, limiting laboratory network expansion.
- Petroleum-Derived Input Volatility:Crude oil price fluctuations compress testing service margins and destabilize binder modification program budgets.
- Accreditation Barriers:ISO/IEC 17025 certification timelines and AASHTO proficiency requirements create multi-year qualification delays for new market entrants.
Strategic Opportunities
- Polymer-Modified Binder Testing:SBS and EVA modification specifications are expanding rheological testing portfolios beyond conventional penetration-grade analysis.
- Real-Time Pavement Management Integration:Connected sensor networks and cloud-based quality control platforms enable predictive maintenance service bundling.
- Carbon-Intensity Disclosure Mandates:Emerging lifecycle assessment requirements for asphalt mixtures create demand for embodied carbon verification services.
Industry Challenges
- Specialized Technician Scarcity:Proficiency in Superpave binder grading and advanced rheological interpretation remains concentrated among experienced laboratory personnel.
- Multi-Jurisdiction Standard Harmonization:Divergent ASTM, AASHTO, and EN 12591 test protocols complicate cross-border service standardization for multinational providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bitumen and Asphalt Testing Services Market |
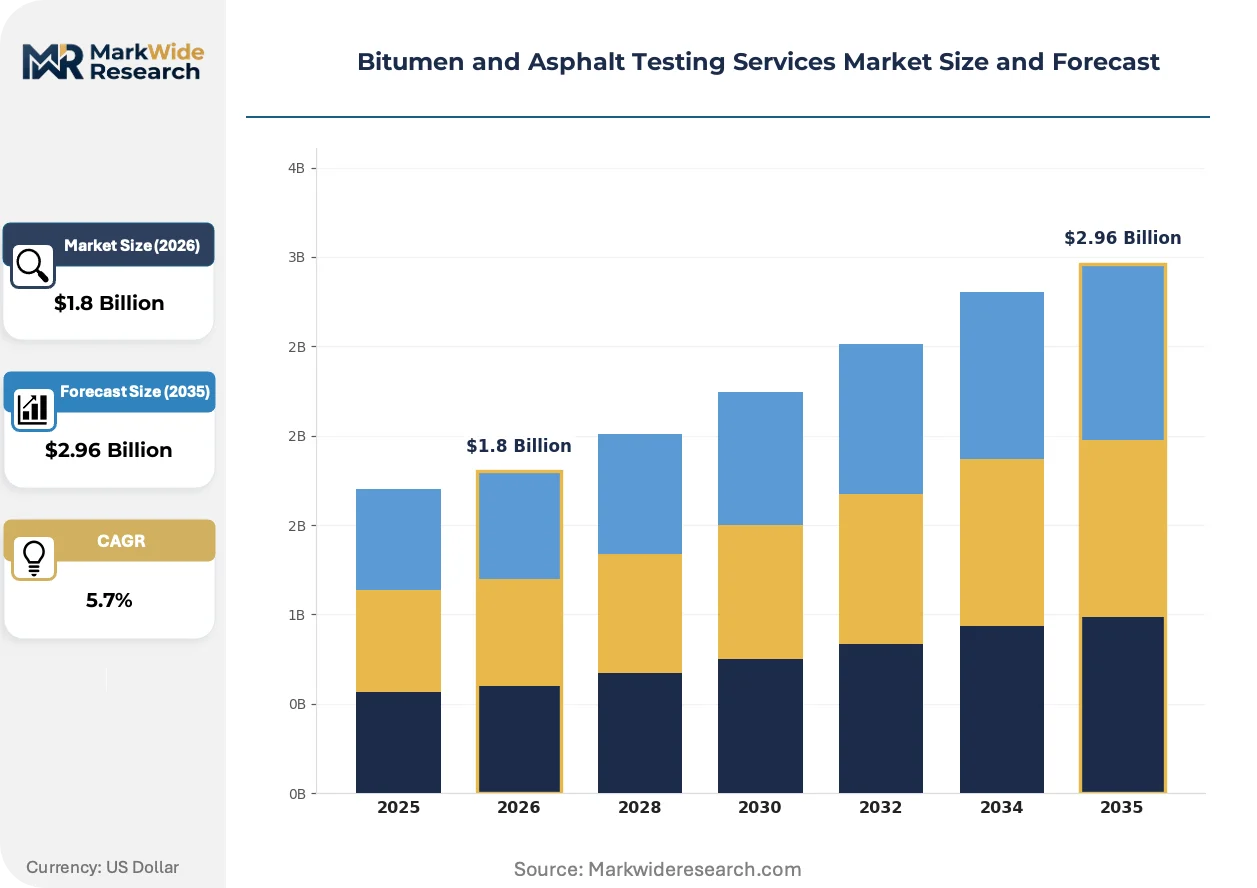
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Laboratory Testing, Field Testing, Quality Control, Consulting Services Testing Method: Penetration Test, Viscosity Test, Elastic Recovery Test, Marshall Stability Test Application: Paving, Roofing, Seal Coating, Emulsion Production End User: Construction Companies, Government Agencies, Material Suppliers, Engineering Firms |
| Companies Covered | SGS SA, Intertek Group plc, Bureau Veritas, Eurofins Scientific SE, Element Materials Technology, ALS Limited, PaveTest Pty Ltd., Asphalt Institute, Accro-Tech Scientific Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bitumen and Asphalt Testing Services Market Strategic Shifts
Digital instrumentation and automated specimen handling are compressing turnaround times while elevating data granularity for pavement performance prediction. Three developments are restructuring competitive positioning.
Portable dynamic shear rheometers with cloud-connected data logging are decentralizing asphalt binder verification from central laboratories to project site field stations. State DOT quality assurance programs in Texas and California are piloting mobile units for real-time acceptance testing. This capability compression is enabling just-in-time construction decisions and reducing specimen transport delays.
India's Ministry of Road Transport and Highways is tightening third-party quality assurance enforcement through mandatory independent testing for all national highway contracts above specified value thresholds. The framework requires accredited laboratories to submit digital test reports directly to centralized project monitoring portals. Heavy-duty highway segments and airport runway specifications are experiencing the most intensive compliance acceleration.
Asset preservation programs for mature road networks are unbundling reactive maintenance from capital reconstruction, creating discrete testing contracts for seal coating and micro-surfacing validation. State and municipal buyers in the United States are separating condition assessment from treatment design, opening procurement to specialized testing-only providers. This service fragmentation is most visible in California and New York pavement management programs.
Bitumen and Asphalt Testing Services Market Segmentation
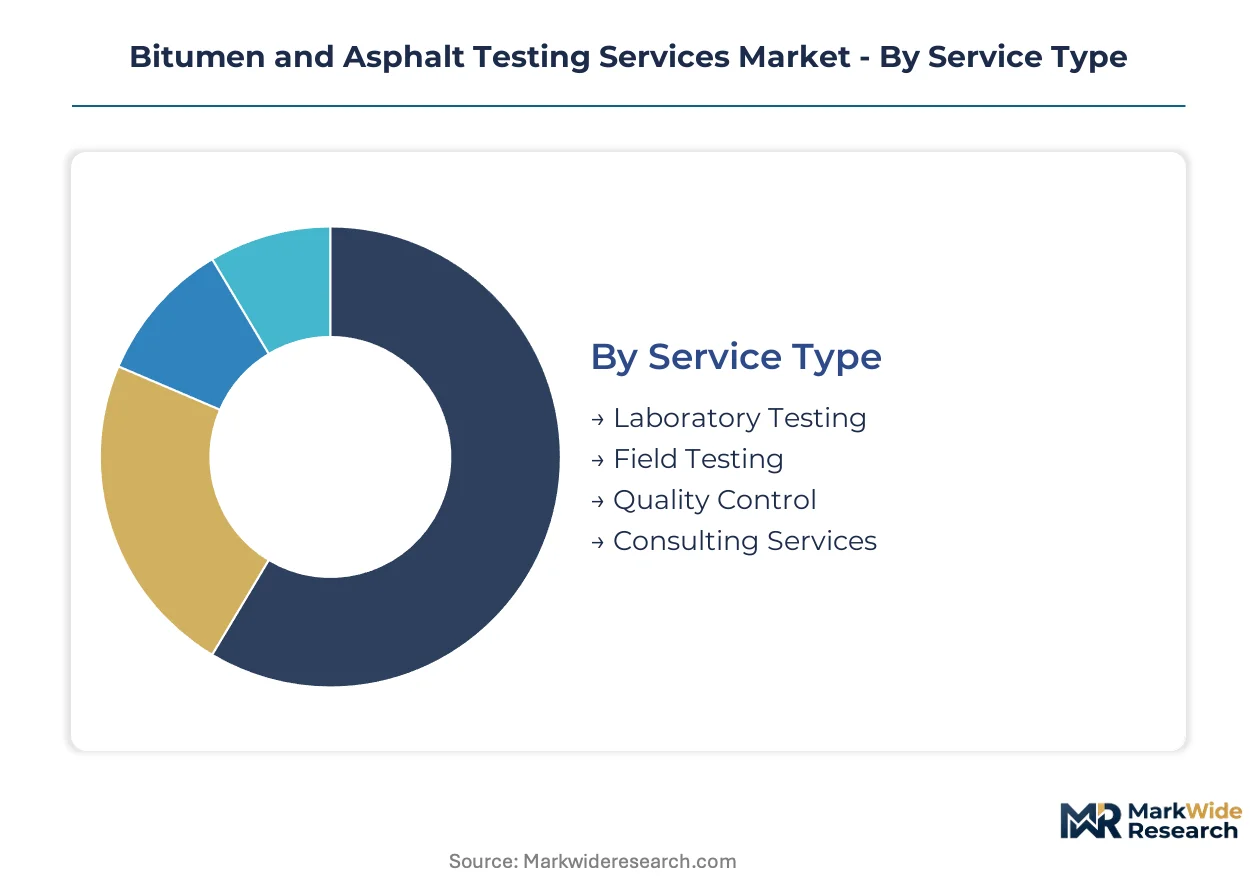
Segmentation in bitumen and asphalt testing services reveals distinct procurement patterns across laboratory-intensive versus field-deployable capabilities. Service providers configure accreditation portfolios and equipment investments around specific contract types rather than pursuing horizontal coverage.
Service Type:
Laboratory testing commands premium pricing due to capital barriers, while field services compete on mobilization speed and technician availability.
- Laboratory Testing:Rheological characterization using dynamic shear rheometers and bending beam rheometers requires ISO/IEC 17025 accreditation. State DOTs in the United States generate recurring demand through Superpave binder grading protocols. Equipment amortization cycles and proficiency testing costs sustain margin premiums for established networks.
- Field Testing:Marshall stability validation and density verification occur at project sites with portable instrumentation. India's MORTH-mandated third-party programs for national highways are accelerating mobile laboratory deployment. Turnaround compression and just-in-time construction decisions favor providers with distributed technician pools.
- Quality Control:Continuous production monitoring at hot-mix asphalt plants integrates automated sampling with real-time data logging.
- Consulting Services:Pavement design validation and forensic failure analysis leverage specialized engineering expertise on discrete project engagements.
Mature deployment sits with Laboratory Testing. Newer deployment is concentrated in Field Testing.
Testing Method:
Method selection tracks specification evolution from empirical penetration grades toward performance-based rheological protocols.
- Marshall Stability Test:Measures resistance to plastic deformation under compressive loading for dense-graded mixtures. Airport runway specifications and heavy-duty highway segments in India and the United States are driving method expansion. Equipment standardization across AASHTO T245 enables cross-laboratory result comparability.
- Penetration Test:Empirical consistency measurement for conventional binder classification retains volume in developing markets with legacy specifications. India's IRC guidelines still reference penetration grades for routine procurement, sustaining baseline demand despite Superpave displacement in premium segments.
- Viscosity Test:Rotational viscometer protocols at elevated temperatures characterize binder workability during mixing and placement.
- Elastic Recovery Test:Polymer-modified binder validation for SBS and EVA formulations requires specialized ductility instrumentation.
Specification migration favors Marshall Stability Test adoption where performance contracting prevails. Penetration Test retains institutional presence where procurement frameworks modernize slowly.
Application:
Application segmentation separates capital-intensive new construction from recurring maintenance programs with distinct testing frequencies.
- Paving:Hot-mix and warm-mix asphalt for highways, airports, and urban roads generates the largest testing volumes. State DOT quality assurance programs in Texas and California require continuous binder verification and mixture design validation. Warm-mix technologies are modifying Marshall protocols for reduced-temperature performance validation.
- Seal Coating:Surface preservation treatments for mature road networks are unbundling from capital reconstruction in California and New York pavement management programs. Condition assessment contracts now separate from treatment design, opening procurement to specialized testing-only providers with lower overhead structures.
- Roofing:Waterproofing membrane and shingle manufacturing requires modified bitumen characterization with distinct rheological targets.
- Emulsion Production:Cold-mix and tack coat formulations demand particle charge and storage stability testing for spray application compatibility.
Volume concentration remains with Paving. Service fragmentation is expanding fastest in Seal Coating.
End User:
End user structure reflects procurement centralization versus project-level discretion in testing specification.
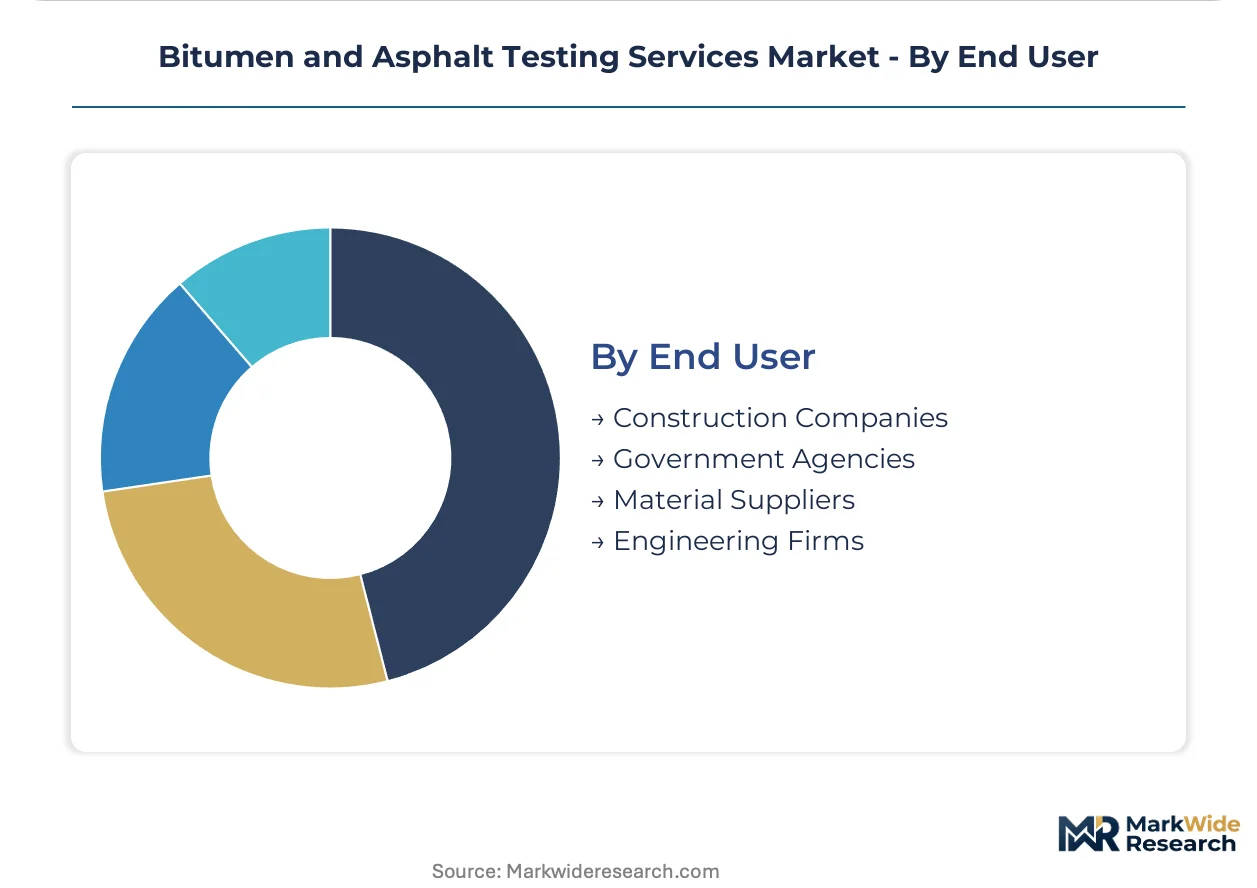
- Government Agencies:State DOTs and national highway authorities enforce mandatory third-party testing through embedded quality assurance frameworks. India's Ministry of Road Transport and Highways mandates independent testing for contracts above specified value thresholds with direct digital reporting to centralized portals. Recurring multi-year programs sustain laboratory network utilization.
- Construction Companies:Prime contractors for design-build and PPP projects internalize testing costs within lump-sum bids. Margin pressure is driving selective outsourcing of specialized rheological characterization while retaining routine field density verification in-house.
- Material Suppliers:Refineries and binder modifiers require certification testing for product release and customer specification compliance.
- Engineering Firms:Design consultants specify testing protocols and witness critical validation without direct laboratory ownership.
Contract volume aggregates with Government Agencies. Procurement flexibility is greatest among Construction Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bitumen consumption concentrates in highway construction corridors while testing service capacity clusters around state DOT procurement centers and national highway development zones. Production of modified binders and polymer additives centers on petroleum refining regions, creating geographic separation from pavement construction demand.
United States
State DOTs in Texas and California generate concentrated demand through Superpave performance-graded binder specifications. The Federal Highway Administration enforces quality assurance protocols that mandate third-party laboratory accreditation. Houston and Los Angeles host dense clusters of AASHTO-accredited testing facilities serving multi-year pavement performance contracts.
India
National highway development under the Ministry of Road Transport and Highways is accelerating third-party testing mandates for contracts above specified value thresholds. IRC and MORTH guidelines require accredited laboratories to submit digital reports directly to centralized project portals. Mumbai and Delhi-NCR concentrate mobile laboratory deployment for field Marshall stability validation.
Germany
Federal motorway expansion and urban infrastructure renewal sustain demand for polymer-modified binder characterization. The country's national road construction regulator enforces DIN and EN standards that exceed baseline EU requirements. Bavaria and North Rhine-Westphalia host specialized rheological testing networks serving cross-border highway projects.
China
Provincial transport bureaus are expanding quality assurance frameworks for expressway construction under national infrastructure investment programs. GB standards govern bitumen testing protocols with increasing alignment toward performance-based specifications. The Yangtze River Delta concentrates laboratory capacity serving high-volume paving projects in Shanghai and Jiangsu province.
United Arab Emirates
Federal and emirate-level transport authorities mandate independent testing for airport runway and highway construction in Dubai and Abu Dhabi. The country's national standards body enforces modified bitumen specifications for extreme climate performance. Jebel Ali and Khalifa Port zones concentrate import testing facilities for binder supply chain verification.
Bitumen and Asphalt Testing Services Market Competitive Environment
The competitive structure tilts toward diversified inspection conglomerates with cross-border laboratory networks. Market concentration remains moderate, with tier-one players commanding premium pricing through accreditation density while regional specialists compete on mobilization speed. Three archetypes dominate: global multi-service inspection firms, specialized pavement engineering consultancies, and state-affiliated research institutes. Capacity expansion through mobile laboratory fleets and strategic partnerships with hot-mix asphalt producers represent the primary competitive vectors.
Among global multi-service providers, SGS SA, Intertek Group plc, and Bureau Veritas occupy positions anchored by ISO/IEC 17025-accredited laboratory networks spanning multiple continents. These Switzerland-based and UK-based conglomerates exemplify the diversified inspection model, leveraging cross-selling across construction materials testing to amortize fixed accreditation costs. Their geographic footprint aligns with state DOT and national highway authority procurement corridors.
| Leading Market Players |
|---|
| SGS SA |
| Intertek Group plc |
| Bureau Veritas |
| Eurofins Scientific SE |
| Element Materials Technology |
| ALS Limited |
| PaveTest Pty Ltd. |
| Asphalt Institute |
| Accro-Tech Scientific Industries |
| Others |
Value Chain & Pricing Dynamics
State DOT procurement programs in the United States concentrate buyer power through multi-year pavement performance contracts, anchoring project-based pricing with volume-tiered discounts for accredited laboratory networks. This procurement concentration compresses margins for field services while sustaining premium pricing for ISO/IEC 17025-certified rheological characterization.
Pricing Analysis
Margin tightening in field testing reflects equipment commoditization and technician pool expansion in India and the United States. Project-based pricing dominates, with differentiation resting on AASHTO accreditation density and mobilization speed rather than brand premium. Cost-down pressure on Marshall stability validation accelerates because warm-mix asphalt protocols demand modified equipment configurations. Construction companies exhibit highest price sensitivity, outsourcing only specialized rheological work while retaining routine density verification in-house.
Supply Chain Analysis
Specialized technician scarcity in Germany and India constrains laboratory network expansion despite equipment availability from European and Japanese manufacturers. Supply concentrates in Switzerland and the United Kingdom for diversified inspection conglomerates, the United States for AASHTO-accredited facilities, and India for mobile field deployment. Dynamic shear rheometers and bending beam rheometers draw from precision instrumentation suppliers in Germany and Japan. Single-source vulnerability sits with petroleum-derived binder reference materials tied to crude oil price volatility. Distribution runs through direct state DOT contracts and prime contractor subcontracts for national highway programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into hot-mix asphalt plant quality control systems and forward integration into real-time pavement management platforms are reshaping competitive positioning as players seek to capture recurring revenue streams beyond discrete testing contracts.
For Market Incumbents: Acquire mobile laboratory fleets and cloud-connected data logging capabilities to compress turnaround times for India's MORTH-mandated field programs. Consolidate around polymer-modified binder testing accreditation before SBS and EVA specification expansion accelerates. State DOT procurement centralization threatens margin premiums for undifferentiated field services. For New Entrants and Emerging Players: Launch via seal coating condition assessment contracts in California and New York, where asset preservation programs unbundle testing from capital reconstruction. Target municipal pavement management systems with lower accreditation barriers than federal highway frameworks. White-space concentration sits with carbon-intensity verification services for emerging lifecycle assessment mandates. For Investors and Strategic Acquirers: The window for entry favors specialized rheological testing boutiques with ISO/IEC 17025 accreditation in underserved state DOT corridors. Long-term viability hinges on digital integration capabilities rather than equipment scale alone. Watch for polymer-modified binder specification adoption rates as inflection signal for portfolio reallocation toward advanced characterization services.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Laboratory Fleet Expansion | India's MORTH mandates compress mobilization windows for national highway contracts. |
| Polymer-Modified Binder Accreditation | SBS and EVA specifications expand testing portfolios beyond penetration-grade analysis. |
| Real-Time Pavement Management Integration | Cloud-based quality control platforms enable predictive maintenance service bundling for state DOTs. |
| Carbon-Intensity Verification Capability | Emerging lifecycle assessment requirements create embodied carbon testing demand. |
| Strategic Partnership with Hot-Mix Producers | Continuous plant monitoring contracts secure recurring revenue outside project-based procurement. |
Study Parameters
Document review covered AASHTO and ASTM standard evolution, state DOT procurement databases, and IRC/MORTH regulatory filings, complemented by interviews with laboratory operations directors, state DOT quality assurance officers, hot-mix asphalt plant managers, and accredited certification body representatives. Secondary validation drew from FHWA technical advisories, equipment manufacturer technical specifications, and national highway authority contract disclosures. Bottom-up service demand modeling and top-down infrastructure spending allocation were triangulated against accreditation registry data.
Segment-level outputs across the projection horizon reflect modeled service type, testing method, application, and end-user procurement patterns. CAGRs were derived from infrastructure investment trajectories, specification migration timelines, and accreditation expansion rates. Warm-mix asphalt adoption curves and third-party testing mandate enforcement intensity served as industry-specific forecast inputs.
Petroleum price volatility, regulatory harmonization delays between ASTM and EN protocols, and technician training pipeline constraints are the dominant revision risks to modeled demand. Forecasts reflect assumptions about specification continuity and accreditation recognition reciprocity. Material deviation in enforcement intensity for India's digital reporting mandates or US state DOT procurement centralization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Gas Calorimeter Market
Testing Equipment
Clean-Up Gel Permeation Chromatography Market
Testing Equipment
Lactose Assay Kit Market
Testing Equipment
Chemical Testing Services Market
Testing Equipment
Microplastics Particle Size and Shape Characterization Systems Market
Testing Equipment
Solar Testing Equipment Market
Testing Equipment
Rheology Controller Market
Testing Equipment
Chemical Detector Market
Testing Equipment
Nitrogen Tester Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Magnesium Testing Reagents Market
Testing Equipment
Global Asbestos Testing Market
Testing Equipment
Process Analytical Technology Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
Rheometer Market
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market