
 Hydrogen Gas Analyzers Market | 2026-2036
Hydrogen Gas Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Gas Analyzers Market Insights
Software-defined calibration and remote diagnostics is realigning what hydrogen gas analyzer vendors bundle into contracts. Emerson Electric Co. leverages embedded predictive maintenance algorithms to extend service attach rates. HORIBA Ltd anchors its position through deep specialization in thermal conductivity detection for high-purity hydrogen streams. Honeywell International Inc. dominates integrated safety systems that combine gas analysis with distributed control architectures.
Hydrogen gas analyzers are precision instruments that measure hydrogen concentration, purity, and trace contaminant levels using detection principles such as thermal conductivity response ratios down to parts-per-billion sensitivity. These devices serve critical quality assurance functions across hydrogen production, distribution, and end-use combustion or fuel-cell conversion processes. Stationary installations command the largest installed base due to permanent integration within reformer and electrolyzer facilities, while portable units represent the fastest-expanding category as field verification needs multiply across decentralized hydrogen hubs. Electrochemical sensing technology leads in cost-sensitive applications, though gas chromatography captures the premium margin pool where ultrahigh-purity certification is mandatory for semiconductor and pharmaceutical hydrogen supply.
The U.S. EPA enforces stationary source emission thresholds that drive continuous hydrogen vent monitoring at refineries and chemical plants. The EU F-Gas Regulation and associated CE marking requirements shape analyzer design standards for equipment sold into European hydrogen infrastructure projects. Japan's METI hydrogen safety codes mandate specific detection response times for pipeline injection points. Stakeholders must monitor how evolving national hydrogen strategies rewrite certification requirements before committing to next-generation analyzer platforms.
Market Dynamics
Capital deployment across hydrogen infrastructure is compressing analyzer qualification timelines as project developers race to capture U.S. Inflation Reduction Act production tax credits before certification deadlines.
Growth Catalysts
- Electrolyzer capacity buildout:Gigawatt-scale green hydrogen projects in Denmark and the Netherlands require continuous purity verification at each compression stage.
- Fuel-cell vehicle mandates:California's Advanced Clean Trucks regulation compels fleet operators to install dedicated refueling quality monitoring systems.
- Pipeline injection standards:Germany's national hydrogen backbone network operators are specifying ppb-level sulfur detection for all grid entry points.
Market Restraints
- Sensor material cost volatility:Platinum-group metal prices for electrochemical cell electrodes fluctuate with South African mining output disruptions.
- Calibration gas supply concentration:Certified reference material production concentrates among three European specialty gas suppliers.
- Detection limit trade-offs:Thermal conductivity methods cannot achieve semiconductor-grade purity thresholds without gas chromatography pre-separation.
Strategic Opportunities
- Saudi Arabia NEOM project scale:The 2 GW electrolyzer complex creates demand for integrated analyzer skids with remote diagnostic capability.
- Ammonia cracking retrofits:Port terminal operators in Rotterdam require portable verification units for bunkering quality assurance.
- EU Hydrogen Bank auction mechanism:Winning bidders must demonstrate certified purity chains, mandating analyzer deployment across production sites.
Industry Challenges
- Metrology technician scarcity:Field calibration of thermal conductivity detectors requires specialized training unavailable in emerging hydrogen hub regions.
- Multi-standard certification overlap:Equipment must simultaneously satisfy EU F-Gas Regulation, ATEX directives, and IECEx schemes for international project deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Gas Analyzers Market |
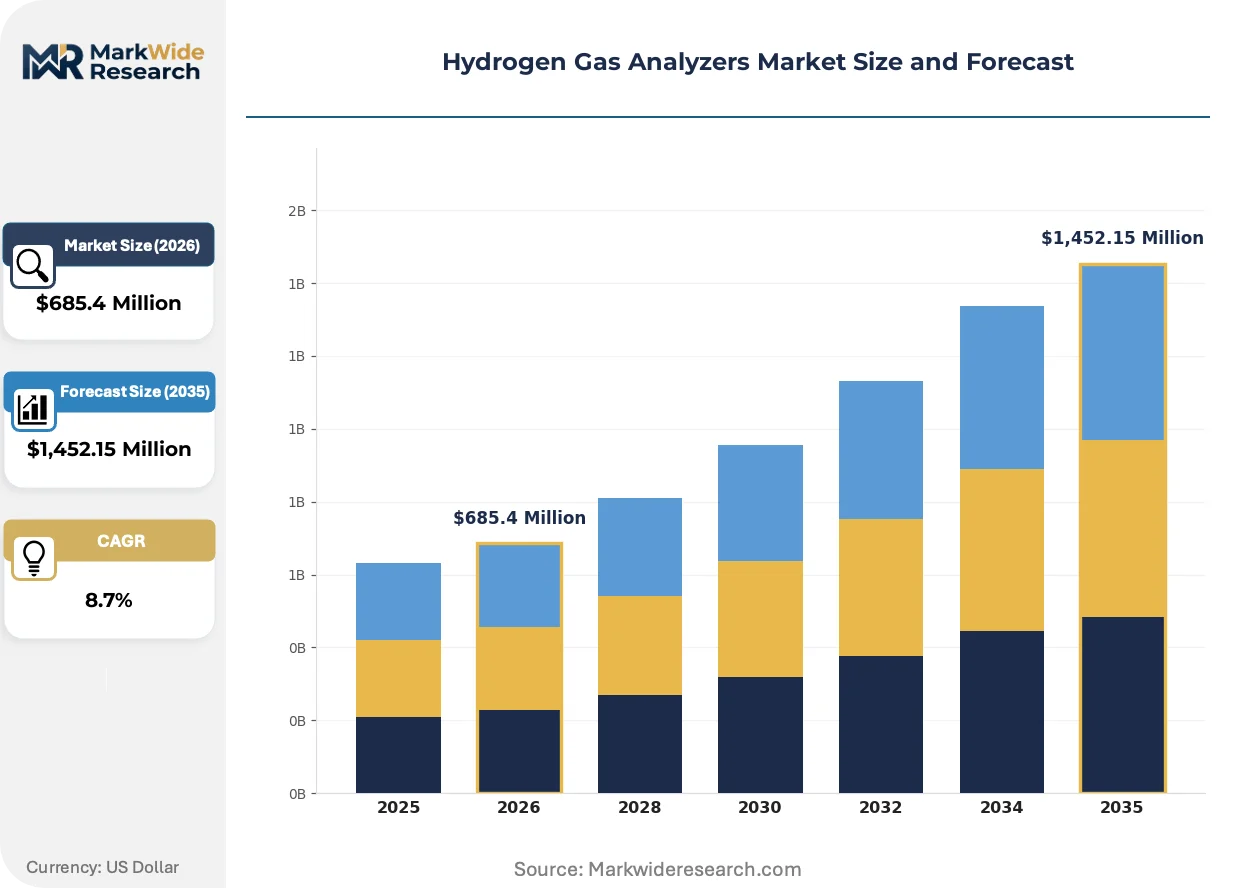
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Fixed, Online Technology: Infrared, Thermal Conductivity, Gas Chromatography, Electrochemical End User: Chemical Industry, Oil & Gas, Power Generation, Research Laboratories Application: Leak Detection, Quality Control, Emission Monitoring, Process Optimization |
| Companies Covered | Honeywell International Inc., Emerson Electric Co., HORIBA Ltd, ABB Ltd, Servomex, AMETEK Process Instruments, Teledyne Analytical Instruments, Nova Analytical Systems, H2scan Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Gas Analyzers Market Trends and Innovations
Analyzer architecture is pivoting from discrete measurement devices to embedded nodes within broader process control networks, collapsing the boundary between sensing and system-level optimization.
MEMS-based thermal conductivity sensors are absorbing functions previously handled by bench-top gas chromatographs in refueling station applications. Station operators in Japan are adopting these compact units for real-time moisture detection at 700 bar dispensing points. The technology is absorbing market share from legacy infrared absorption methods by eliminating carrier gas dependencies and reducing maintenance intervals from quarterly to annual cycles.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in cooling systems that stabilize analyzer electronics, forcing redesigns toward thermoelectric temperature control. Equipment manufacturers serving European hydrogen backbone projects must now certify alternative thermal management architectures. German pipeline operators are responding by specifying F-Gas-free analyzer skids in tender documents, creating competitive differentiation for compliant suppliers.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts into component-level subscriptions. Refinery operators in Texas are purchasing predictive algorithm licenses separately from hardware, then sourcing third-party field calibration services. This pattern is most pronounced in North American industrial clusters where specialized metrology contractors have established regional presence independent of original equipment manufacturers.
Hydrogen Gas Analyzers Market Segmentation
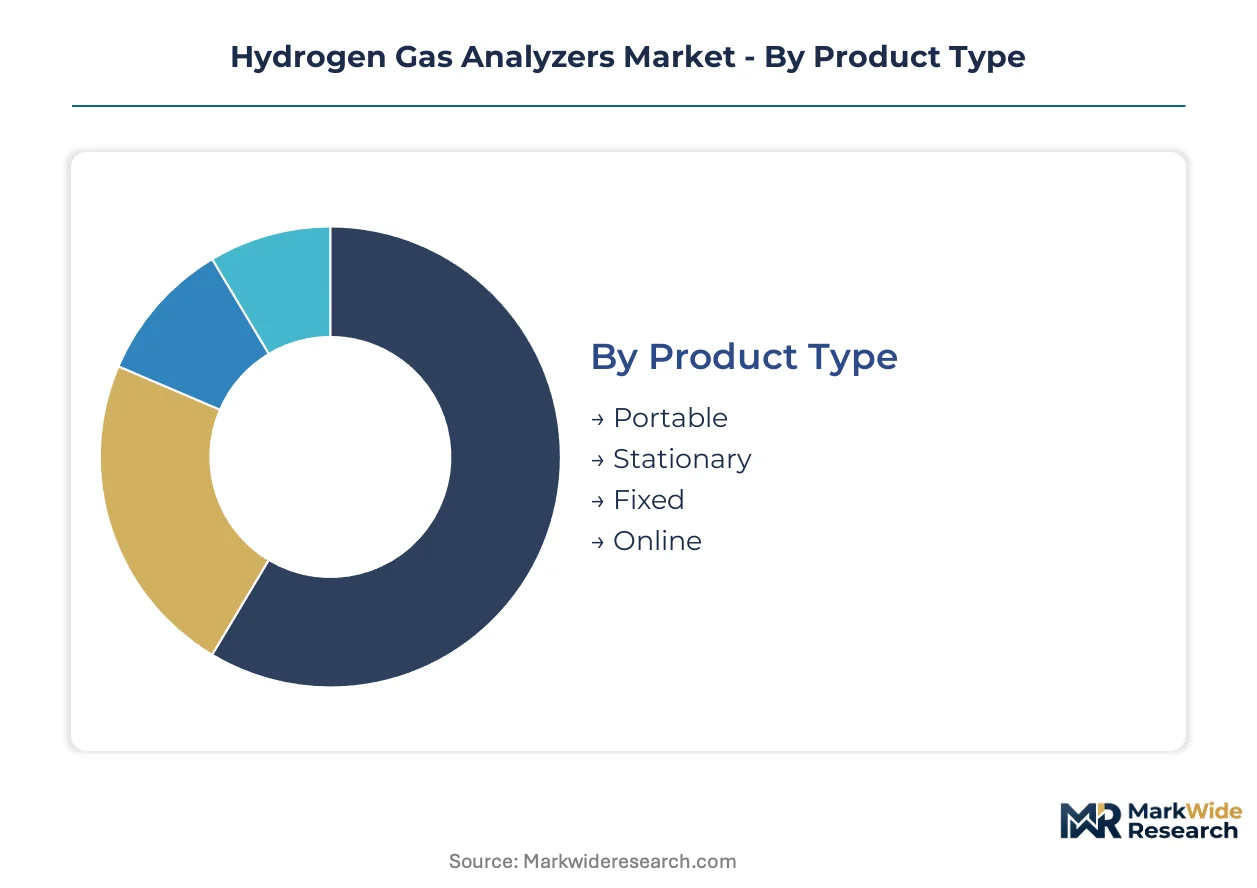
Hydrogen gas analyzer segmentation reflects divergent technical requirements across centralized production and distributed infrastructure. Product mobility, detection methodology, and end-use certification standards create distinct commercial pockets with specialized vendor competencies.
Product Type:
Physical deployment architecture determines calibration protocols, connectivity requirements, and service attach rates.
- Stationary:Permanent installations integrate directly into electrolyzer and reformer facilities with continuous sampling loops. Demand concentrates in Germany's national hydrogen backbone network, where pipeline injection points require uninterruptible purity verification under EU F-Gas Regulation compliance timelines.
- Portable:Battery-powered units with wireless data transmission enable field verification at decentralized hydrogen hubs. California's Advanced Clean Trucks regulation compels fleet operators to deploy these for refueling station quality assurance during commercial vehicle rollout.
- Fixed:Hardwired installations within industrial process control architectures deliver real-time data to distributed control systems. Refinery operators in Texas specify these for EPA-mandated vent monitoring at catalytic reformer units.
- Online:Direct-process insertion designs eliminate sampling lag for rapid response applications. Japanese METI hydrogen safety codes mandate specific detection response times that favor this architecture at 700 bar dispensing points.
Mature deployment sits with Stationary. Newer deployment is concentrated in Portable.
Technology:
Detection principle selection trades capital cost against sensitivity threshold and maintenance burden.
- Thermal Conductivity:Measures hydrogen concentration through thermal response ratio differentials against reference gases. HORIBA Ltd anchors market position through deep specialization in high-purity hydrogen stream applications where ppb-level resolution is required.
- Gas Chromatography:Pre-separation columns enable semiconductor-grade purity certification. Demand concentrates in pharmaceutical and electronics hydrogen supply chains where contaminant specification exceeds thermal conductivity method limits.
- Electrochemical:Platinum-group metal electrodes deliver cost-sensitive measurement for industrial process monitoring. South African mining output disruptions create sensor material cost volatility that compresses margin structures.
- Infrared:Absorption spectroscopy targets moisture and hydrocarbon contaminant detection. MEMS-based thermal conductivity sensors are displacing legacy infrared methods in refueling station applications by eliminating carrier gas dependencies.
Electrochemical captures volume concentration. Gas Chromatography commands premium positioning.
End User:
Industry verticals impose distinct certification, response time, and integration specifications.
- Oil & Gas:Refinery hydrogen production and hydrotreater vent monitoring drive continuous analyzer deployment. U.S. EPA stationary source emission thresholds mandate permanent installation at catalytic reformer facilities.
- Chemical Industry:Ammonia and methanol synthesis require precise hydrogen-to-nitrogen or hydrogen-to-carbon monoxide ratio control. Rotterdam port terminal operators specify portable verification for bunkering quality assurance.
- Power Generation:Gas turbine blending and fuel-cell integration create emerging demand for rapid-response purity verification. Saudi Arabia's NEOM project specifies integrated analyzer skids for its electrolyzer complex.
- Research Laboratories:Metrology-grade reference instruments support standard material certification. European specialty gas suppliers concentrate certified reference material production, constraining calibration gas availability.
Oil & Gas sustains replacement demand. Power Generation is climbing the fastest.
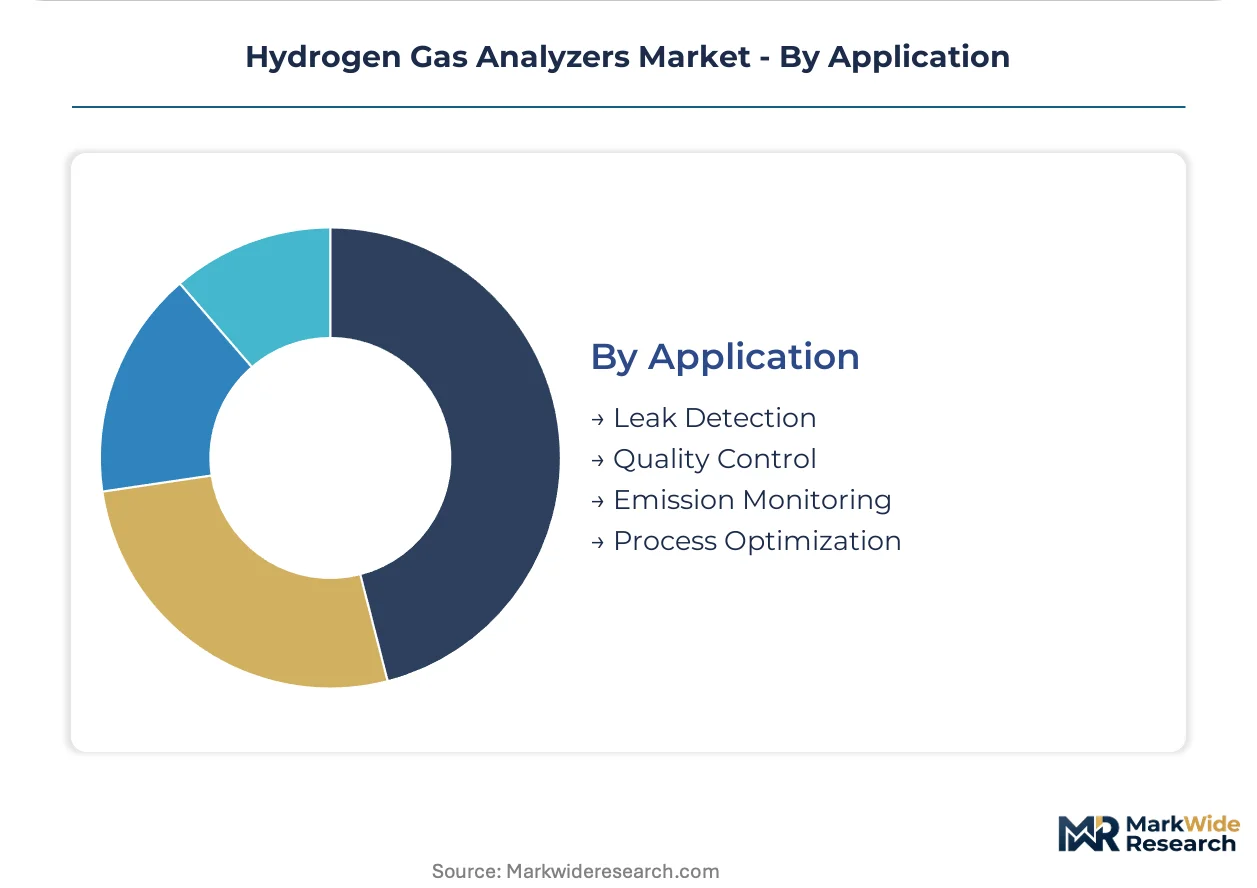
Application:
Functional use case determines sensor configuration, data logging requirements, and alarm integration depth.
- Quality Control:Purity verification at production, compression, and dispensing stages ensures fuel-cell vehicle compatibility. Germany's pipeline operators specify ppb-level sulfur detection for all grid entry points.
- Leak Detection:Ambient hydrogen monitoring prevents explosive atmosphere formation in enclosed spaces. Japanese METI codes mandate specific response times for pipeline injection point surveillance.
- Emission Monitoring:Continuous vent stream measurement satisfies regulatory reporting obligations. U.S. EPA enforcement drives installation at refinery and chemical plant hydrogen handling systems.
- Process Optimization:Real-time composition feedback enables reformer and electrolyzer efficiency tuning. EU Hydrogen Bank auction winners must demonstrate certified purity chains across production sites.
Quality Control dominates capital allocation. Leak Detection is gaining share fastest in safety-critical installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates where electrolyzer manufacturing scales fastest, while consumption clusters around refueling infrastructure and industrial hydrogen demand centers. This geographic split shapes analyzer deployment patterns across manufacturing hubs and end-use markets.
Germany
The national hydrogen backbone network drives continuous pipeline quality monitoring requirements. EU F-Gas Regulation compliance timelines accelerate analyzer qualification for grid entry points. Industrial clusters in North Rhine-Westphalia deploy ppb-level sulfur detection systems at compression stations.
United States
Texas refinery operators install EPA-mandated vent monitoring at catalytic reformer facilities. IRA hydrogen production tax credits compress project timelines for purity verification equipment. California fleet operators deploy portable units under Advanced Clean Trucks regulation compliance.
Japan
700 bar fuel-cell vehicle dispensing creates demand for rapid-response moisture detection. METI hydrogen safety codes mandate specific detection response times at pipeline injection points. Kanto region station operators adopt MEMS-based thermal conductivity sensors for real-time monitoring.
Saudi Arabia
NEOM's 2 GW electrolyzer complex specifies integrated analyzer skids with remote diagnostic capability. The kingdom's national hydrogen strategy prioritizes export-grade purity certification. Red Sea coastal development zones concentrate deployment of portable verification units.
Netherlands
Rotterdam port terminal operators require portable verification for ammonia cracking bunkering operations. EU Hydrogen Bank auction winners must demonstrate certified purity chains across production sites. Gigawatt-scale green hydrogen projects in the northern provinces drive continuous purity verification demand.
Hydrogen Gas Analyzers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the analyzer value chain. The vendor base stratifies between integrated industrial conglomerates and specialized detection technology firms. Three archetypes dominate: diversified automation suppliers with embedded analyzer portfolios, pure-play gas analysis specialists, and emerging MEMS sensor developers. Consolidation pressure intensifies as project developers seek single-source accountability for integrated safety systems.
Within the diversified automation tier, Honeywell International Inc. and Emerson Electric Co. exemplify platform-scale positioning. HORIBA Ltd anchors the specialist archetype through thermal conductivity detection focus. These three occupy distinct competitive terrain: the automation majors leverage distributed control integration, while the specialist commands premium positioning in high-purity certification segments.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Emerson Electric Co. |
| HORIBA Ltd |
| ABB Ltd |
| Servomex |
| AMETEK Process Instruments |
| Teledyne Analytical Instruments |
| Nova Analytical Systems |
| H2scan Corporation |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between semiconductor-qualified and industrial-process analyzers manifests in divergent pricing architectures and sourcing footprints. Premium units commanding gas chromatography pre-separation stages draw from German and Japanese precision component networks, while cost-optimized electrochemical sensors anchor in South Korean and Chinese platinum-group metal processing corridors.
Pricing Analysis
Margin tightening in portable analyzer tiers reflects MEMS sensor commoditization and third-party calibration service unbundling. Project-based equipment sales dominate stationary installations for electrolyzer complexes, while subscription licensing for predictive maintenance algorithms penetrates North American refinery clusters. Price differentiation separates ATEX/IECEx dual-certified platforms from single-standard equipment, with California fleet operators exhibiting highest sensitivity and German pipeline operators least. Cost compression accelerates as South African mining disruptions in platinum-group metals feed into electrochemical cell electrode pricing.
Supply Chain Analysis
EU F-Gas Regulation domestic-content mandates are reshaping analyzer thermal management component sourcing toward European thermoelectric suppliers. Manufacturing concentrates in Germany, Japan, and the United States for precision detection modules, while China and South Korea supply MEMS substrates and platinum-group metal electrodes. Raw material dependencies include specialty gas calibration mixtures from European reference material producers, sapphire optical windows for infrared detection, and high-purity carrier gases for chromatography columns. Single-source vulnerability sits with certified reference gas production concentrated among three European specialty suppliers. Distribution runs through authorized system integrators for large electrolyzer projects and direct OEM channels for refueling station retrofit deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogen gas analyzer market functions as a cost-of-compliance arena where EU F-Gas Regulation certification timelines erect barrier-to-entry moats for vendors with established European testing infrastructure.
For Market Incumbents: Deepen vertical control over calibration gas supply chains to offset European specialty supplier concentration risk. Expand embedded predictive maintenance algorithm development to capture recurring software revenue streams as hardware margins compress. MEMS-based thermal conductivity entrants threaten legacy infrared absorption positions in refueling station applications. For New Entrants and Emerging Players: Regional metrology contractors in Texas and California represent underexploited channel partners for portable analyzer distribution independent of OEM service networks. White-space concentrates in ammonia cracking bunkering verification at Rotterdam port terminals and remote diagnostic-enabled skids for Saudi electrolyzer complexes. Pursue software-defined calibration subscriptions to bypass capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play thermal conductivity specialists given semiconductor-grade purity certification requirements tightening across pharmaceutical and electronics hydrogen supply chains. Long-term viability favors acquisition targets with established IECEx/ATEX dual-certification capabilities and embedded service attach rate infrastructure. Watch for EU Hydrogen Bank auction winner announcements as purity chain demonstration mandates trigger analyzer procurement inflections.| Strategic Initiative | Industry Significance |
|---|---|
| F-Gas-Free Thermal Management Redesign | European pipeline operators now specify compliant skids, differentiating qualified suppliers in German backbone tenders. |
| MEMS Sensor Platform Integration | Japanese 700 bar dispensing point operators adopt compact units, displacing legacy infrared absorption methods. |
| Remote Diagnostic Capability Deployment | Saudi NEOM electrolyzer complex specifications demand integrated skids with predictive maintenance architecture. |
| Calibration Gas Backward Integration | Three-supplier European concentration creates vulnerability for electrochemical sensor manufacturers dependent on certified reference materials. |
| Software-Defined Service Unbundling | Texas refinery operators now license predictive algorithms separately from hardware, fragmenting traditional bundled contracts. |
Research Methodology
Independent corroboration across electrolyzer project developers, refinery instrumentation managers, and hydrogen refueling station operators underwrites the qualitative findings in this study. Primary interviews with plant engineers at catalytic reformer facilities, procurement leads at pipeline network operators, and aftermarket service heads at regional metrology contractors combined with secondary validation from SEC filings, EU Hydrogen Bank auction documentation, and EPA stationary source enforcement records. Bottom-up electrolyzer capacity buildout estimates and top-down industrial hydrogen demand projections were reconciled through iterative triangulation.
Comparable-period anchoring to historical electrolyzer commissioning timelines and fuel-cell vehicle deployment curves structured the forecast window across the projection horizon. Segmentation dimensions modeled include product mobility architecture, detection methodology sensitivity tiers, end-use certification requirements, and regional regulatory framework clusters. CAGRs were derived from capacity-weighted electrolyzer buildout schedules and purity verification equipment attach rate assumptions. Industry-specific inputs incorporated IRA production tax credit qualification timelines and EU F-Gas Regulation phase-down schedules.
Caveats apply where South African platinum-group metal supply disruptions, EU Hydrogen Bank auction outcome revisions, or MEMS sensor reliability field data could materially shift the outlook. Forecasts reflect documented assumptions regarding electrolyzer capacity realization rates and pipeline injection standard harmonization timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Chromatography Market
Testing Equipment
Material Testing Market
Testing Equipment
Chlorine Meter Market
Testing Equipment
Automated Solid Phase Extraction Systems Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
In-Line UV-Vis Spectroscopy Market
Testing Equipment
Chemical Testing Services Market
Testing Equipment
Lubricant Testing Machine Market
Testing Equipment
High Performance Liquid Chromatography (HPLC) Market
Testing Equipment
Global Rheometer and Viscometer Market
Testing Equipment
Adhesive Tester Market
Testing Equipment
Benchtop Density Meter for Solids Market
Testing Equipment
Global Laboratory Analytical Instruments and Consumables Market
Testing Equipment
Viscometer Market
Testing Equipment
In Line Process Viscometer (ILPV) Market
Testing Equipment
Solar Testing Equipment Market