
 Europe Process Analytics Market | 2026-2036
Europe Process Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Process Analytics Market Insights
The capital-intensity divergence between hardware-centric instrument makers and software-native analytics platforms is collapsing as both camps invest in hybrid edge-to-cloud architectures. Siemens AG leverages its automation hardware footprint to bundle analytics software through its industrial edge portfolio. ABB Ltd. anchors its position in process industries with integrated control systems that embed real-time analytical modules. Emerson Electric Co. competes through acquisition of specialized analytics firms rather than organic software development.
Process analytics encompasses the systematic measurement, interpretation, and optimization of operational data streams using spectroscopic, chromatographic, and chemometric methods to ensure product quality and process efficiency in continuous and batch manufacturing environments. The technology deploys in-line sensors operating at temperatures up to 400°C and pressures exceeding 200 bar to deliver real-time compositional data without sampling delays. Cloud-based deployment now leads in new implementations among mid-sized chemical producers seeking scalable infrastructure without capital expenditure, while on-premises systems retain dominance in pharmaceutical audit-trail environments where data residency requirements are non-negotiable. Machine learning applications within process analytics represent the fastest-expanding technology segment as manufacturers deploy neural networks for multivariate statistical process control and anomaly detection in complex reaction kinetics.
EMA guidelines on process analytical technology and the EU's CSRD reporting requirements are tightening documentation standards for batch consistency and environmental footprint disclosure across European manufacturing. REACH substance registration protocols and the EU AI Act's risk classification framework for automated decision systems are reshaping vendor qualification criteria and software validation protocols. Stakeholders must monitor how the forthcoming EU pharmaceutical strategy revisions integrate real-time release testing requirements with existing GMP frameworks.
Market Dynamics
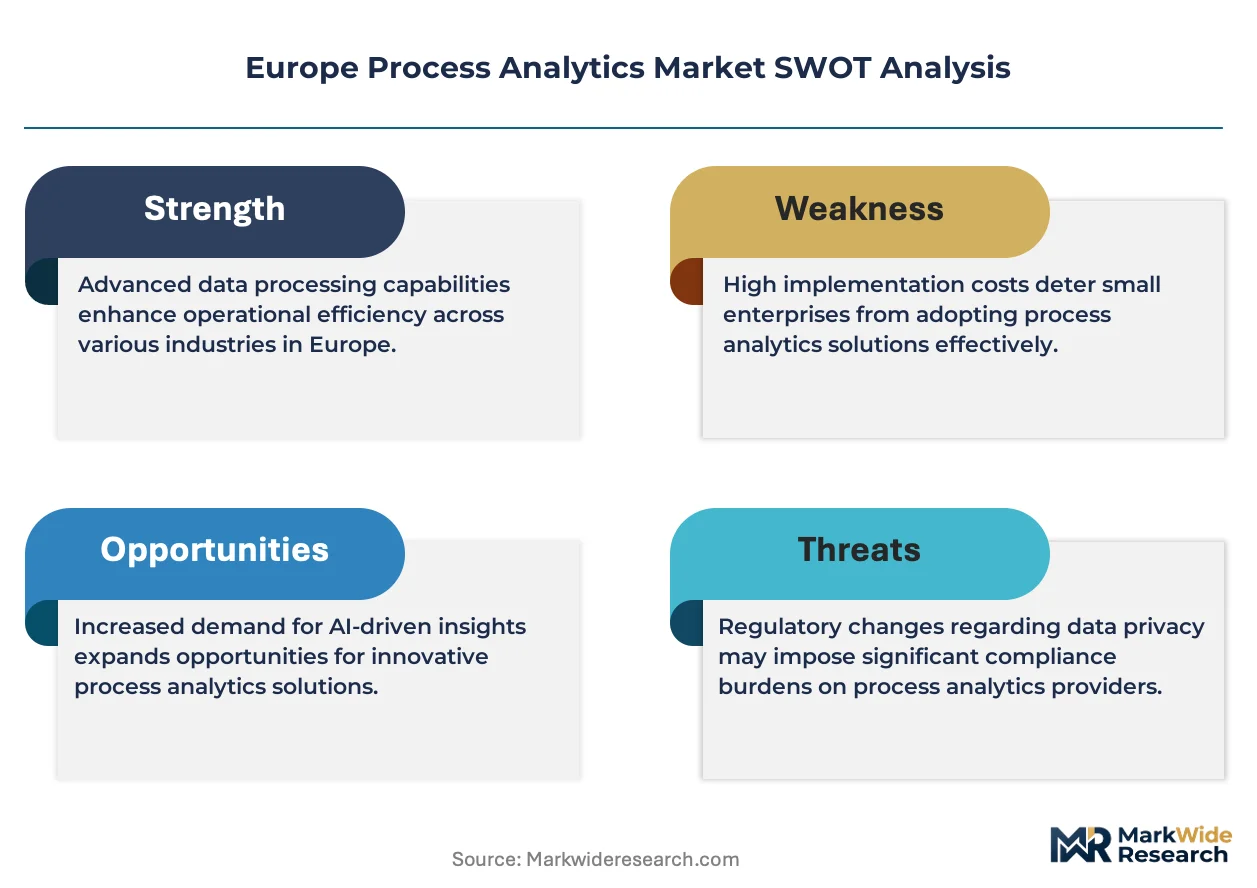
Cloud-based deployment architectures are compressing the traditional hardware-software boundary in European process analytics, forcing instrument vendors to restructure revenue models around subscription analytics services rather than capital equipment sales.
Growth Catalysts
- EMA Process Analytical Technology Guidelines:Batch release requirements for real-time quality verification are mandating in-line spectroscopic systems across German and French pharmaceutical manufacturing facilities.
- AI-driven chemometric platforms:Neural networks for multivariate statistical process control are compressing anomaly detection cycles in complex reaction kinetics for specialty chemical producers.
- ECHA substance tracking mandates:REACH registration protocols are requiring continuous compositional monitoring for high-volume chemical intermediates produced in Dutch and Swiss industrial clusters.
Market Restraints
- High-purity sensor materials:Sapphire optical windows and corrosion-resistant alloys for in-line probes face concentrated supply from specialized German and Japanese component suppliers.
- EU AI Act risk classification:Automated decision systems for quality release trigger stringent validation documentation requirements that extend software deployment timelines by 12-18 months.
- Legacy distributed control systems:Proprietary communication protocols in existing plant infrastructure create integration friction for open-architecture analytics platforms.
Strategic Opportunities
- Biotech clusters in Switzerland:Geneva and Basel regions show underpenetrated demand for cell culture analytics as contract manufacturing organizations expand capacity.
- EU CSRD environmental reporting:Mandatory process emissions disclosure is creating demand for integrated carbon-footprint analytics alongside traditional quality parameters.
- Edge-to-cloud hybrid architectures:Convergence of on-premises data residency with scalable cloud compute is opening mid-sized chemical producers previously locked out of advanced analytics.
Industry Challenges
- Chemometric modeling expertise:Shortage of specialists capable of developing and validating multivariate calibration models for complex pharmaceutical reaction pathways.
- EU GMP Annex 15 compliance timelines:Computerized system validation requirements for cloud-deployed analytics extend qualification periods and delay production release.
- Interoperability with legacy historians:Data extraction from 1990s-era plant databases requires custom middleware development for audit-trail continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Process Analytics Market |
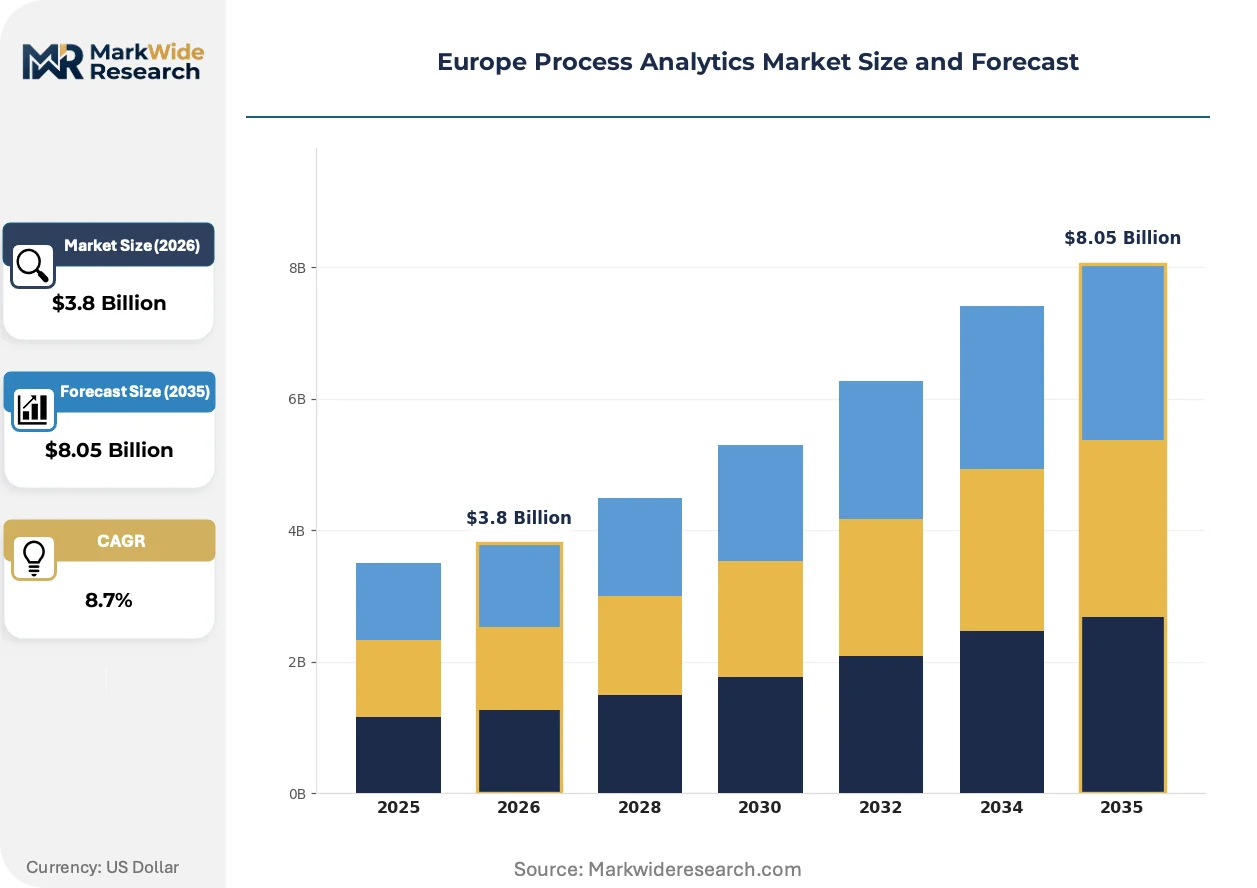
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Application: Business Process Management, Performance Management, Data Management, Compliance Monitoring End User: Manufacturing, Telecommunications, Retail, Government Technology: Machine Learning, Data Mining, Artificial Intelligence, Business Intelligence |
| Companies Covered | Siemens AG, ABB Ltd., Emerson Electric Co., Endress Hauser, Yokogawa Electric Corporation, Thermo Fisher Scientific Inc., AMETEK Inc., Mettler-Toledo International Inc., Horiba Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Process Analytics Market Trends and Innovations
Real-time analytical instrumentation is undergoing fundamental redesign as manufacturers demand measurement capabilities directly at process connection points without sample conditioning infrastructure.
Raman spectroscopy is miniaturizing through solid-state laser and compact detector integration, enabling direct insertion probes for bioreactor monitoring without fiber-optic coupling. Biopharmaceutical manufacturers in Ireland and Denmark are deploying these probes at pilot scale with plans for commercial manufacturing expansion. The technology is miniaturizing the footprint of quality control laboratories, compressing the physical separation between production and analytical functions into unified manufacturing suites.
EU Green Deal industrial emissions targets are mandating continuous pollutant monitoring for chemical installations above threshold capacity, extending process analytics scope beyond quality to environmental compliance. The F-Gas Regulation is accelerating replacement of gas chromatography carrier gases with hydrogen or helium alternatives, forcing method redevelopment across installed analytical bases. German chemical producers in the Ruhr region are most affected, retrofitting existing systems while qualifying alternative analytical approaches.
Service unbundling is separating hardware maintenance from software subscription renewals, allowing mid-sized producers to source analytical modules from specialized vendors while retaining incumbent automation suppliers for control system support. Chemical distributors in the Netherlands are introducing rental models for portable spectroscopic equipment, displacing capital purchase for seasonal or campaign-based manufacturing. This shift is most visible among contract manufacturers serving agrochemical and fine chemical markets with irregular production schedules.
Europe Process Analytics Market Segmentation
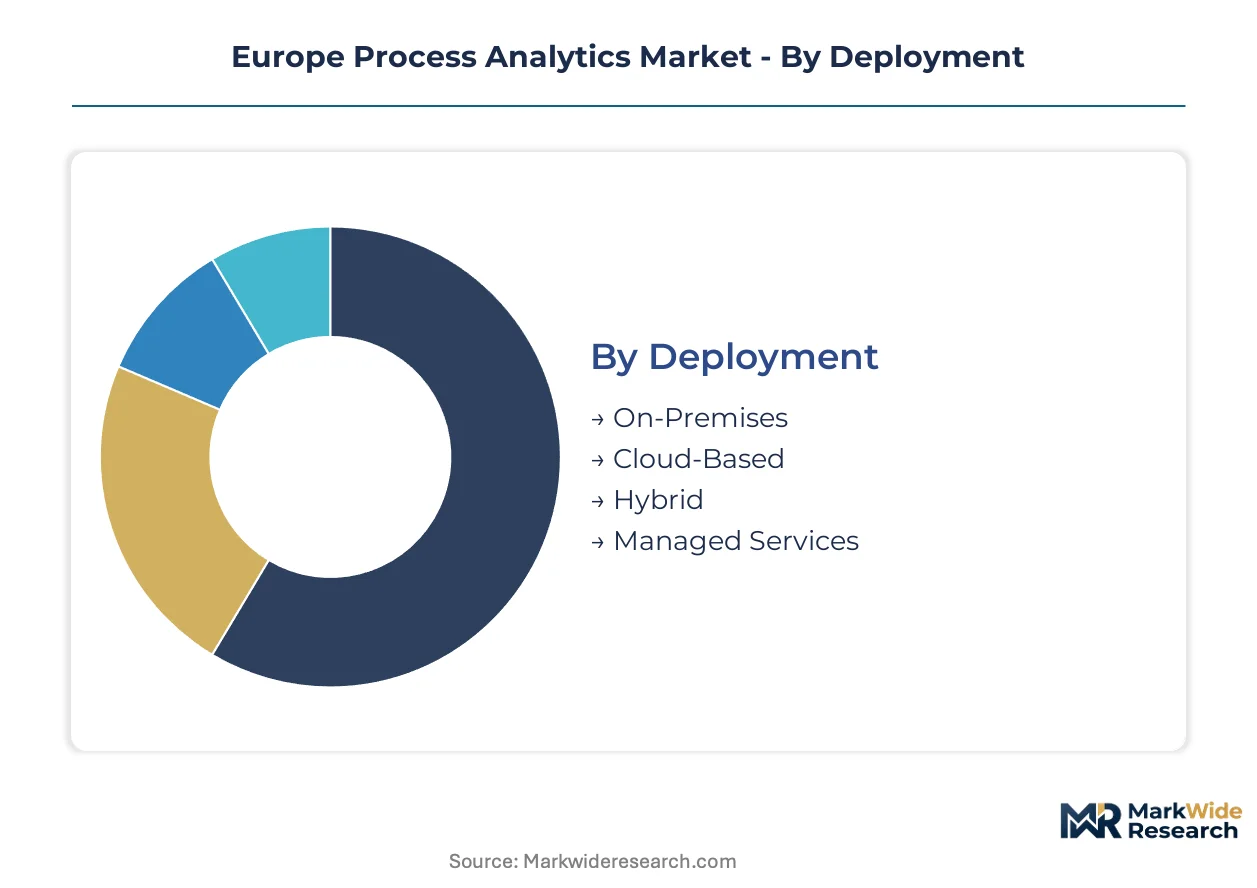
Deployment architecture choices determine capital recovery cycles and data sovereignty compliance in European process analytics procurement. Application focus areas reflect divergent regulatory pressures across EMA pharmaceutical mandates and EU CSRD environmental disclosure requirements. End user concentration in manufacturing clusters versus service sector adoption shapes vendor go-to-market investments.
Deployment:
Margin pools concentrate in recurring revenue streams rather than upfront hardware sales as vendors pivot to subscription analytics services.
- On-Premises:Dedicated server infrastructure maintains data residency within facility boundaries for pharmaceutical audit-trail requirements. German and French manufacturers favor this model for EMA batch release documentation where cloud egress triggers compliance review.
- Cloud-Based:Scalable compute resources eliminate capital expenditure for mid-sized chemical producers seeking neural network training capacity. Dutch industrial clusters deploy this architecture to satisfy ECHA substance tracking mandates without infrastructure ownership.
- Hybrid:Edge processing for real-time control decisions couples with cloud analytics for model development and regulatory reporting.
- Managed Services:Third-party operation of analytical infrastructure transfers compliance liability to specialized service providers.
On-Premises holds installed capacity. Cloud-Based is rotating up the share rankings.
Application:
Compliance Monitoring commands premium pricing due to non-negotiable regulatory deadlines and validation documentation requirements.
- Compliance Monitoring:Automated audit-trail generation for EU GMP Annex 15 and REACH substance tracking protocols. Swiss biotech manufacturers require continuous validation evidence for Swismedic inspections.
- Business Process Management:Workflow optimization across batch and continuous manufacturing operations with real-time deviation alerting. Specialty chemical producers in Belgium deploy these systems for campaign-based production scheduling.
- Performance Management:KPI dashboards linking operational metrics to environmental footprint disclosure under CSRD mandates.
- Data Management:Historian integration and spectral data archiving for long-term batch record retention.
Compliance Monitoring anchors vendor profitability. Business Process Management is climbing the fastest as operational efficiency pressures intensify.
End User:
Manufacturing absorbs the majority of spectroscopic and chromatographic instrumentation spend due to in-line sensor density requirements.
- Manufacturing:Pharmaceutical, chemical, and biotech production facilities deploying Raman probes and near-infrared spectrometers for real-time release testing. Irish biopharmaceutical sites lead European adoption of direct insertion bioreactor monitoring.
- Telecommunications:Network infrastructure monitoring for predictive maintenance and energy optimization.
- Retail:Supply chain analytics for perishable goods tracking and cold chain integrity verification.
- Government:Environmental monitoring stations and regulatory inspection laboratories.
Manufacturing dominates current deployments. Telecommunications is gaining share fastest as edge analytics penetrate infrastructure management.
Technology:
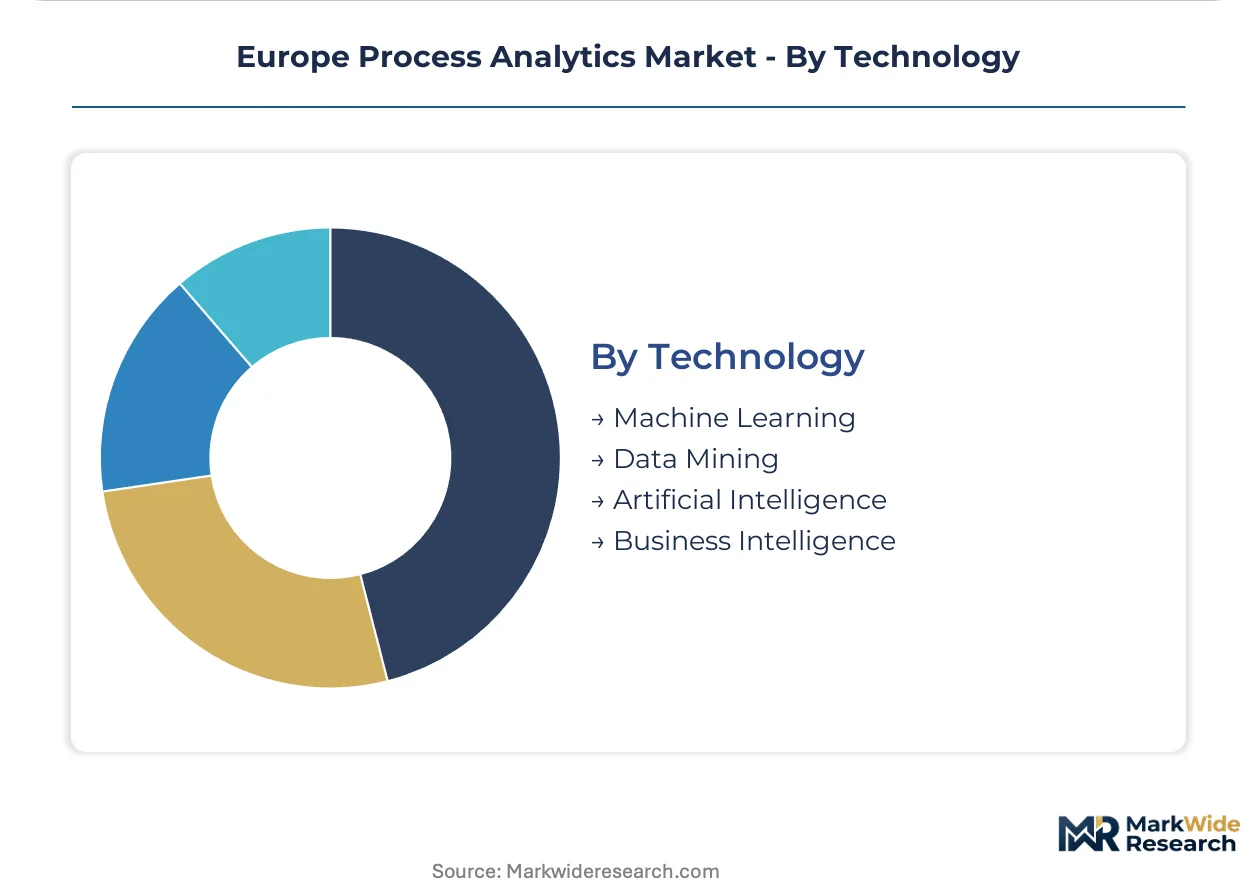
Artificial Intelligence carries the steepest pricing premium where neural network validation for quality release decisions requires specialized expertise.
- Artificial Intelligence:Deep learning architectures for multivariate calibration and anomaly detection in complex reaction kinetics. The EU AI Act risk classification framework imposes stringent documentation burdens on automated quality release systems.
- Machine Learning:Supervised and unsupervised algorithms for statistical process control with interpretable model outputs preferred for regulatory submissions.
- Data Mining:Pattern extraction from historical batch records to identify critical process parameters and design space boundaries.
- Business Intelligence:Visualization and reporting tools for operational dashboards and executive decision support.
Artificial Intelligence captures premium pricing. Machine Learning is expanding most quickly as interpretability requirements temper deep learning adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Switzerland and the Netherlands demonstrate the lowest price elasticity, absorbing premium analytics solutions for compliance-critical biotech operations. German and French pharmaceutical manufacturers show moderate sensitivity, balancing validation requirements against total cost of ownership. Mid-sized chemical producers in Poland and Spain exhibit the highest elasticity, prioritizing subscription-based cloud deployments over capital-intensive on-premises systems.
Germany
Ruhr region chemical producers and Bavarian pharmaceutical facilities drive concentrated demand for in-line spectroscopic systems. EMA batch release requirements under EU GMP Annex 15 mandate real-time quality verification infrastructure. Siemens AG anchors the industrial automation cluster in Munich, bundling analytics software through edge computing portfolios.
Switzerland
Geneva and Basel biotech clusters exhibit underpenetrated demand for cell culture analytics as contract manufacturing organizations expand capacity. Swismedic inspection protocols require continuous validation evidence for automated quality release systems. Swiss pharmaceutical manufacturers absorb premium pricing for hybrid edge-to-cloud architectures that satisfy data residency requirements.
Netherlands
Dutch chemical distributors pioneer rental models for portable spectroscopic equipment, displacing capital purchases for seasonal manufacturing campaigns. ECHA substance tracking mandates under REACH protocols drive continuous compositional monitoring for high-volume chemical intermediates. Rotterdam industrial clusters deploy cloud-based architectures to satisfy regulatory mandates without infrastructure ownership.
France
French pharmaceutical manufacturers expand process analytics adoption to meet EMA batch release requirements and computerized system validation standards. ANSM inspection protocols align with EU GMP Annex 15 compliance timelines. Lyon and Paris-region biotech facilities invest in AI-driven predictive quality models for complex reaction kinetics.
Ireland
Irish biopharmaceutical sites lead European adoption of direct insertion Raman probes for bioreactor monitoring at commercial manufacturing scale. IDA Ireland investment incentives attract contract manufacturing organizations expanding analytical infrastructure. Cork and Dublin clusters deploy miniaturized spectroscopic systems that compress quality control laboratory footprints into unified manufacturing suites.
Europe Process Analytics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure across European process analytics. Industrial automation conglomerates leverage hardware footprints to bundle software subscriptions, while specialized instrumentation vendors compete on measurement precision and regulatory validation depth. Three archetypes dominate: diversified automation suppliers with edge-to-cloud portfolios, pure-play analytical instrument specialists, and emerging software-native platforms. Consolidation through acquisition of specialized analytics firms and strategic partnerships for chemometric modeling expertise represent the dominant competitive moves.
Within the diversified automation tier, Siemens AG and ABB Ltd. exemplify players leveraging industrial control system installed bases to embed analytical modules. Emerson Electric Co. occupies a position representing acquisition-driven capability expansion rather than organic software development. Among analytical instrumentation specialists, Thermo Fisher Scientific Inc. and Mettler-Toledo International Inc. anchor the precision measurement segment, while Endress Hauser represents the process industry sensor specialist archetype with deep regulatory validation expertise.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd. |
| Emerson Electric Co. |
| Endress Hauser |
| Yokogawa Electric Corporation |
| Thermo Fisher Scientific Inc. |
| AMETEK Inc. |
| Mettler-Toledo International Inc. |
| Horiba Ltd. |
| Others |
Pricing and Supply Chain Analysis
Hydrogen carrier gas replacement for helium in gas chromatography systems simultaneously relocates supply dependence from Qatar and the US to regional electrolyzer projects in Germany and the Netherlands while compressing operating cost structures for Ruhr chemical producers. This substitution dynamic redistributes bargaining power toward domestic gas suppliers and reshapes total cost of ownership calculations for analytical instrument procurement.
Pricing Analysis
Extended service contracts and software subscription renewals generate lifetime value multiples exceeding original hardware margins for European process analytics vendors. Three-tier pricing structure across premium validation-grade, standard industrial, and economy portable equipment segments reflects divergent certification burdens under EU GMP Annex 15 and REACH protocols. Pricing pressure stems from mid-sized chemical producers in Poland and Spain prioritizing rental and subscription models over capital purchases. Pharmaceutical manufacturers in Germany and Switzerland exhibit lowest price sensitivity due to non-negotiable audit-trail requirements.
Supply Chain Analysis
Inventory buffers for sapphire optical windows and corrosion-resistant probe alloys stretch to six-to-nine months given concentrated German and Japanese component supply. Germany, Switzerland, and the Netherlands anchor European production of in-line spectroscopic systems, while specialized sensor materials draw from Japanese ceramics foundries and German precision machining clusters. Single-source vulnerability for high-purity sapphire substrates threatens probe availability during demand surges. Distribution runs through authorized automation integrators with regulatory validation expertise rather than direct equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German and Swiss pharmaceutical contract manufacturers as facility consolidation reduces the number of qualified procurement decision-makers. This consolidation intensifies price competition among vendors while elevating importance of regulatory validation depth.
For Market Incumbents: Fortify service contract retention through embedded chemometric modeling expertise that raises switching costs for pharmaceutical clients facing EMA inspection cycles. Acquire specialized AI validation consultancies to address EU AI Act documentation burdens before competitors capture this capability gap. Siemens AG and ABB Ltd. should deepen captive supply of edge computing hardware to defend against software-native platform entrants. For New Entrants and Emerging Players: Cloud-native chemometric platform services represent the most penetrable white space, as incumbents under-serve mid-sized Dutch and Belgian chemical producers with legacy on-premises architectures. Target seasonal agrochemical manufacturers in the Netherlands with rental spectroscopic equipment paired with subscription analytics. Pursue partnership routes with Rotterdam-area chemical distributors already embedded in campaign-based production scheduling. For Investors and Strategic Acquirers: Capital is best deployed toward software-native analytics platforms with validated AI quality release modules, as hardware-centric vendors face margin compression from hybrid cloud transitions. Long-term viability hinges on regulatory validation depth rather than measurement precision alone. Monitor EMA pharmaceutical strategy revisions for real-time release testing mandates as the inflection signal for accelerated platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of AI Validation Specialist | Addresses EU AI Act risk classification documentation burdens for automated quality release systems. |
| Edge-to-Cloud Hybrid Architecture Launch | Captures mid-sized chemical producers in the Netherlands seeking scalable infrastructure without capital expenditure. |
| Strategic Partnership with Chemical Distributor | Enables rental model penetration for seasonal agrochemical manufacturers in Belgium and the Netherlands. |
| Backward Integration into Sapphire Optics | Reduces single-source vulnerability for high-purity probe components from Japanese suppliers. |
| Regulatory Consulting Service Unbundling | Creates separate revenue stream for EU GMP Annex 15 validation support beyond equipment sales. |
Research Methodology
Desk research of EMA guideline documents, ECHA substance registration databases, and EU CSRD implementation frameworks preceded structured interviews with pharmaceutical plant managers, chemical procurement leads, analytical instrument R&D directors, and regulatory affairs specialists across Germany, Switzerland, and the Netherlands. Secondary validation drew from SEC filings of listed automation conglomerates, Cefic chemical industry reports, and customs trade data for spectroscopic instrument imports. Bottom-up demand modeling from individual facility deployments was triangulated against top-down market sizing from vendor revenue disclosures.
Variance decomposition across deployment architectures, application focus areas, and end-user concentration levels structured the analytical framework over the projection horizon. Segmentation dimensions modeled include on-premises versus cloud-based deployment, compliance monitoring versus business process management applications, and manufacturing versus telecommunications end-use sectors. CAGRs were derived from fitted growth curves calibrated to historical adoption rates for in-line spectroscopic systems and neural network validation timelines under EU AI Act protocols.
Forecasts assume regulatory continuity in EMA batch release requirements and EU AI Act risk classification frameworks; material policy shifts would require re-modeling of software deployment timelines and validation documentation burdens. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Sand Testing Equipments Market
Testing Equipment
Chromatography Accessories and Consumables Market
Testing Equipment
Gas Chromatography Columns Market
Testing Equipment
Flash Point Apparatus Market
Testing Equipment
Water Penetration Tester Market
Testing Equipment
Global Adsorption Equipment Market
Testing Equipment
Oxidation Stability Analyzer Market
Testing Equipment
Global Asbestos Testing Market
Testing Equipment
Gold Purity Tester Market
Testing Equipment
Combustion Testing Equipment Market
Testing Equipment
Global Silica Analyzer Market
Testing Equipment
Drop Weight Tear Tester Market
Testing Equipment
Wood Moisture Tester Market
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Asia-Pacific Process Analytics Market
Testing Equipment
Pitting Machines Market