
 Brittleness Tester Market | 2026-2036
Brittleness Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Brittleness Tester Market Analysis
Modular tester configurations is expanding as equipment vendors unbundle software, load cells, and environmental chambers into separately purchasable components. Testing Machines, Inc. leverages this architecture to let automotive clients upgrade digital acquisition without replacing mechanical frames. Qualitest International anchors its position through integrated temperature chambers that pair with its base units. Elastocon AB specializes in low-temperature brittleness systems for Nordic polymer suppliers.
A brittleness tester measures the temperature or impact energy at which a material transitions from ductile to brittle fracture, typically using cooled specimen clamps and controlled striking hammers to record failure points. These instruments serve polymer, rubber, and coating laboratories that must certify low-temperature performance for automotive, aerospace, and infrastructure applications. Digital testers capture the fastest equipment demand as laboratories replace dial-gauge mechanical units with sensor-based systems that log force-displacement curves to 0.1-degree precision. Composites testing generates premium pricing within the material type dimension because carbon-fiber and glass-reinforced polymers require specialized specimen geometries and non-standard clamping fixtures that mechanical legacy designs cannot accommodate.
ASTM International publishes D746 and D2137 protocols that govern low-temperature brittleness testing for plastics and rubber in North American markets, while JIS K 6261 and ISO 812 standards shape equipment specifications in Japan and European laboratories respectively. FDA material qualification requirements for medical device polymers further tighten traceability demands on digital tester data outputs. Stakeholders must monitor whether regional standards bodies harmonize specimen preparation rules, as divergence would fragment equipment design requirements and complicate multinational vendor service strategies.
Market Dynamics
Digital sensor architecture is compressing replacement cycles for mechanical brittleness testers as laboratories pursue traceable force-displacement data for polymer certification. Automotive OEMs in Germany and Japan now mandate digital validation protocols, forcing equipment vendors to reconfigure hardware-software bundling strategies.
Growth Catalysts
- ECE R118 automotive mandates:German OEMs require validated low-temperature brittleness data for polymer intake manifolds, driving digital tester procurement at Tier-1 suppliers.
- FDA material qualification:Medical device manufacturers must demonstrate traceable polymer performance data, accelerating replacement of dial-gauge mechanical units with sensor-based systems.
- Carbon-fiber composite testing:Aerospace and wind energy applications require specialized specimen geometries that mechanical legacy designs cannot accommodate, creating premium equipment demand.
Market Restraints
- Load cell supply concentration:Precision force sensors concentrate among Japanese and German component suppliers, exposing equipment vendors to input cost volatility and extended lead times.
- ISO 812 harmonization delays:Divergent specimen preparation rules between European and Asian standards bodies fragment equipment design requirements, complicating multinational service strategies.
- Mechanical tester residual value:Legacy dial-gauge units retain functional utility in cost-sensitive rubber compound laboratories, slowing digital replacement in emerging economies.
Strategic Opportunities
- India polymer laboratory expansion:Domestic automotive component manufacturing under BIS standards is creating demand for localized brittleness validation capacity.
- Modular software unbundling:Equipment vendors can sell digital acquisition modules separately from mechanical frames, capturing upgrade revenue without full system replacement.
- Integrated environmental chamber pairing:Temperature control systems that dock with base units address multi-protocol testing needs in centralized polymer research facilities.
Industry Challenges
- Metrology technician scarcity:Force calibration and sensor maintenance require specialized skills that polymer laboratories struggle to retain against semiconductor and aerospace compensation benchmarks.
- Multi-standard certification timelines:Equipment must simultaneously satisfy ASTM D746, JIS K 6261, and ISO 812 protocols, extending validation periods before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brittleness Tester Market |
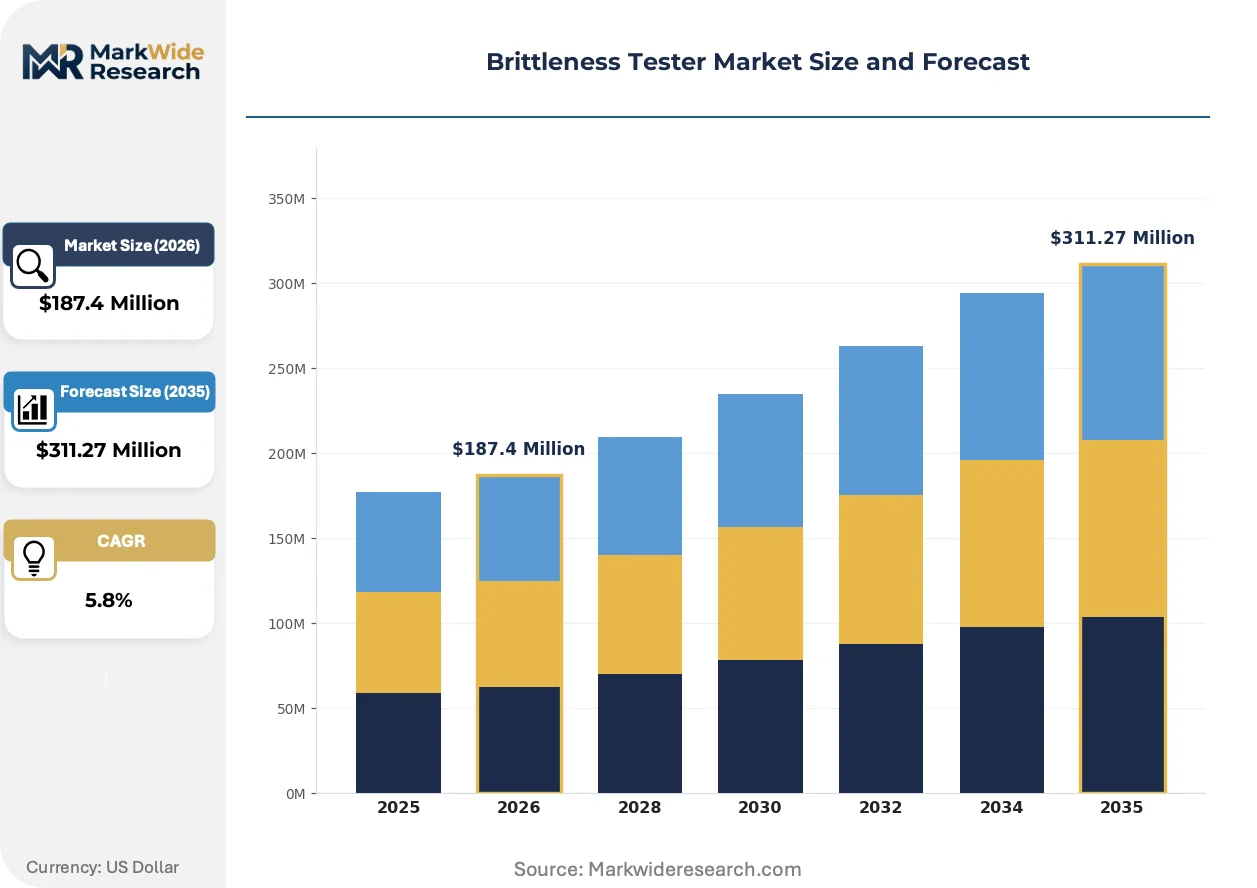
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Testers, Digital Testers, Portable Testers, Automatic Testers Material Type: Metals, Plastics, Ceramics, Composites End User: Manufacturers, Research Labs, Quality Control, Educational Institutions Application: Material Testing, Product Development, Quality Assurance, Compliance Testing |
| Companies Covered | Testing Machines, Inc., Qualtech Products Industry Co., Ltd, Qualitest International, Elastocon AB, Gotech Testing Machines Inc., CCSi, Inc., Ueshima Seisakusho Co., Ltd, Yasuda Seiki, Toyo Seiki Seisaku-sho, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brittleness Tester Market Emerging Trajectories
Sensor-based data acquisition is displacing mechanical measurement across polymer testing workflows, compressing the gap between raw specimen failure and actionable compliance documentation. This shift reconfigures vendor revenue models and laboratory capital allocation priorities.
Multi-channel digital data loggers is electrifying brittleness tester architecture by capturing force-displacement curves to 0.1-degree precision. Automotive polymer laboratories in Germany and Japan are adopting these systems at accelerated pace to satisfy ECE R118 and JIS K 6261 validation requirements. The technology is compressing certification cycle times while expanding the addressable market for premium equipment configurations.
REACH substance restrictions on phthalate plasticizers are reshaping polymer formulation strategies across European rubber and coating supply chains. Compound developers must validate alternative plasticizer performance under low-temperature conditions, generating incremental brittleness testing demand. Medical device and automotive sealing segments are most affected, with laboratories accelerating digital tester procurement to maintain compliance documentation.
After-sales service unbundling is altering equipment vendor economics as polymer laboratories seek à-la-carte calibration and software maintenance contracts. Traditional bundled service agreements are losing share to third-party metrology providers in the United States and Western Europe. This pattern concentrates among FDA-regulated medical device manufacturers where external calibration independence supports audit trail requirements.
Brittleness Tester Market Segmentation
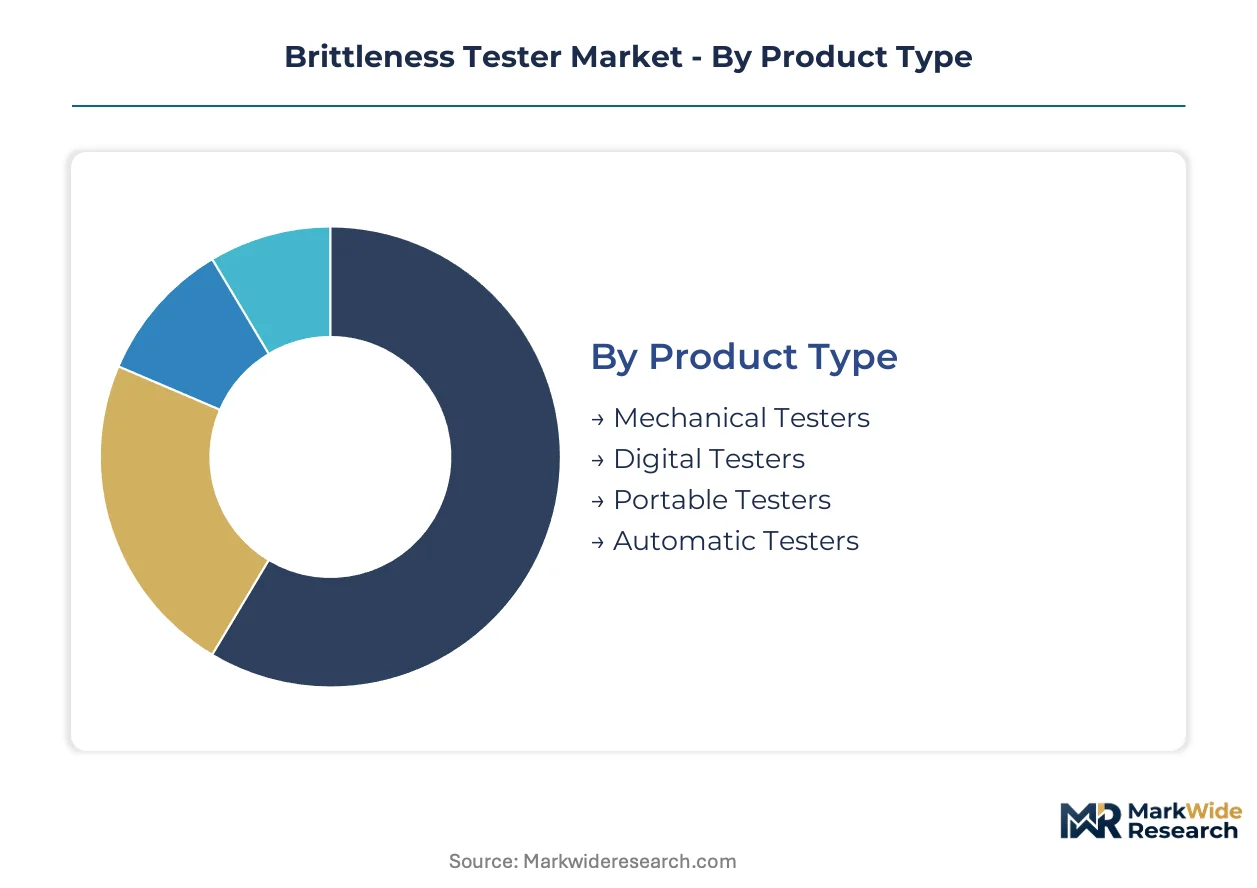
Brittleness tester procurement patterns diverge sharply across product architectures and material categories. Laboratories align equipment specifications with protocol mandates from ECE R118, ASTM D746, and JIS K 6261, fragmenting demand across precision tiers and environmental capabilities.
Product Type:
Equipment vendors navigate a customization-vs-standardization spectrum where digital acquisition modules unbundle from mechanical frames while portable units sacrifice environmental control for field deployment flexibility.
- Mechanical Testers:Dial-gauge systems with manual specimen clamping and striker hammers retain installed base in cost-sensitive rubber compound laboratories. Legacy units satisfy JIS K 6261 protocols at Japanese Tier-2 automotive suppliers where digital traceability requirements remain unenforced.
- Digital Testers:Sensor-based architectures capture force-displacement curves to 0.1-degree precision, logging compliance documentation for FDA material qualification. German automotive OEMs mandate these systems under ECE R118 for polymer intake manifold validation, compressing replacement cycles at Tier-1 suppliers.
- Portable Testers:Battery-powered field units sacrifice temperature chamber integration for on-site infrastructure inspection. Bridge coating contractors deploy these for rapid low-temperature adhesion verification.
- Automatic Testers:Robotic specimen handling systems reduce technician exposure to cryogenic coolants in high-throughput polymer research facilities. Aerospace composite laboratories favor these for carbon-fiber specimen batches.
Leading the category by volume: Mechanical Testers. Expanding most quickly: Digital Testers.
Material Type:
Specimen geometry complexity and clamping fixture specialization determine margin tiers, with carbon-fiber systems commanding premium pricing against standardized rubber pad configurations.
- Metals:Cryogenic steel validation for LNG infrastructure drives demand for ultra-low temperature chambers. Pipeline contractors specify these systems under ASTM E23 protocols for Charpy impact correlation.
- Plastics:Polymer laboratories dominate equipment utilization, with automotive intake manifolds and medical device housings requiring validated ductile-brittle transition data. REACH phthalate restrictions are accelerating alternative plasticizer testing cycles.
- Ceramics:Thermal shock resistance validation for aerospace heat shields employs specialized specimen geometries. NASA contractor facilities represent concentrated demand pockets.
- Composites:Carbon-fiber and glass-reinforced polymers require non-standard clamping fixtures that mechanical legacy designs cannot accommodate. Wind turbine blade manufacturers generate premium equipment demand for biaxial specimen testing.
Highest margin capture: Composites. Broadest addressable base: Plastics.
End User:
Capital allocation authority and compliance documentation requirements separate centralized research facilities from distributed manufacturing quality stations.
- Manufacturers:Tier-1 automotive suppliers in Germany and Japan deploy digital testers for ECE R118 and JIS K 6261 protocol compliance. Production line integration demands 99.5% uptime guarantees from equipment vendors.
- Research Labs:Centralized polymer research facilities require multi-protocol flexibility across ASTM, ISO, and JIS standards. Modular environmental chamber pairing addresses this need.
- Quality Control:High-throughput rubber compound screening prioritizes cycle time over precision. Mechanical testers retain share here.
- Educational Institutions:Training laboratories prioritize equipment durability and simplified maintenance over advanced data acquisition. State university systems in the United States represent cyclical procurement demand.
Dominant procurement authority: Manufacturers. Fastest upgrade cycles: Research Labs.
Application:
Regulatory filing requirements and product liability exposure determine whether laboratories invest in traceable digital systems or retain mechanical legacy units.
- Material Testing:Polymer certification for automotive and medical device applications demands force-displacement curve documentation. FDA traceability requirements are displacing dial-gauge systems.
- Product Development:Formulation laboratories iterate plasticizer alternatives under REACH restrictions. Digital testers compress validation timelines for new compound introduction.
- Quality Assurance:Production batch release testing prioritizes throughput over precision in rubber gasket manufacturing. Mechanical testers retain functional utility.
- Compliance Testing:Third-party laboratories serving multinational OEMs must simultaneously satisfy ASTM D746, JIS K 6261, and ISO 812 protocols. Multi-standard certification extends equipment validation periods.
Largest equipment installed base: Material Testing. Steepest digital replacement trajectory: Compliance Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment production clusters in Germany and Japan while consumption concentrates in the United States and China, creating a trade flow in precision load cells and digital acquisition modules. Laboratories in automotive and medical device hubs drive replacement cycles for mechanical legacy units.
United States
FDA material qualification protocols for medical device polymers accelerate digital tester procurement at Minnesota and Massachusetts device manufacturers. ASTM D746 compliance documentation requirements displace dial-gauge systems in polymer certification workflows. The Boston-Cambridge corridor hosts concentrated demand from biopolymer startups validating alternative formulations.
Germany
ECE R118 mandates for polymer intake manifolds force Tier-1 automotive suppliers to adopt sensor-based validation systems. KBA enforcement of low-temperature brittleness data requirements compresses replacement cycles at Stuttgart and Munich polymer laboratories. Bavaria's automotive supplier density generates premium equipment demand for multi-protocol testing configurations.
Japan
JIS K 6261 standard compliance drives digital tester adoption at Yokohama and Nagoya rubber compound facilities. METI-backed polymer research initiatives expand centralized laboratory capacity for next-generation elastomer validation. The Chubu region's tire manufacturing cluster sustains demand for automated specimen handling systems.
China
Domestic automotive component manufacturing under GB standards creates demand for localized brittleness validation capacity in Shanghai and Guangdong polymer laboratories. MIIT industrial upgrading programs accelerate replacement of imported mechanical units with domestically assembled digital systems. The Yangtze River Delta hosts the fastest-growing concentration of third-party compliance testing facilities.
India
BIS standard implementation for automotive sealing components drives procurement at Pune and Chennai Tier-2 suppliers. CDSCO traceability requirements for medical device polymers penetrate slowly, preserving mechanical tester share in cost-sensitive quality control stations. Gujarat's petrochemical corridor attracts modular equipment configurations for multi-material testing workflows.
Brittleness Tester Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the brittleness tester market, creating tiered competitive dynamics. Testing equipment divisions of broader instrumentation groups leverage cross-selling channels into polymer laboratories. Pure-play vendors anchor positioning through protocol-specific expertise and regional service density. Consolidation pressure concentrates among mid-scale mechanical tester fabricators unable to fund digital sensor integration. Strategic moves center on modular software unbundling and integrated environmental chamber partnerships.
Within the modular architecture tier, Testing Machines, Inc. and Qualitest International exemplify divergent approaches to hardware-software bundling. Elastocon AB occupies a position among Nordic-focused low-temperature specialists. These three anchors illustrate how geographic specialization and product architecture choices segment competitive positioning without requiring scale-driven conglomerate structures.
| Leading Market Players |
|---|
| Testing Machines, Inc. |
| Qualtech Products Industry Co., Ltd |
| Qualitest International |
| Elastocon AB |
| Gotech Testing Machines Inc. |
| CCSi, Inc. |
| Ueshima Seisakusho Co., Ltd |
| Yasuda Seiki |
| Toyo Seiki Seisaku-sho |
| Others |
Supply Flow & Price Mechanics
Metrology technician scarcity in Germany and Japan widens pricing-tier spreads as specialized force-calibration skills command semiconductor-industry compensation premiums, compressing margins on economy-grade mechanical testers while insulating premium digital-system pricing.
Pricing Analysis
Margin tightening in economy-tier mechanical units reflects residual functional utility in cost-sensitive rubber compound laboratories. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service bundling. Pricing pressure intensifies in standard-tier configurations as modular software unbundling lets laboratories upgrade acquisition modules without full-system replacement. Medical device manufacturers show least price sensitivity due to FDA traceability mandates, while Tier-2 automotive suppliers in emerging economies retain dial-gauge systems longest.
Supply Chain Analysis
Freight cost volatility for precision load cells from Japanese and German component suppliers amplifies input cost exposure for equipment vendors assembling in North America. Manufacturing concentrates in Germany, Japan, and the United States, with cryogenic cooling systems and force sensors drawing from concentrated specialist suppliers. Single-source vulnerability in precision sensor fabrication creates procurement risk. Distribution runs through direct vendor-laboratory relationships and third-party metrology service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
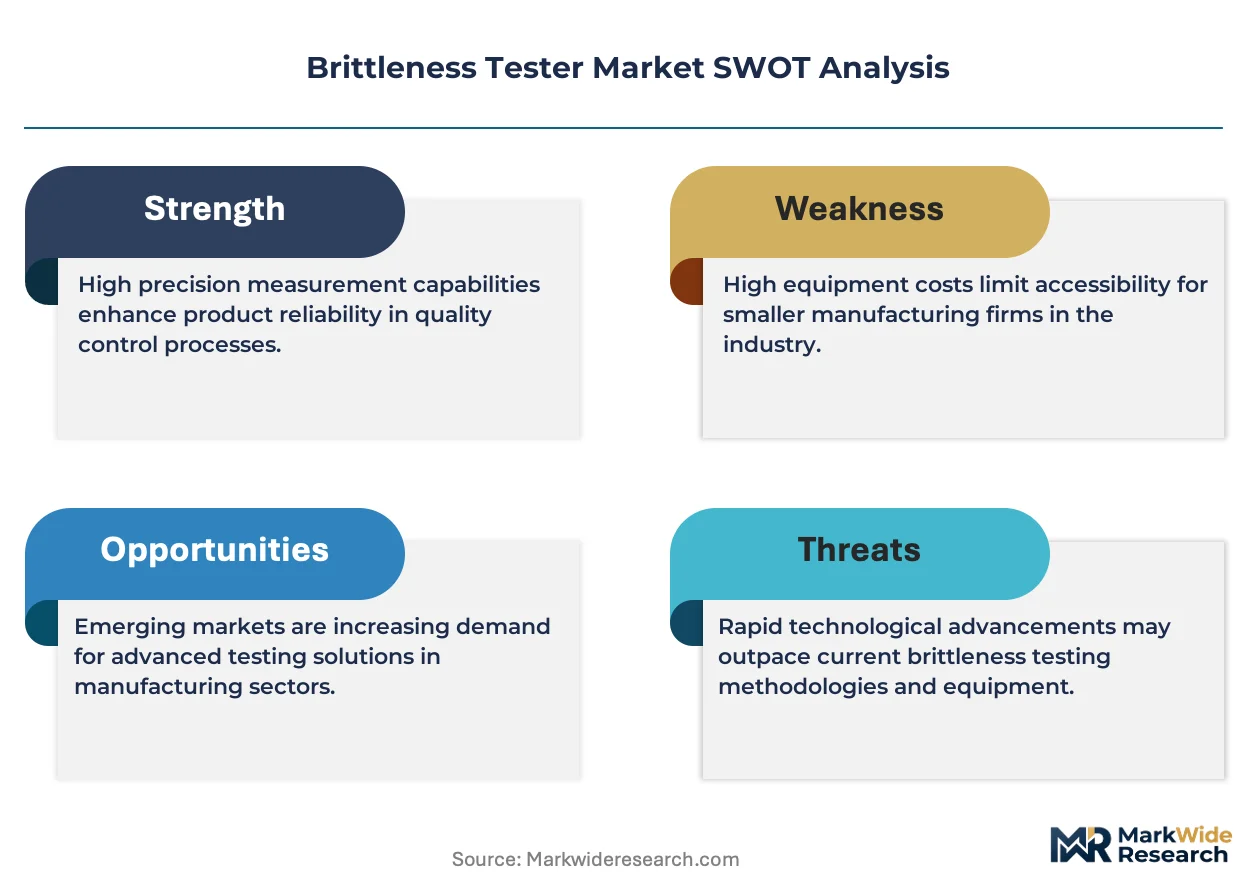
The brittleness tester market functions as a cost-of-compliance arena where ECE R118 automotive mandates erect barrier-to-entry moats for players lacking multi-standard certification capabilities.
For Market Incumbents: Hedge against modular architecture disruption by unbundling digital acquisition software from mechanical frames, capturing upgrade revenue without ceding position to third-party metrology providers. Accelerate integrated environmental chamber partnerships to defend against Qualitest International's temperature-control bundling strategy.
For New Entrants and Emerging Players: Sensor-based data acquisition platforms offer technology-first wedge opportunities in India's BIS-standard polymer laboratory expansion, where localized brittleness validation capacity lags domestic automotive component manufacturing growth. Target Pune and Chennai Tier-2 suppliers with modular configurations that pair with existing mechanical frames.
For Investors and Strategic Acquirers: Re-rating potential sits with Nordic-focused low-temperature specialists given REACH phthalate restriction tailwinds accelerating alternative plasticizer testing cycles. Long-term viability favors vendors with ISO 812, ASTM D746, and JIS K 6261 simultaneous certification capabilities. Watch METI-backed polymer research initiative funding trajectories as inflection indicators for Japanese laboratory capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Software Unbundling | Lets automotive clients upgrade digital acquisition without replacing mechanical frames, capturing recurring upgrade revenue. |
| Integrated Environmental Chamber Partnership | Addresses multi-protocol testing needs in centralized polymer research facilities requiring ASTM, ISO, and JIS flexibility. |
| Multi-Standard Certification Investment | Simultaneous ECE R118, FDA, and JIS K 6261 compliance opens Tier-1 automotive and medical device procurement channels. |
| Localized Service Density Buildout | India BIS-standard implementation creates demand for regional calibration and maintenance capabilities beyond equipment sale. |
| After-Sales Service Independence | External calibration contracts support FDA audit trail requirements for medical device manufacturers seeking vendor independence. |
Methodological Framework
SEC filings, ASTM International protocol documentation, and customs trade data formed the secondary backbone, cross-referenced against primary interviews with polymer laboratory directors, Tier-1 automotive supplier procurement managers, FDA regulatory affairs specialists, and aftermarket metrology service technicians. Bottom-up equipment shipment data triangulated against top-down polymer industry capital expenditure patterns.
Top-down macroeconomic drivers anchored the analytical lens while bottom-up vendor revenue and installation base estimates populated segment-level models. Product type, material category, end-user vertical, and geographic regulatory cluster dimensions structured the forecast framework. CAGRs derived from regression analysis against automotive production forecasts and medical device polymer qualification timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ISO 812 harmonization delays or load cell supply disruptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
Global Liquid Process Analyzer Market
Testing Equipment
Chemical Testing Services Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
Global Oxidative Stress Assay Market
Testing Equipment
Paint Tester Market
Testing Equipment
Adhesive Tester Market
Testing Equipment
Paper Tester Market
Testing Equipment
Leather Testing Machine Market
Testing Equipment
Steel Testing Equipment Market
Testing Equipment
Dynamic Light Scattering (DLS) Measure Instrument Market
Testing Equipment
Solid Density Tester Market
Testing Equipment
Flash Point Apparatus Market
Testing Equipment
Microplastics Particle Size and Shape Characterization Systems Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
In Vitro Toxicity Testing Market