
 High-Intensity Sweeteners Market | 2026-2036
High-Intensity Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
High-Intensity Sweeteners Market Analysis
Ingredient customization revenue is reshaping margin pools across the high-intensity sweeteners value chain, pulling profitability away from commodity bulk sales toward tailored blending and formulation services. Tate & Lyle PLC leverages its deep technical application expertise to anchor premium positions in beverage reformulation partnerships. Cargill Incorporated sustains broad supply security through its integrated agricultural sourcing and global distribution infrastructure. Ajinomoto Co., Inc. specializes in amino acid-derived sweetener chemistry, occupying a defensible niche in aspartame production scale.
High-intensity sweeteners are non-caloric or low-caloric compounds, typically 200 to 600 times sweeter than sucrose, produced through chemical synthesis or extraction and purification from plant sources such as Stevia rebaudiana, serving primarily to reduce sugar content in processed foods and beverages while maintaining desired sweetness profiles. Sucralose and steviol glycosides lead volume consumption due to their heat stability and clean taste profiles, with steviol glycosides recording the fastest trajectory as clean-label preferences intensify across food and beverage categories. The powder form dominates industrial procurement channels, though liquid concentrates gain traction in beverage manufacturing lines seeking streamlined batch processing and reduced handling costs.
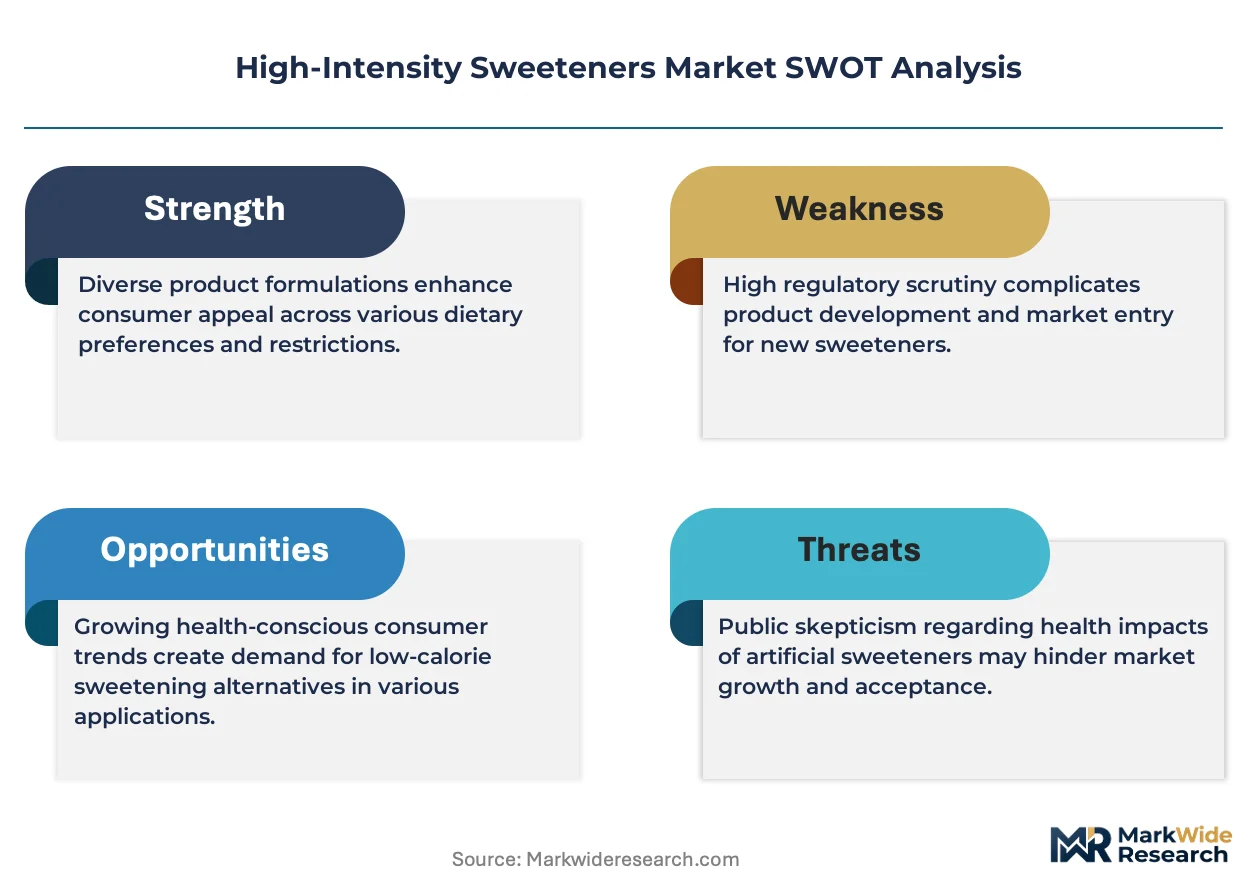
The FDA governs food additive safety evaluations and acceptable daily intake thresholds in the United States, while EMA's EFSA panel provides parallel scientific opinions that shape European market access conditions for novel sweetener entrants. REACH compliance requirements in Europe add substance registration burdens that favor established suppliers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving WHO guidance on non-sugar sweeteners and anticipate how shifting national dietary guidelines will redirect R&D investment toward next-generation natural extraction technologies.
Market Dynamics
Clean-label reformulation pressure from beverage manufacturers is restructuring procurement relationships across the high-intensity sweeteners value chain, forcing suppliers to abandon commodity bulk positioning in favor of integrated formulation partnerships.
Growth Catalysts
- US FDA GRAS self-affirmation pathways:Accelerated market entry timelines for novel steviol glycoside variants enable faster commercialization cycles compared to full food additive petitions.
- Beverage reformulation mandates:Sugar reduction targets in carbonated soft drinks and ready-to-drink teas pull high-intensity sweetener volumes into mainstream product portfolios.
- Enzymatic biotransformation:Engineered yeast platforms for producing rare steviol glycosides like Reb M and Reb D are collapsing cost curves for taste-optimized natural alternatives.
Market Restraints
- Stevia leaf supply concentration:Raw material sourcing clusters in China and Paraguay expose processors to climate volatility and geopolitical friction.
- Acceptable daily intake ceilings:EFSA's stringent ADI thresholds for certain cyclamate applications restrict formulation flexibility in European confectionery.
- Bitterness masking requirements:Lingering off-taste profiles in high-rebaudioside extracts necessitate costly companion flavor systems.
Strategic Opportunities
- Pharmaceutical excipient applications:Pediatric and geriatric dosage forms present untapped demand for palatable, non-caloric coating and bulking agents.
- EU Green Deal bioeconomy incentives:Fermentation-derived sweetener production qualifies for sustainable finance taxonomy alignment and preferential lending.
- Direct-to-beverage liquid dosing systems:Precision dispensing equipment integration opens service revenue streams beyond ingredient supply.
Industry Challenges
- Regulatory affairs specialization shortage:Navigating divergent GRAS, Novel Food, and FEMA FEMA GRAS pathways requires scarce cross-jurisdictional expertise.
- Clean-label certification backlog:Third-party non-GMO and organic verification queues delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Intensity Sweeteners Market |
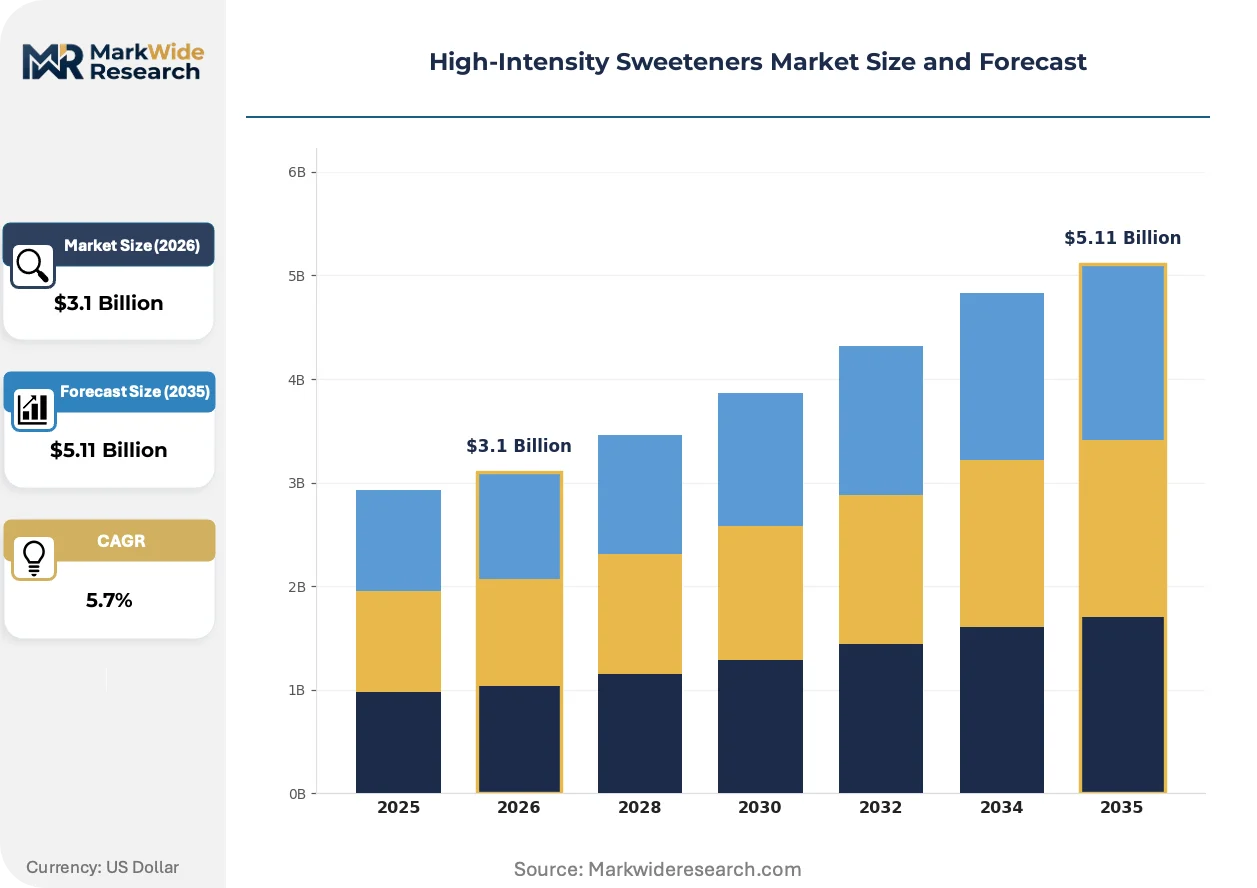
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.11 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aspartame, Sucralose, Steviol Glycosides, Acesulfame K Application: Beverages, Bakery Products, Dairy Products, Confectionery End User: Food Manufacturers, Beverage Companies, Retailers, Restaurants Form: Liquid, Powder, Granular, Tablets |
| Companies Covered | Tate & Lyle PLC, Cargill Incorporated, Archer-Daniels-Midland Company, Ingredion Incorporated, Ajinomoto Co., Inc., DuPont de Nemours, Inc., Südzucker AG, Mitsubishi Corporation, JK Sucralose Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Intensity Sweeteners Market Emerging Trajectories
Biotechnology-enabled production methods and evolving procurement specifications are compressing traditional extraction economics while opening molecular precision advantages previously unavailable to natural sweetener platforms.
Enzymatic glycosylation platforms are migrating from pilot-scale demonstrations to commercial deployment. Contract manufacturers in North America and Europe are installing 100,000-liter bioreactor capacity to supply beverage brands with rare steviol glycosides. This migration from chemical extraction to cell-cultured production is collapsing the historical price premium between natural-identical and plant-derived molecules.
REACH substance registration requirements in Europe are tightening documentation burdens for imported steviol glycoside preparations. ECHA's updated guidance on complex natural substance characterization demands expanded toxicological dossiers. Mid-sized importers lacking dedicated regulatory affairs teams are ceding market position to suppliers with in-house registration capabilities.
Long-term offtake agreements are replacing spot-market purchasing for high-volume beverage accounts. Procurement teams at multinational soft drink manufacturers are consolidating supplier panels to three to five qualified partners per sweetener category. This concentration is most visible in North America, where reformulation timelines of 18-24 months reward relationship continuity over price arbitrage.
High-Intensity Sweeteners Market Segmentation
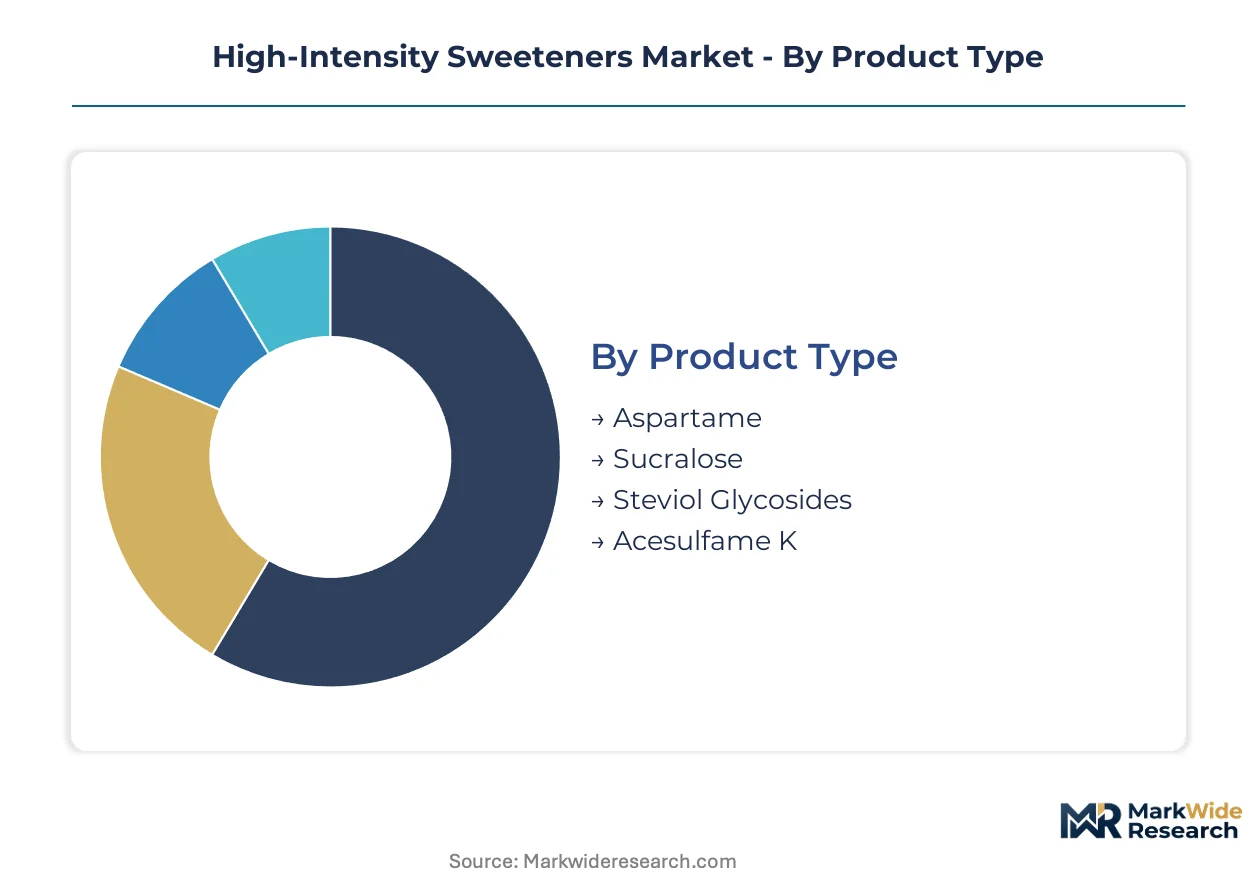
Segmentation in high-intensity sweeteners reveals how reformulation priorities diverge across customer types and delivery formats. Procurement specifications vary sharply between multinational beverage brands seeking heat-stable solutions and artisanal bakeries demanding label-friendly alternatives.
Product Type:
Mature synthetic chemistries dominate current procurement volumes, while emerging plant-derived platforms capture reformulation-driven growth.
- Steviol Glycosides:Purified extracts from Stevia rebaudiana leaves, primarily rebaudioside A and stevioside, deliver zero-calorie sweetness with heat stability up to 200°C. Beverage manufacturers in the United States prioritize these compounds as FDA GRAS self-affirmation pathways accelerate clean-label launches.
- Sucralose:A trichlorinated sucrose derivative synthesized through selective chlorination of sucrose, offering exceptional thermal stability and pH tolerance across baking and pasteurization processes. Carbonated soft drink producers rely on sucralose for consistent sweetness retention in high-temperature filling operations.
- Aspartame:A dipeptide methyl ester combining L-aspartic acid and L-phenylalanine, unstable above 30°C and in prolonged alkaline conditions.
- Acesulfame K:A potassium salt of 6-methyl-1,2,3-oxathiazine-4-one 2,2-dioxide, valued for synergistic blending with other sweeteners to mask off-tastes.
Steviol glycosides retain volume leadership; sucralose holds the steepest expansion curve in heat-processed applications.
Application:
Cost tier segmentation separates high-volume commodity formulations from precision-engineered specialty blends commanding formulation service premiums.
- Beverages:Carbonated soft drinks, ready-to-drink teas, and flavored waters represent the dominant consumption channel, with manufacturers demanding liquid concentrates for streamlined batch processing and reduced handling overhead in high-speed filling lines.
- Bakery Products:Cookies, cakes, and pastries require heat-stable sweeteners that maintain sweetness intensity through Maillard browning reactions and extended oven exposure.
- Confectionery:Hard candies, chewing gums, and chocolate coatings leverage high-intensity sweeteners for sugar-free positioning.
- Dairy Products:Yogurts, ice creams, and flavored milks incorporate sweeteners with freeze-thaw stability and clean dairy flavor compatibility.
Beverages command procurement priority; bakery applications are gaining share fastest as clean-label reformulation penetrates shelf-stable categories.
End User:
Customer type determines service intensity, with multinational accounts demanding integrated formulation partnerships and smaller buyers accepting commodity spot purchasing.
- Beverage Companies:Global soft drink manufacturers and regional ready-to-drink tea producers drive specification-setting through 18-24 month reformulation timelines that reward supplier relationship continuity.
- Food Manufacturers:Processed food producers across bakery, dairy, and confectionery segments require technical application support for sweetness optimization and bitterness masking.
- Retailers:Private label and store-brand product developers seek cost-optimized sweetener blends for competitive shelf positioning.
- Restaurants:Foodservice operators and chain restaurants utilize tabletop packets and bulk dispensing systems for customer-controlled sweetness.
Beverage companies anchor procurement volume; food manufacturers are expanding most quickly as reformulation mandates broaden across processed categories.
Form:
Supply concentration in powder processing infrastructure shapes availability, while liquid and specialty formats require differentiated production assets.
- Powder:Spray-dried and crystalline formats dominate industrial procurement channels, offering extended shelf stability and flexible dosing across dry-mix applications.
- Liquid:Aqueous concentrates and suspensions streamline beverage manufacturing through direct tank injection, eliminating dust handling and dissolution steps.
- Granular:Free-flowing agglomerated particles improve dispersibility in instant beverage and tabletop applications.
- Tablets:Compressed single-serve units serve foodservice and consumer tabletop segments.
Powder retains volume leadership; liquid concentrates are climbing the fastest as beverage manufacturers optimize line efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: beverage reformulation dominates procurement in the United States, while European buyers prioritize regulatory compliance and Asian markets emphasize cost-optimized bulk sourcing for processed food exports.
United States
Beverage manufacturers in Atlanta, Georgia and Purchase, New York drive steviol glycoside demand through aggressive sugar-reduction targets in carbonated portfolios. The FDA's GRAS self-affirmation pathway accelerates novel sweetener commercialization compared to full food additive petitions. Chicago and Minneapolis host concentrated technical application labs where suppliers co-develop customized blending formulations with multinational soft drink producers.
Germany
Confectionery and bakery producers in Cologne and Hamburg prioritize heat-stable sucralose for Maillard-compatible sugar-free positioning. REACH substance registration requirements administered by ECHA demand expanded toxicological dossiers for steviol glycoside imports. The Bavarian chemical cluster around Munich houses fermentation technology specialists developing enzymatic biotransformation platforms for rare glycoside production.
China
Stevia leaf processing concentrates in Shandong and Jiangsu provinces, supplying global extract demand through integrated agricultural sourcing networks. SAMR's food additive safety evaluations align with evolving GB standards for non-caloric sweetener applications. Qingdao and Shanghai serve as export logistics hubs where bulk powder shipments consolidate for North American and European beverage manufacturing lines.
Brazil
Processed food exporters in São Paulo and Minas Gerais integrate high-intensity sweeteners for cost-competitive sugar-free positioning in Latin American markets. ANVISA's food additive registry maintains parallel safety thresholds with Codex Alimentarius guidelines. The Campinas research corridor hosts application development centers where suppliers optimize sweetness profiles for tropical fruit beverage formulations.
India
Pharmaceutical excipient demand in Hyderabad and Mumbai drives specialized procurement for pediatric and geriatric dosage palatability. FSSAI's food safety standards govern sweetener usage thresholds across processed dairy and confectionery categories. The Gujarat industrial belt around Ahmedabad houses blending facilities serving both domestic food manufacturers and export-oriented contract manufacturing organizations.
High-Intensity Sweeteners Market Vendor Landscape
Capability concentration sits with specialized biotech developers; scale advantage sits with integrated agricultural processors. The market structures around three tiers: multinational ingredient conglomerates with formulation service arms, regional extraction specialists with captive leaf supply, and fermentation technology entrants collapsing cost curves for rare glycosides. Dominant competitive moves include long-term offtake agreements replacing spot purchasing and enzymatic platform licensing to secure next-generation production capacity.
Within the integrated agricultural tier, Tate & Lyle PLC and Cargill Incorporated exemplify suppliers anchoring premium positions through beverage reformulation partnerships. Ajinomoto Co., Inc. occupies a defensible niche representing amino acid-derived sweetener chemistry specialization. These three entities collectively illustrate how technical application expertise, supply security, and molecular precision each anchor distinct competitive positions without overlapping strategic territory.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Cargill Incorporated |
| Archer-Daniels-Midland Company |
| Ingredion Incorporated |
| Ajinomoto Co., Inc. |
| DuPont de Nemours, Inc. |
| Südzucker AG |
| Mitsubishi Corporation |
| JK Sucralose Inc. |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor carries steviol glycoside concentrates from Shandong processing facilities to European beverage manufacturers, with freight cost volatility amplifying price spreads between contract-bound multinationals and spot-market buyers while reinforcing procurement consolidation around integrated suppliers with captive logistics.
Pricing Analysis
Long-term offtake agreements now govern procurement for high-volume beverage accounts, replacing spot-market purchasing and compressing price variance between qualified suppliers. Price differentiation rests on formulation service bundling and regulatory dossier completeness rather than commodity purity alone. Cost compression in standard-grade steviol glycosides is intensifying as enzymatic biotransformation platforms expand capacity. Regional ready-to-drink tea producers exhibit the highest price sensitivity, while multinational soft drink manufacturers prioritize relationship continuity over arbitrage.
Supply Chain Analysis
REACH substance registration requirements administered by ECHA restrict market access for imported steviol glycoside preparations lacking expanded toxicological dossiers. Raw material sourcing clusters in China and Paraguay, with Shandong province hosting integrated extraction facilities and Paraguayan cooperatives supplying organic-certified leaf. Supply chain risk centers on climate volatility in subtropical growing regions. Distribution runs through bulk powder shipments consolidating at Qingdao and Shanghai for transoceanic routes, with liquid concentrate capacity expanding near North American beverage manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-jurisdictional regulatory affairs expertise has become the binding constraint on market access, with qualified specialists commanding premium compensation and bottlenecking product launches for mid-sized suppliers lacking in-house capabilities.
For Market Incumbents: Harden formulation service moats by embedding technical application teams within beverage manufacturer R&D facilities, co-developing customized bitterness-masking systems that lock in 18-24 month reformulation partnerships. Deepen upstream control over rare steviol glycoside production through exclusive enzymatic platform licensing, preempting fermentation entrants from collapsing cost curves on taste-optimized natural alternatives. For New Entrants and Emerging Players: Pharmaceutical excipient applications for pediatric and geriatric dosage palatability represent the most penetrable entry point, with Hyderabad and Mumbai contract manufacturing organizations seeking qualified non-caloric coating agents. EU Green Deal bioeconomy incentives for fermentation-derived production qualify for sustainable finance taxonomy alignment, opening preferential lending channels for bioreactor capacity installation. Target direct-to-beverage liquid dosing system integration as a service revenue wedge beyond commodity ingredient supply. For Investors and Strategic Acquirers: EFSA's evolving guidance on non-sugar sweeteners and WHO policy shifts reshape the acquisition landscape toward suppliers with dedicated regulatory affairs capabilities and in-house Novel Food dossier expertise. Fermentation technology specialists with commercial-scale enzymatic glycosylation platforms offer the strongest 5-10 year viability profile as cell-cultured production collapses historical price premiums. Monitor ECHA substance registration enforcement actions as the critical inflection signal for importer market share redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Beverage manufacturers consolidate supplier panels to three qualified partners per sweetener category. |
| Backward Integration | Integrated agricultural processors secure captive stevia leaf supply in Shandong and Paraguay. |
| Green Manufacturing Transition | Fermentation-derived sweetener production qualifies for EU Green Deal sustainable finance taxonomy. |
| Joint Venture | Enzymatic platform licensing partnerships secure next-generation Reb M and Reb D production capacity. |
| Regulatory Dossier Investment | Expanded toxicological documentation satisfies ECHA's updated complex natural substance characterization. |
Methodological Framework
Cross-validation between primary interviews with beverage formulation scientists, regulatory affairs directors at sweetener suppliers, procurement leads at multinational soft drink manufacturers, and technical application specialists anchors the qualitative findings. Secondary validation draws from FDA GRAS notifications, EFSA scientific opinions, ECHA substance registration databases, and customs trade data for steviol glycoside shipments. Bottom-up volume modeling triangulates against top-down market sizing across product type, application, and end-user segments.
Calibration against historical price points for standard-grade and premium-grade steviol glycosides, sucralose contract terms, and aspartame volume trends informs the analytical framework across the projection horizon. Segmentation dimensions include sweetener chemistry class, delivery format, heat stability specification, and regional regulatory cluster. CAGRs derive from trend extrapolation adjusted for technology diffusion curves and procurement pattern shifts. Forecast inputs incorporate enzymatic biotransformation capacity expansion timelines and beverage reformulation mandate implementation schedules.
Practitioners should monitor EFSA ADI threshold revisions, WHO non-sugar sweetener guidance updates, and climate disruption in Paraguayan growing regions for early signals requiring forecast reassessment. Material shifts in fermentation-derived production cost curves or REACH enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Africa and Middle East Sugarcane Syrup Market
Sweeteners
China Saccharin Market
Sweeteners
Mannitol Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
Africa Stevia Market
Sweeteners
Maltitol Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Brown Rice Syrup Market
Sweeteners
Oligofructose Market
Sweeteners
Rice Syrup Market
Sweeteners
Granulated Sugar Market
Sweeteners
China Allulose Market
Sweeteners
India Food Sweetener Market
Sweeteners
Natural Caloric Sweeteners Market
Sweeteners
United States Xylitol Market