
 China Allulose Market | 2026-2036
China Allulose Market Size, Share, and Industry Trends Forecast 2026-2036
China Allulose Market Insights
Multi-source procurement among sweetener buyers is shifting toward qualified domestic suppliers with enzymatic conversion capabilities. Shandong Sanyuan Biotechnology leverages its integrated fermentation infrastructure to anchor supply contracts with major beverage brands. Matsutani Chemical Industry competes through proprietary immobilized enzyme technology that sustains higher purity yields. Baolingbao differentiates via backward integration into corn starch feedstock, controlling input costs across volatile agricultural cycles.
Allulose is a rare monosaccharide, epimeric to fructose at the C-3 position, produced through enzymatic epimerization of fructose using D-tagatose 3-epimerase with typical purity grades exceeding 99%. The ingredient functions as a zero-calorie bulk sweetener with 70% sucrose sweetness and no glycemic impact, serving sugar-reduction formulations in processed foods and functional beverages. Powdered allulose leads volume share due to handling compatibility with existing dry-blend manufacturing lines, while liquid allulose captures faster growth from ready-to-drink beverage applications. Food manufacturers represent the dominant end-user channel, though nutraceuticals emerge as a high-margin segment for encapsulated and tableting grades.
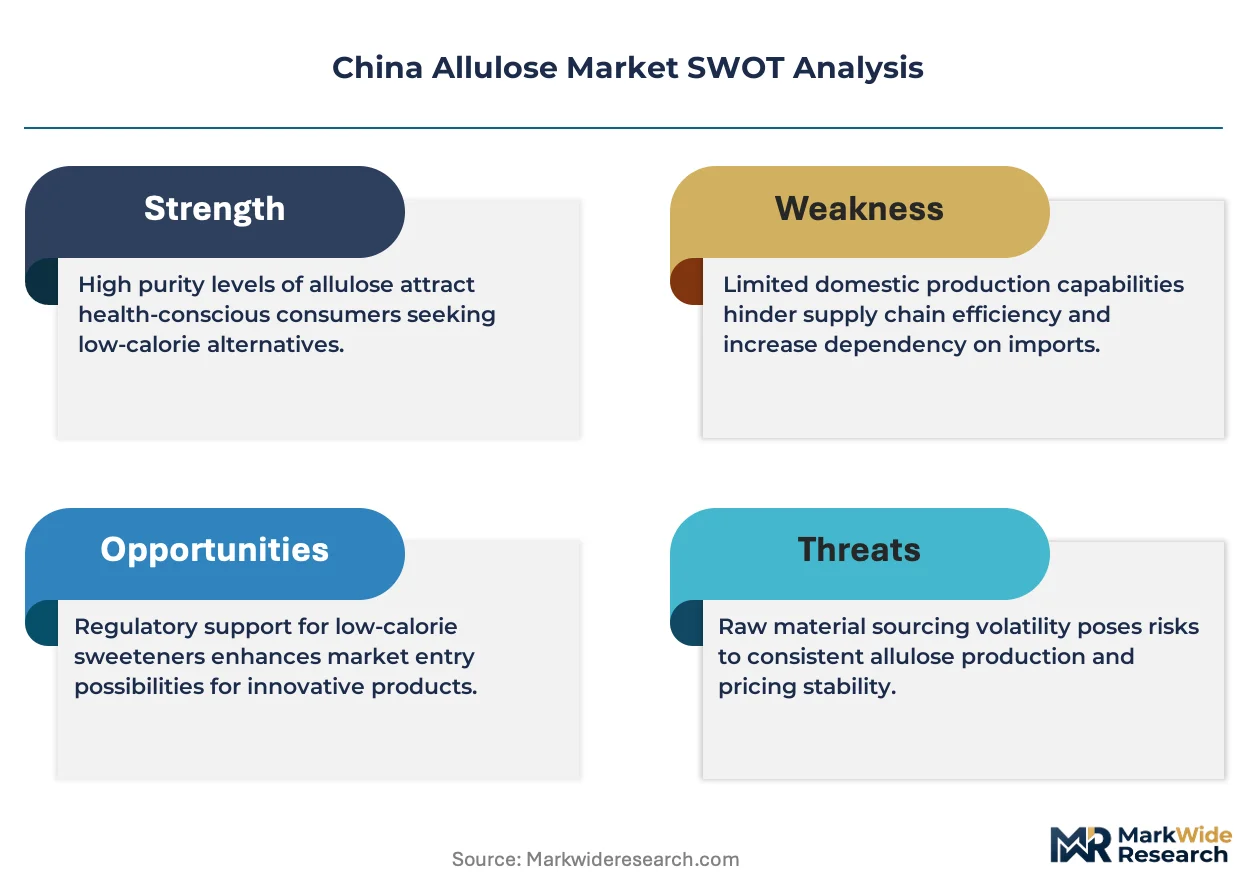
NHC novel food ingredient registration requirements determine market access timelines for new allulose producers, while GB standards for food additives establish purity and safety specifications. SAMR enforcement of labeling rules for low-glycemic claims shapes product positioning and consumer communication strategies. China's dual carbon goals pressure energy-intensive enzymatic production facilities toward renewable power sourcing. Stakeholders must monitor NHC approval queue acceleration and provincial green energy quotas to calibrate capacity expansion timing.
Market Dynamics
Enzymatic epimerization technology maturation is compressing production costs and redrawing competitive boundaries among Chinese allulose manufacturers. NHC novel food ingredient registration timelines now function as the primary gating mechanism for capacity expansion decisions.
Growth Catalysts
- Zero-sugar beverage formulations:Major beverage brands in China are reformulating carbonated and ready-to-drink tea portfolios with allulose as the preferred bulk sweetener to meet clean-label expectations.
- NHC approval pathway acceleration:Streamlined novel food ingredient registration procedures are shortening market entry timelines for domestic enzymatic conversion specialists.
- Shandong province fermentation infrastructure:Concentrated industrial biotechnology clusters provide shared utilities and skilled technical labor pools that lower greenfield facility costs.
Market Restraints
- Corn starch feedstock volatility:Agricultural commodity price swings directly compress margins for producers without backward integration into starch processing.
- Enzyme supplier concentration:Global supply of immobilized D-tagatose 3-epimerase concentrates among Japanese and Korean specialty enzyme houses, creating input bottlenecks.
- GB standards compliance friction:Evolving purity specifications for food additives force reformulation investments that disadvantage smaller fermentation operators.
Strategic Opportunities
- Functional confectionery expansion:Sugar-free chocolate and hard candy segments in tier-2 Chinese cities remain underpenetrated relative to beverage applications.
- Nutraceutical encapsulation grades:High-margin pharmaceutical-adjacent applications for tableting and controlled-release formulations command premium positioning.
- Dual carbon goals renewable energy sourcing:SAMR green energy quotas for industrial facilities create first-mover advantages for producers securing provincial wind and solar allocations.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation optimization and enzyme immobilization expertise concentrates among a limited pool of specialists with cross-training in food-grade GMP protocols.
- NHC registration documentation intensity:Novel food ingredient dossiers require extensive toxicology and stability studies that extend cash conversion cycles for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Allulose Market |
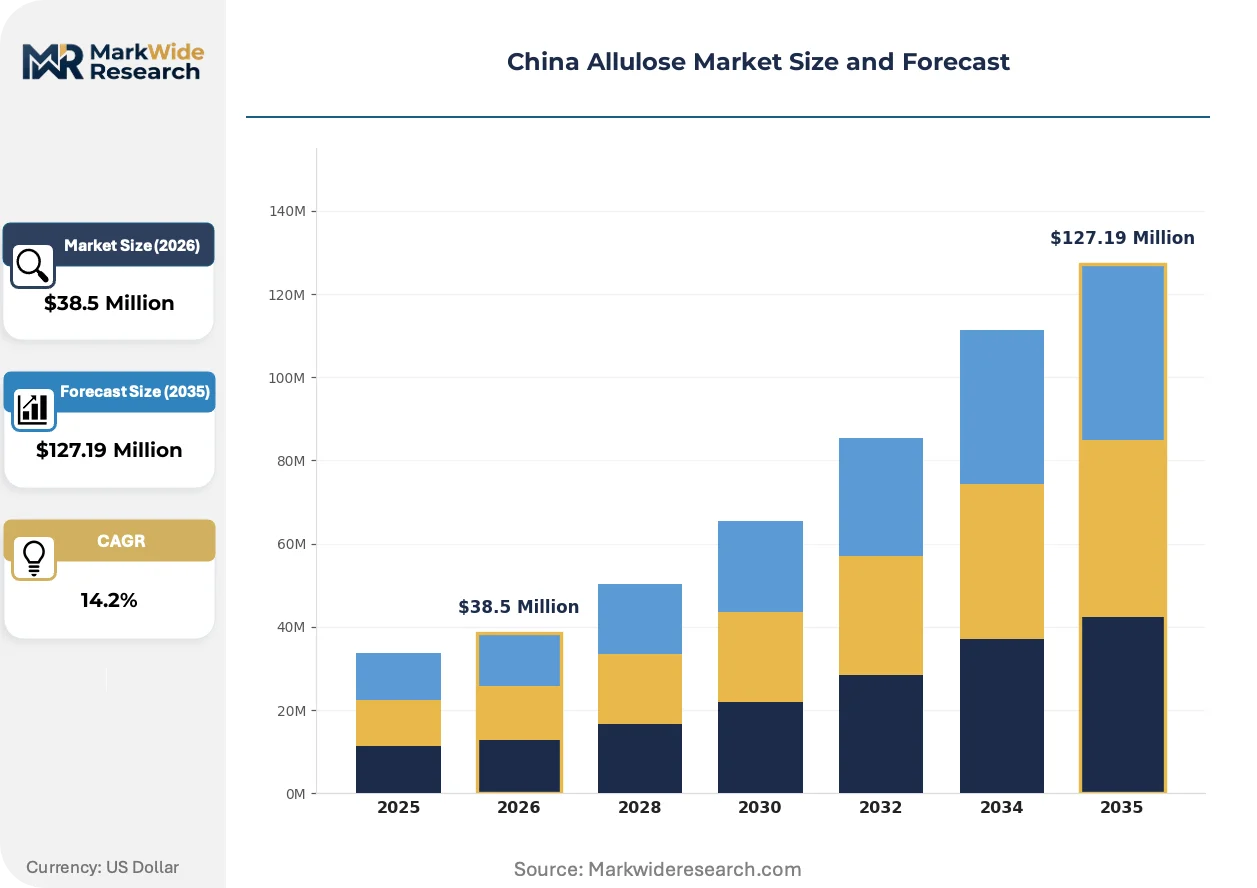
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $127.19 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Allulose, Powdered Allulose, Granulated Allulose, Syrup Allulose Application: Beverages, Bakery, Dairy, Confectionery End User: Food Manufacturers, Beverage Companies, Nutraceuticals, Personal Care Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Matsutani Chemical Industry, Shandong Sanyuan Biotechnology, Baolingbao, Ingredion Incorporated, Tate & Lyle, Sanyuan Biotech, Shandong Fuyang Bio-tech, Archer Daniels Midland Company, Dongxiao Biotech, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Allulose Market Trends and Innovations
Continuous enzymatic conversion systems are displacing batch fermentation as the dominant production architecture, compressing unit economics and enabling modular capacity scaling. This shift is redrawing supplier qualification criteria across Chinese beverage and food manufacturing channels.
Immobilized enzyme reactor technology is converging with membrane filtration purification systems to deliver higher-purity allulose streams with reduced downstream processing steps. Shandong-based fermentation specialists are retrofitting existing fructose syrup lines with continuous-flow epimerization modules. The technology convergence is compressing capital intensity requirements and enabling mid-scale producers to achieve parity yields with integrated majors.
GB standards for low-glycemic labeling claims are tightening disclosure requirements for sweetener blends and functional food positioning. SAMR enforcement actions against misleading metabolic health assertions are forcing reformulation transparency in marketing materials. Beverage manufacturers are responding by segregating allulose-dedicated production lines to maintain audit trail integrity for premium positioning.
Direct supplier relationships are displacing multi-tier distribution for bulk sweetener procurement among large Chinese food manufacturers. Tier-1 beverage brands are establishing qualified supplier programs with enzymatic conversion specialists, bypassing traditional chemical distributors. This pattern concentrates procurement leverage among coastal manufacturing clusters around Shanghai and Guangdong province.
China Allulose Market Segmentation
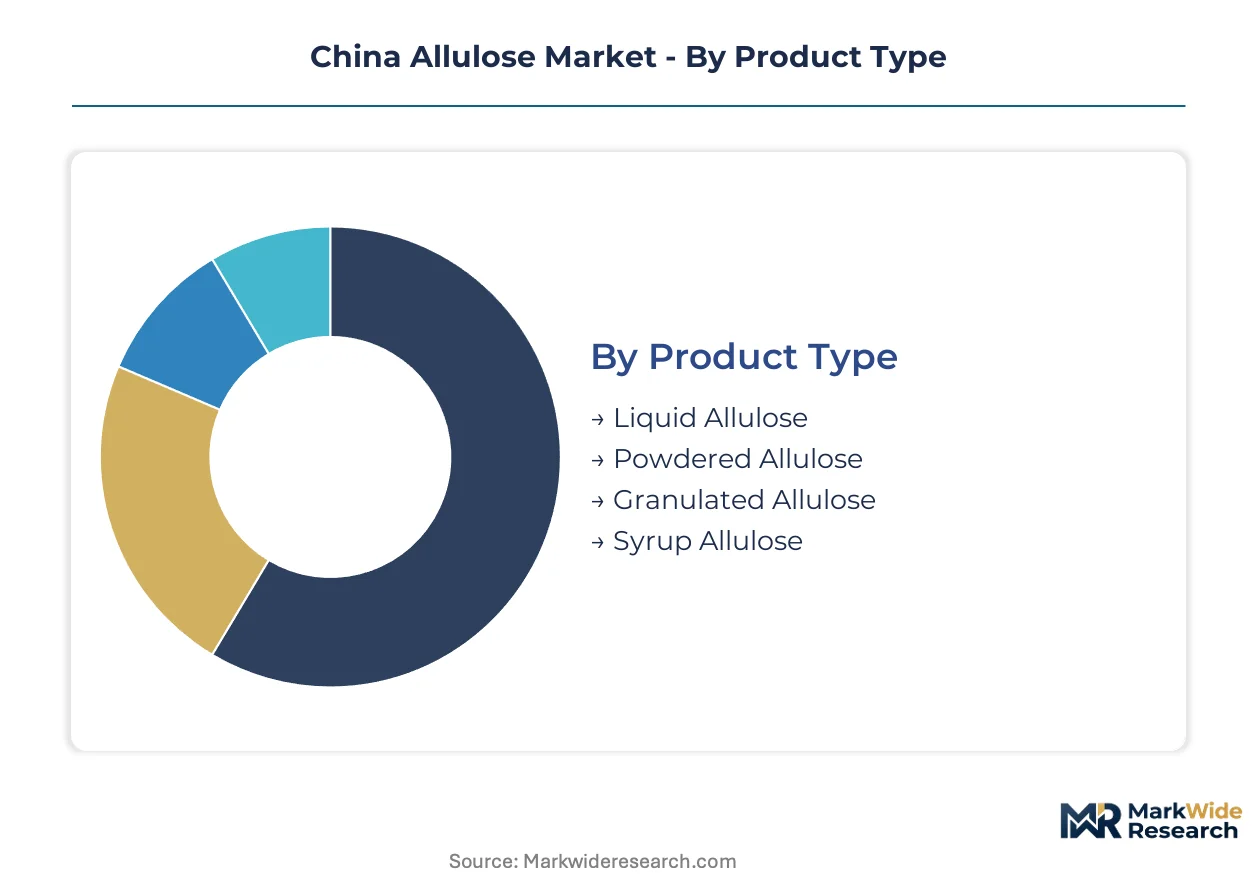
Allulose segmentation in China reflects divergent processing requirements between beverage-ready liquid formats and industrial-scale dry blends. Manufacturers configure enzymatic conversion and downstream purification around specific physical specifications that determine compatibility with existing production lines.
Product Type:
Customization intensity varies sharply across physical formats, from standardized syrup concentrations to client-specified particle distributions in powdered grades.
- Liquid Allulose:Aqueous solutions at 70-75% solids content integrate directly into ready-to-drink beverage formulations without reconstitution. Shanghai-based carbonated soft drink producers specify this format for zero-sugar line extensions requiring clean dissolution profiles.
- Powdered Allulose:Spray-dried crystalline material with controlled particle size distribution matches existing dry-blend infrastructure in Shandong province baking operations. Food manufacturers prefer this format for handling compatibility with legacy metering equipment.
- Granulated Allulose:Agglomerated crystals with enhanced flow properties suit table-top packaging applications.
- Syrup Allulose:High-viscosity concentrate for industrial confectionery processing.
Leading the category by volume: Powdered Allulose. Growing fastest: Liquid Allulose.
Application:
End-use concentration determines purity grade requirements and certification burden across manufacturing verticals.
- Beverages:Carbonated drinks, ready-to-drink teas, and functional waters constitute the primary demand channel. NHC novel food ingredient registration requirements for beverage applications establish the baseline compliance threshold for all allulose suppliers entering China.
- Bakery:Maillard reaction compatibility and moisture retention properties drive reformulation in Shandong and Guangdong industrial baking clusters. GB standards for food additives specify maximum usage levels that constrain formulation flexibility.
- Dairy:Fermented milk and ice cream applications leverage allulose freezing point depression characteristics.
- Confectionery:Hard candy and chocolate segments in tier-2 cities remain underpenetrated relative to coastal beverage markets.
Dominant by procurement scale: Beverages. Steepest expansion trajectory: Confectionery.
End User:
Customer sophistication tiers separate qualified supplier program participants from spot-market purchasers.
- Food Manufacturers:Industrial-scale processors of baked goods, sauces, and prepared foods specify allulose in bulk tender contracts with enzymatic conversion specialists. Direct supplier relationships are displacing multi-tier distribution for sweetener procurement among large Chinese food manufacturers.
- Beverage Companies:Tier-1 carbonated and RTD tea brands establish dedicated production lines to maintain audit trail integrity for low-glycemic claims under SAMR enforcement protocols.
- Nutraceuticals:Encapsulation and tableting grades command premium positioning for pharmaceutical-adjacent applications.
- Personal Care:Emerging segment for humectant properties in topical formulations.
Highest volume concentration: Food Manufacturers. Premium margin capture: Nutraceuticals.
Distribution Channel:
Channel selection reflects order scale and technical service requirements rather than pure cost optimization.
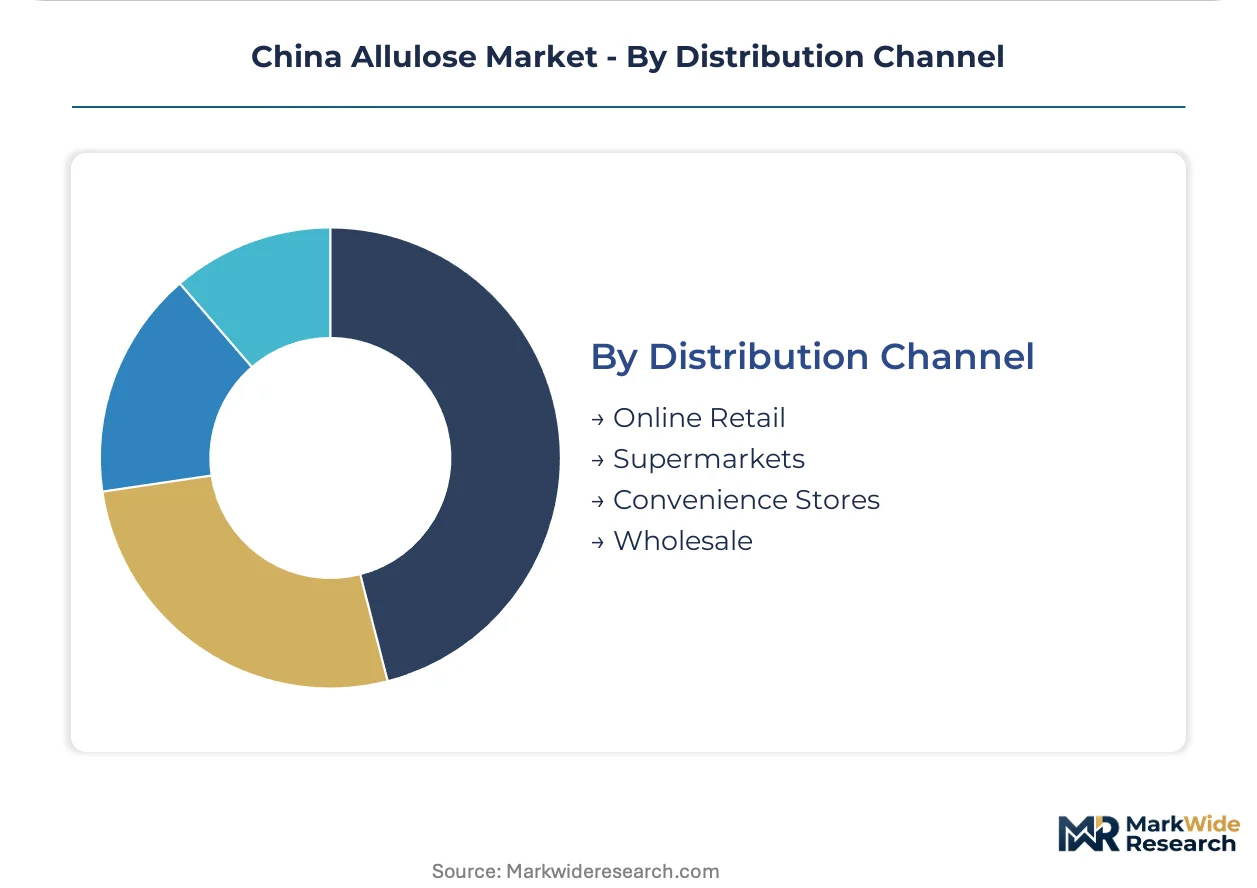
- Wholesale:Bulk sweetener procurement among coastal manufacturing clusters concentrates through qualified supplier programs bypassing traditional chemical distributors. Shandong fermentation specialists anchor supply contracts directly with major beverage brands.
- Online Retail:Table-top and small-format packaged allulose reaches health-conscious consumers through e-commerce platforms serving tier-1 and tier-2 cities.
- Supermarkets:Branded consumer packs in premium retail channels.
- Convenience Stores:Single-serve and impulse purchase formats in urban locations.
Largest transaction value: Wholesale. Channel gaining share fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in coastal manufacturing clusters where enzymatic conversion specialists anchor supply contracts with beverage brands. Provincial green energy quotas and NHC registration timelines reshape capacity expansion decisions across sub-regional markets.
Shandong Province
Beverage reformulation drives procurement from fermentation infrastructure concentrated around Jinan and Qingdao. GB standards for food additives establish purity baselines that filter qualified suppliers. Shandong Sanyuan Biotechnology leverages integrated enzymatic conversion capabilities to secure direct contracts with tier-1 carbonated drink manufacturers.
Yangtze River Delta
Shanghai-based ready-to-drink tea producers specify liquid allulose formats for zero-sugar line extensions. SAMR enforcement of low-glycemic labeling claims forces dedicated production line segregation. The delta's industrial biotechnology parks attract mid-scale producers retrofitting fructose syrup lines with continuous-flow epimerization modules.
Guangdong Province
Pearl River Delta confectionery manufacturers experiment with allulose in hard candy and chocolate segments. Provincial dual carbon goals pressure enzymatic facilities toward renewable power sourcing. Shenzhen nutraceutical encapsulation specialists command premium positioning for tableting grades.
Beijing-Tianjin-Hebei
Functional beverage startups in the capital region drive spot-market demand for small-batch liquid formats. NHC novel food ingredient registration documentation intensity extends cash conversion cycles for new entrants. Tianjin port infrastructure facilitates import of immobilized D-tagatose 3-epimerase from Japanese specialty enzyme houses.
Sichuan-Chongqing
Western China dairy processors leverage allulose freezing point depression characteristics in ice cream applications. Agricultural commodity price volatility in corn starch feedstock compresses margins for non-integrated producers. Chengdu-based distributors serve tier-2 city bakery chains through qualified supplier programs bypassing traditional chemical channels.
China Allulose Market Competitive Landscape
Capacity expansion dominates the current landscape as enzymatic conversion specialists retrofit existing fermentation infrastructure. The vendor base organizes around three tiers: integrated majors with backward starch control, mid-scale continuous-flow adopters, and spot-market batch operators. Strategic archetypes include coastal supply contract anchors, provincial green energy first-movers, and nutraceutical grade premium positioners. Competitive moves concentrate on NHC registration queue positioning and renewable power allocation securing.
Among Japanese and Korean enzyme technology licensors, Matsutani Chemical Industry occupies a position exemplifying proprietary immobilized reactor expertise. Shandong Sanyuan Biotechnology and Baolingbao represent the integrated domestic tier, with the former anchoring coastal beverage supply contracts and the latter exemplifying backward corn starch integration. These three entities illustrate how geographic concentration and feedstock control separate qualified suppliers from spot-market participants.
| Leading Market Players |
|---|
| Matsutani Chemical Industry |
| Shandong Sanyuan Biotechnology |
| Baolingbao |
| Ingredion Incorporated |
| Tate & Lyle |
| Sanyuan Biotech |
| Shandong Fuyang Bio-tech |
| Archer Daniels Midland Company |
| Dongxiao Biotech |
| Others |
Pricing and Supply Chain Analysis
Corn starch futures volatility on the Dalian Commodity Exchange cascades through enzymatic conversion economics, compressing margins for non-integrated producers while concentrating pricing power among Shandong-based majors with captive starch processing. NHC novel food ingredient registration timelines further stratify procurement tiers, as qualified suppliers command premium positioning over spot-market batch operators awaiting regulatory clearance.
Pricing Analysis
Volume-heavy beverage contracts trade at thin margins against nutraceutical encapsulation grades capturing substantial premiums. Pricing stratifies across pharmaceutical-adjacent certification tiers, volume scale thresholds, and geographic delivery zones from coastal clusters to inland processors. Cost compression in standard-grade liquid formats is intensifying because Japanese enzyme licensors maintain immobilized D-tagatose 3-epimerase supply control. Tier-2 city bakery chains exhibit highest price sensitivity, while Shanghai-based carbonated drink manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Domestic-content mandates under China's dual carbon goals and provincial green energy quotas are reshaping sourcing patterns, pressuring facilities toward renewable power procurement to maintain qualified supplier status. Manufacturing concentrates in China, Japan, and South Korea, with enzymatic conversion expertise anchored in Shandong fermentation clusters and immobilized reactor technology controlled by Japanese specialty houses. The chain draws from corn starch feedstock, immobilized enzyme inputs, and membrane filtration systems. Single-source vulnerability runs through D-tagatose 3-epimerase licensors in Japan and Korea. Distribution runs through direct supplier relationships with tier-1 beverage brands bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous enzymatic conversion systems are displacing legacy batch fermentation architectures, compressing unit economics and redrawing supplier qualification criteria across Chinese beverage channels.
For Market Incumbents: Cement coastal supply contract positions by retrofitting existing fructose syrup infrastructure with continuous-flow epimerization modules before NHC registration queue acceleration admits additional competitors. Anchor procurement leverage through backward integration into corn starch processing to neutralize agricultural commodity volatility threatening margin stability. Prioritize provincial wind and solar allocation securing under dual carbon goals to defend qualified supplier status against green energy compliance challengers. For New Entrants and Emerging Players: Begin with tier-2 city confectionery applications in hard candy and chocolate segments where allulose penetration lags coastal beverage saturation. Target Sichuan-Chongqing dairy processors seeking freezing point depression alternatives for ice cream formulations. Pursue white-label enzymatic conversion partnerships with Shandong fermentation specialists lacking downstream customer access rather than greenfield facility investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale continuous-flow adopters in Shandong province with NHC registration dossiers already submitted but awaiting toxicology study completion. Long-term viability hinges on enzymatic conversion technology maturation compressing capital intensity requirements across the projection horizon. Monitor provincial green energy quota allocation announcements as inflection indicator for facility operating cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Reactor Retrofit | Shandong fermentation specialists achieve parity yields with integrated majors through fructose line conversion. |
| NHC Registration Queue Positioning | Novel food ingredient dossier submission timing determines market access windows relative to competitor clearance. |
| Backward Starch Integration | Corn processing control neutralizes Dalian Commodity Exchange volatility compressing non-integrated margins. |
| Provincial Renewable Power Allocation | Dual carbon goals compliance secures qualified supplier status for SAMR green energy enforcement protocols. |
| Nutraceutical Grade Certification | Pharmaceutical-adjacent tableting specifications command premium positioning in encapsulation segments. |
Research Methodology
Regulatory filings with SAMR and NHC, customs trade databases tracking enzymatic conversion equipment imports, and GB standards documentation formed the secondary backbone for this analysis. Primary interviews with fermentation plant managers, beverage procurement leads at tier-1 carbonated brands, technical R&D directors at Shandong biotech clusters, and distribution channel partners in coastal manufacturing zones combined with secondary validation through bottom-up and top-down triangulation approaches.
Bottom-up modeling of enzymatic conversion capacity utilization, NHC registration queue velocity, and provincial green energy quota allocation across the analysis window converged with top-down sweetener substitution elasticity estimates. Segmentation dimensions included physical format specifications, end-use application verticals, customer sophistication tiers, and regional production cluster development. CAGRs derived from capacity expansion announcements, beverage reformulation pipeline disclosures, and corn starch feedstock price trajectory assumptions.
Underlying measurement precision varies by segment; beverage procurement volumes carry tighter precision than emerging nutraceutical encapsulation grades where supplier qualification remains fluid. Forecasts reflect assumptions around NHC approval pathway acceleration, enzyme technology licensing availability, and agricultural commodity price stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Coconut Sugar Market
Sweeteners
Asia Pacific Food Sweetener Market
Sweeteners
Spain Food Sweetener Market
Sweeteners
Sodium Saccharin Market
Sweeteners
United States Xylitol Market
Sweeteners
Asia-Pacific Sugar Substitute Market
Sweeteners
Palm Sugar Market
Sweeteners
Fructose Market
Sweeteners
Africa and Middle East Sugarcane Syrup Market
Sweeteners
Maltodextrin Market
Sweeteners
Corn Syrup Market
Sweeteners
Methyl Glucose Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
Cassava Syrup Market
Sweeteners
Sugar Beet Juice Extract Market
Sweeteners
Maltitol Market