
 Brown Rice Syrup Market | 2026-2036
Brown Rice Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Brown Rice Syrup Market Analytics
EU Organic Regulation 2018/848 is rebalancing the cost-of-entry calculus for brown rice syrup suppliers seeking European market access. California Natural Products leverages its West Coast processing infrastructure to sustain organic certification across multiple export jurisdictions. Gulshan Polyols Ltd. anchors its position through backward integration into Indian rice milling networks. Archer-Daniels-Midland Company competes via its established distribution density in North American food ingredient channels.
Brown rice syrup is a glucose-dominant liquid sweetener manufactured through enzymatic hydrolysis of brown rice starch, typically yielding dextrose equivalents between 42 and 70 depending on hydrolysis depth. Food manufacturers deploy it as a maltose or high-fructose corn syrup replacement in clean-label formulations where caramelization and moisture retention prove functionally critical. The organic product type segment commands premium positioning in European and North American retail, while conventional grades dominate bulk industrial procurement for beverage and baked goods applications. Online retail channels are capturing the fastest growth velocity as direct-to-consumer health brands bypass traditional wholesale intermediaries.
The FDA governs added-sugar disclosure thresholds on Nutrition Facts panels, directly incentivizing formulators to scrutinize brown rice syrup's glycemic contribution in finished goods. EFSA and USDA Organic standards impose divergent pesticide residue and processing aid restrictions that fragment certification compliance costs across export destinations. Stakeholders must monitor evolving definition disputes around "no added sugar" claims in multiple jurisdictions where brown rice syrup's natural-origin status remains contested by consumer advocacy coalitions.
Market Dynamics
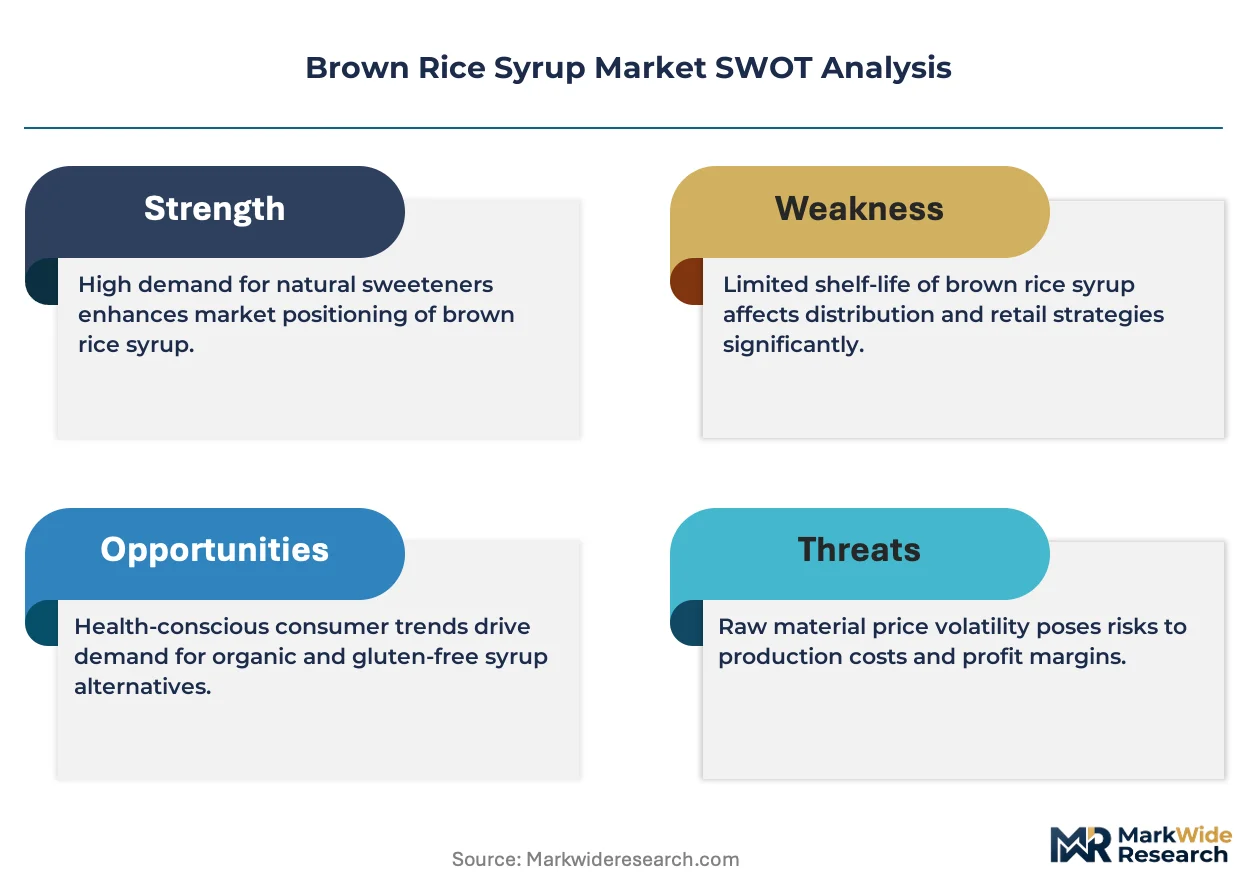
Clean-label reformulation mandates from major retailers are compressing formulation cycles for brown rice syrup suppliers, forcing rapid certification upgrades and supply base consolidation.
Growth Catalysts
- EU Organic Regulation 2018/848:Mandatory residue testing and traceability requirements are locking in supplier relationships with certified organic rice processors, creating switching costs that protect incumbent positions.
- Beverage clean-labeling:Hard seltzer and functional drink manufacturers are substituting brown rice syrup for maltose to secure "no artificial sweeteners" shelf positioning in natural food channels.
- Enzymatic hydrolysis advancement:Novel glucoamylase blends are enabling 70+ dextrose equivalent outputs from brown rice starch, matching high-fructose corn syrup functionality without the fructose load.
Market Restraints
- Input cost volatility:Organic brown rice premiums fluctuate with Indian monsoon patterns and Mississippi River barge rates, compressing processor margins unpredictably.
- Supply concentration risk:Over 60% of organic rice milling capacity clusters in Punjab and Haryana, exposing buyers to single-region climate and policy shocks.
- Glycemic indexing limitations:Brown rice syrup's high glucose content triggers mandatory added-sugar disclosure under FDA Nutrition Facts rules, restricting "low glycemic" marketing claims.
Strategic Opportunities
- Korean functional food expansion:K-food export growth and MFDS health claim pathways are opening formulation partnerships for blood-sugar-management positioned products.
- Direct-to-consumer channel innovation:Subscription-based clean-label baking kits are bypassing wholesale intermediaries, capturing full margin from health-conscious households.
- USDA Organic and Non-GMO Project co-certification:Stacked verification protocols command 35-50% price premiums in US natural retail, justifying dedicated production lines.
Industry Challenges
- Multi-jurisdiction certification timelines:EU 2018/848, USDA Organic, and JAS organic audits require 14-18 month synchronization, delaying new market entry.
- Legacy ERP integration friction:Lot-level traceability systems for organic compliance often conflict with existing inventory management platforms, requiring middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brown Rice Syrup Market |
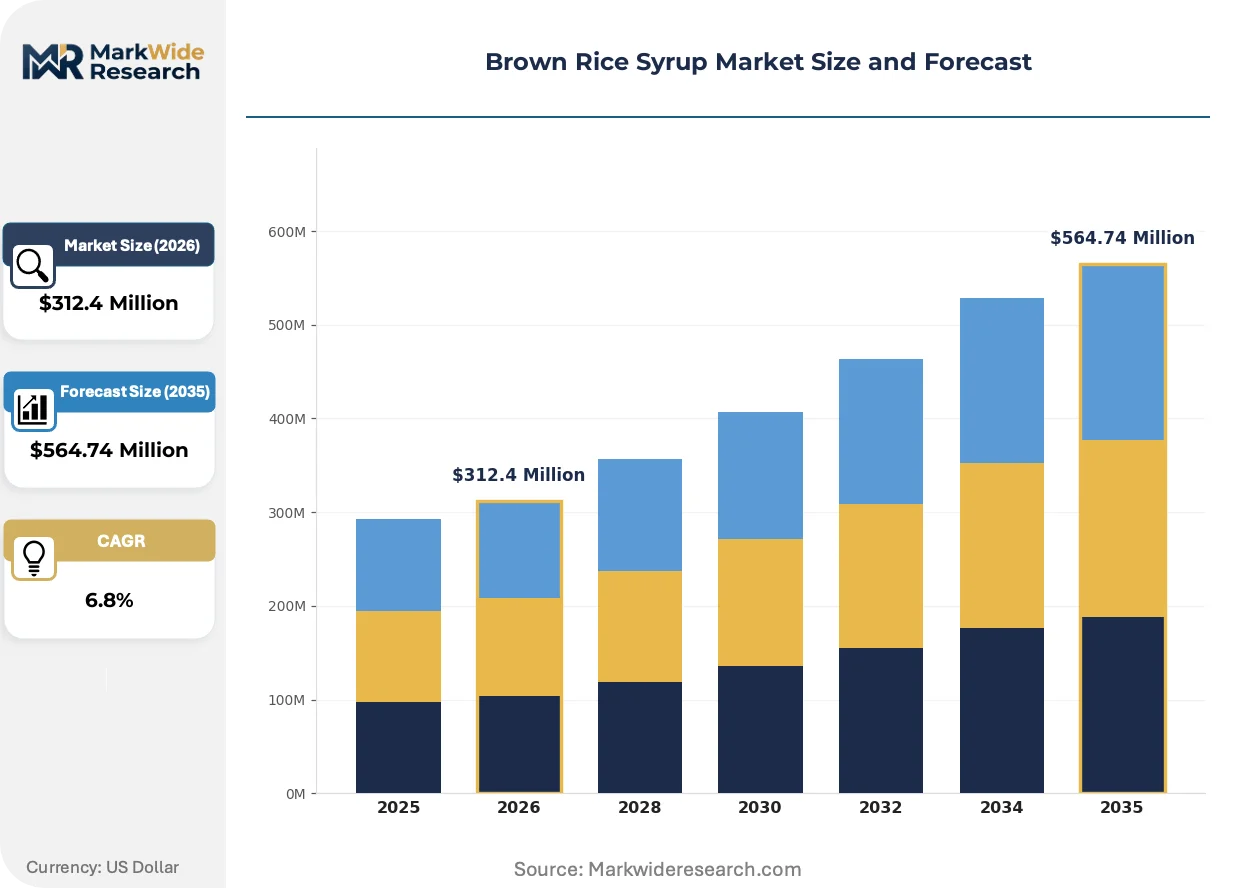
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Raw, Instant Application: Beverages, Baked Goods, Snacks, Confectionery Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale Packaging Type: Bottles, Tubs, Pouches, Bulk |
| Companies Covered | California Natural Products, Gulshan Polyols Ltd., Archer-Daniels-Midland Company, Matco Foods Limited, Austrade Inc., Cargill, Wuhu Deli Foods Co., Ltd, Ciranda, Inc., Shafi Gluco Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brown Rice Syrup Market Evolving Landscape
Enzyme engineering and regulatory disclosure requirements are simultaneously elevating product performance standards and compressing acceptable ingredient lists across formulated foods.
Low-temperature vacuum evaporation is overtaking conventional open-kettle concentration for premium organic grades. Specialty chocolate and infant nutrition manufacturers specify this process to preserve Maillard reaction precursors and color consistency. The technology is compressing acceptable supplier pools to those with capital equipment depth.
REACH registration requirements for processing aids used in starch hydrolysis are tightening documentation burdens on European imports. Suppliers must now disclose full enzymatic preparation compositions to ECHA, raising compliance costs for smaller Asian processors. German and Dutch organic food manufacturers are responding by consolidating procurement with vertically integrated partners possessing in-house regulatory affairs capacity.
Bulk ingredient procurement through cooperative purchasing platforms is fragmentizing traditional distributor relationships. Mid-sized US natural food brands now pool orders through member-owned buying groups, extracting volume pricing without minimum order commitments. This pattern is most visible in California and Pacific Northwest clusters where clean-label brand density concentrates.
Brown Rice Syrup Market Segmentation
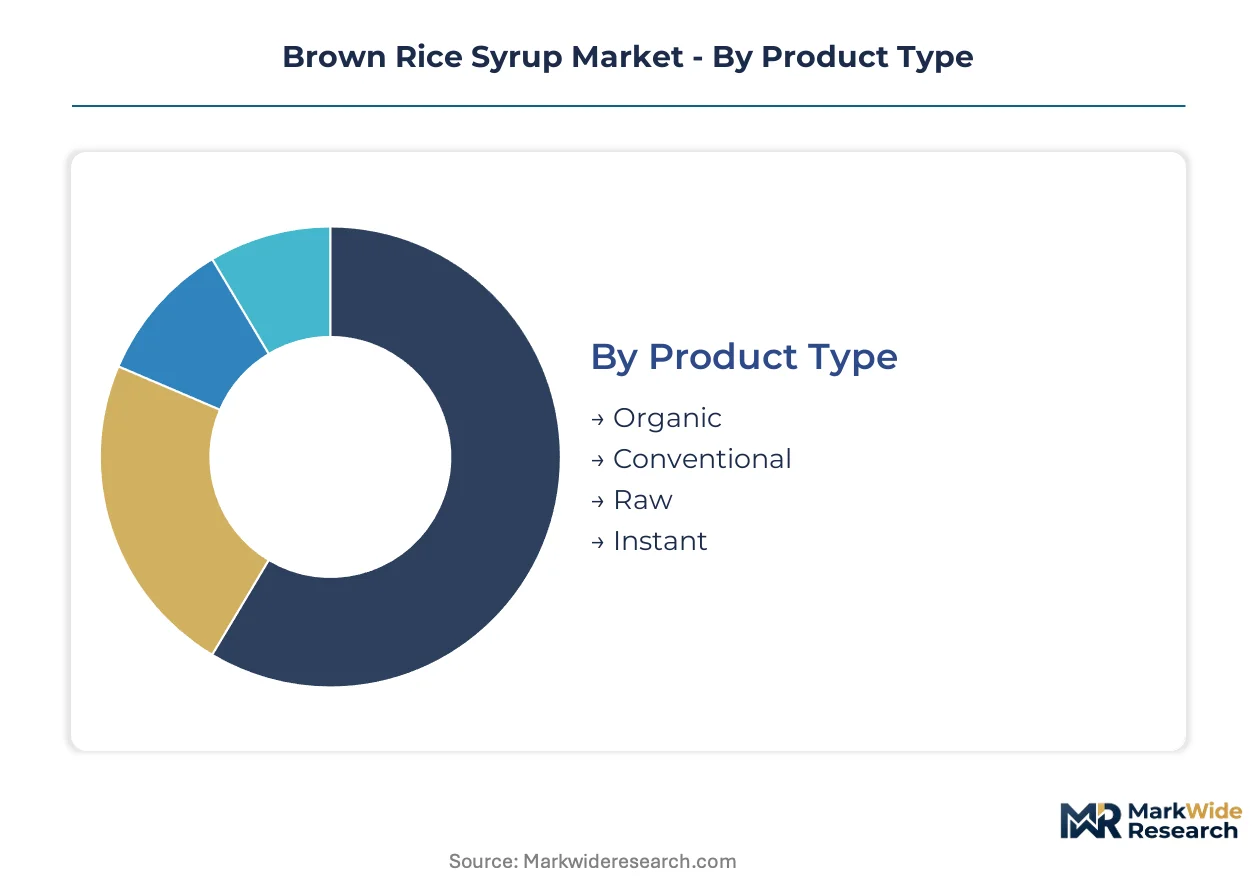
Brown rice syrup procurement patterns diverge sharply across certification tiers and channel structures. Manufacturers configure production lines around these divisions because organic certification and conventional processing require incompatible equipment and audit protocols.
Product Type:
Organic brown rice syrup demands substantially higher capital commitment than conventional grades due to dual-certification equipment, segregated storage infrastructure, and residue-testing laboratories.
- Organic:Enzymatic hydrolysis proceeds under USDA Organic or EU 2018/848 protocols with prohibited processing aid restrictions. Clean-label beverage formulators in Germany and the Netherlands specify this grade for infant nutrition and premium chocolate applications where Maillard reaction control proves critical.
- Conventional:Standard enzymatic processing without organic certification constraints allows broader glucoamylase selection and higher throughput rates. Industrial bakeries and mass-market beverage producers in the United States source this grade for cost-sensitive formulations where caramelization performance outweighs label claims.
- Raw:Minimal heat processing preserves enzyme activity and native protein structures. Specialty health food manufacturers in California specify this grade for raw food diet positioning.
- Instant:Spray-dried or agglomerated formats dissolve rapidly in cold liquids. Functional drink powder brands favor this format for single-serve convenience.
Conventional syrup absorbs the bulk of installed capacity; organic is expanding most quickly.
Application:
End-use specifications determine dextrose equivalent targets, with beverage formulators demanding the tightest viscosity and fermentability tolerances.
- Beverages:Hard seltzer and functional drink manufacturers specify 60-70 dextrose equivalent syrup to replace maltose while securing "no artificial sweeteners" shelf positioning in natural food channels.
- Baked Goods:Moisture retention and crust browning requirements drive 42-50 dextrose equivalent selection. Artisan bread producers in France and industrial cookie manufacturers in the United States both source brown rice syrup for clean-label reformulations.
- Snacks:Binding and sheen properties in granola and energy bar formulations favor mid-range dextrose equivalents. Direct-to-consumer subscription brands are bypassing wholesale intermediaries for this application.
- Confectionery:Crystallization control and humectancy requirements in premium caramels and soft candies demand precise reducing sugar ratios. Belgian and Swiss chocolate houses specify low-temperature vacuum-evaporated grades.
Beverage applications command the steepest expansion trajectory; baked goods maintain the largest volume base.
Distribution Channel:
Channel selection directly determines margin capture, with direct-to-consumer formats yielding 35-50% premiums over bulk wholesale.
- Online Retail:Subscription-based clean-label baking kits and health food platforms are capturing full margin from health-conscious households. California and Pacific Northwest brand clusters dominate this channel.
- Supermarkets:Mass-market penetration requires slotting fee negotiations and retailer-specific clean-label mandates. Conventional grades predominate here.
- Health Food Stores:Independent natural retailers in Germany and the Netherlands stock organic and raw grades exclusively. Co-certification with Non-GMO Project verification commands price premiums.
- Wholesale:Bulk procurement through cooperative purchasing platforms is fragmentizing traditional distributor relationships. Mid-sized US natural food brands pool orders through member-owned buying groups.
Wholesale channels still move the largest tonnage; online retail is climbing the fastest.
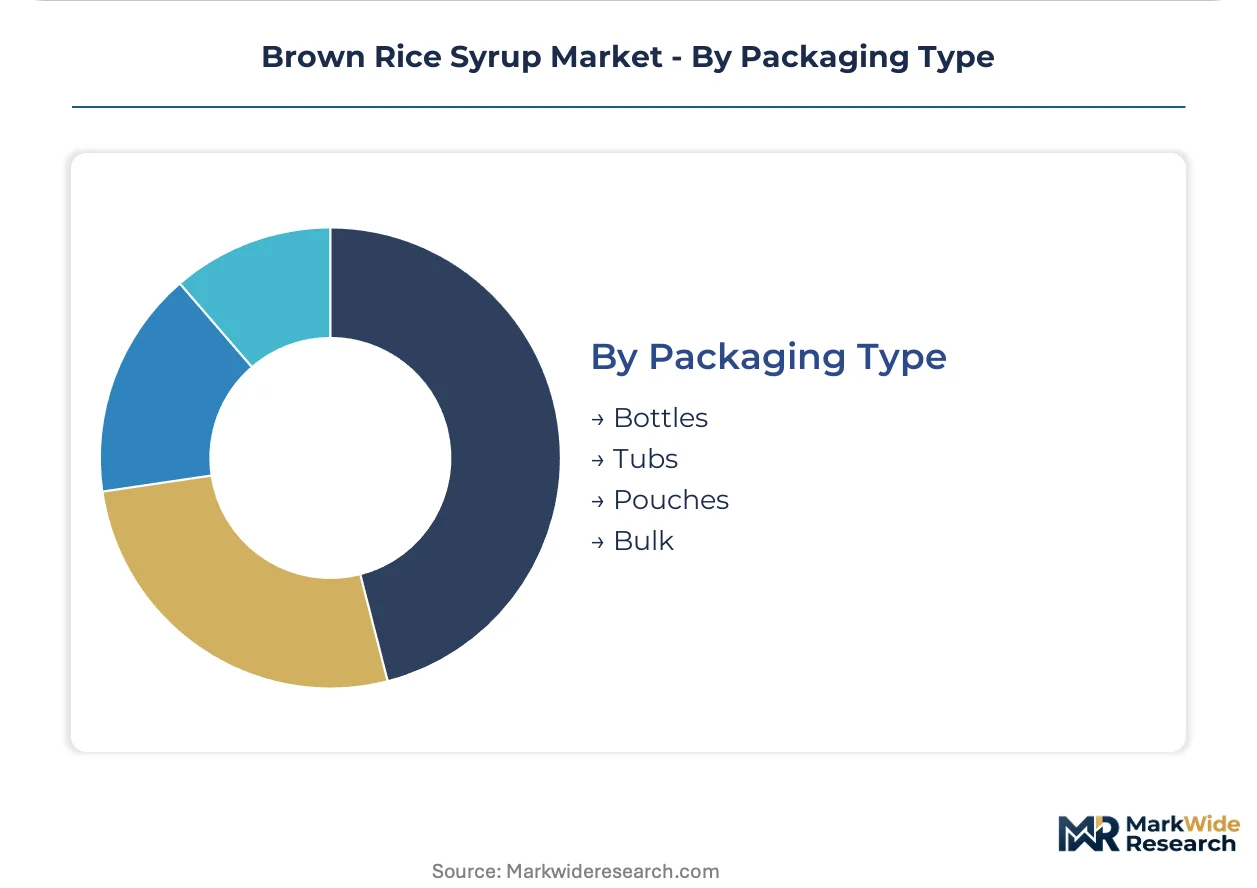
Packaging Type:
Packaging configuration reflects downstream automation requirements and shelf-life demands across divergent end-use environments.
- Bottles:Standard retail formats for liquid syrup with 12-18 month stability. Pour-spout designs target home bakers and small commercial kitchens.
- Tubs:Wide-mouth containers suit high-viscosity grades and foodservice scooping operations. Institutional bakeries favor this format.
- Pouches:Flexible formats reduce shipping cube and suit single-serve or sample applications. Direct-to-consumer brands specify custom-printed pouches.
- Bulk:Tote tanks and drum formats for industrial users with dedicated pumping infrastructure. Beverage and baked goods manufacturers with continuous production lines source exclusively here.
Bulk packaging dominates industrial procurement; pouches are gaining share fastest in direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clean-label beverage formulators in the United States and organic chocolate manufacturers in Germany absorb the largest share of premium brown rice syrup procurement. Indian rice milling clusters supply the upstream starch base for both markets. Regulatory divergence across FDA, EFSA, and MFDS jurisdictions fragments certification requirements.
United States
Hard seltzer manufacturers and functional drink brands in California specify 60-70 dextrose equivalent syrup to replace maltose while securing shelf positioning in natural food channels. FDA added-sugar disclosure rules on Nutrition Facts panels directly incentivize formulators to scrutinize glycemic contributions. Sacramento Valley processing infrastructure sustains organic certification across multiple export jurisdictions.
Germany
Premium chocolate houses and infant nutrition manufacturers in Cologne and Hamburg specify low-temperature vacuum-evaporated organic grades for Maillard reaction control. EFSA pesticide residue standards and EU Organic Regulation 2018/848 impose traceability requirements that lock in supplier relationships with certified processors. North Rhine-Westphalia consolidates procurement with vertically integrated partners possessing regulatory affairs capacity.
India
Organic brown rice premiums fluctuate with Punjab and Haryana monsoon patterns, compressing processor margins unpredictably. FSSAI standards and export-oriented organic certification requirements govern enzymatic hydrolysis protocols. Over 60% of organic rice milling capacity clusters in Punjab and Haryana, exposing buyers to single-region climate and policy shocks.
South Korea
K-food export growth and MFDS health claim pathways open formulation partnerships for blood-sugar-management positioned products. Seoul-based functional food brands seek clean-label sweeteners for domestic and export markets. Gyeonggi-do processing facilities bridge traditional fermentation expertise with modern enzymatic hydrolysis.
Netherlands
Rotterdam and Amsterdam natural retailers stock organic and raw grades exclusively, with Non-GMO Project co-certification commanding 35-50% price premiums. ECHA REACH registration requirements for processing aids tighten documentation burdens on Asian imports. Dutch organic food manufacturers consolidate procurement with partners possessing in-house regulatory capacity.
Brown Rice Syrup Market Competitive Landscape
United States producers anchor one tier; Indian specialists hold upstream starch supply; European traders intermediate certification-heavy flows. The vendor base separates into three strategic archetypes: West Coast processors with multi-jurisdiction organic certification, South Asian millers with backward integration into rice networks, and global traders with distribution density in food ingredient channels. Competitive moves concentrate on capacity expansion in low-temperature vacuum evaporation and strategic partnerships for direct-to-consumer channel access.
Among United States-based processors, California Natural Products exemplifies the certified-organic archetype with West Coast infrastructure. Gulshan Polyols Ltd. occupies a position within the Indian upstream tier, representing backward integration into rice milling networks. Archer-Daniels-Midland Company anchors the global trading segment, sitting within established North American distribution channels.
| Leading Market Players |
|---|
| California Natural Products |
| Gulshan Polyols Ltd. |
| Archer-Daniels-Midland Company |
| Matco Foods Limited |
| Austrade Inc. |
| Cargill |
| Wuhu Deli Foods Co., Ltd |
| Ciranda, Inc. |
| Shafi Gluco Chem |
| Others |
Value Network & Pricing Analysis
Backward integration into Indian rice milling networks anchors both supply security and margin protection for brown rice syrup processors. Gulshan Polyols Ltd. and similar upstream-integrated players capture organic brown rice premiums before monsoon-driven volatility transmits to spot markets, while non-integrated buyers absorb cost compression from Punjab and Haryana supply concentration.
Pricing Analysis
Volume-driven conventional grades trade at thin margins while organic certification commands substantial premiums. Three-tier pricing structure across organic, conventional, and raw grades separates procurement by certification burden and processing intensity. Pricing pressure stems from Mississippi River barge rate volatility and Indian monsoon patterns compressing processor margins. Industrial bakeries exhibit highest price sensitivity; infant nutrition manufacturers accept premium positioning for low-temperature vacuum-evaporated organic grades.
Supply Chain Analysis
Organic brown rice supply rests on Punjab and Haryana milling clusters, with secondary concentration in Sacramento Valley processing infrastructure. Enzymatic hydrolysis inputs include glucoamylase preparations, brown rice starch, and processing aids subject to ECHA REACH registration. Single-region climate exposure in northwest India creates supply vulnerability to monsoon failure and policy shocks. Distribution runs through cooperative purchasing platforms fragmenting traditional wholesale intermediaries, with direct-to-consumer channels capturing fastest growth velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brown rice syrup procurement is consolidating around certified processors with multi-jurisdiction compliance capacity, as EU Organic Regulation 2018/848 and FDA disclosure rules force smaller Asian mills out of premium supply tiers.
For Market Incumbents: Deploy low-temperature vacuum evaporation capacity additions in California and North Rhine-Westphalia to defend organic grade positioning against conventional-grade price erosion. Lock in 14-18 month certification timelines with EU 2018/848-accredited rice processors before audit queue lengthening excludes late entrants. Consolidate procurement relationships with vertically integrated Indian millers possessing FSSAI and USDA Organic dual certification. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer white-space access with 35-50% margin premiums over wholesale. Target raw and instant format segments where established processors underinvest in spray-drying and agglomeration equipment. Enter through Korean functional food partnerships leveraging MFDS health claim pathways for blood-sugar-management positioning. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by global ingredient traders seeking West Coast organic certification infrastructure. Five-to-ten year viability favors processors with captive rice supply and in-house regulatory affairs capacity. Watch EU 2018/848 enforcement intensity as inflection signal for certification cost barriers accelerating supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Temperature Vacuum Evaporation Investment | Belgian chocolate houses and German infant nutrition manufacturers specify this process for Maillard reaction control. |
| USDA Organic and Non-GMO Project Co-Certification | Stacked verification protocols command premium positioning in California and Pacific Northwest natural retail channels. |
| Direct-to-Consumer Channel Launch | Subscription-based clean-label baking kits bypass wholesale intermediaries and capture full household margin. |
| Backward Integration into Rice Milling | Captive supply from Punjab and Haryana clusters insulates processors from monsoon-driven input cost volatility. |
| Enzymatic Hydrolysis Advancement Partnership | Novel glucoamylase blends enabling 70+ dextrose equivalent outputs match high-fructose corn syrup functionality. |
Research Methodology
Independent corroboration across plant managers at enzymatic processing facilities, procurement leads at beverage and baked goods manufacturers, distribution channel partners, and technical R&D directors at enzyme suppliers underwrites the qualitative findings. Secondary validation draws from FDA filings on added-sugar disclosure rules, EFSA pesticide residue standards, EU Organic Regulation 2018/848 documentation, and USDA Organic certification databases. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across the analysis window.
Historical reference periods anchor the projection horizon to pre-pandemic baseline demand and post-regulatory-shift procurement patterns. The analytical framework segments by certification tier, dextrose equivalent range, end-use application, and regional regulatory cluster. CAGRs derive from installed capacity utilization trends and substitution elasticity estimates for maltose and high-fructose corn syrup displacement. Forecast inputs include organic rice acreage expansion rates and clean-label beverage formulation cycle compression.
The model holds under stable EU-US organic equivalence recognition and Indian monsoon patterns within historical variance; deviation in ECHA REACH enforcement intensity or Punjab water policy would shift supply cost assumptions. Forecasts reflect documented assumptions on certification timeline standardization and enzyme engineering advancement. A small set of named triggers—EU 2018/848 audit backlog, Mississippi River logistics disruption, and FDA "no added sugar" claim litigation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Asia-Pacific Cane Sugar Market
Sweeteners
Erythritol Market
Sweeteners
Floral Nectar Market
Sweeteners
Allulose Powder Market
Sweeteners
Invert Sugar Market
Sweeteners
Isomaltulose Market
Sweeteners
China Allulose Market
Sweeteners
Sanding Sugar Market
Sweeteners
Sugar Free Lifesavers Market
Sweeteners
Coconut Sugar Market
Sweeteners
Vanilla Sugar Market
Sweeteners
Glucose, Dextrose, and Maltodextrin Market
Sweeteners
North America Plant-Derived and Synthetic Sugar Market
Sweeteners
Asia-Pacific Plant-Derived and Synthetic Sugar Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
North America Low-Calorie Sweeteners Market