
 United States Xylitol Market | 2026-2036
United States Xylitol Market Size, Share, and Industry Trends Forecast 2026-2036
United States Xylitol Market Intelligence
Subscription-based formulation support is hardening as a core revenue layer in the United States xylitol market, with ingredient suppliers bundling technical consulting and recipe optimization into multi-year contracts. Cargill leverages its corn wet milling infrastructure to secure captive xylose supply across the Upper Midwest. DuPont de Nemours sustains biotechnology leadership through proprietary fermentation strain development. Ingredion anchors industrial-scale production with integrated distribution to food manufacturers nationwide.
Xylitol is a five-carbon sugar alcohol (C5H12O5) manufactured through catalytic hydrogenation of xylose derived from hardwood or agricultural biomass, functioning as a non-cariogenic sweetener with approximately 2.4 kilocalories per gram and a glycemic index of seven. Powder formulations dominate pharmaceutical and dental care compounding due to compressibility and flow properties, while liquid xylitol gains traction in beverage applications where rapid dissolution matters. The food and beverage application segment commands the deepest margin pools, though nutraceuticals represent the fastest-growing demand vector as functional positioning intensifies.
FDA GRAS determinations and USDA organic certification requirements shape product standards and channel access for domestic producers, while FERC-regulated energy costs influence fermentation economics at Midwest processing facilities. OSHA process safety mandates and EPA wastewater discharge rules add compliance layers that favor capital-intensive operators with established environmental management systems. Stakeholders must monitor pending FDA guidance on sugar alcohol labeling declarations and assess whether state-level clean energy incentives will reshape facility location decisions.
Market Dynamics
Corn wet milling concentration across Iowa, Minnesota, and Nebraska creates captive xylose supply chains that lock in regional production economics and disadvantage coastal entrants lacking feedstock proximity.
Growth Catalysts
- FDA GRAS Self-Affirmation Pathway:Food manufacturers accelerate xylitol incorporation without pre-market notification delays, compressing formulation-to-launch cycles for reduced-sugar product lines.
- Hardwood Biomass Hydrolysis:Southern pulp mills retrofit spent liquor processing to extract xylose, diversifying feedstock beyond corn-derived sources.
- Dental Caries Prevention Positioning:Pediatric oral care brands reformulate around xylitol's non-cariogenic properties, pulling volume through pharmacy and professional channels.
Market Restraints
- Corn Price Volatility:Drought cycles across the Corn Belt spike xylose input costs unpredictably, squeezing fermentation margins at Midwest facilities.
- Supply Concentration Risk:Three biotech manufacturing clusters control over 80% of domestic xylose hydrogenation capacity, creating single-point failure exposure.
- Technological Substitution:Allulose and erythritol achieve comparable sweetness profiles with lower cooling effects, eroding xylitol's formulation advantage in beverages.
Strategic Opportunities
- USDA BioPreferred Program:Federal procurement mandates for biobased ingredients open institutional foodservice channels previously closed to synthetic sweeteners.
- Pet Oral Care Applications:Veterinary dental chews represent an untapped application vertical with premium pricing tolerance and minimal regulatory friction.
- Continuous Fermentation Systems:Integration of cell immobilization with real-time analytics reduces batch variability and utility consumption.
Industry Challenges
- Fermentation Strain Engineering Talent:Shortage of metabolic pathway specialists delays proprietary strain development timelines.
- EPA NPDES Permit Renewal:Wastewater discharge compliance for high-BOD fermentation effluent requires multi-year capital deployment.
- Organic Certification Audit Burden:USDA National Organic Program traceability requirements extend certification cycles for biomass-sourced xylose.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Xylitol Market |
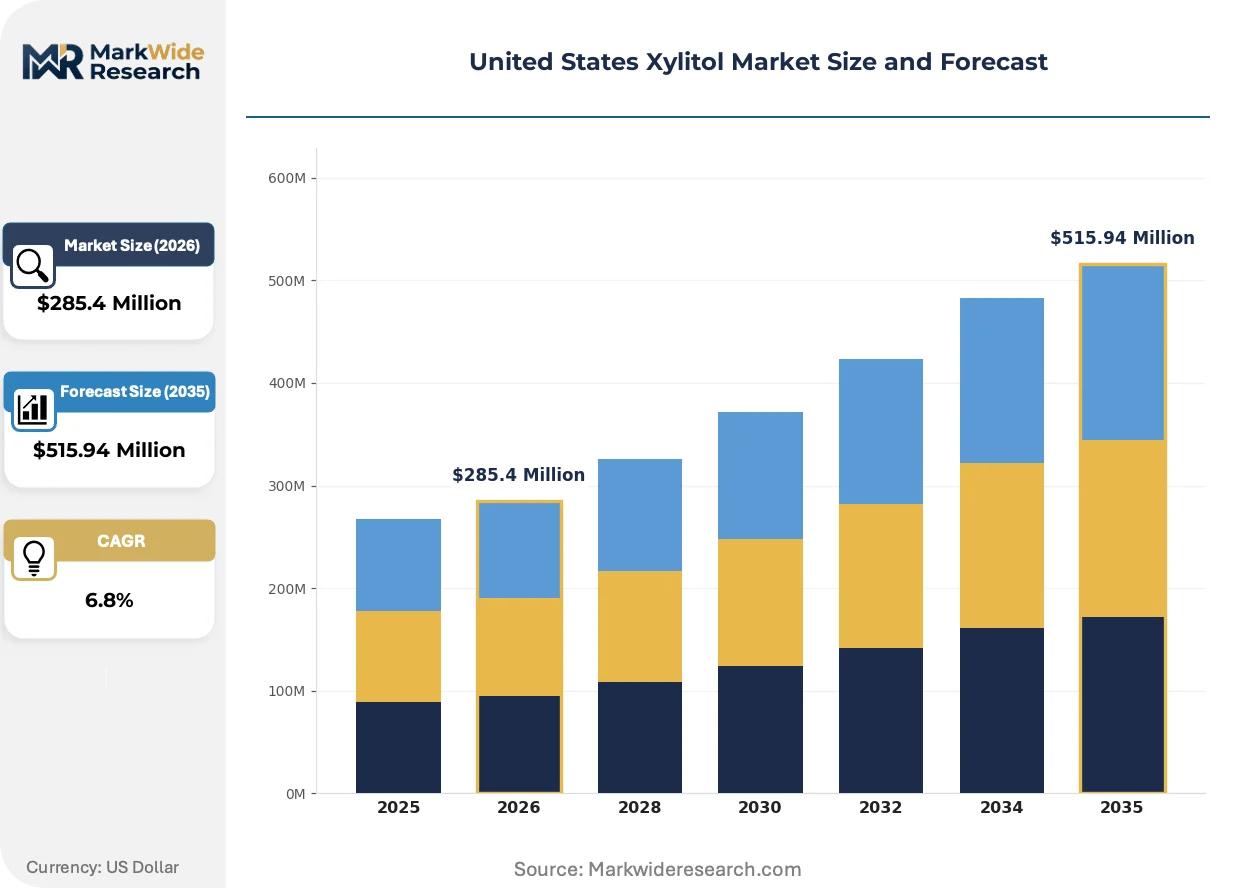
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Tablet, Liquid Application: Food & Beverage, Dental Care, Pharmaceuticals, Nutraceuticals End User: Consumers, Healthcare Providers, Food Manufacturers, Toothpaste Brands Distribution Channel: Online Retail, Supermarkets, Health Stores, Distributors |
| Companies Covered | Cargill, DuPont de Nemours, Ingredion, zuChem, Roquette Frères, Archer Daniels Midland Company, Dynamic Food Ingredients, Danisco, DFI Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Xylitol Market Strategic Shifts & Innovations
Bioprocess intensification and regulatory labeling evolution are compressing traditional manufacturing economics while opening premium positioning channels for verified-sustainability xylitol grades.
Continuous catalytic hydrogenation with fixed-bed reactor designs is decentralizing production scale requirements. Mid-size manufacturers in Wisconsin and Michigan adopt modular skid-mounted systems that slash capital thresholds from $50 million to $8 million per line. This technology is decentralizing geographic concentration by enabling distributed processing closer to regional biomass sources rather than centralized Corn Belt megafacilities.
Pending FDA guidance on sugar alcohol declaration formatting will mandate gram-per-serving quantification on front-of-pack labels. Reformulation teams at beverage and confectionery manufacturers preemptively reduce polyol loadings to avoid consumer perception penalties. The food and beverage segment faces the steepest compliance burden, with brands accelerating clean-label repositioning ahead of rule finalization.
Direct procurement contracts between food manufacturers and xylose suppliers are displacing distributor-mediated purchasing. Large bakery and beverage producers in California and Texas negotiate multi-year offtake agreements with guaranteed volume floors. This pattern concentrates most visibly in the Southwest, where logistics costs from Midwest production centers incentivize buyers to secure price certainty through contractual commitment rather than spot market exposure.
United States Xylitol Market Segmentation
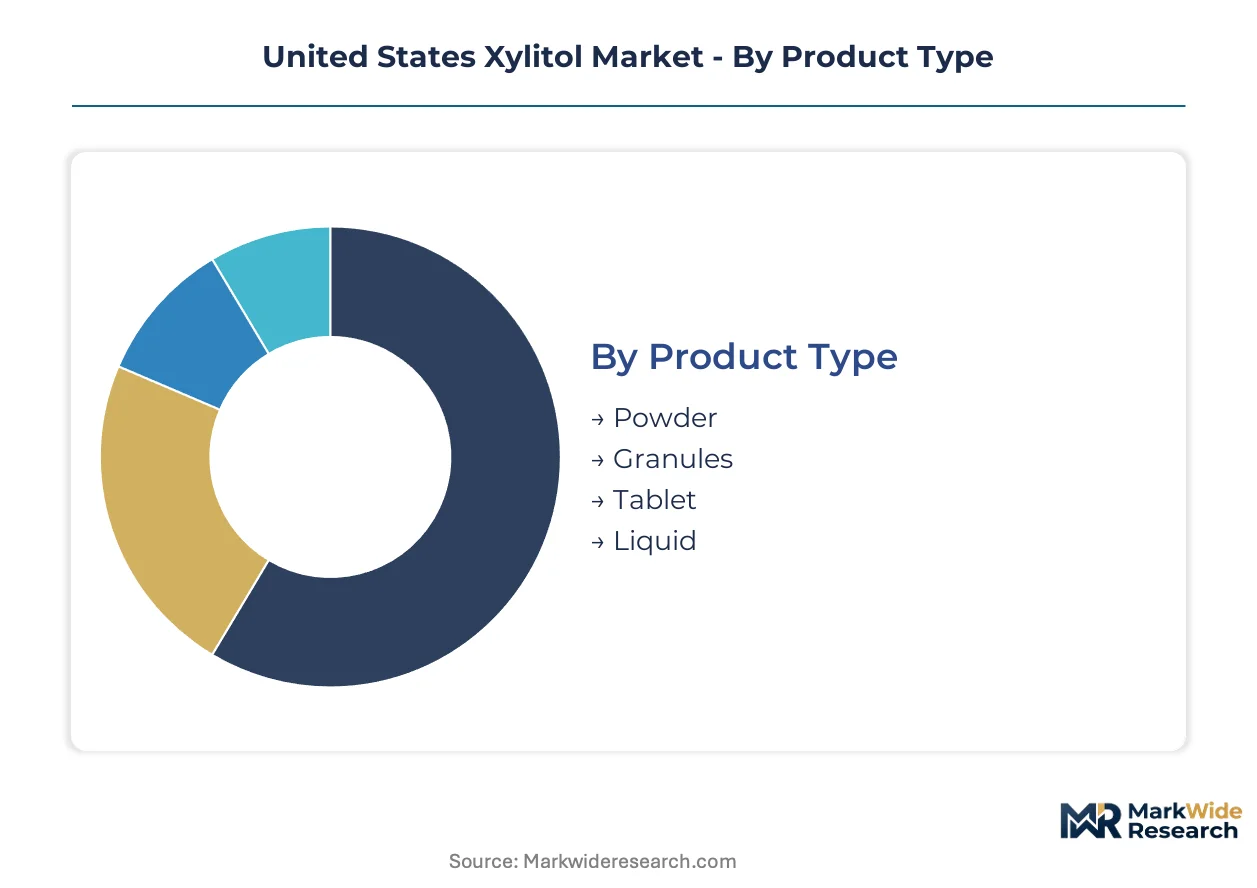
Xylitol's physical form and channel pathways dictate capital deployment, margin capture, and regulatory exposure across the United States value chain. Segmentation reveals where fermentation economics favor scale versus where formulation flexibility commands premium pricing.
Product Type:
Powder and liquid formats demand divergent capital intensity—spray-drying towers and bulk silos versus aseptic filling lines and cold-chain logistics.
- Powder:Micronized crystalline form with standardized mesh sizes between 80-200 microns enables direct compression in tablet manufacturing and dry blending in bakery applications. Dental care compounders in the Northeast concentrate procurement here due to compressibility requirements for chewable delivery systems, though hygroscopicity constraints necessitate climate-controlled warehousing.
- Liquid:Aqueous solutions at 70-75% concentration dissolve rapidly in beverage matrices without crystallization lag. California beverage manufacturers drive demand for tanker-truck delivery to avoid powder reconstitution steps, despite shorter shelf stability and higher freight costs per unit sweetness.
- Granules:Intermediate particle size for controlled-release confectionery applications requiring slower dissolution kinetics.
- Tablet:Pre-compressed unit doses for direct-to-consumer dental protocols and clinical caries prevention programs.
Powder absorbs the bulk of installed capacity; liquid is expanding most quickly.
Application:
Application segments stratify by regulatory burden and formulation complexity, with food manufacturing presenting the steepest compliance ladder.
- Food & Beverage:GRAS-affirmed sweetener replacement in reduced-sugar baked goods, chewing gums, and ready-to-drink formulations. Midwest contract manufacturers anchor volume here, leveraging proximity to corn wet milling feedstock clusters for cost-competitive xylose supply.
- Dental Care:Non-cariogenic positioning in pediatric toothpastes, mouth rinses, and professional varnishes. Pharmacy chains in Florida and Texas pull volume through clinical recommendation programs targeting early childhood caries prevention.
- Pharmaceuticals:Excipient-grade material for orodispersible tablets and pediatric liquid formulations requiring USP-NF certification.
- Nutraceuticals:Functional ingredient in blood glucose management supplements and gut microbiome modulation products.
Food & Beverage commands the deepest margin pools; nutraceuticals are gaining share fastest.
End User:
End user categories diverge by procurement sophistication, with institutional buyers extracting volume discounts unavailable to retail channels.
- Food Manufacturers:Industrial-scale buyers negotiating multi-year offtake agreements with xylose suppliers for price certainty. Bakery and beverage producers in California and Texas dominate contract structuring.
- Toothpaste Brands:Formulation-driven procurement emphasizing non-cariogenic clinical validation and pediatric safety positioning.
- Consumers:Direct retail purchasers through health stores and online channels, price-sensitive and brand-loyal.
- Healthcare Providers:Dental clinics and hospital systems prescribing xylitol protocols for high-caries-risk patient populations.
Food Manufacturers absorb the bulk of installed capacity; Healthcare Providers are expanding most quickly.
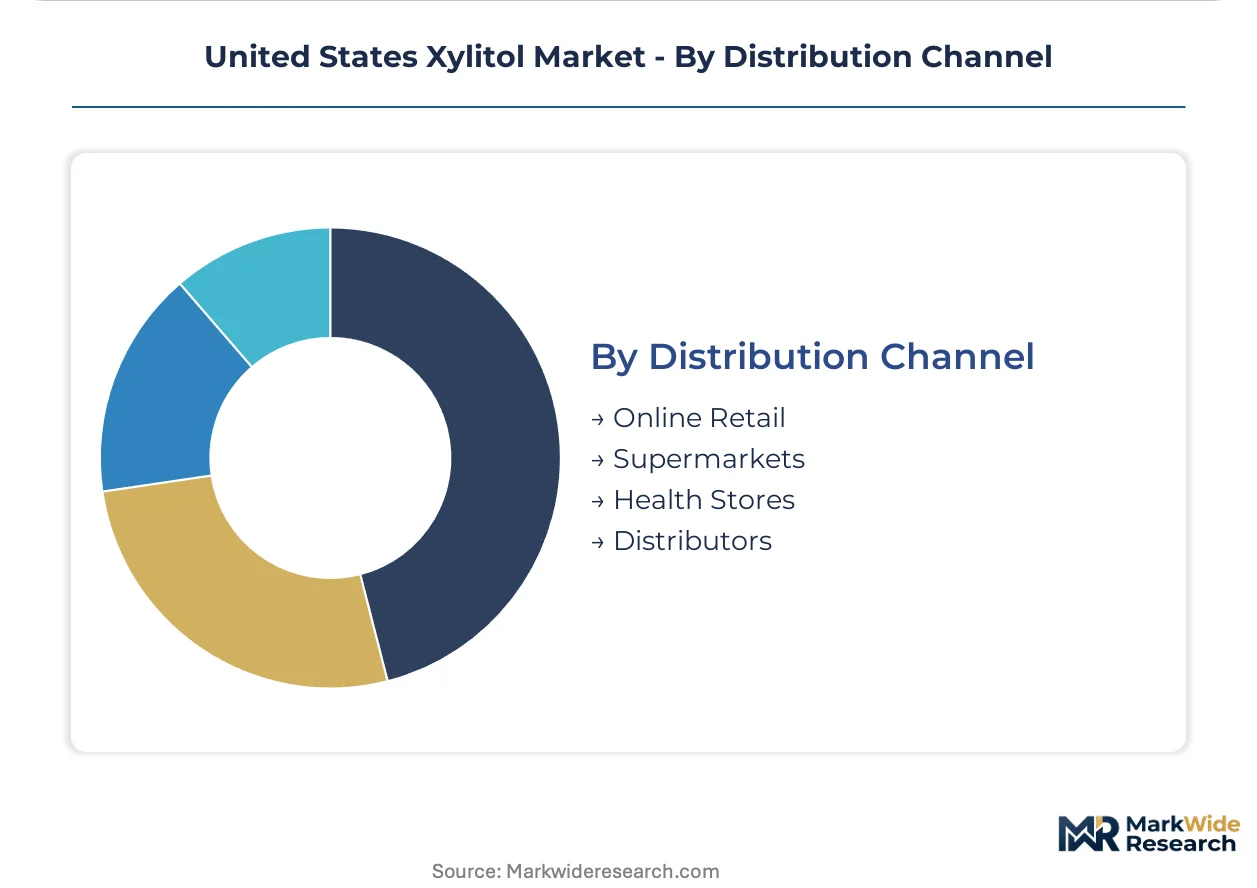
Distribution Channel:
Channel selection determines working capital intensity and geographic reach, with distributor networks requiring inventory float that squeezes smaller producers.
- Distributors:National ingredient distributors aggregate demand from regional food manufacturers, offering technical support and just-in-time delivery. Ingredion and Cargill's captive distribution arms dominate this channel.
- Online Retail:Direct-to-consumer platforms for dental care and nutraceutical SKUs, enabling premium pricing through subscription models and clinical content marketing.
- Supermarkets:Mass retail placement for consumer-packaged goods with front-of-pack sugar reduction claims.
- Health Stores:Specialty retail channel for organic-certified and non-GMO positioned products with higher margin tolerance.
Distributors absorb the bulk of installed capacity; Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in the Corn Belt while consumption spreads across coastal formulation centers. The Midwest generates captive xylose supply from wet milling infrastructure. Coastal states drive finished product demand through food manufacturing and dental care channels.
Midwest
Corn wet milling operations across Iowa, Minnesota, and Nebraska generate captive xylose feedstock for hydrogenation facilities. FERC-regulated electricity rates influence fermentation economics at bioprocessing plants. Minneapolis-St. Paul anchors technical services clusters supporting formulation optimization for regional food manufacturers.
Southwest
Texas beverage producers negotiate multi-year offtake agreements to secure price certainty against Midwest logistics costs. FDA GRAS self-affirmation pathways accelerate reduced-sugar product launches from Dallas-Fort Worth formulation labs. Houston petrochemical infrastructure supports specialty chemical distributors serving regional food manufacturers.
California
Beverage manufacturers in Los Angeles and San Francisco drive liquid xylitol demand for rapid-dissolution applications. State-level clean energy incentives reshape facility location decisions for fermentation-based production. Sacramento regulatory consultants specialize in USDA organic certification navigation for biomass-sourced xylose suppliers.
Southeast
Pediatric oral care brands in Florida leverage pharmacy chain distribution for clinical caries prevention programs. Southern pulp mills retrofit spent liquor processing to extract xylose from hardwood biomass. Atlanta distribution hubs aggregate demand from regional bakery and confectionery manufacturers.
Northeast
Dental care compounders in the Northeast concentrate procurement of micronized powder grades for compressible delivery systems. OSHA process safety mandates favor capital-intensive operators with established environmental management systems. Boston-area nutraceutical developers formulate blood glucose management supplements targeting functional positioning trends.
United States Xylitol Market Key Industry Players
Top-tier vendors anchor supply-side concentration, while mid-size manufacturers exploit modular technology to decentralize production. Three biotech manufacturing clusters control over 80% of domestic xylose hydrogenation capacity. Strategic archetypes include corn wet milling conglomerates with captive feedstock, biotechnology specialists with proprietary fermentation strains, and regional processors with distributed biomass sourcing. Dominant competitive moves encompass backward integration into xylose supply and capacity expansion through continuous catalytic hydrogenation systems.
Among established domestic operators, Cargill exemplifies the feedstock-integrated archetype through its Upper Midwest corn wet milling infrastructure. DuPont de Nemours occupies a position within biotechnology leadership circles through metabolic pathway engineering capabilities. Ingredion anchors industrial-scale production with nationwide distribution integration. ZuChem represents the specialized fermentation technology segment with Chinese operational origins. Roquette Frères, a French société anonyme, exemplifies European biomass processing expertise applied to North American market development.
| Leading Market Players |
|---|
| Cargill |
| DuPont de Nemours |
| Ingredion |
| zuChem |
| Roquette Frères |
| Archer Daniels Midland Company |
| Dynamic Food Ingredients |
| Danisco |
| DFI Corp |
| Others |
Cost & Logistics Intelligence
Corn futures price volatility cascades through xylose hydrogenation economics, compressing fermentation margins at Midwest facilities and forcing contract renegotiations between ingredient suppliers and food manufacturers across three distinct pricing tiers.
Pricing Analysis
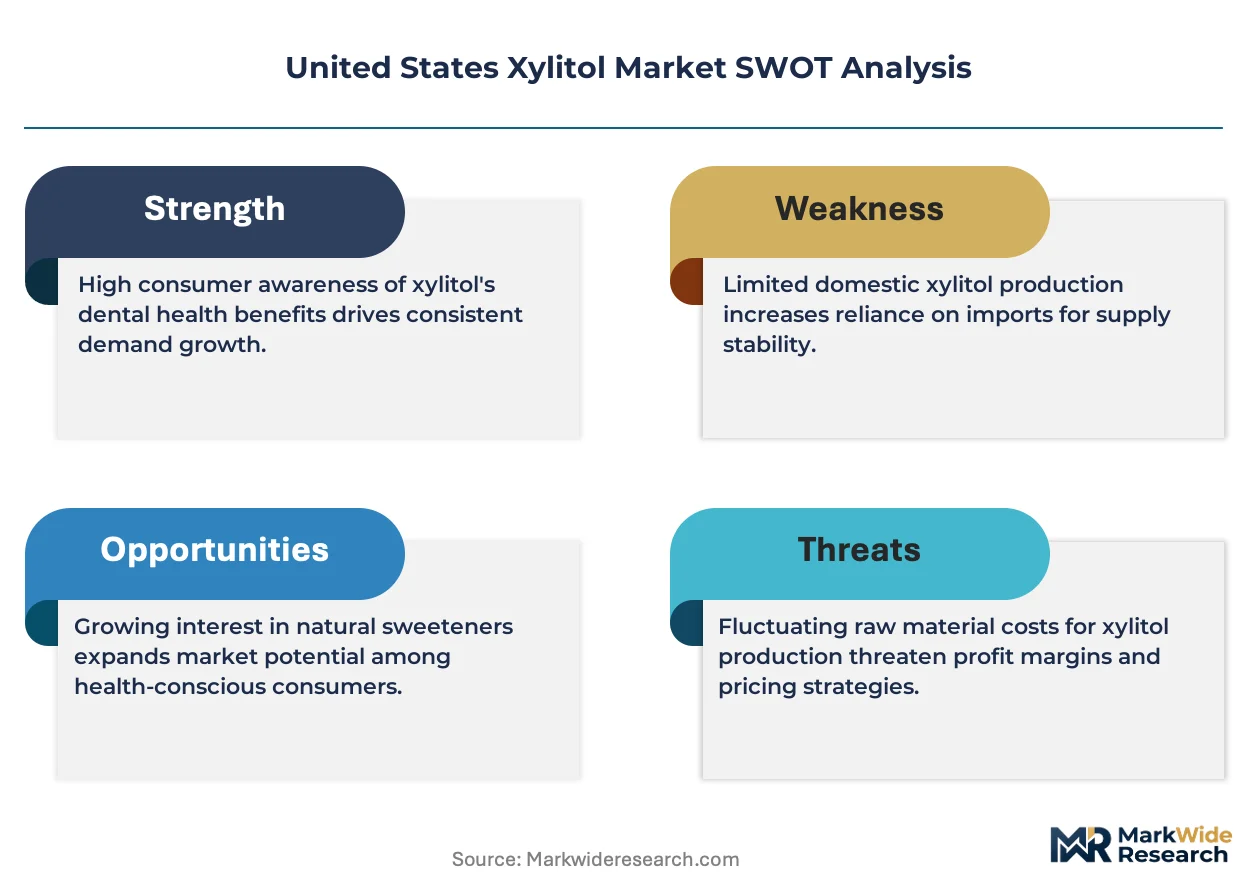
Cost compression in standard-grade powder formulations accelerates as allulose and erythritol achieve functional parity in beverage applications, eroding xylitol's formulation premium. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certifications separates premium dental-care compounders from mass-market bakery producers. Pricing pressure intensifies in liquid formats as California beverage manufacturers demand tanker-truck delivery guarantees. Contract-based long-term offtake agreements dominate procurement for food manufacturers seeking price certainty, while spot-market exposure concentrates among smaller nutraceutical blenders least able to hedge feedstock volatility.
Supply Chain Analysis
Freight costs from Iowa and Minnesota production clusters to Texas and California formulation centers add 12-18% to delivered xylitol costs, incentivizing Southwest buyers to secure multi-year volume commitments. Domestic supply concentrates in the Upper Midwest corn belt, with limited hardwood biomass hydrolysis capacity emerging in the Southeast. Raw material dependencies center on corn-derived xylose, catalytic hydrogenation catalysts, and FERC-regulated process energy. Single-source vulnerability pervades the concentrated biotech manufacturing cluster structure. Distribution runs through captive distributor arms of major suppliers and direct procurement contracts with large food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous catalytic hydrogenation systems are displacing legacy batch fermentation infrastructure, compressing capital thresholds and enabling distributed production economics that reshape competitive positioning across the value chain.
For Market Incumbents: Extend backward integration into hardwood biomass xylose sourcing to diversify beyond corn price exposure. Lock in fermentation strain engineering talent through dedicated metabolic pathway research centers in Minneapolis-St. Paul technical clusters. Defend market position by accelerating USDA organic certification timelines ahead of pending FDA sugar alcohol labeling guidance. For New Entrants and Emerging Players: Veterinary dental care compounders represent an underserved buyer archetype with premium pricing tolerance and minimal regulatory friction. Target pet oral care applications through direct veterinary channel partnerships, bypassing established food manufacturer procurement hierarchies. White-space concentration appears strongest in regional biomass processing for certified-organic xylitol grades serving health store distribution. For Investors and Strategic Acquirers: Distressed-cycle entries favor modular skid-mounted hydrogenation system operators in Wisconsin and Michigan with sub-$10 million capital deployment thresholds. Long-term viability hinges on feedstock flexibility and regulatory compliance infrastructure rather than scale alone. Watch FDA guidance finalization timing as the inflection signal for reformulation-driven demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biomass Sourcing | Hardwood xylose extraction diversifies supply beyond Corn Belt corn price cycles. |
| Continuous Catalytic Hydrogenation Deployment | Fixed-bed reactor designs slash capital thresholds from $50 million to $8 million per line. |
| USDA Organic Certification Investment | Certified-sustainability grades command premium positioning in health store channels. |
| Direct Procurement Contract Structuring | Multi-year offtake agreements with California and Texas food manufacturers displace distributor mediation. |
| Veterinary Dental Care Channel Development | Pet oral care applications open premium pricing vertical with minimal FDA regulatory friction. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with corn wet milling procurement directors, fermentation plant managers, food manufacturer formulation leads, and dental care compounder technical buyers. FDA GRAS determination databases, USDA National Organic Program certification records, FERC electricity rate filings, and EPA NPDES permit disclosures provided regulatory context. Bottom-up volume modeling triangulated against top-down value chain analysis.
Data-stream reconciliation across production capacity surveys, feedstock price indices, and end-use demand audits informed the analytical framework. Segmentation dimensions spanned physical form, application vertical, end-user procurement sophistication, and regional production-consumption dynamics. CAGRs derived from trend extrapolation of xylose hydrogenation capacity expansion and substitution elasticity estimates for competing polyols. Industry-specific forecast inputs incorporated corn price cycle modeling and pending FDA labeling rule impact assessment.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to drought-induced corn price spikes, regulatory guidance timing, and technological substitution rates. Forecasts reflect documented assumptions about feedstock availability, energy cost trajectories, and competitive polyol performance evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Citrus Molasses Market
Sweeteners
Fructose Market
Sweeteners
South America Stevia Market
Sweeteners
Raw Beetroot Sugar Market
Sweeteners
Egypt Food Sweetener Market
Sweeteners
Africa Stevia Market
Sweeteners
Granulated Sugar Market
Sweeteners
Naturally Derived Sweeteners Market
Sweeteners
Sugar Syrups Market
Sweeteners
Dextrose Syrup Market
Sweeteners
Agave Syrup Market
Sweeteners
Fermented Sweeteners Market
Sweeteners
Allulose Market
Sweeteners
Xylose Market
Sweeteners
Middle East and Africa Sugar Substitutes Market
Sweeteners
China Allulose Market