
 Natural Malt Sweeteners Market | 2026-2036
Natural Malt Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Malt Sweeteners Market Foresight
Food manufacturer procurement is shifting toward malt extract and liquid malt as clean-label alternatives to refined sugars in bread, crackers, and cereal formulations. Cargill, Incorporated leverages its North American grain origination network to secure barley supply continuity for malt syrup production. Briess Malt & Ingredients Co. specializes in craft-scale roasting profiles that differentiate its portfolio for premium bakery clients. Grain Processing Corporation anchors industrial volume through large-scale dry malt capacity serving multinational food manufacturers.
Natural malt sweeteners are enzymatically converted barley or other grain extracts containing maltose, dextrins, and trace minerals, typically produced through controlled germination followed by mashing and evaporation to achieve 65–80 percent solids content. Their primary commercial purpose is to provide browning, moisture retention, and fermentable sugars without synthetic additives. Liquid malt extract dominates food manufacturer channels where bulk handling and consistent viscosity reduce formulation variance, while dry malt powder captures margin pools in artisanal bakeries seeking extended shelf stability and precise dosing control. Beverage applications represent the fastest-growing application segment as craft brewers and malt-based soft drink producers expand capacity.
EFSA nutrition labeling requirements and EU Green Deal agricultural sourcing standards shape product formulation and supply chain documentation across European production. The FDA GRAS status for malt-derived ingredients governs US market access, while FSSAI clean-label guidelines in India create parallel compliance pathways for exporters. Stakeholders must monitor evolving added-sugar threshold definitions in multiple jurisdictions to anticipate reformulation cycles and qualification requirements.
Market Dynamics
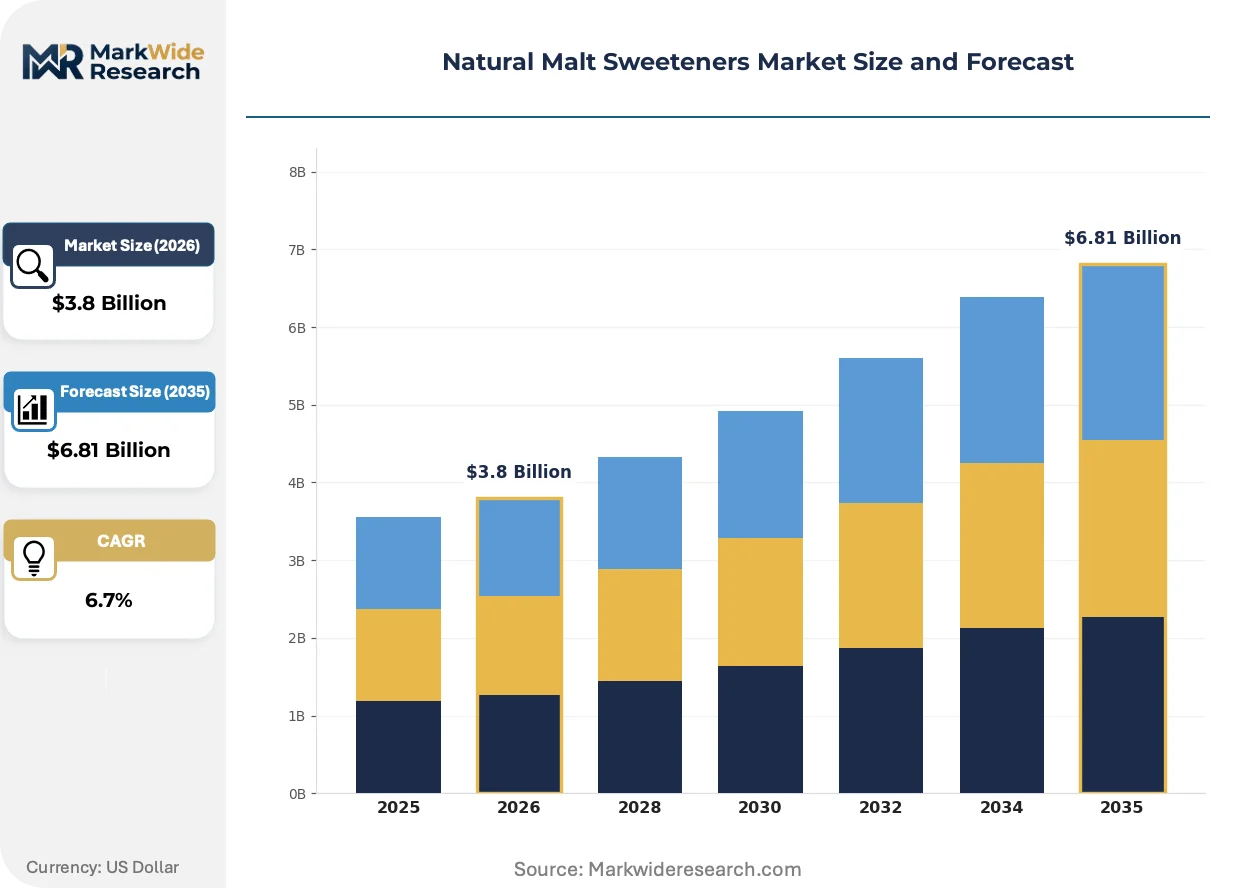
Clean-label disclosure mandates in Western Europe are forcing systematic reformulation across industrial bakery supply chains, pulling malt extract into formulations that previously relied on refined sucrose or high-fructose corn syrup.
Growth Catalysts
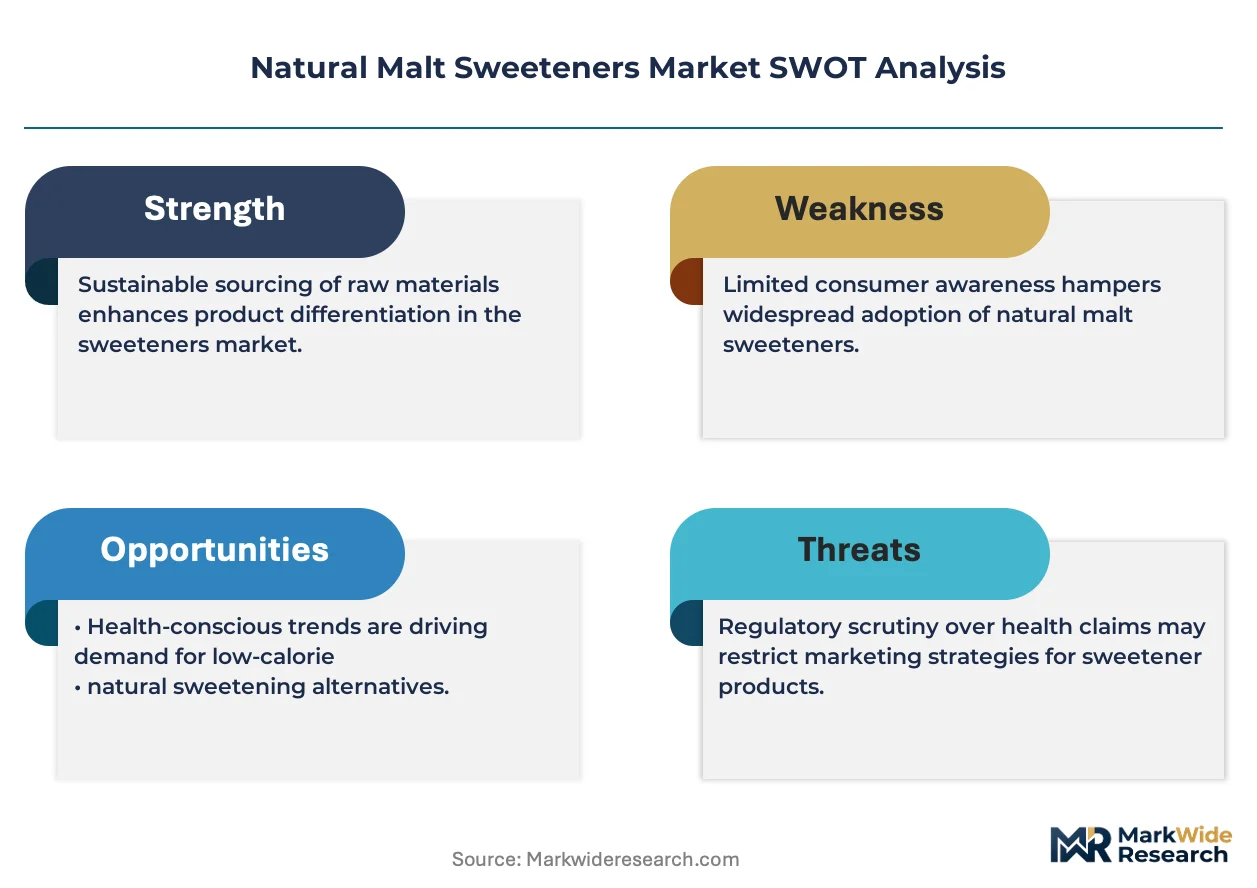
- EFSA added-sugar thresholds:Tightened disclosure rules in Germany and France compel industrial bakers to substitute malt-derived ingredients for refined sugars to avoid front-of-package warning labels.
- Craft beverage expansion:Small-scale brewers and malt-based soft drink producers in Belgium and the Netherlands are scaling capacity, creating parallel demand streams for liquid malt extract.
- Enzymatic conversion efficiency:Advances in controlled germination and mashing protocols reduce extraction losses, improving unit economics for malt syrup producers serving food manufacturers.
Market Restraints
- Barley input volatility:Weather-driven yield fluctuations in major grain-producing regions create margin pressure for malt processors without long-term origination contracts.
- Supply concentration:A limited number of specialized roasters control premium malt extract capacity, creating bottleneck risk for artisanal bakery clients seeking differentiated flavor profiles.
- Technical substitution:Allulose and monk fruit extracts offer comparable clean-label positioning with lower caloric density, threatening malt sweetener share in calorie-conscious segments.
Strategic Opportunities
- India FSSAI clean-label pathways:Exporters meeting Indian food safety standards can access reformulating processed food manufacturers in Mumbai and Bangalore seeking alternatives to synthetic sweeteners.
- Precision fermentation convergence:Hybrid processes combining traditional malting with enzyme engineering enable customized dextrin profiles for functional nutrition applications.
- Direct-to-bakery digital channels:E-procurement platforms connecting malt suppliers with regional bakery cooperatives bypass traditional distributor markups in fragmented Southern European markets.
Industry Challenges
- Malting technician scarcity:Specialized knowledge in germination control and kilning optimization is concentrating among aging workforces in traditional producing regions.
- EU Green Deal documentation:Agricultural sourcing traceability requirements demand capital investment in supply chain monitoring systems for barley provenance verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Malt Sweeteners Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Malt Extract, Liquid Malt, Dry Malt, Malt Syrup Application: Baking, Beverages, Confectionery, Dairy Products End User: Food Manufacturers, Beverage Companies, Bakeries, Restaurants Form: Powder, Liquid, Syrup, Granules |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Grain Processing Corporation, Briess Malt & Ingredients Co., Ingredion Incorporated, Tate & Lyle PLC, DuPont Nutrition & Health, Roquette Freres, Associated British Foods Plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Malt Sweeteners Market Shifts & Advancements
Enzymatic process control and regulatory disclosure mechanics are reshaping how malt sweeteners compete against both synthetic alternatives and novel natural substitutes across food and beverage formulations.
Spray-drying technology with modified atmosphere packaging is integrating into malt powder production lines to extend shelf stability without antioxidant additives. Premium artisanal bakeries in Denmark and Sweden are adopting these stabilized formats for precise dosing in small-batch operations. The technology is integrating formerly separate handling and storage steps, reducing formulation variance for remote bakery locations.
EU Green Deal agricultural sourcing standards now require documented carbon footprint calculations for imported grain inputs. Malt processors must retrofit supply chain audit systems to maintain access to institutional foodservice contracts in France and Germany. Industrial bakers with multinational retail exposure are prioritizing suppliers with certified sustainable barley programs to preempt compliance gaps.
Buyer consolidation among European supermarket private-label programs is compressing supplier negotiation cycles from annual to quarterly reviews. Mid-sized malt extract producers in Poland and the Czech Republic are losing shelf space to vertically integrated grain processors with dedicated clean-label divisions. This concentration is most visible in German discount retail channels where reformulation decisions now centralize at headquarters level rather than regional procurement offices.
Natural Malt Sweeteners Market Segmentation
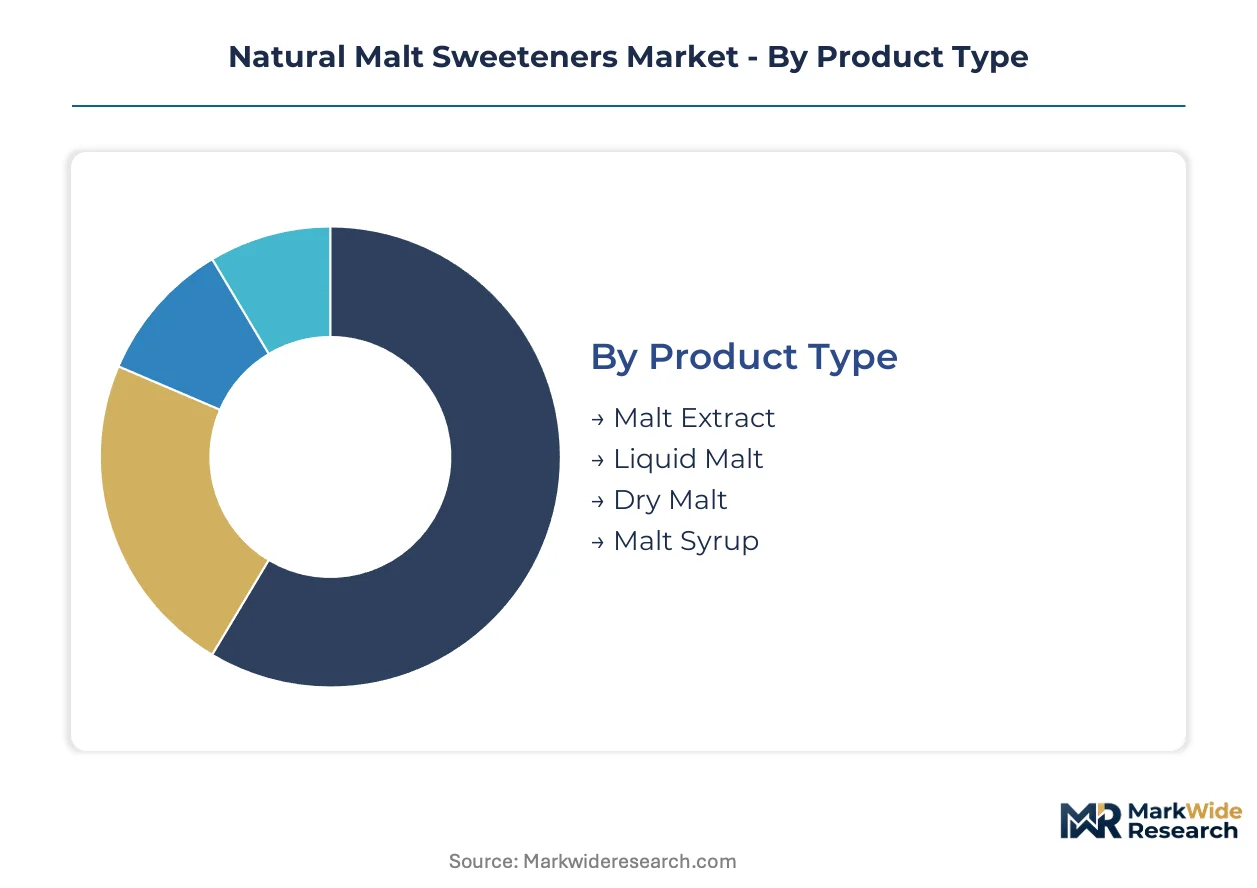
Malt sweetener procurement patterns diverge sharply by product viscosity, application heat tolerance, and end-user scale. Understanding these splits reveals where formulation flexibility commands premium pricing versus where bulk logistics dominate supplier selection.
Product Type:
Reformulation cycles in Western European baking are accelerating replacement of refined sugars with enzymatically converted grain extracts, with viscosity specifications determining equipment compatibility.
- Malt Extract:Concentrated barley or grain derivatives containing 65–80 percent solids with standardized maltose content. German and French industrial bakers deploy this format for consistent browning control in high-volume bread lines where EFSA disclosure thresholds drive sucrose substitution.
- Liquid Malt:Pumpable syrup with controlled dextrin profiles enabling bulk tanker delivery. Beverage companies in Belgium and the Netherlands scale capacity fastest here, as craft brewers and malt-based soft drink producers require fermentable sugar streams with minimal handling variance.
- Dry Malt:Spray-dried powder with extended ambient stability. Artisanal bakeries in Denmark favor this for precise gram-scale dosing in small-batch operations.
- Malt Syrup:High-viscosity reduced liquid with enhanced Maillard reactivity. Confectionery applications in Poland select this for caramel color development without synthetic additives.
Volume placements concentrate in Malt Extract; the faster expansion belongs to Liquid Malt.
Application:
Heat exposure during processing and finished-product moisture targets segment demand by functional requirement rather than brand positioning.
- Baking:Crust browning and crumb moisture retention in bread, crackers, and cereals. Industrial lines in Germany reformulate most aggressively here to preempt front-of-package warning labels under tightened national sugar disclosure rules.
- Beverages:Fermentable substrates for brewing and malt-based soft drinks. Belgian craft brewers and Dutch non-alcoholic malt drink producers are climbing the fastest as capacity investments outpace other segments.
- Confectionery:Viscosity modulation and color development in caramels and coatings. Polish and Czech manufacturers prioritize clean-label positioning for export to German discount retail channels.
- Dairy Products:Flavor masking and texture enhancement in yogurts and ice creams. Swedish and Finnish processors test limited trials for reduced-sugar positioning in Nordic markets.
Revenue gravity sits with Baking; Beverages are gaining share fastest on capacity expansion.
End User:
Procurement sophistication and quality documentation requirements split the customer base between multinational compliance systems and regional flexibility.
- Food Manufacturers:Multinational packaged goods producers with centralized reformulation mandates. German and French headquarters-level procurement now consolidates supplier selection quarterly, favoring processors with EU Green Deal barley traceability systems.
- Beverage Companies:Brewers and soft drink producers with fermentation-specific sugar specifications. Belgian craft brewers and Dutch malt beverage specialists source most dynamically, often direct from specialized roasters.
- Bakeries:Artisanal and industrial bread producers ranging from cooperative networks to factory lines. French artisanal clusters and German industrial districts diverge sharply in format preference—powder versus liquid.
- Restaurants:Foodservice operators with intermittent small-batch needs. Institutional caterers in France and Germany increasingly specify certified sustainable barley for contract compliance.
Contract value concentrates with Food Manufacturers; Beverage Companies are expanding procurement most rapidly.
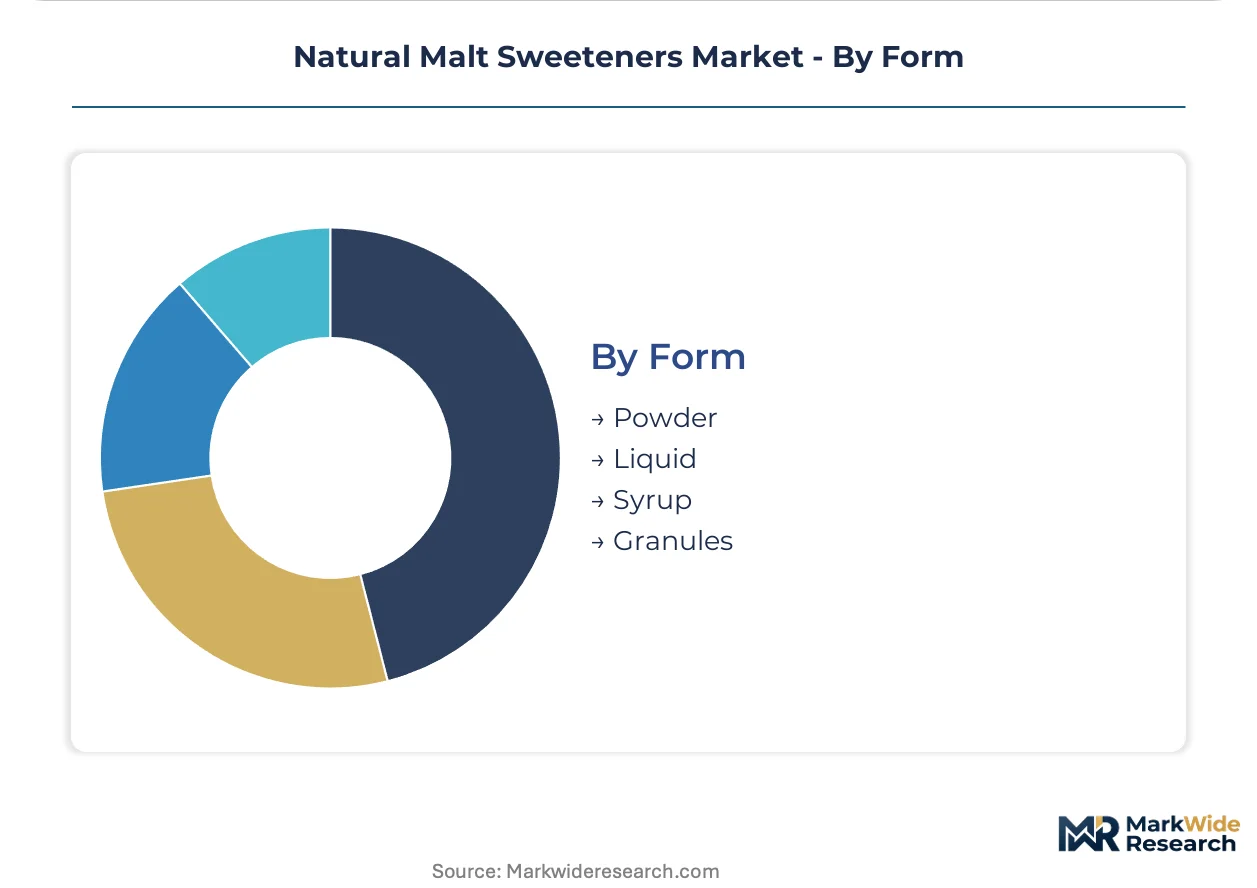
Form:
Handling infrastructure and shelf stability requirements determine format selection across climatic and logistical conditions.
- Powder:Spray-dried extract with modified atmosphere packaging stability. Remote artisanal bakeries in Southern Europe and Scandinavia select this for ambient storage without refrigeration infrastructure.
- Liquid:Bulk tanker-compatible syrup with consistent viscosity. German and Dutch industrial food manufacturers deploy this for automated dosing and minimal formulation variance.
- Syrup:High-viscosity reduced liquid for precise viscosity targets. Confectionery producers in Poland and the Czech Republic favor this for controlled caramelization behavior.
- Granules:Agglomerated powder for free-flowing handling characteristics. Limited niche adoption in bakery cooperatives seeking intermediate handling properties.
Shipment volumes cluster in Liquid; Powder is climbing fastest on extended-shelf-life technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Barley cultivation concentrates in temperate grain belts, while malt sweetener consumption clusters in reformulating food manufacturing hubs. This geographic split shapes trade flows and regulatory compliance investments.
Germany
Industrial bakers in Bavaria and North Rhine-Westphalia drive malt extract procurement as tightened national sugar disclosure rules compel front-of-package reformulation. EFSA thresholds govern labeling requirements across German retail channels. The Munich-Stuttgart corridor hosts headquarters-level procurement consolidation for multinational bakery programs.
France
Artisanal bakery cooperatives in Île-de-France and Hauts-de-France source dry malt powder for precise small-batch dosing. EU Green Deal agricultural sourcing standards mandate documented carbon footprint calculations for imported grain inputs. Lille and Paris basin industrial zones anchor reformulation activity for discount retail private-label programs.
Belgium
Craft brewers in Flanders and Wallonia scale liquid malt extract capacity fastest among European beverage segments. National regulators align with EFSA disclosure frameworks while accommodating fermentation-specific sugar specifications. The Leuven-Liège axis concentrates malt beverage innovation and specialty roasting capacity.
Netherlands
Malt-based soft drink producers in Randstad cities expand fermentation capacity for non-alcoholic alternatives. Dutch food safety authorities enforce parallel compliance with EU-wide clean-label standards. Rotterdam-Amsterdam logistics corridors enable bulk tanker distribution across Northwestern European manufacturing networks.
India
Processed food manufacturers in Maharashtra and Karnataka test malt-derived ingredients for clean-label positioning in domestic and export markets. FSSAI guidelines create compliance pathways for natural sweetener alternatives to synthetic additives. Mumbai and Bangalore industrial clusters drive procurement trials among reformulating multinational subsidiaries.
Natural Malt Sweeteners Market Competitive Landscape
Top-tier vendors anchor North American grain origination networks, while mid-sized European specialists control premium roasting capacity. The vendor base stratifies across three tiers: multinational grain processors with captive malting divisions, regional specialists in craft-scale flavor profiles, and commodity traders supplying bulk industrial volumes. Two dominant competitive moves are emerging: backward integration into barley origination contracts to secure input stability, and portfolio diversification into spray-dried formats for extended-shelf-life applications.
Within the multinational processor tier, Cargill, Incorporated and Archer Daniels Midland Company represent integrated grain-to-malt supply chain control. Among specialized roasting specialists, Briess Malt & Ingredients Co. occupies a position exemplifying craft-scale differentiation for premium bakery clients. Grain Processing Corporation anchors industrial volume capacity serving large-scale food manufacturers with standardized extract specifications.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Grain Processing Corporation |
| Briess Malt & Ingredients Co. |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| DuPont Nutrition & Health |
| Roquette Freres |
| Associated British Foods Plc. |
| Others |
Supply & Pricing Matrix
Malting technician scarcity in traditional producing regions of Germany and the Czech Republic widens labor-cost differentials between craft-scale roasters and industrial processors, compressing pricing-tier spreads as premium capacity commands escalating wage premiums.
Pricing Analysis
Margin tightening in standard-grade malt extract reflects buyer consolidation among German discount retail private-label programs. Three-tier pricing structure across premium, standard, and economy levels differentiates by roasting profile sophistication and EU Green Deal barley certification status. Cost-down pressure on economy tiers accelerates because multinational food manufacturers centralize procurement quarterly, squeezing mid-sized Polish and Czech suppliers. Artisanal bakeries in Denmark and Sweden show least price sensitivity, prioritizing spray-dried format stability over per-kilogram cost.
Supply Chain Analysis
EU Green Deal agricultural sourcing standards gate market access through documented carbon footprint calculations for imported grain inputs. Supply concentrates in Germany, France, and Belgium for premium roasting capacity, with North American grain origination feeding industrial volume streams. Barley input dependency rests on temperate cultivation belts vulnerable to weather-driven yield fluctuations. Single-source vulnerability concentrates in specialized kilning equipment providers. Distribution runs through Rotterdam-Amsterdam bulk tanker corridors for liquid formats and modified-atmosphere packaging channels for powder stability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized malting technician scarcity props pricing power for premium extract capacity, constraining supply expansion faster than reformulation demand accumulates across Western European bakery supply chains.
For Market Incumbents: Deepen backward integration into long-term barley origination contracts to neutralize weather-driven input volatility threatening margin stability. Expand spray-dried production lines in Denmark and Sweden to capture artisanal bakery demand for extended-shelf-life formats. Allulose and monk fruit substitution threats in calorie-conscious segments demand accelerated precision fermentation R&D investment.
For New Entrants and Emerging Players: FSSAI clean-label guidelines in India open a window for malt extract penetration among reformulating processed food manufacturers in Mumbai and Bangalore. Target e-procurement platform integration for Southern European bakery cooperatives bypassing traditional distributor markups. White-space concentration sits with direct-to-artisan digital channels and certified sustainable barley programs for institutional foodservice contracts.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-sized European roasting specialists given EU Green Deal traceability compliance as a scarce capability. Five-to-ten-year viability favors processors with hybrid traditional malting and enzyme engineering expertise. Watch Belgian craft brewer capacity expansion rates as inflection indicator for liquid malt extract demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barley Origination | Long-term supply contracts with North American grain networks secure input continuity against climate volatility. |
| Spray-Drying Capacity Expansion | Modified atmosphere packaging integration captures premium pricing from remote artisanal bakeries in Scandinavia. |
| Precision Fermentation Convergence | Hybrid enzyme engineering enables customized dextrin profiles for functional nutrition applications. |
| EU Green Deal Traceability Certification | Documented carbon footprint systems maintain access to French and German institutional foodservice contracts. |
| Direct-to-Bakery Digital Platform Launch | E-procurement channels bypass distributor markups in fragmented Southern European cooperative markets. |
Research Methodology
Trade flow databases, EFSA regulatory filings, and FSSAI guideline documents formed the secondary backbone for supply chain mapping and compliance pathway identification. Primary interviews with malting technicians, industrial bakery procurement directors, craft brewer operations managers, and grain origination specialists validated extraction yield assumptions and reformulation timelines. Bottom-up volume estimates by product format and application segmented across top-down macroeconomic constraints.
Historical trendline analysis of malt extract displacement rates in German and French industrial baking informed projection elasticity parameters. Segmentation modeling spanned product viscosity, heat tolerance requirements, end-user procurement sophistication, and regional regulatory clusters. CAGRs derived from capacity expansion announcements, fermentation substrate demand curves, and clean-label substitution elasticities across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation convergence would alter the outlook if enzyme engineering achieves cost parity faster than anticipated. Forecasts reflect assumptions about EFSA threshold enforcement consistency and barley yield stability in major producing regions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Turbinado Sugar Market
Sweeteners
Sugar Alcohol Market
Sweeteners
South America Stevia Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
China Saccharin Market
Sweeteners
Argentina Food Sweetener Market
Sweeteners
Asia-Pacific Low-Calorie Sweeteners Market
Sweeteners
Sugar Polyols Market
Sweeteners
Dry Sweeteners Market
Sweeteners
Floral Nectar Market
Sweeteners
Global Starch Sweetener Market
Sweeteners
Sweet Modulator Market
Sweeteners
Stevia Market
Sweeteners
D-Mannose Market
Sweeteners
Natural Caloric Sweeteners Market
Sweeteners
Citrus Molasses Market