
 Granulated Sugar Market | 2026-2036
Granulated Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Granulated Sugar Market Foresight
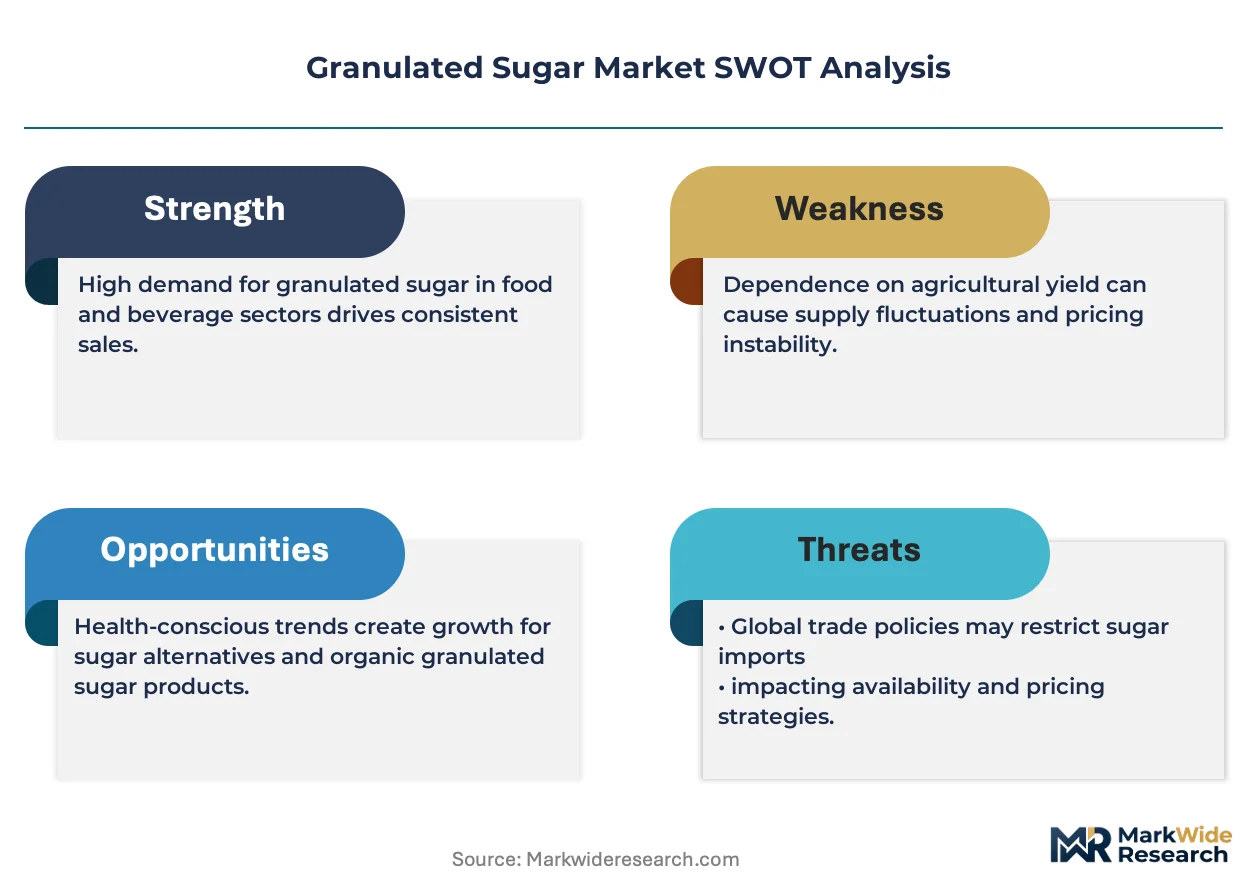
The capital-intensity divergence between integrated millers and standalone refiners is redrawing competitive boundaries across the sector. Südzucker AG leverages its beet-to-bag vertical integration to sustain margin capture across Central European growing regions. Raízen S.A. anchors its position through bioenergy co-generation assets that offset processing costs at Brazilian cane complexes. Tereos S.A. competes via cooperative ownership structures that lock in raw material supply from French beet growers.
Granulated sugar consists of sucrose crystals refined from sugarcane or sugar beet to achieve minimum purity standards, typically processed through diffusion, carbonatation, and crystallization stages to produce free-flowing crystals for industrial and consumer use. White sugar dominates volume flows into beverage manufacturing, where standardization requirements favor consistent crystal size and color grades. Brown sugar and organic sugar command premium positioning within retail channels, though specialty sugar variants targeting artisanal bakery applications represent the fastest-expanding margin pool as clean-label formulations gain traction.
The FDA enforces added-sugar disclosure rules on Nutrition Facts panels, while the EU Green Deal drives decarbonization benchmarks across beet processing operations. India's FSSAI mandates quantitative sugar declarations on packaged foods, reshaping reformulation strategies for confectionery exporters. Stakeholders must monitor evolving sweetener substitution thresholds in beverage formulations, as regulatory pressure and consumer preference shifts jointly determine the viable demand ceiling for crystalline sucrose.
Market Dynamics
Beet-to-cane sourcing ratios are compressing as climate volatility disrupts traditional growing calendars across temperate and tropical zones simultaneously. Refiners now hedge procurement across multiple hemispheres to maintain crush schedules.
Growth Catalysts
- Clean-label confectionery mandates:EU Green Deal decarbonization benchmarks are forcing packaged food manufacturers to source certified low-carbon sucrose for export eligibility.
- Brazil's ethanol-sugar flex capacity:São Paulo state mills now divert crush volumes toward crystalline output when international sweetener premiums exceed biofuel returns.
- Carbonatation filtration advances:Membrane diffusion technologies are reducing energy intensity in beet processing plants across France and Germany.
Market Restraints
- Input cost volatility:Natural gas price spikes directly inflate thermal energy costs for crystallization and drying stages at European beet refineries.
- Supply concentration risk:Thailand's drought-prone Northeast region supplies critical raw cane to ASEAN processors, creating single-point vulnerability.
- Substitution threat:Allulose and monk fruit extract are capturing formulation share in premium beverage applications where calorie reduction is paramount.
Strategic Opportunities
- Underpenetrated African markets:Nigeria's packaged food sector remains dependent on imported refined sugar despite rising domestic cane cultivation in Kano state.
- Regulatory tailwind:India's PLI scheme for food processing infrastructure offers capital subsidies for integrated sugar-ethanol complexes in Uttar Pradesh and Maharashtra.
- Channel innovation:Direct-to-bakery distribution networks are bypassing traditional commodity brokers in Mexico's artisanal bread sector.
Industry Challenges
- Skill scarcity in process automation:Beet factories struggle to hire control systems engineers capable of integrating AI-driven crystallization monitoring with legacy carbonatation equipment.
- Certification timeline compression:FSSAI's tightened labeling norms require reformulation documentation that extends product development cycles for exporters targeting India.
- Capex intensity for co-generation:Bagasse-fired turbine retrofits demand capital allocations that strain cooperative-owned mill balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Granulated Sugar Market |
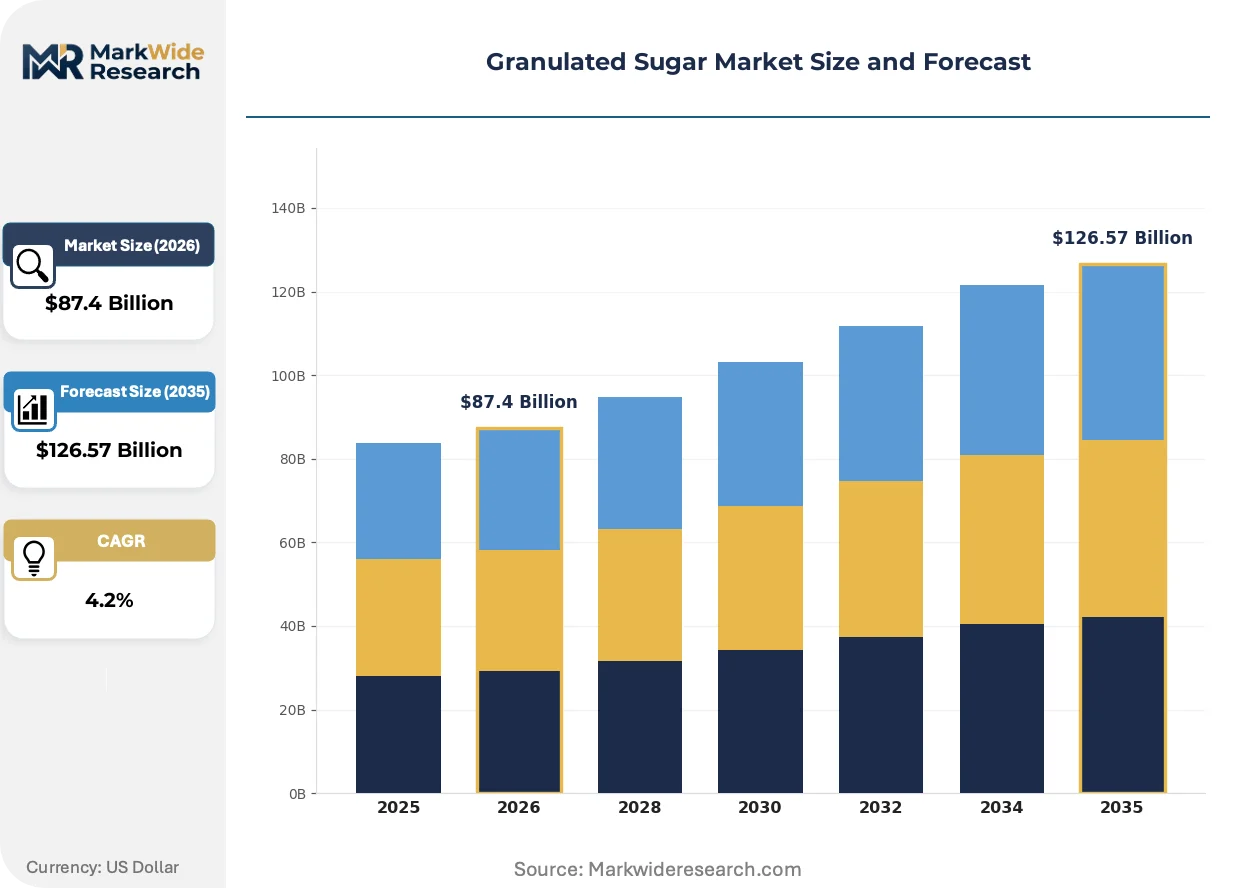
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $126.57 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Sugar, Brown Sugar, Organic Sugar, Specialty Sugar End User: Food Industry, Beverage Manufacturers, Bakery Products, Confectionery Packaging Type: Bags, Bulk Containers, Sachets, Pouches Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Raízen S.A., American Sugar Refining, Südzucker AG, Nordzucker AG, Mitr Phol Sugar, Tereos S.A., Wilmar International Ltd., Associated British Foods, Cosan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Granulated Sugar Market Shifts & Advancements
Digital traceability platforms are penetrating agricultural procurement, while thermal efficiency technologies reshape processing economics. These shifts are compressing traditional cost structures and opening premium positioning pathways.
Continuous vacuum pan automation is displacing batch crystallization systems that dominated twentieth-century refinery design. Brazilian and Indian mills now deploy sensor-driven brix control to standardize crystal formation rates. This precision is displacing manual pan boiling labor and enabling real-time quality certification for export-grade ICUMSA specifications.
REACH chemical registration requirements are tightening impurity thresholds for processing aids used in European beet factories. Carbonatation lime quality standards now mandate heavy metal testing that adds analytical costs but protects downstream food safety credentials. German and French refiners are responding by vertically integrating into captive limestone quarrying to secure compliant supply.
Consolidation among beverage multinationals is compressing supplier qualification timelines and favoring refiners with integrated logistics assets. Direct procurement contracts now bypass commodity exchanges for volume commitments exceeding fifty thousand metric tons annually. This concentration is most visible in Mexico and Colombia, where Coca-Cola FEMSA and Postobón have reduced their approved supplier rosters by two-thirds since 2022.
Granulated Sugar Market Segmentation
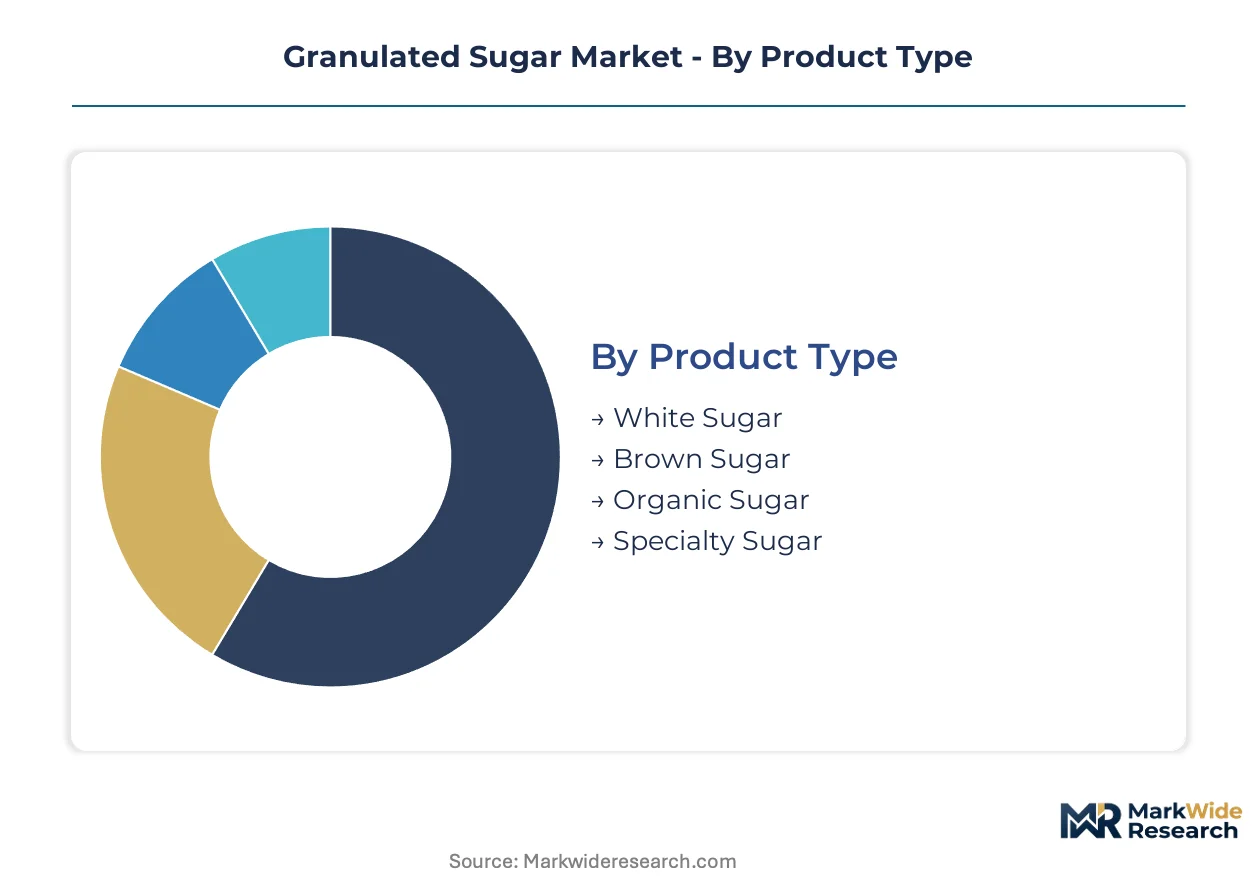
Granulated sugar markets fragment across crystalline purity grades, industrial procurement patterns, and logistics formats that determine margin capture. Each segmentation axis reveals distinct competitive dynamics between commodity volume plays and premium positioning strategies.
Product Type:
Premium extraction and certification costs concentrate margin pools at the specialty and organic ends of this spectrum, while white sugar dominates absolute volume flows.
- White Sugar:Refined sucrose achieving ICUMSA color standards below 45 IU serves as the baseline specification for industrial beverage and confectionery formulations. Brazilian mills in São Paulo state and Thai exporters anchor supply into ASEAN and Middle Eastern processing plants, where standardization requirements lock in multi-year procurement contracts.
- Brown Sugar:Retained molasses content of 3.5-6.5% by weight delivers moisture and flavor complexity for artisanal bakery applications. North American and Western European retail channels command premium shelf positioning, though moisture variability complicates industrial-scale handling.
- Organic Sugar:Certified cane cultivation excluding synthetic pesticides and herbicides commands 40-60% price elevation over conventional grades. Supply concentrates in Paraguayan and Indian certified cooperatives serving EU Green Deal compliance requirements.
- Specialty Sugar:Demerara, turbinado, and muscovado variants target clean-label confectionery and premium beverage garnish segments. French and Mauritian exporters dominate origin-designated positioning.
The dominant share belongs to White Sugar, while Specialty Sugar is closing the gap fastest.
End User:
Procurement scale and specification stringency vary dramatically across food manufacturing verticals, with beverage producers imposing the tightest quality audit protocols.
- Food Industry:Processed food manufacturers source standard-grade crystalline sucrose for sauces, dressings, and preserved products. Indian FSSAI labeling mandates are accelerating reformulation documentation requirements for exporters.
- Beverage Manufacturers:Carbonated and ready-to-drink tea processors demand consistent brix levels and rapid dissolution kinetics. Coca-Cola FEMSA and Postobón in Latin America have consolidated supplier rosters by two-thirds since 2022.
- Bakery Products:Artisanal bread and pastry operations favor brown sugar and specialty grades for moisture retention and caramelization control. Direct-to-bakery distribution networks are bypassing commodity brokers in Mexico.
- Confectionery:Hard candy and chocolate producers require precise crystal size distribution for texture engineering. EU Green Deal decarbonization benchmarks are forcing packaged food manufacturers to source certified low-carbon sucrose for export eligibility.
Beverage Manufacturers capture the largest procurement volumes, though Bakery Products are expanding most quickly through channel disintermediation.
Packaging Type:
Logistics cost structures and customer handling requirements create sharp segmentation between industrial bulk and consumer-facing formats.
- Bags:Multi-wall paper and woven polypropylene containers of 25-50 kg serve food manufacturing and foodservice redistribution. European beet refiners favor bagged formats for seasonal delivery flexibility.
- Bulk Containers:Flexible intermediate bulk containers and tanker shipments minimize unit logistics costs for high-volume beverage and confectionery processors. São Paulo state mills deploy dedicated rail spurs for bulk container loading.
- Sachets:Single-serve 5-10 gram packets dominate foodservice and airline catering channels. Indian and Southeast Asian packaging converters specialize in moisture-barrier laminates.
- Pouches:Stand-up and flat pouches of 500g-2kg target retail pantry stocking. Brazilian supermarket chains are expanding private-label pouch formats.
Bulk Containers command the highest absolute tonnage, while Pouches are gaining share fastest through retail format innovation.
Distribution Channel:
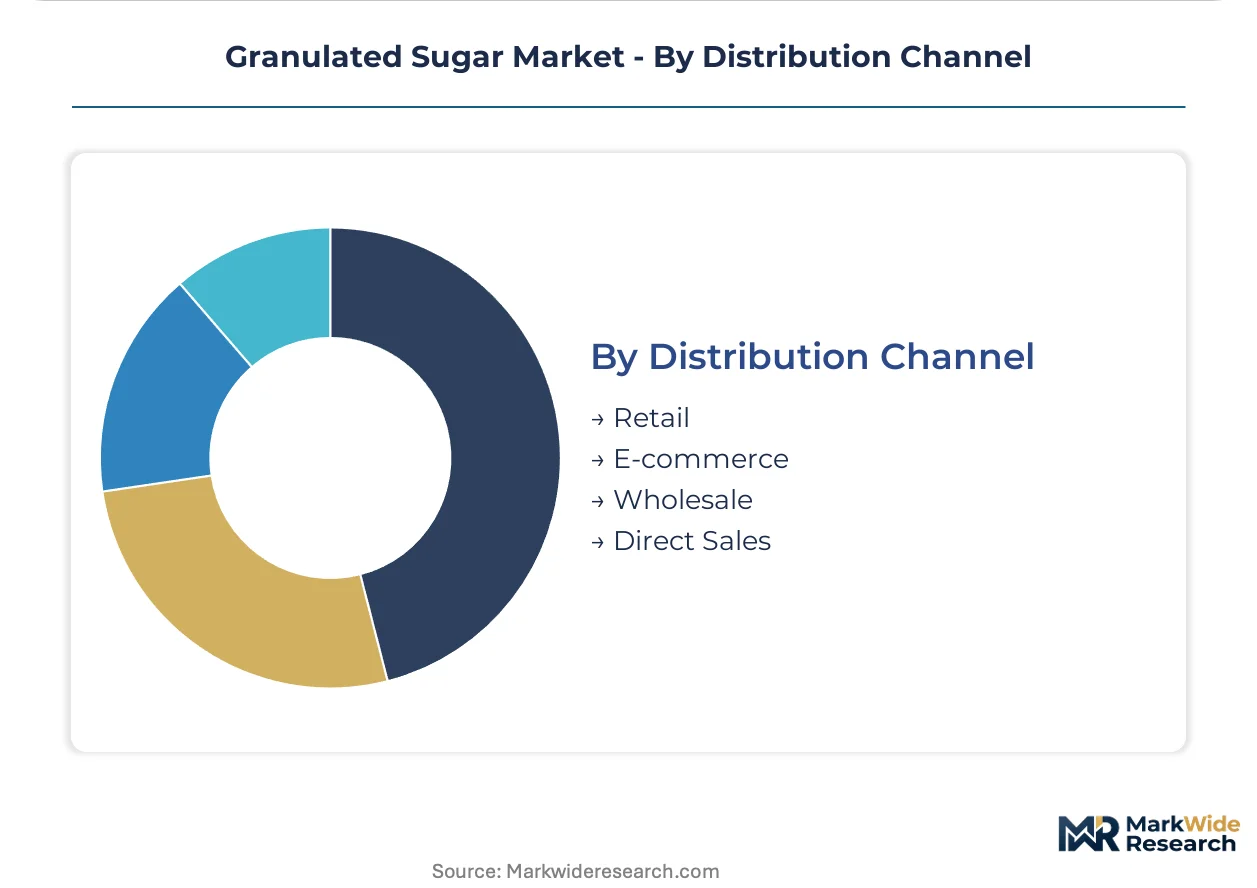
Channel control determines pricing transparency and customer relationship depth, with direct procurement eroding traditional commodity exchange intermediation.
- Retail:Supermarket and hypermarket shelf placement requires slotting fee investments and promotional calendar coordination. French and German retail cooperatives wield substantial buyer power.
- E-commerce:Direct-to-consumer and B2B platform sales of specialty and organic grades bypass traditional wholesale markups. Indian quick-commerce platforms are expanding packaged sugar delivery.
- Wholesale:Commodity brokers and trading houses aggregate spot and contract volumes for redistribution to smaller processors. Price discovery remains tied to ICE futures benchmarks.
- Direct Sales:Refiner-processor bilateral contracts exceeding fifty thousand metric tons annually now bypass commodity exchanges. This concentration is most visible in Mexico and Colombia.
Direct Sales anchor volume commitments among multinationals, while E-commerce is climbing the fastest through platform infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Beverage manufacturers in Brazil and Thailand absorb price swings through ethanol-flex diversion, while European confectionery buyers face rigid reformulation costs under decarbonization mandates.
Brazil
São Paulo state mills crush record cane volumes as international sweetener premiums pull output from ethanol. ANVISA maintains food-grade sucrose purity standards that exceed regional benchmarks. Piracicaba and Ribeirão Preto host the densest mill clusters, where Raízen S.A. and Cosan operate integrated bioenergy complexes.
India
Uttar Pradesh and Maharashtra ethanol-blending mandates are redirecting molasses toward fuel rather than crystalline output. FSSAI labeling rules now require quantitative sugar disclosure on all packaged foods. Kolhapur and Muzaffarnagar mill belts are expanding crushing capacity under PLI scheme subsidies for integrated sugar-ethanol infrastructure.
Germany
Beet processors face natural gas cost volatility that compresses crystallization margins. REACH chemical registration tightens impurity thresholds for carbonatation lime and processing aids. Saxony-Anhalt and Lower Saxony growing regions concentrate Nordzucker AG and Südzucker AG refining assets with captive limestone quarrying.
Thailand
ASEAN beverage manufacturers source bulk refined sugar through long-term procurement contracts. Drought cycles in the Northeast region create raw cane supply vulnerability. Khon Kaen and Udon Thani provinces anchor Mitr Phol Sugar crushing operations with dedicated bulk container rail links to Laem Chabang port.
United States
Soft drink bottlers impose stringent ICUMSA color and dissolution specifications on domestic refiners. FDA added-sugar disclosure rules on Nutrition Facts panels accelerate reformulation timelines. Florida and Louisiana cane belts supply American Sugar Refining facilities, while Great Lakes beet regions serve Midwestern confectionery clusters.
Granulated Sugar Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on origin certification and channel control. Brazilian and European millers dominate volume flows through backward integration into cane and beet cultivation. Three archetypes define positioning: flex-capacity bioenergy integrators, cooperative-owned beet processors, and Asian trading-house aggregators. Competitive moves center on ethanol-sugar swing allocation and direct procurement contracts that bypass commodity exchanges.
Within the integrated bioenergy tier, Raízen S.A. and Cosan exemplify flex-capacity operators that optimize crush allocation between crystalline output and fuel ethanol. Südzucker AG anchors the European cooperative model with captive beet supply chains across Central European growing regions. Tereos S.A. occupies a position bridging cooperative ownership with multinational procurement reach into beverage manufacturing accounts.
| Leading Market Players |
|---|
| Raízen S.A. |
| American Sugar Refining |
| Südzucker AG |
| Nordzucker AG |
| Mitr Phol Sugar |
| Tereos S.A. |
| Wilmar International Ltd. |
| Associated British Foods |
| Cosan |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between São Paulo state mills and Coca-Cola FEMSA lock in both cane supply access and price visibility for crystalline sucrose volumes exceeding fifty thousand metric tons annually. These bilateral arrangements bypass ICE futures benchmarks and compress working capital requirements for integrated bioenergy operators.
Pricing Analysis
After-sales service contracts for technical assistance on crystallization automation systems drive lifetime value for European beet processor relationships. Three-tier pricing structure across organic certification, standard ICUMSA grades, and bulk commodity separates premium Paraguayan cooperatives from São Paulo flex-capacity mills. Cost compression in standard white sugar is intensifying because natural gas price spikes inflate thermal energy expenses at German refineries. Beverage manufacturers exhibit lowest price sensitivity due to formulation lock-in, while artisanal bakeries show highest sensitivity to brown sugar premiums.
Supply Chain Analysis
Inventory lead times stretch across crushing seasons as Brazilian mills divert cane toward ethanol when biofuel returns exceed crystalline premiums. Supply concentrates in Brazil, Thailand, and India for raw cane, while Germany and France anchor beet processing. Raw material dependencies include cane crush volumes, natural gas for crystallization thermal energy, and carbonatation lime quality. Single-source vulnerability concentrates in Thailand's drought-prone Northeast region. Distribution runs through direct refiner-processor bilateral contracts for multinationals and commodity brokers for smaller ASEAN processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping procurement as digital traceability systems create interoperability between cane field sensors and beverage manufacturer quality certification portals. This ecosystem shift compresses supplier qualification timelines and favors refiners with integrated logistics assets.
For Market Incumbents: Shield margin capture by deepening backward integration into captive limestone quarrying for REACH-compliant carbonatation lime supply. Secure multi-year direct procurement contracts with consolidated beverage rosters before digital traceability mandates harden qualification barriers. Natural gas price volatility remains the primary threat to European beet processor competitiveness. For New Entrants and Emerging Players: Lead with certified organic sugar offerings targeting EU Green Deal compliance requirements where incumbent cooperatives lack surplus capacity. Nigeria's packaged food sector presents the most penetrable geography given dependence on imported refined sugar despite rising Kano state domestic cultivation. Direct-to-bakery distribution networks in Mexico's artisanal bread sector offer a proven go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward flex-capacity bioenergy integrators with ethanol-sugar swing allocation capability across São Paulo state mill clusters. Long-term viability over the coming decade hinges on positioning for clean-label confectionery mandates and carbon certification premiums. Watch for FSSAI labeling norm enforcement intensity as the inflection indicator for reformulation-driven demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Ethanol-Sugar Flex Capacity Expansion | Enables Raízen S.A. and Cosan to optimize crush allocation between crystalline output and biofuel returns based on real-time premium spreads. |
| Captive Limestone Quarrying Integration | Allows Südzucker AG and Nordzucker AG to secure REACH-compliant carbonatation lime supply and protect downstream food safety credentials. |
| Direct-to-Bakery Distribution Networks | Bypasses traditional commodity brokers in Mexico's artisanal bread sector and captures premium positioning for brown sugar variants. |
| Digital Traceability Platform Deployment | Compresses supplier qualification timelines for Coca-Cola FEMSA and Postobón while enabling real-time ICUMSA certification. |
| Integrated Sugar-Ethanol Complex Subsidies | India's PLI scheme for Uttar Pradesh and Maharashtra infrastructure redirects molasses toward fuel blending mandates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with sugar mill operations directors, beverage procurement leads, and carbonatation equipment engineers; and secondary validation through customs/trade data, ANVISA food-grade standards documentation, and FSSAI regulatory filings. Bottom-up triangulation across crush volume reports and top-down reconciliation against ethanol-swing allocation models anchored volume estimates. Primary fieldwork concentrated on São Paulo state mill clusters and Saxony-Anhalt beet processing facilities.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning crystalline purity grades, end-use verticals from beverage manufacturing to artisanal bakery, packaging formats from bulk containers to retail pouches, and distribution channel structures. CAGRs were derived from crush capacity expansion trajectories and ethanol-blending mandate intensities. Forecast inputs incorporated natural gas price volatility assumptions for European thermal energy costs and drought cycle probabilities for Thai Northeast region cane supply.
Underlying assumptions cover climate volatility patterns and regulatory enforcement timelines, with deviation risk concentrated in FSSAI labeling norm implementation pace and EU Green Deal decarbonization benchmark stringency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Nutritive Sweeteners Market
Sweeteners
Indonesia Food Sweetener Market
Sweeteners
Low-Calorie Sweetener Market
Sweeteners
Sugar Substitutes Market
Sweeteners
Polyol Sweeteners Market
Sweeteners
Stevia Mints Market
Sweeteners
Brown Rice Syrup Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
Raw Beetroot Sugar Market
Sweeteners
Sweeteners Market
Sweeteners
Asia-Pacific Low-Calorie Sweeteners Market
Sweeteners
Europe Stevia Market
Sweeteners
Australia Allulose Market
Sweeteners
Sugar-Free Syrups Market
Sweeteners
Rice Syrup Market
Sweeteners
Intensive Sweeteners Market