
 Rice Syrup Market | 2026-2036
Rice Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Rice Syrup Market Analysis
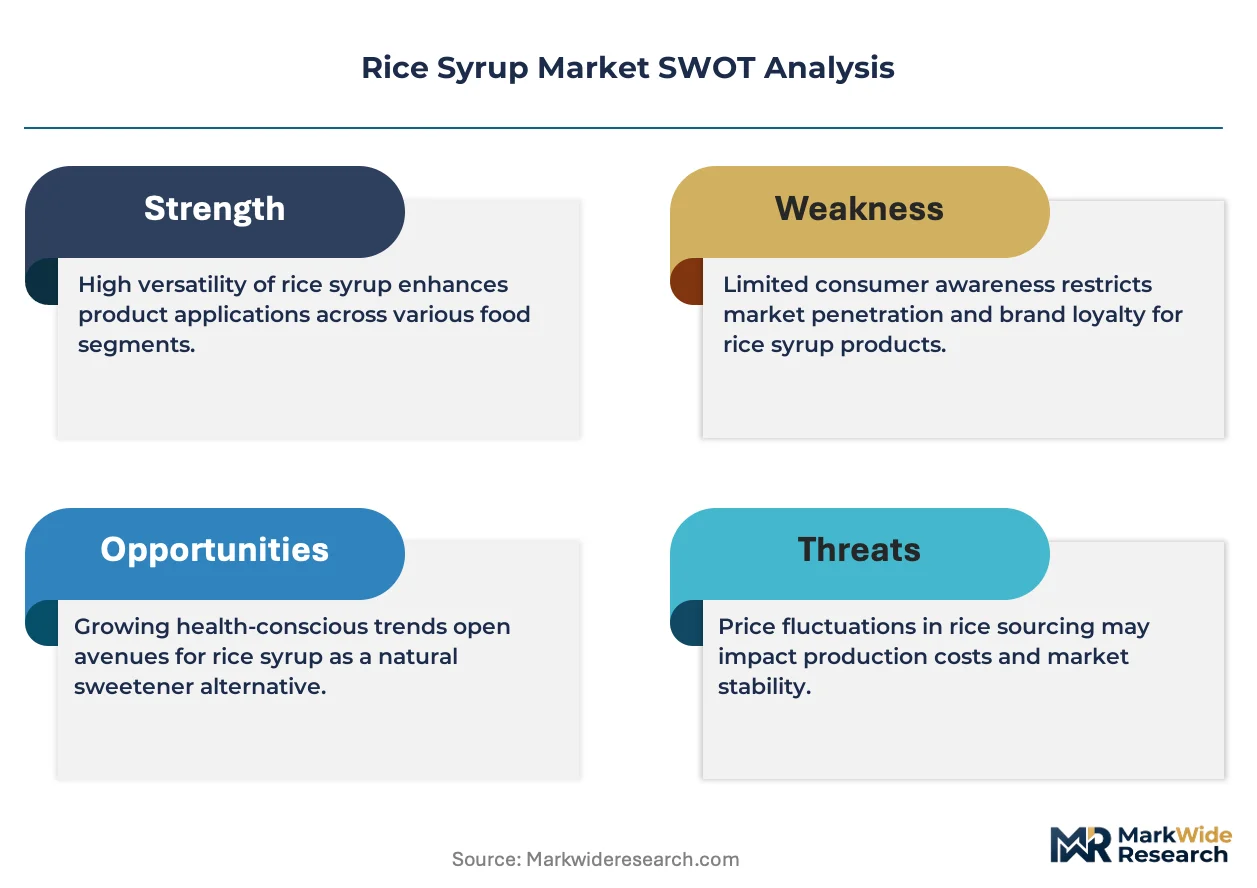
Maltodextrin is repositioning as a cost-competitive alternative in certain beverage applications, yet rice syrup retains advantage in clean-label positioning. Cargill, Incorporated leverages its global grain procurement network to sustain cost-advantaged feedstock access. Axiom Foods Inc. specializes in organic-certified rice syrup, occupying a premium niche among health-focused formulators. Tate & Lyle PLC competes through its heritage in specialty sweeteners, extending technical service capabilities to bakery customers.
Rice syrup is a liquid sweetener produced by enzymatic hydrolysis of rice starch, typically containing glucose, maltose, and higher saccharides with dextrose equivalent values ranging from 20 to 70 DE. The hydrolysis process employs alpha-amylase and glucoamylase enzymes to break down starch polymers into fermentable sugars, yielding a viscous, light-colored syrup used primarily as a bulking agent, humectant, and sweetness modulator in processed foods. Organic rice syrup commands margin premiums due to certification complexity and limited supplier pools, while brown rice syrup captures demand from whole-grain positioning in health food stores. The food and beverage industry anchors volume consumption, though bakery manufacturers represent the fastest-growing end-user channel as clean-label reformulation accelerates.
The FDA governs rice syrup labeling under its sweetener and GRAS notification frameworks, while USDA organic certification shapes premium product access. In Europe, EFSA evaluates novel sweetener claims and REACH compliance affects processing chemical registrations. India's FSSAI mandates additive specifications for imported rice syrup, influencing export market entry. Stakeholders must monitor evolving sugar-reduction targets and enzyme technology advances that could alter production economics.
Market Dynamics
Clean-label reformulation in European confectionery manufacturing is compressing switching timelines for high-fructose corn syrup replacement, with Hamburg and Cologne bakery clusters now mandating documented supply chain transparency from enzyme suppliers through finished goods.
Growth Catalysts
- EU F-Gas Regulation:Mandates for lower-GWP processing agents are accelerating capital deployment into enzymatic hydrolysis systems that reduce thermal energy intensity in rice starch conversion.
- Confectionery clean-label mandates:Major retail chains in Germany now require non-GMO sweetener documentation, pulling brown rice syrup into premium chocolate and licorice formulations.
- Enzyme immobilization technology:Fixed-bed glucoamylase systems are cutting conversion cycle times by half while improving dextrose equivalent consistency for industrial bakers.
Market Restraints
- Organic rice supply concentration:Certified organic paddy availability clusters in specific Thai and Vietnamese growing regions, exposing processors to climate-driven harvest volatility.
- Maltodextrin cost advantage:Corn-derived bulking agents maintain price spreads that block rice syrup penetration in mass-market beverage applications.
- REACH compliance burden:ECHA registration requirements for processing aids create fixed cost barriers that disproportionately burden small-batch organic syrup producers.
Strategic Opportunities
- India FSSAI import specifications:Recent additive purity standards for imported rice syrup create first-mover advantage for exporters achieving dual organic-FSSAI certification.
- Precision fermentation convergence:Cell-culture enzyme production is unifying with traditional grain processing to yield custom dextrose equivalent profiles for functional beverage formulators.
- Direct-to-manufacturer channels:Bulk procurement platforms are bypassing traditional ingredient distributors in German bakery clusters, compressing margin capture for intermediaries.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous USDA organic, EU organic, and FSSAI approvals require 18-24 month validation cycles that freeze product launch schedules.
- Liquid syrup logistics reconfiguration:Tanker cleaning protocols for allergen-free transport demand dedicated fleet investment that mid-cap processors struggle to amortize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rice Syrup Market |
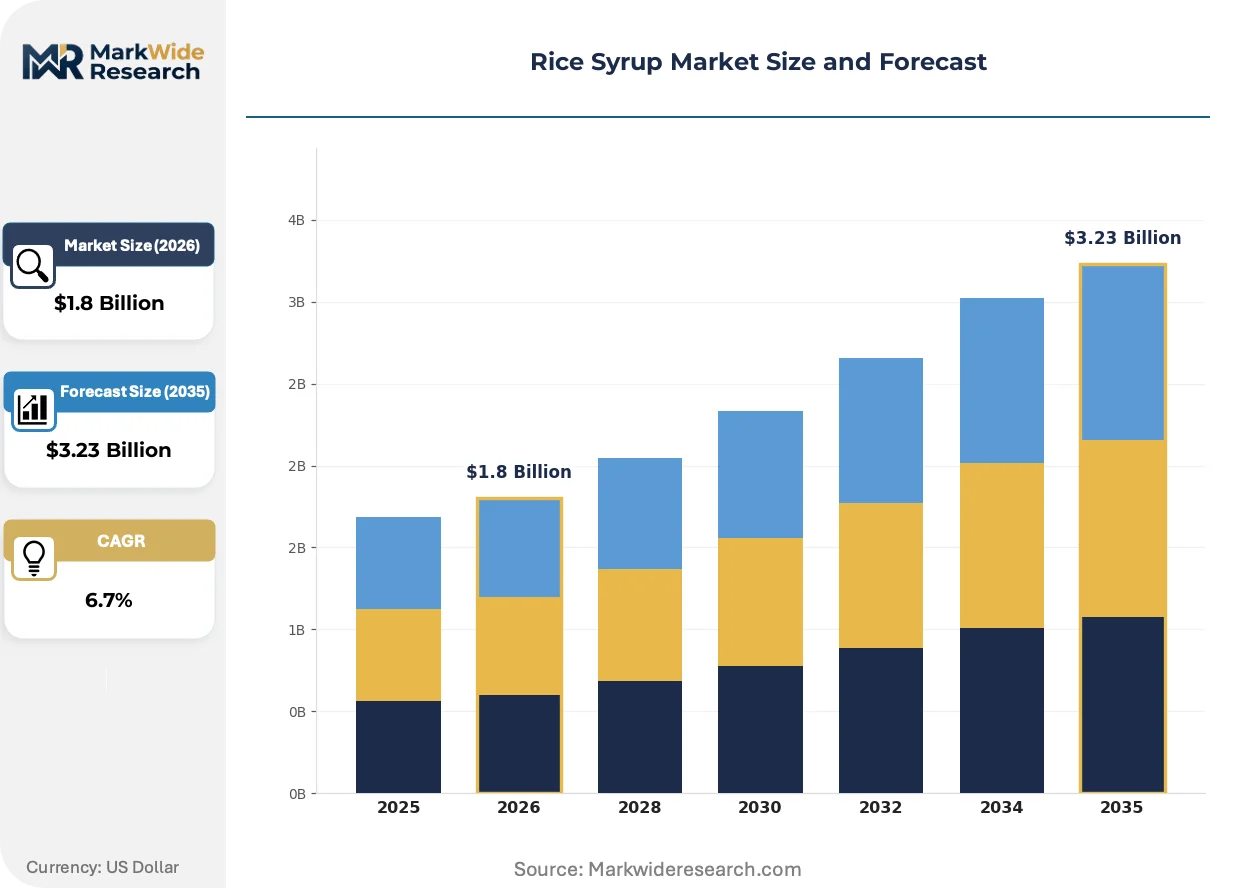
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Rice Syrup, Non-Organic Rice Syrup, Brown Rice Syrup, White Rice Syrup End User: Food & Beverage Industry, Bakery Manufacturers, Confectionery Producers, Health Food Stores Packaging Type: Bottles, Pouches, Drums, Tubs Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Axiom Foods Inc., Wuhu Deli Foods Co., Ltd., California Natural Products, Gulshan Polyols Ltd., Nature Bio-Foods Ltd., Pioneer Industries Private Limited, Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rice Syrup Market Emerging Trajectories
Enzymatic process intensification and regulatory chemistry substitution are compressing the technical gap between commodity and specialty rice syrup grades, while procurement digitization restructures how European formulators source liquid sweeteners.
Continuous-flow enzyme reactor technology is unifying hydrolysis and filtration stages into single-pass systems that slash water consumption and thermal input. German industrial bakeries in the Cologne cluster are piloting these units for 70 DE syrup production. The structural consequence is collapsing minimum efficient scale thresholds, enabling regional micro-mills to serve local confectionery producers.
REACH Annex XIV authorization requirements for legacy catalysts are forcing processors to substitute enzymatic pathways for acid hydrolysis in dextrose equivalent modification. ECHA's sunset date scheduling creates phased compliance windows that favor early adopters with validated alternative processes. Brown rice syrup manufacturers targeting EU organic certification face the tightest substitution timelines.
Spot-market purchasing through B2B ingredient platforms is displacing annual volume contracts among mid-sized European confectioners. Hamburg-based procurement teams now source rice syrup through auction mechanisms that expose price volatility previously absorbed by distributors. This behavioral shift concentrates volume with processors offering real-time inventory visibility and flexible dextrose equivalent specifications.
Rice Syrup Market Segmentation
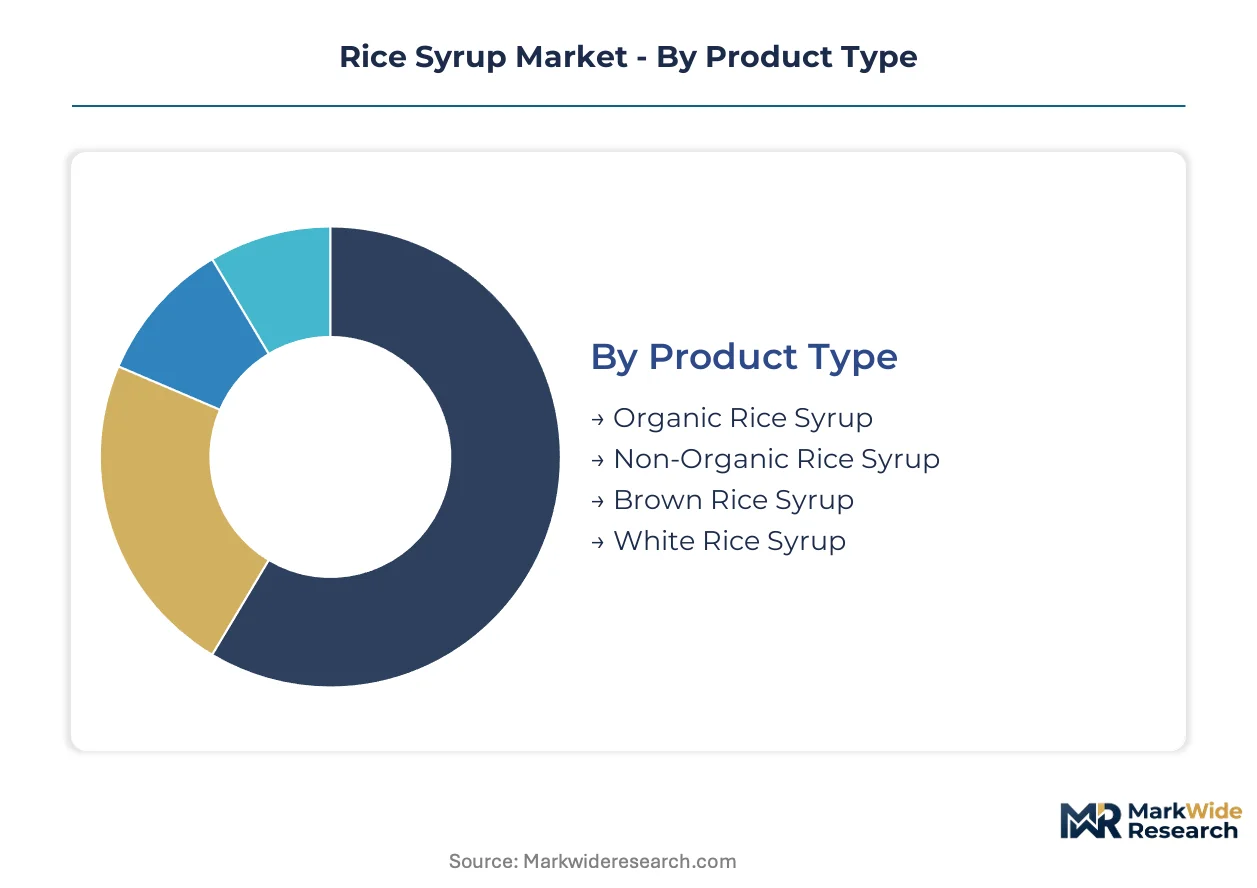
Rice syrup segmentation tracks how clean-label mandates and processing economics split demand across certification grades, end-use channels, and logistics formats. Manufacturers configure production lines around these divides to capture margin premiums or volume scale.
Product Type:
Upgrade cycles in rice syrup procurement follow certification complexity, with buyers trading up from conventional grades to organic-certified variants as supply chain documentation requirements tighten.
- Organic Rice Syrup:Enzymatic hydrolysis of certified organic rice starch yields dextrose equivalent values from 20 to 70 DE with full traceability documentation. German confectionery clusters in Hamburg and Cologne now mandate organic certification for premium chocolate formulations, pulling supply toward Thai and Vietnamese certified paddy sources. REACH Annex XIV compliance for processing aids adds fixed validation costs that concentrate production among scaled processors.
- Brown Rice Syrup:Whole-grain rice processing retains bran layer nutrients, producing darker color and stronger flavor profiles preferred in health food positioning. Health food stores in North American markets stock brown rice syrup as a mineral-rich alternative to refined sweeteners, though color constraints limit penetration in light-colored bakery applications. FSSAI import specifications in India create dual-certification hurdles for exporters targeting this grade.
- Non-Organic Rice Syrup:Conventional rice starch conversion serves cost-sensitive beverage and mass-market bakery applications where clean-label positioning is secondary to price.
- White Rice Syrup:Refined starch base delivers neutral flavor and light color for confectionery applications requiring visual clarity and minimal aftertaste.
Non-Organic Rice Syrup sits at the top of the volume ranking, with Organic Rice Syrup climbing the fastest.
End User:
Cost tier differentiation separates commodity-scale buyers from premium formulators willing to absorb certification premiums for supply chain transparency.
- Bakery Manufacturers:Industrial bakers in the Cologne cluster pilot continuous-flow enzyme reactors for 70 DE syrup production, collapsing minimum efficient scale thresholds. Real-time inventory visibility and flexible dextrose equivalent specifications now determine supplier selection as procurement digitization accelerates.
- Confectionery Producers:Premium chocolate and licorice manufacturers in Germany require non-GMO sweetener documentation, mandating verified enzyme sources through finished goods. EU F-Gas Regulation compliance for processing agents adds capital intensity that favors early adopters with validated enzymatic pathways.
- Food & Beverage Industry:Mass-market beverage formulators face maltodextrin cost competition that blocks rice syrup penetration in price-sensitive applications.
- Health Food Stores:Specialty retail channels stock brown rice syrup for whole-grain positioning, though volume remains constrained by premium pricing and limited distribution reach.
Food & Beverage Industry holds the largest volume position, while Bakery Manufacturers are expanding most quickly.
Packaging Type:
Application requirements and logistics economics shape format selection, with bulk industrial users diverging sharply from retail-channel configurations.
- Drums:Standard 200-liter steel and plastic drums dominate industrial bakery and confectionery procurement, enabling tanker-to-tanker transfer with minimal handling. Dedicated fleet investment for allergen-free transport protocols burdens mid-cap processors unable to amortize cleaning infrastructure across sufficient volume.
- Bottles:Retail-format glass and PET bottles serve health food store channels and direct-to-consumer online sales, with label real estate competing for organic certification marks and dextrose equivalent callouts.
- Pouches:Flexible film packaging gains traction in food service and small-batch artisan bakery segments for portion control and reduced shipping weight.
- Tubs:Rigid plastic containers target food service scoops and ingredient bench applications where resealability matters more than unit cost.
Drums command the highest shipment volume, with Pouches gaining share fastest in emerging channels.
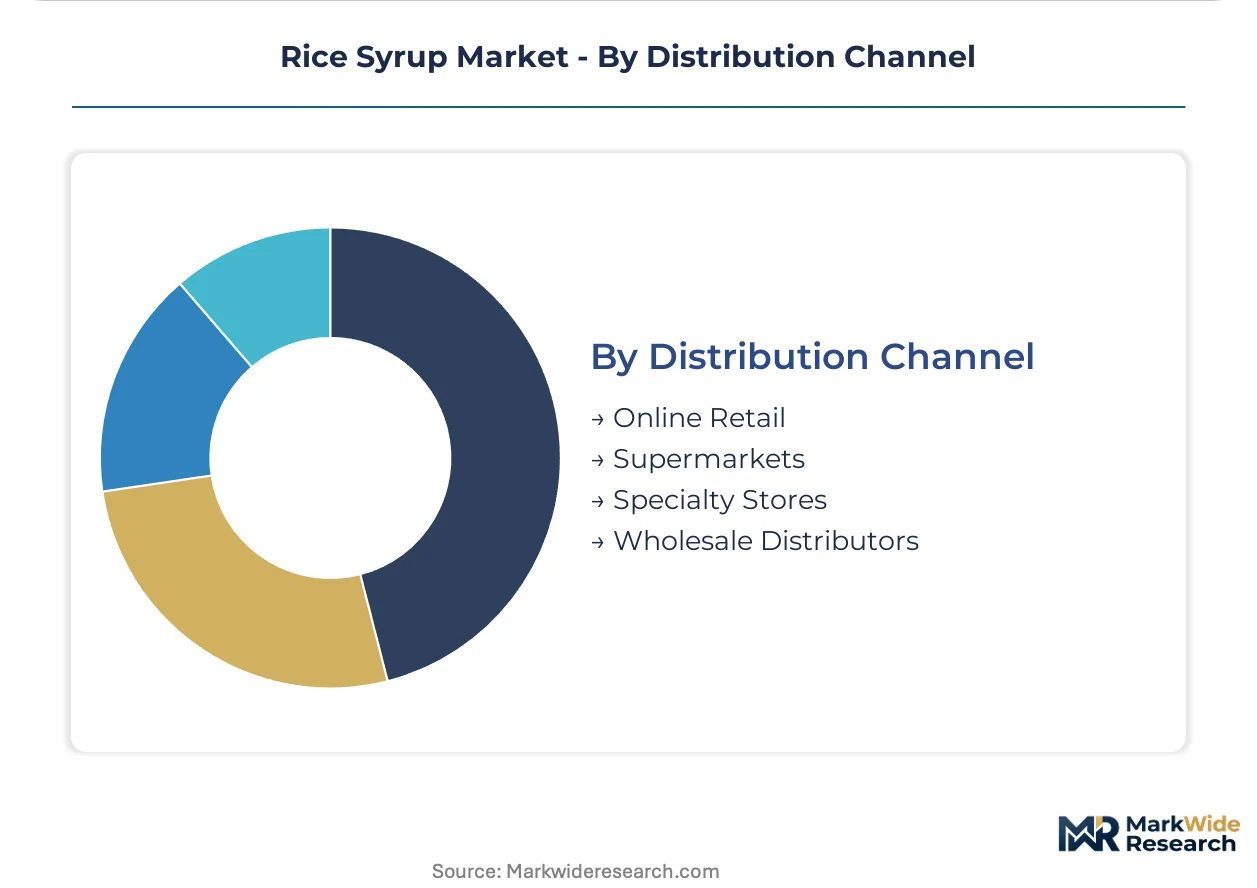
Distribution Channel:
Customer type fragmentation between industrial procurement teams and retail buyers creates parallel channel structures with diverging service requirements.
- Wholesale Distributors:Traditional ingredient distributors absorb price volatility through annual volume contracts, though their margin capture compresses as direct-to-manufacturer platforms expand. Technical service capabilities and dextrose equivalent customization retain value for complex bakery formulations.
- Online Retail:B2B ingredient platforms enable spot-market purchasing and auction mechanisms that expose mid-sized European confectioners to real-time price discovery. Inventory visibility systems and flexible specification management determine platform selection.
- Supermarkets:Mass retail channels stock consumer-format rice syrup for home baking and natural foods positioning, competing with agave and maple syrup alternatives.
- Specialty Stores:Health food and organic-focused retailers curate brown rice syrup SKUs for clean-label shoppers, with certification storytelling driving shelf placement.
Wholesale Distributors maintain volume leadership, with Online Retail showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cologne and Hamburg bakery clusters anchor demand concentration for rice syrup in Europe, with enzymatic hydrolysis capacity expanding to meet clean-label procurement mandates from industrial confectioners.
Germany
Industrial bakers in Cologne pilot continuous-flow enzyme reactors for 70 DE syrup production, while Hamburg confectionery clusters mandate non-GMO sweetener documentation. The EU F-Gas Regulation accelerates capital deployment into lower-GWP processing systems. REACH Annex XIV compliance timelines favor early adopters with validated enzymatic pathways.
United States
Health food stores in coastal metros stock brown rice syrup for whole-grain positioning, while mass-market beverage formulators face maltodextrin cost competition. FDA GRAS notification frameworks govern sweetener labeling. California natural products manufacturers drive organic-certified procurement.
India
FSSAI import specifications for additive purity create dual-certification hurdles for exporters targeting conventional syrup grades. Domestic bakery manufacturers in Maharashtra and Gujarat represent emerging demand channels. The FSSAI mandates additive specifications that influence export market entry protocols.
Thailand
Certified organic paddy availability clusters in specific growing regions, exposing processors to climate-driven harvest volatility. Thai processors supply German confectionery clusters with organic-certified feedstock. The country's agricultural extension programs support organic certification uptake among smallholder rice farmers.
Vietnam
Mekong Delta rice processors export conventional syrup grades to mass-market beverage formulators across Asia-Pacific. Organic certification infrastructure remains less developed than Thai counterparts. Vietnamese exporters target FSSAI-compliant production for Indian market access.
Rice Syrup Market Vendor Landscape
Global majors compete with regional champions across enzymatic processing technology and certification complexity. The vendor base splits between diversified grain processors and specialty organic suppliers. Three archetypes dominate: integrated agribusiness conglomerates with captive starch supply, mid-cap organic specialists with certification depth, and Asian contract manufacturers with cost-positioned conventional grades. Capacity expansion and strategic partnerships represent the dominant competitive moves.
Within the integrated agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify global scale advantages in grain procurement networks. Tate & Lyle PLC occupies a heritage position in specialty sweeteners with technical service capabilities. Among organic specialists, Axiom Foods Inc. represents premium-niche positioning for health-focused formulators. These three anchors illustrate how certification depth, geographic footprint, and customer segment focus stratify competitive positioning.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Axiom Foods Inc. |
| Wuhu Deli Foods Co., Ltd. |
| California Natural Products |
| Gulshan Polyols Ltd. |
| Nature Bio-Foods Ltd. |
| Pioneer Industries Private Limited |
| Tate & Lyle PLC |
| Others |
Supply Flow & Price Mechanics
Thai organic paddy benchmark prices cascade through enzymatic hydrolysis costs into three-tier pricing structure across premium, standard, and economy levels. REACH Annex XIV compliance burdens and FSSAI dual-certification requirements concentrate margin capture among scaled processors with validated alternative pathways.
Pricing Analysis
Input-cost pass-through from certified organic rice starch and immobilized enzyme systems stratifies rice syrup pricing across certification grades. Price differentiation hinges on USDA organic documentation depth and dextrose equivalent customization flexibility. Cost compression in conventional grades is intensifying because maltodextrin maintains price spreads in mass-market beverage applications. Mass-market beverage formulators exhibit highest price sensitivity, while German confectionery clusters absorb certification premiums for supply chain transparency.
Supply Chain Analysis
Organic rice syrup supply rests on certified paddy availability clustering in Thailand and Vietnam, with conventional grades sourcing from Mekong Delta processors. Key inputs include alpha-amylase and glucoamylase enzymes, filtration membranes, and stainless steel reactor vessels. Single-source vulnerability concentrates in Thai organic certification infrastructure exposed to climate-driven harvest volatility. Distribution runs through wholesale distributors for industrial bakery and confectionery procurement, though B2B platforms are displacing annual volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU F-Gas Regulation compliance costs in Europe and lower processing intensity in Southeast Asian export hubs.
For Market Incumbents: Deploy enzyme immobilization technology to halve conversion cycle times and defend against precision fermentation convergence threatening traditional grain processing economics. Backward integration into certified organic paddy procurement in Thailand reduces climate-driven harvest volatility exposure. Capacity addition in Cologne cluster continuous-flow reactor installations captures German bakery demand for 70 DE syrup with real-time inventory visibility. For New Entrants and Emerging Players: FSSAI import specifications in India open a window for dual organic-FSSAI certification first-movers in brown rice syrup grades. White-space targets include Maharashtra and Gujarat domestic bakery manufacturers and precision fermentation-enabled custom dextrose equivalent profiles for functional beverage formulators. Direct-to-manufacturer platform participation bypasses distributor margin capture in Hamburg procurement clusters. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap organic specialists with 18-24 month multi-jurisdiction certification validation cycles already completed. Long-term viability centers on processors with dedicated allergen-free tanker fleet infrastructure amortizable across sufficient volume. Watch for enzyme technology advances altering production economics as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Paddy | Captive supply from Thai certified growing regions reduces climate volatility exposure. |
| Continuous-Flow Reactor Deployment | Cologne cluster pilots slash water consumption and thermal input for 70 DE production. |
| Dual Certification Investment | Simultaneous USDA organic and FSSAI approval unlocks Indian import channel access. |
| B2B Platform Channel Expansion | Real-time inventory visibility systems displace traditional distributor annual contracts. |
| Precision Fermentation Partnership | Cell-culture enzyme production yields custom dextrose equivalent profiles for beverage formulators. |
Methodological Framework
Direct dialogue with plant managers at enzymatic processing facilities, procurement leads at German bakery and confectionery clusters, organic certification auditors, and distribution channel partners grounds qualitative findings. Secondary validation draws from customs and trade data, FSSAI additive specifications, ECHA REACH Annex XIV sunset schedules, and SEC 10-K filings of diversified grain processors. Bottom-up volume modeling from individual facility capacities and top-down demand segmentation from end-use consumption patterns triangulate market sizing.
Segmented outputs across certification grade, dextrose equivalent tier, end-use channel, and regional production hub feed into growth derivation across the analysis window. CAGRs emerge from fitted trend analysis against historical consumption patterns and projected clean-label reformulation penetration. Industry-specific inputs include enzyme technology adoption curves, EU F-Gas Regulation capital deployment timelines, and organic paddy harvest volatility indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH processing aid substitution deadlines or severe Mekong Delta climate disruptions. Projections reflect assumptions on clean-label mandate enforcement intensity and maltodextrin price spread stability. A small set of triggers—ECHA authorization acceleration, FSSAI specification expansion, precision fermentation cost parity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Tapioca Maltodextrin Market
Sweeteners
Floral Nectar Market
Sweeteners
Global Cane Molasses Market
Sweeteners
North America Food Sweetener Market
Sweeteners
Australia Food Sweetener Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
United States Food Sweetener Market
Sweeteners
North America Stevia Market
Sweeteners
Global Stevia Sugar Blends Market
Sweeteners
Maltitol Market
Sweeteners
Natural Stevia Market
Sweeteners
Global Alternative Sweeteners Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Monk Fruit Sweetener Market
Sweeteners
Allulose Powder Market
Sweeteners
Dry Sweeteners Market