
 Global Stevia Sugar Blends Market | 2026-2036
Global Stevia Sugar Blends Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stevia Sugar Blends Market Outlook
Specialty store distribution is fragmenting as direct-to-manufacturer channels capture bulk procurement volumes. Cargill leverages its integrated supply chain from stevia leaf sourcing to finished blend formulation. Tate & Lyle sustains competitive pressure through proprietary taste-modulation technologies that mask bitter aftertastes. Ingredion anchors its position in beverage sector partnerships with North American and Latin American bottlers.
Stevia sugar blends combine high-purity steviol glycosides extracted from Stevia rebaudiana leaves with conventional caloric sweeteners or bulking agents, typically achieving 50-90% sugar reduction while preserving functional properties in thermal processing. Powder formats lead volume demand due to superior shelf stability and ease of scaling in industrial batch production. Liquid concentrates represent the fastest-expanding category as ready-to-drink beverage manufacturers seek pumpable dosing systems. Bakery applications concentrate margin pools where heat-stable glycoside formulations command technical premiums over standard grades.
The U.S. FDA maintains GRAS oversight for steviol glycoside specifications, while the EMA and EFSA govern novel food approvals across European jurisdictions. China's NMPA and SAMR enforce GB standards for food additive purity thresholds that directly determine import eligibility. India's FSSAI stevia notification requirements shape local formulation strategies for multinational suppliers. Stakeholders must monitor evolving purity benchmarks and regional maximum-use levels as these determine both product registration timelines and reformulation costs.
Market Dynamics
Beverage manufacturers are driving procurement consolidation toward direct supplier relationships, compressing distributor margins while elevating technical specification requirements for heat-stable glycoside formulations. This structural shift favors suppliers with captive extraction capabilities and proprietary taste-modulation intellectual property.
Growth Catalysts
- GRAS Pathway Acceleration:The U.S. FDA's streamlined notification process for novel steviol glycosides reduces commercialization timelines for new sweetening compounds. Food and beverage formulators exploit this regulatory efficiency to launch reduced-calorie product lines faster.
- Clean-Label Sugar Reduction:Consumer packaged goods manufacturers across beverage and dairy verticals specify stevia blends to achieve 50-90% caloric reduction without artificial sweetener declarations. Retail shelf positioning rewards these formulations with premium placement.
- Extraction Technology Maturation:Membrane filtration and chromatographic purification methods now yield Reb M and Reb D glycosides at commercial scale. These rare glycosides deliver superior taste profiles that expand addressable applications into baking and confectionery.
Market Restraints
- Leaf Supply Geographic Concentration:Stevia rebaudiana cultivation concentrates in China and Paraguay, exposing processors to climate volatility and agricultural input cost swings. Sourcing diversification remains limited by agronomic adaptation requirements.
- Bitter Aftertaste Technical Ceiling:Standard Reb A formulations exhibit lingering bitterness above 300 ppm equivalent sweetness, constraining high-intensity applications. Taste-modulation additives add formulation complexity and cost.
- Maximum-Use-Level Variability:China's SAMR enforces stricter GB 2760 additive limits than FDA GRAS determinations, forcing multinational suppliers to maintain multiple specification tiers. Regulatory fragmentation elevates compliance overhead.
Strategic Opportunities
- Bakery Heat-Stability Premium:Thermal degradation-resistant glycoside formulations command technical premiums in industrial bread and cake manufacturing. Current penetration remains below 15% of addressable volume.
- Liquid Concentrate Pump Systems:Ready-to-drink beverage bottlers seek pumpable dosing formats that eliminate powder handling and improve batch consistency. Equipment retrofits create switching costs and supplier stickiness.
- EU Novel Food Expansion:EFSA's evolving steviol glycoside specifications under Regulation (EU) 2015/2283 open pathways for expanded use in dairy alternatives. Early registrants capture shelf-space advantages.
Industry Challenges
- Sensory Scientist Scarcity:Formulation teams require rare expertise in glycoside synergies and bulking agent interactions. Talent competition intensifies as CPG manufacturers build in-house capability.
- Batch-to-Batch Glycoside Variability:Agricultural stevia leaf exhibits natural Reb A content swings of 8-12%, forcing processors to maintain buffer inventories. Quality assurance protocols strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stevia Sugar Blends Market |
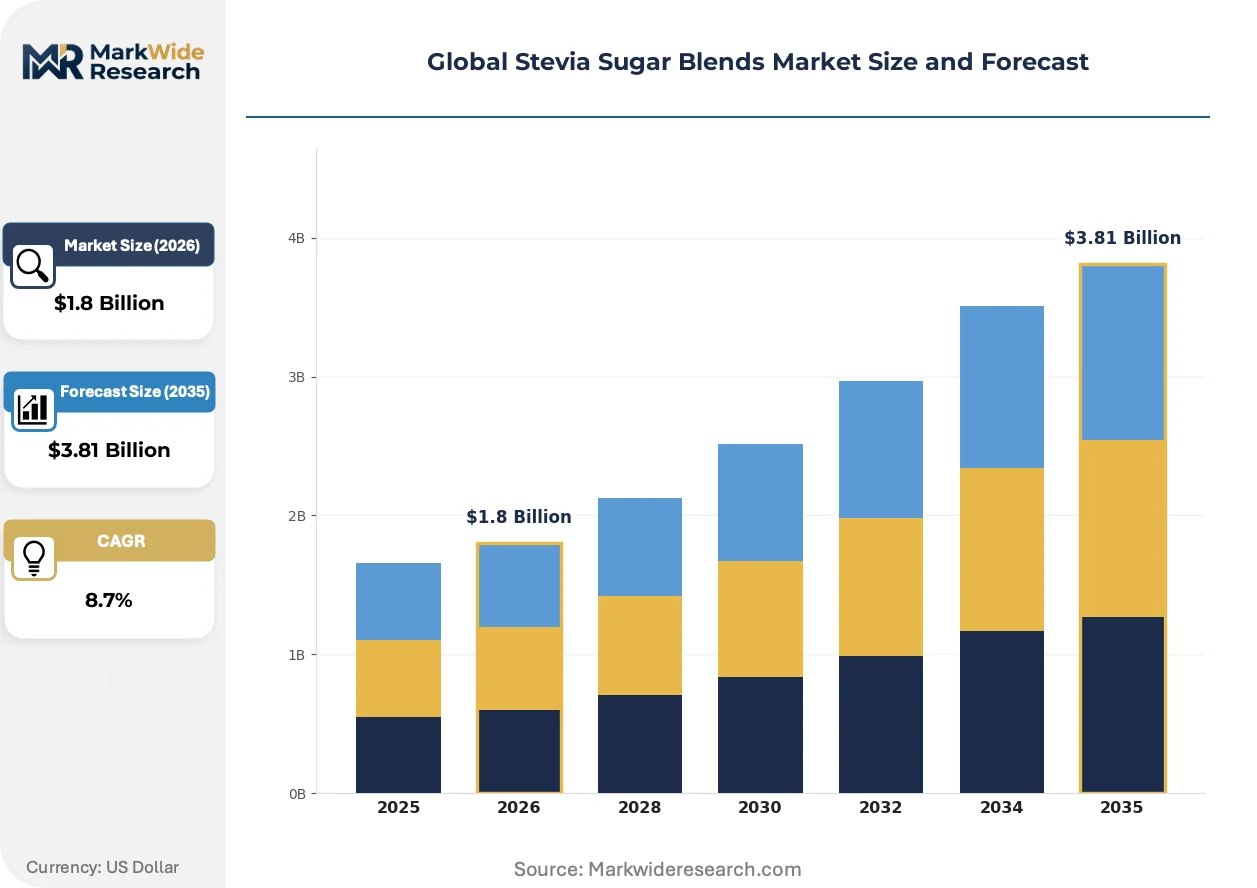
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Tablet End User: Food Manufacturers, Beverage Companies, Bakery Products, Dietary Supplements Application: Food Additive, Sweetener, Flavor Enhancer, Baking Ingredient Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Cargill, Tate & Lyle, Ingredion, PureCircle, Archer Daniels Midland, GLG Life Tech, Sunwin Stevia International, Pyure Brands, Stevia First, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stevia Sugar Blends Market Strategic Shifts
Bioconversion fermentation is displacing agricultural extraction as the dominant production paradigm, while regulatory harmonization efforts and procurement centralization reshape competitive requirements across formulation supply chains.
Precision fermentation platforms utilizing engineered yeast strains now produce Reb M and Reb D steviol glycosides without agricultural cultivation. Ingredient suppliers including Cargill and Tate & Lyle have scaled these bioprocesses to commercial volumes. This biotechnology is rendering obsolete traditional leaf-extraction capacity investments in regions with high land and labor costs.
China's SAMR revised GB 2760-2024 food additive standards to expand permitted steviol glycoside categories and align purity benchmarks with Codex Alimentarius guidelines. Domestic manufacturers gain export qualification advantages while importers face recertification timelines. The regulatory convergence most affects European and North American suppliers seeking unified specification tiers.
Beverage bottlers are consolidating sweetener procurement through direct manufacturer agreements that bypass traditional ingredient distributors. North American and Latin American bottlers now specify technical service packages including on-site formulation support and sensory validation. This channel compression squeezes distributor margins while rewarding suppliers with integrated application laboratories.
Global Stevia Sugar Blends Market Segmentation
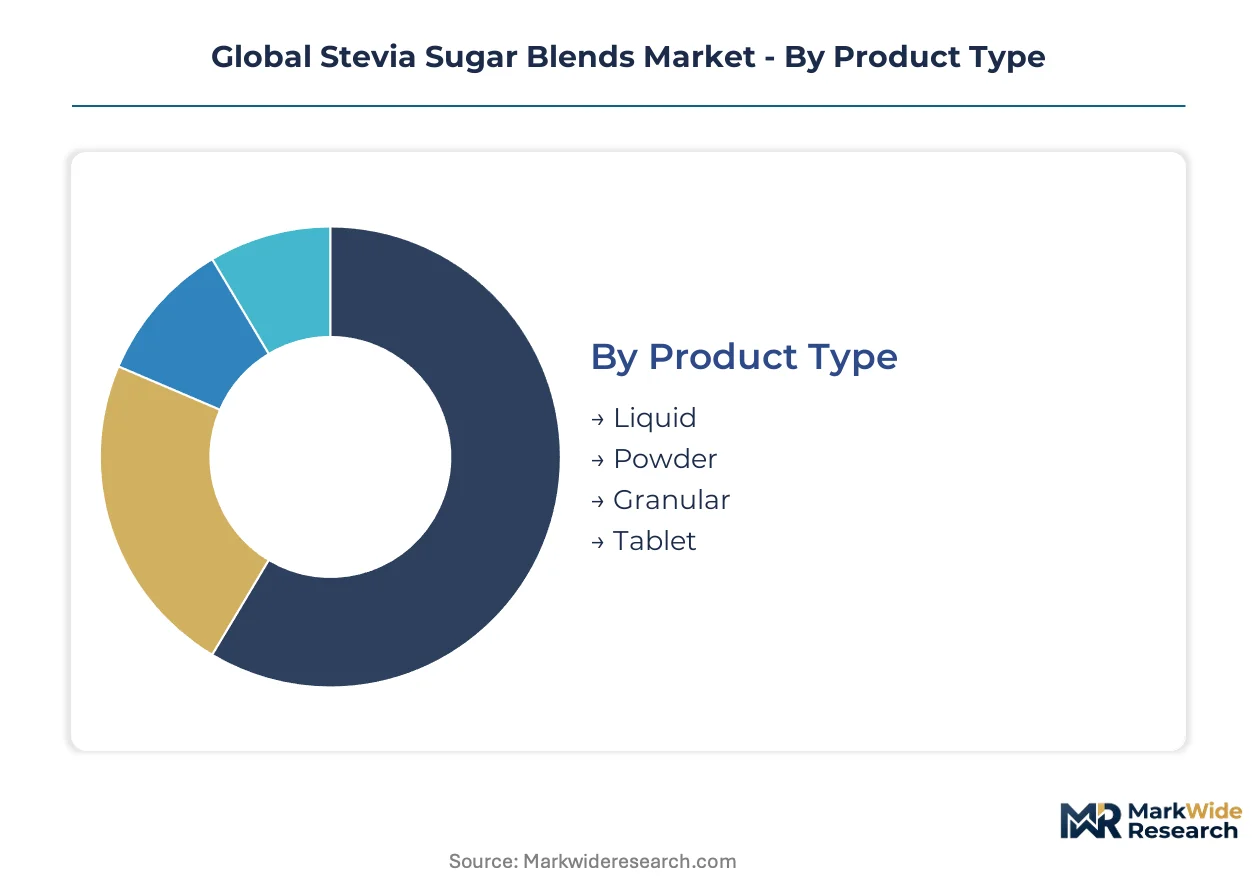
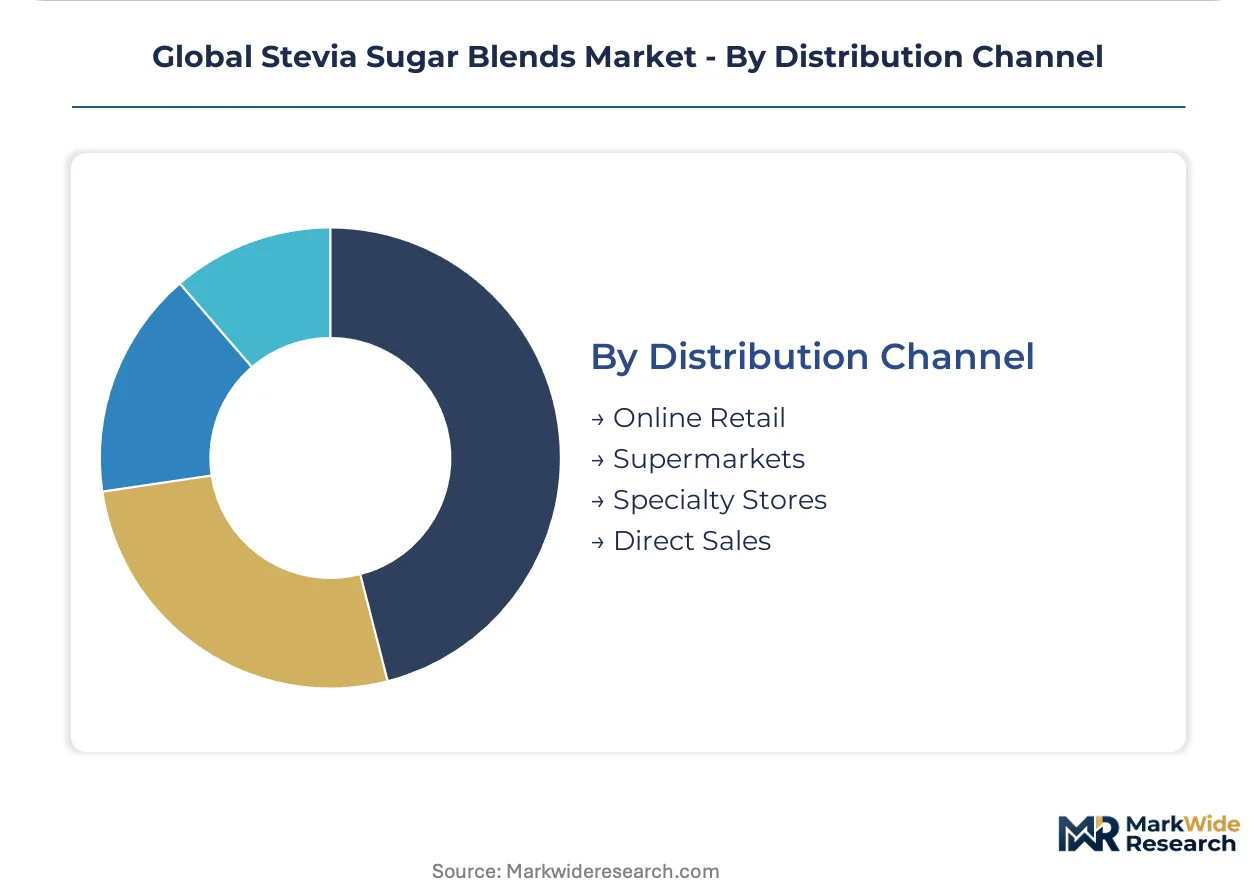
Segmentation in stevia sugar blends reflects divergent technical requirements across formulation formats and procurement channels. Powder and liquid variants serve distinct manufacturing infrastructures, while direct sales channels are displacing traditional distribution for bulk volumes.
Product Type:
Physical format determines handling protocols, shelf stability, and dosing precision in industrial settings.
- Powder:Free-flowing blends of steviol glycosides with maltodextrin or erythritol carriers achieve 50-90% sugar reduction in dry mixes. Food manufacturers in China and India specify powder for industrial batch scaling and extended ambient storage.
- Liquid:Pumpable concentrates dissolve instantly in aqueous systems, eliminating dust exposure and improving batch consistency. Beverage bottlers across Brazil and Mexico are retrofitting dosing equipment to capture these operational advantages.
- Granular:Crystalline textures mimic sucrose pourability for tabletop and small-format foodservice applications.
- Tablet:Compressed single-serve units target portability requirements in dietary supplement and foodservice segments.
Powder commands the established base. The steepest expansion runs through liquid concentrates.
End User:
Customer type shapes specification intensity, with beverage and bakery sectors driving divergent purity and thermal stability requirements.
- Beverage Companies:Ready-to-drink and concentrate formulators require heat-stable Reb M and Reb D glycosides that withstand pasteurization without degradation. Direct procurement agreements with extraction technology owners are compressing traditional ingredient distributor margins.
- Food Manufacturers:CPG producers across dairy, sauces, and condiments specify stevia blends for clean-label sugar reduction. China's SAMR GB 2760-2024 compliance requirements filter supplier qualification pools.
- Bakery Products:Industrial bread and cake manufacturing demands thermal degradation-resistant formulations that maintain sweetness through oven temperatures exceeding 180°C.
- Dietary Supplements:Tablet and capsule producers prioritize high-purity Reb A with minimal excipient load for caloric transparency.
Beverage companies anchor volume demand. Bakery applications capture the fastest margin expansion.
Application:
Functional role in finished goods determines glycoside selection, regulatory pathway, and maximum-use thresholds.
- Sweetener:Primary caloric replacement function in reduced-sugar beverages and dairy, subject to FDA GRAS notification or EFSA novel food approval depending on jurisdiction.
- Food Additive:Processing aids and preservation adjuncts governed by Codex Alimentarius purity benchmarks and national implementing standards.
- Flavor Enhancer:Synergistic amplification of fruit, vanilla, and cocoa notes at sub-sweetening doses, expanding addressable use cases beyond sugar replacement.
- Baking Ingredient:Heat-stable glycoside formulations with bulking agents that replicate sucrose's structural contribution to crumb texture and moisture retention.
Sweetener applications dominate current formulation volumes. Flavor enhancer positioning is climbing the fastest as CPG marketers seek differentiation beyond caloric reduction claims.
Distribution Channel:
Channel structure is concentrating toward direct manufacturer relationships for bulk procurement, fragmenting traditional wholesale roles.
- Direct Sales:Supplier technical service teams embed with beverage and bakery R&D functions, providing formulation support and sensory validation. North American bottlers now require on-site application laboratories as a procurement precondition.
- Online Retail:E-procurement platforms serve mid-tier food manufacturers and regional bakery chains with standardized specification tiers and rapid sample fulfillment.
- Supermarkets:Mass retail channels move consumer tabletop formats and small-package baking blends, with private-label penetration intensifying price competition.
- Specialty Stores:Health food and organic retailers stock premium-positioned organic stevia blends, though volume share is eroding as mainstream channels expand natural sweetener assortments.
Direct sales channels capture the established procurement base. Online retail is expanding most quickly among mid-market manufacturers seeking supplier diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos in Brazil anchors South American stevia leaf exports, while Shanghai's Yangshan deep-water container terminal handles inbound glycoside shipments for Asia-Pacific formulation plants. These maritime corridors determine regional cost structures and inventory cycles.
United States
Beverage bottlers in Atlanta and Chicago drive procurement consolidation toward direct supplier contracts. The FDA's GRAS notification pathway for novel steviol glycosides accelerates commercialization timelines for reformulated product lines. California's Central Valley hosts pilot cultivation trials seeking to reduce dependence on Chinese leaf supply.
China
Stevia rebaudiana cultivation concentrates in Shandong and Jiangsu provinces, supplying extraction facilities in Zhejiang. SAMR's GB 2760-2024 revision aligns purity benchmarks with Codex Alimentarius, streamlining export qualification for domestic processors. Qingdao's port infrastructure supports glycoside shipments to European and North American formulators.
India
Food manufacturers in Maharashtra and Gujarat specify stevia blends for clean-label dairy and beverage applications. FSSAI notification requirements for steviol glycoside imports shape supplier qualification protocols. Mumbai's chemical processing corridor hosts toll-manufacturing arrangements for multinational sweetener suppliers.
Germany
Industrial bakery chains in Bavaria and North Rhine-Westphalia demand heat-stable glycoside formulations for reduced-sugar bread lines. EFSA's novel food approvals under Regulation (EU) 2015/2283 govern maximum-use thresholds across member states. Hamburg's port complex serves as the primary entry point for Asian glycoside shipments into continental Europe.
Brazil
Stevia cultivation in Mato Grosso do Sul and Paraná supplies both domestic processors and export markets. ANVISA's food additive regulations determine formulation compliance for beverage and confectionery applications. São Paulo's industrial corridor hosts blending operations serving Latin American ready-to-drink manufacturers.
Global Stevia Sugar Blends Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on extraction technology and proprietary glycoside variants. The vendor base stratifies between multinational ingredient conglomerates with captive supply chains and regional blenders serving niche applications. Three archetypes dominate: fermentation-based bioprocessors, agricultural extractors with leaf sourcing networks, and formulation houses with sensory modulation capabilities. Competitive intensity centers on backward integration into glycoside production and technical service embedding with beverage R&D functions.
Within the integrated supply chain tier, Cargill and Tate & Lyle occupy positions anchored by fermentation platform investments and taste-modulation intellectual property. Ingredion sits within the beverage partnership archetype, exemplifying suppliers that embed technical service teams with North American bottlers. These three entities represent the dominant competitive anchors against which regional blenders and specialty distributors position alternative sourcing options.
| Leading Market Players |
|---|
| Cargill |
| Tate & Lyle |
| Ingredion |
| PureCircle |
| Archer Daniels Midland |
| GLG Life Tech |
| Sunwin Stevia International |
| Pyure Brands |
| Stevia First |
| Others |
Value Chain & Pricing Dynamics
Shandong Province's stevia leaf processing clusters dictate downstream pricing leverage through their concentration of extraction capacity and glycoside refinement infrastructure. Beverage bottlers in North America and Latin America face compressed negotiating room when procurement volumes fall below direct-contract thresholds.
Pricing Analysis
Volume-discount tiering separates fermentation-derived Reb M formulations from agricultural Reb A extracts and commodity-grade blended sweeteners. Price differentiation rests on purity certification against FDA GRAS and SAMR GB 2760-2024 benchmarks, with thermal stability grades commanding additional premiums. Cost compression in standard-grade powder formats is intensifying because Chinese leaf processors are expanding fermentation capacity. Mid-tier regional food manufacturers exhibit the highest price sensitivity, while multinational beverage conglomerates prioritize technical service bundling over unit cost.
Supply Chain Analysis
Upstream Stevia rebaudiana cultivation draws from China, Paraguay, and emerging plots in Brazil's Mato Grosso do Sul. Raw material dependencies span agricultural leaf supply, fermentation feedstock for bioconversion platforms, and chromatographic resins for purification. Single-source vulnerability concentrates in Shandong and Jiangsu extraction corridors, where climate disruption or regulatory inspection halts would cascade through global glycoside availability. Distribution runs through direct manufacturer contracts for bulk beverage procurement, bypassing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beverage bottler procurement consolidation has shifted negotiating power toward large-scale buyers, compressing supplier margins and elevating technical service requirements as table stakes for contract eligibility.
For Market Incumbents: Harden formulation IP moats through proprietary taste-modulation patents that mask bitter aftertastes in high-intensity applications. Deepen captive supply of heat-stable Reb M and Reb D glycosides via fermentation platform expansion, neutralizing agricultural leaf supply volatility as a competitive wedge for bioprocessing entrants. For New Entrants and Emerging Players: Mid-market bakery chains in Germany and Brazil represent the most penetrable entry point, as these segments demand thermal degradation-resistant formulations without the technical service infrastructure required by multinational beverage accounts. Specialty organic stevia blends for European health food retailers offer a secondary beachhead with lower capital barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational ingredient conglomerates seeking to divest legacy agricultural extraction assets rendered obsolete by precision fermentation economics. Long-term viability hinges on biotechnology transition completion rather than leaf-sourcing network scale. The signal to watch is SAMR's enforcement trajectory on GB 2760-2024 recertification timelines, which will separate compliant processors from stranded capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Platform Scale-Up | Bioconversion capacity displaces agricultural extraction in Reb M and Reb D production. |
| Heat-Stability Formulation Development | Thermal degradation-resistant glycosides unlock industrial bakery applications above 180°C processing. |
| Direct Technical Service Embedding | On-site application laboratories with North American bottlers create switching costs and contract stickiness. |
| Regulatory Convergence Certification | Unified FDA GRAS and SAMR GB 2760-2024 compliance tiers reduce multinational specification overhead. |
| Liquid Concentrate Pump System Integration | Pumpable dosing formats eliminate powder handling and improve batch consistency for ready-to-drink manufacturers. |
Study Parameters
Desk research of FDA GRAS notifications, SAMR GB standards filings, EFSA novel food approvals, and trade customs data preceded structured interviews with beverage formulation directors, stevia extraction plant managers, sensory scientists, and procurement leads at North American bottlers. Primary fieldwork with Chinese leaf processors and Brazilian cultivation cooperatives validated secondary volume estimates. Bottom-up capacity modeling and top-down demand calibration from beverage sector consumption patterns were triangulated against glycoside shipment records.
Assumptions held fixed include current FDA GRAS pathway efficiency, EFSA regulatory timelines under Regulation (EU) 2015/2283, and fermentation yield curves for Reb M production. Variables tested across the projection horizon encompass SAMR enforcement intensity, climate volatility in Shandong cultivation zones, and beverage manufacturer substitution elasticity between stevia blends and emerging rare sugar alternatives. CAGRs were derived from segment-level volume build-ups across powder, liquid, and granular formats, with bakery heat-stability premiums and liquid concentrate adoption curves as industry-specific demand inputs.
Practitioners should monitor SAMR inspection protocols and EFSA specification amendments for early signals of regulatory divergence that would force specification tier fragmentation. Forecasts reflect these assumptions without certainty on biotechnology cost curves or agricultural yield stability. Cross-checking against customs trade data and extraction facility utilization benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Egypt Food Sweetener Market
Sweeteners
Stevia Mints Market
Sweeteners
Sweeteners Market
Sweeteners
Polyol Sweeteners Market
Sweeteners
Turbinado Sugar Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
Glucose-Fructose Syrup (GFS) Market
Sweeteners
Mexico Food Sweetener Market
Sweeteners
Europe Stevia Market
Sweeteners
Intensive Sweeteners Market
Sweeteners
Agave Nectar Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
Low-Calorie Sweetener Market
Sweeteners
China Saccharin Market
Sweeteners
Sanding Sugar Market
Sweeteners
Allulose Market