
 Africa and Middle East Sugarcane Syrup Market | 2026-2036
Africa and Middle East Sugarcane Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Africa and Middle East Sugarcane Syrup Market Insights
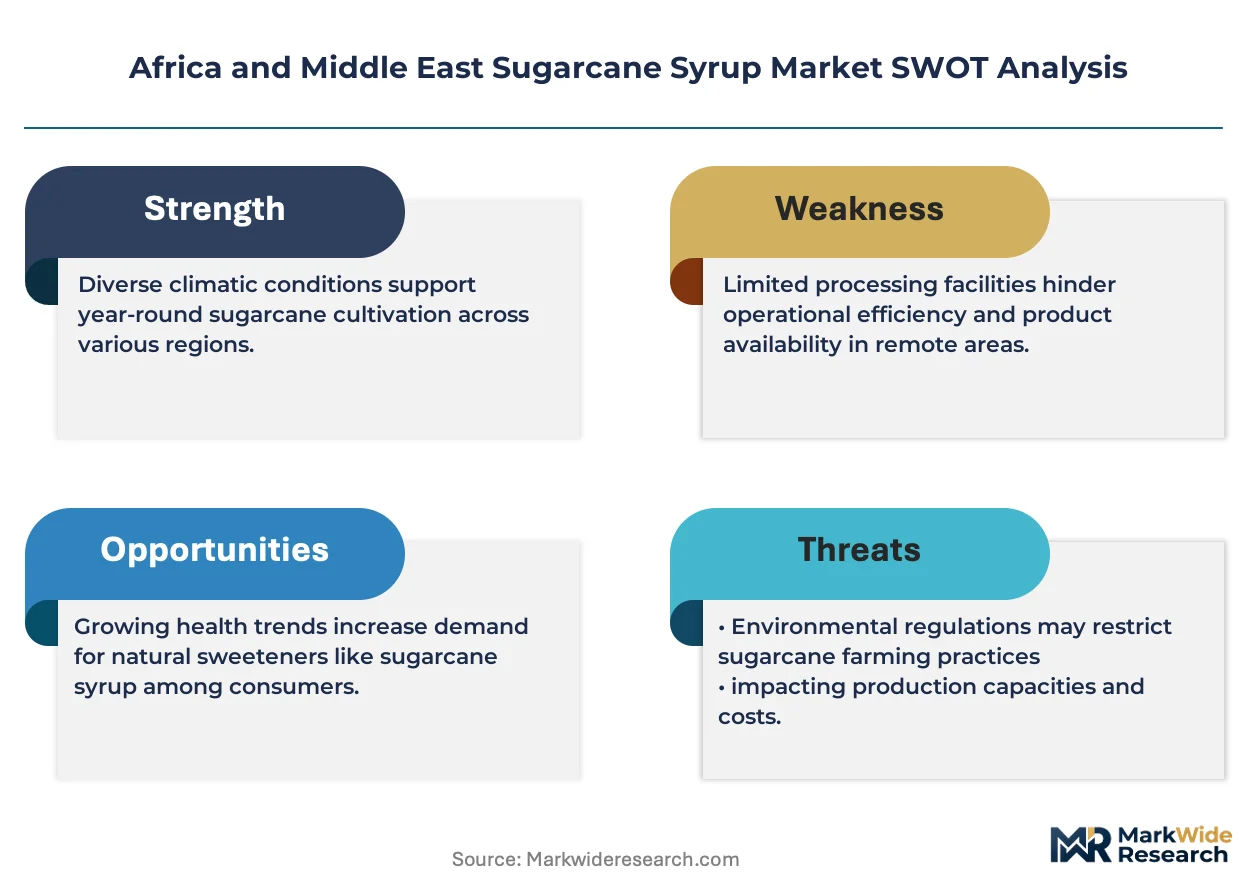
ISO 22000 certification is redrawing competitive boundaries across the Africa and Middle East Sugarcane Syrup Market, forcing smaller refiners to upgrade hazard-control systems or exit foodservice channels. Illovo Sugar (Pty) Ltd leverages backward integration into South African cane estates to secure feedstock consistency for its syrup fraction. Tongaat Hulett anchors regional supply through Mozambican and Zimbabwean milling assets that feed cross-border syrup trade. Kenana Sugar Company dominates Sudanese output with irrigation-fed cane operations that sustain year-round liquid syrup production.
Sugarcane syrup denotes a viscous, sucrose-dense liquid extracted from crushed Saccharum officinarum stalks, typically standardized to 65–75 degrees Brix and preserved through thermal evaporation or pasteurization for industrial food formulation. The product serves as a bulk sweetener, humectant, and browning agent across beverage, confectionery, and sauce manufacturing. Refined syrup captures the largest volume share due to its neutral flavor profile and extended shelf stability in hot-climate distribution. Organic syrup registers the fastest expansion as Gulf retailers and South African supermarkets impose pesticide-residue thresholds that favor certified cane sources. Specialty syrup, including dark molasses-style variants, commands premium positioning in ethnic and artisanal foodservice segments.
Egypt's national food safety regulator enforces additive-labeling rules that shape syrup import documentation, while South Africa's Department of Health mandates nutritional panel disclosure for retail-format products. Saudi Arabia's SFDA applies Gulf Standardization Organization halal criteria that filter which syrup suppliers qualify for institutional tenders across the GCC. Stakeholders must monitor diverging national fortification mandates and traceability requirements that will determine which production configurations remain viable across North, East, and Southern African trade corridors.
Market Dynamics
ISO 22000 certification is redrawing competitive boundaries across the Africa and Middle East Sugarcane Syrup Market, forcing smaller refiners to upgrade hazard-control systems or exit foodservice channels. Egypt's FSSAI-aligned food safety modernization and rising halal certification requirements are tightening entry barriers for imported syrups, concentrating procurement power among certified domestic and regional suppliers.
Growth Catalysts
- Beverage manufacturing expansion:Carbonated soft drink producers in Nigeria and Egypt are scaling liquid cane syrup procurement for reformulated recipes that replace refined sugar with viscous sweeteners.
- SFDA halal mandates:Saudi Arabia's Gulf Standardization Organization criteria are institutionalizing halal-certified syrup requirements across GCC institutional tenders, filtering supplier pools.
- Nile Delta clustering:Confectionery and sauce producers concentrate near Egyptian cane milling infrastructure, reducing feedstock transport costs and enabling just-in-time syrup delivery.
Market Restraints
- Irrigation water scarcity:Sudanese and Egyptian cane estates face Nile water allocation constraints that cap year-round syrup production volumes regardless of processing capacity.
- Import documentation friction:Egypt's national food safety regulator enforces additive-labeling rules that delay customs clearance for non-regional syrup shipments.
- High-fructose corn syrup substitution:Industrial buyers in price-sensitive segments trial corn-based alternatives where cane syrup premiums exceed formulation budget thresholds.
Strategic Opportunities
- Organic certification gap:Gulf retailers and South African supermarkets impose pesticide-residue thresholds that favor certified cane sources, creating premium positioning for compliant suppliers.
- Ethnic artisanal channels:Dark molasses-style specialty syrups command premium placement in Middle Eastern and North African foodservice segments underserved by standardized refined products.
- Mozambican cross-border trade:Tongaat Hulett's milling assets anchor regional supply corridors that can extend liquid syrup distribution into underpenetrated East African markets.
Industry Challenges
- ISO 22000 implementation timeline:Small refiners face 12-18 month certification cycles requiring hazard analysis critical control point documentation and third-party audit costs.
- Traceability system integration:Diverging national fortification mandates across North, East, and Southern African trade corridors force producers to maintain multiple production configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa and Middle East Sugarcane Syrup Market |
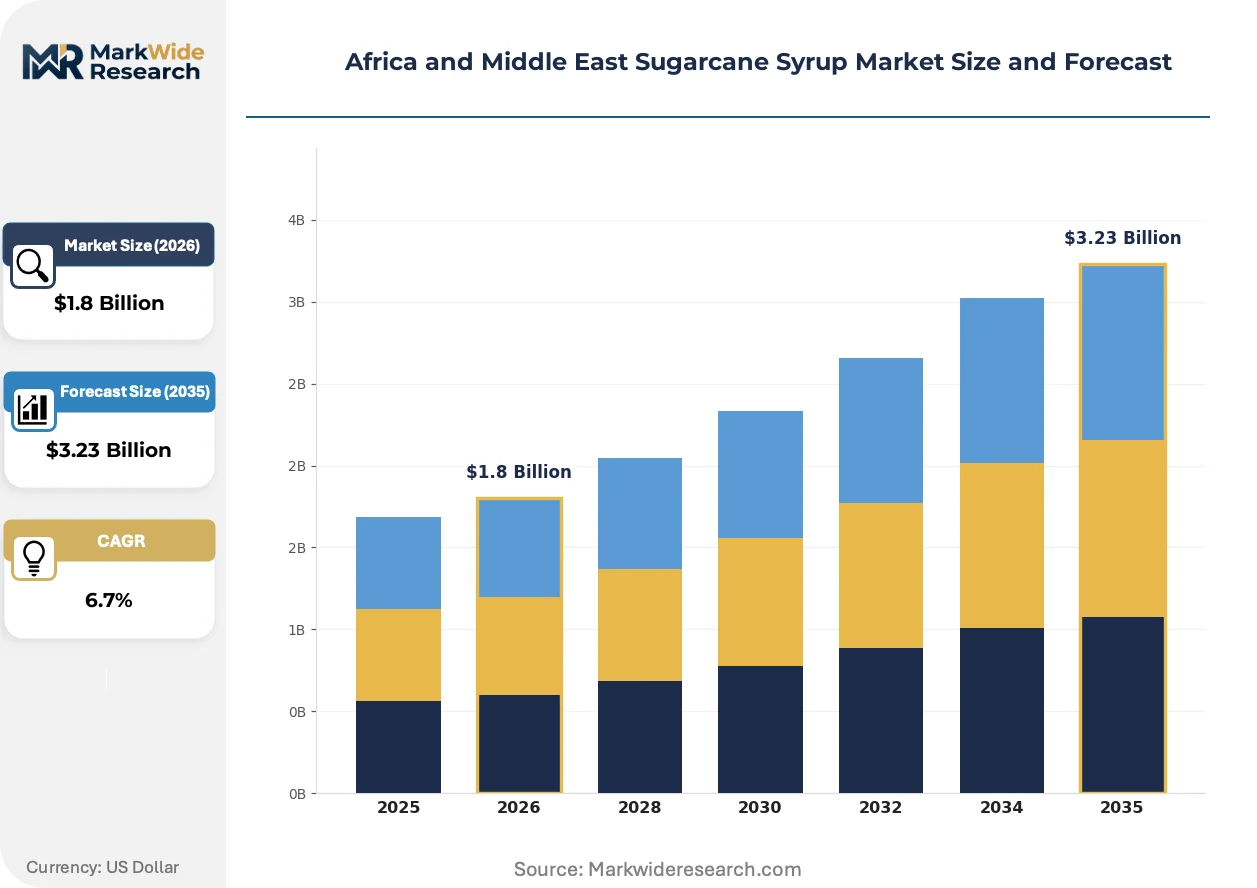
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Syrup, Refined Syrup, Raw Syrup, Specialty Syrup End Use: Beverages, Confectionery, Baked Goods, Sauces Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Foodservice Form: Liquid, Granulated, Powdered, Concentrated |
| Companies Covered | Illovo Sugar (Pty) Ltd, Tongaat Hulett, Super Syrups, Sunshine Sugar, Frozy Egypt, Kenana Sugar Company, White Nile Sugar Company, GM Sugar Uganda Limited, Kinyara Sugar Works Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa and Middle East Sugarcane Syrup Market Trends and Innovations
Membrane filtration and precision evaporation technologies are reshaping how regional refiners balance yield against quality grades. These process innovations enable simultaneous production of neutral refined syrups and character-retaining specialty variants from identical cane feedstock.
Membrane filtration technology is bifurcating the Africa and Middle East Sugarcane Syrup Market into dual-stream operations. South African and Egyptian refiners deploy ceramic microfiltration to produce sterile, extended-shelf-life syrups for beverage manufacturers requiring 18-month stability in hot-climate distribution. Simultaneously, bypass streams retain flavor-active compounds for ethnic foodservice buyers. The technology is bifurcating supplier portfolios into commodity-neutral and premium-characterized product lines.
Egypt's FSSAI-aligned food safety modernization mandates additive-labeling disclosure that exceeds previous import documentation requirements. Industrial buyers now demand batch-level certificates of analysis before tender participation. Confectionery manufacturers in the Nile Delta processing corridor are consolidating supplier relationships with domestic refiners capable of real-time traceability documentation.
Buyer concentration among multinational beverage manufacturers is compressing procurement cycles from annual to quarterly negotiations. Nigerian and Egyptian carbonated soft drink producers now require just-in-time syrup delivery synchronized with bottling schedules. This pattern concentrates volume commitments with refiners possessing captive cane supply and integrated logistics assets.
Africa and Middle East Sugarcane Syrup Market Segmentation
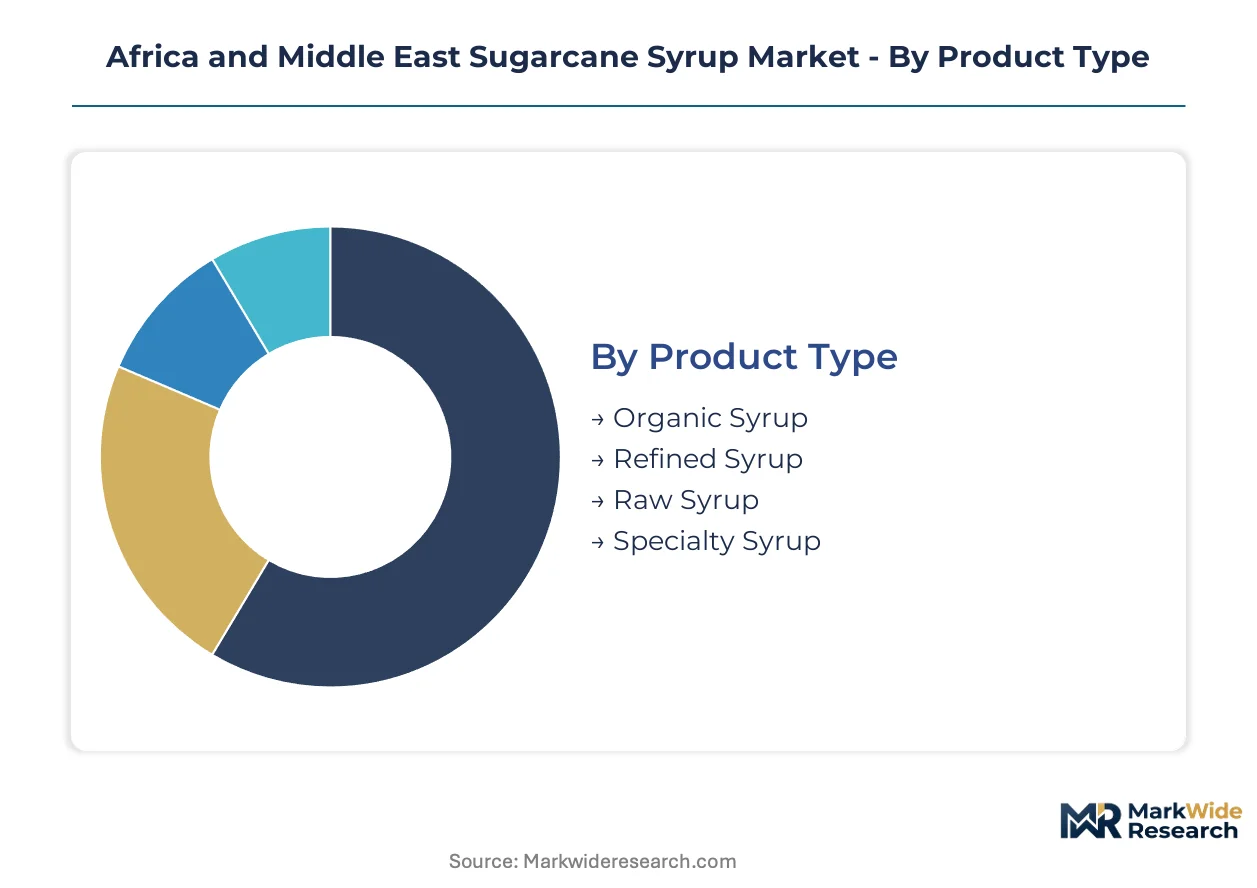
Channel configuration determines how syrup grades reach industrial buyers versus retail consumers across the Africa and Middle East Sugarcane Syrup Market. Certification requirements and shelf-stability demands fragment procurement pathways, with beverage manufacturers sourcing through institutional contracts while artisanal buyers navigate specialty distribution networks.
Product Type:
Refined and organic grades flow through divergent channel structures, with neutral syrups dominating institutional procurement and certified variants commanding premium retail placement.
- Refined Syrup:Neutral-flavor syrup standardized to 65–75 degrees Brix delivers extended shelf stability for hot-climate distribution. Beverage manufacturers in Nigeria and Egypt concentrate procurement of this grade for carbonated soft drink reformulation where consistency and clarity specifications dominate supplier selection.
- Organic Syrup:Certified cane sources meeting pesticide-residue thresholds imposed by Gulf retailers and South African supermarkets. This segment gains share fastest as procurement policies at institutional buyers harden around sustainability documentation requirements.
- Raw Syrup:Minimally processed cane juice concentrate retaining molasses character for traditional applications.
- Specialty Syrup:Dark molasses-style variants targeting ethnic foodservice channels and artisanal confectionery producers.
Refined syrup dominates installed base. Organic syrup is where expansion concentrates.
End Use:
Application-specific viscosity and browning requirements segment buyers by formulation sophistication, with high-volume beverage plants demanding sterile supply chains versus small-batch artisanal tolerance for variability.
- Beverages:Liquid cane syrup serves as bulk sweetener and humectant in carbonated soft drinks and traditional juices. Nigerian and Egyptian bottlers are scaling procurement volumes as reformulation replaces refined sugar with viscous sweeteners that improve mouthfeel and reduce crystallization risk.
- Confectionery:Precise Brix control and consistent browning kinetics for caramels and toffees. Nile Delta processing corridor clusters near Egyptian cane milling infrastructure, reducing feedstock transport costs and enabling just-in-time delivery synchronized with production schedules.
- Baked Goods:Humectant properties extending shelf life in hot-climate distribution for packaged breads and pastries.
- Sauces:Viscosity modification and Maillard browning in condiment manufacturing.
Beverage applications anchor volume commitments. Confectionery represents the fastest-growing trajectory as regional processing infrastructure consolidates.
Distribution Channel:
Channel selection correlates with buyer scale and certification burden, with multinational beverage manufacturers bypassing retail entirely while small-batch users fragment across specialty access points.
- Foodservice:Institutional procurement channels serving hotels, restaurants, and catering operations across GCC markets. Saudi Arabia's SFDA halal mandates filter supplier pools for this channel, concentrating volume with certified domestic and regional refiners capable of real-time traceability documentation.
- Supermarkets:Retail-format syrup for household and small commercial baking. South African and Egyptian regulators mandate nutritional panel disclosure that shapes packaging and labeling investments for this channel.
- Specialty Stores:Ethnic and artisanal foodservice segments sourcing dark molasses-style variants.
- Online Retail:Direct-to-consumer and small-business procurement with limited cold-chain requirements.
Foodservice commands the largest volume throughput. Supermarkets are where margin expansion concentrates.
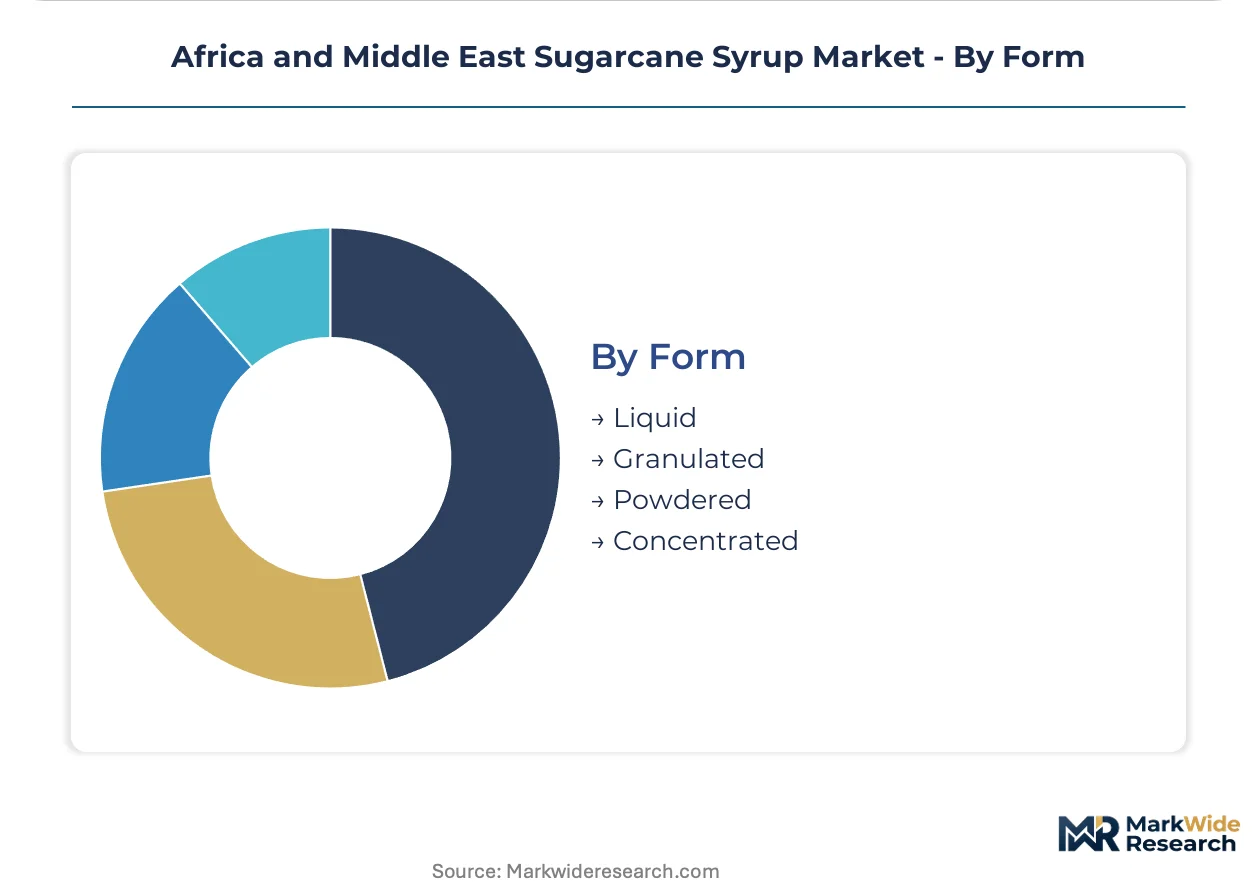
Form:
Physical state determines logistics economics and reconstitution requirements, with liquid formats dominating industrial procurement and concentrated or dried forms serving dispersed or import-dependent markets.
- Liquid:Ready-to-use viscous syrup preserved through thermal evaporation or pasteurization. Beverage manufacturers require this form for direct incorporation into bottling lines without reconstitution steps, with just-in-time delivery synchronized to production schedules.
- Concentrated:Reduced-water formulations for cost-efficient long-distance transport and extended storage. Sudanese and Egyptian buyers facing irrigation water scarcity favor this form to minimize reconstitution overhead.
- Granulated:Dried syrup solids for bakery and dry-mix applications.
- Powdered:Fine-particle spray-dried syrup for instant beverage and sauce formulations.
Liquid form dominates installed processing capacity. Concentrated is climbing the fastest as water-stressed regions optimize logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National food safety regulators across Africa and the Middle East are tightening certification requirements for imported syrups, concentrating procurement with compliant domestic and regional suppliers. Egypt's FSSAI-aligned modernization and Saudi Arabia's SFDA halal mandates are reshaping trade corridors. Processing infrastructure clusters near cane milling assets in the Nile Delta and Southern Africa.
Egypt
Beverage manufacturers in Cairo and the Nile Delta corridor are scaling liquid cane syrup procurement for carbonated soft drink reformulation. The country's national food safety regulator enforces additive-labeling rules that exceed previous import documentation thresholds. Confectionery and sauce producers cluster near Egyptian cane milling infrastructure, enabling just-in-time syrup delivery synchronized with production schedules.
Saudi Arabia
GCC institutional tenders for hotels, restaurants, and catering operations are filtering supplier pools through SFDA halal certification requirements. The Gulf Standardization Organization criteria are institutionalizing compliant syrup mandates across foodservice channels. Riyadh-based procurement offices are consolidating volume commitments with certified domestic and regional refiners capable of real-time traceability documentation.
South Africa
Supermarket chains are imposing pesticide-residue thresholds that favor certified organic cane sources for retail-format syrup placement. The Department of Health mandates nutritional panel disclosure that shapes packaging and labeling investments. Durban and Johannesburg processing hubs anchor regional supply through backward integration into captive cane estates.
Sudan
Irrigation-fed cane estates along the White Nile sustain year-round liquid syrup production regardless of seasonal rainfall patterns. Water allocation constraints from the Nile Basin Initiative cap expansion potential despite available processing capacity. Kenana and surrounding milling assets feed cross-border syrup trade into underpenetrated East African markets.
Nigeria
Carbonated soft drink producers in Lagos and Kano are replacing refined sugar with viscous cane sweeteners that improve mouthfeel and reduce crystallization risk. The country's national food safety regulator is aligning documentation requirements with regional standards. Beverage bottling corridors near northern processing clusters are compressing procurement cycles from annual to quarterly negotiations.
Africa and Middle East Sugarcane Syrup Market Competitive Landscape
Player mix skews toward integrated sugar conglomerates with captive cane supply and independent regional refiners serving niche certification tiers. Market structure concentrates volume commitments among three to four vertically integrated operators controlling milling and syrup fractionation assets. Strategic archetypes include estate-backed integrated producers, halal-certified regional specialists, and organic-accredited premium suppliers. Dominant competitive moves encompass backward integration into upstream cane cultivation and portfolio diversification across refined, organic, and specialty syrup grades.
Among estate-integrated African operators, Illovo Sugar (Pty) Ltd and Tongaat Hulett occupy positions anchored by Southern and East African milling assets. Kenana Sugar Company exemplifies the irrigation-backed production archetype with year-round output capability. These three entities represent the scale-driven tier where captive feedstock control and integrated logistics assets concentrate procurement power among multinational beverage manufacturers.
| Leading Market Players |
|---|
| Illovo Sugar (Pty) Ltd |
| Tongaat Hulett |
| Super Syrups |
| Sunshine Sugar |
| Frozy Egypt |
| Kenana Sugar Company |
| White Nile Sugar Company |
| GM Sugar Uganda Limited |
| Kinyara Sugar Works Ltd |
| Others |
Pricing and Supply Chain Analysis
Captive cane estate scale in South Africa and Sudan anchors cost floors across the Africa and Middle East Sugarcane Syrup Market, concentrating pricing power among three vertically integrated operators while forcing smaller refiners toward specialty certification tiers to escape commodity compression.
Pricing Analysis
Certification level creates the primary spread between ISO 22000-compliant institutional grades and uncertified commodity offerings. Contract-based long-term offtake dominates multinational beverage procurement, while spot transactions serve artisanal buyers. Price differentiation rests on halal certification status and captive irrigation access. Cost compression in Egyptian Nile Delta processing is intensifying because Kenana's year-round output floods regional supply. Industrial beverage manufacturers show lowest price sensitivity; small confectionery producers in price-sensitive segments trial high-fructose corn syrup alternatives.
Supply Chain Analysis
Nile Basin water allocation chokepoints tether year-round syrup output to Sudanese irrigation-fed estates regardless of seasonal rainfall elsewhere. Supply concentrates in Sudan, Egypt, and South Africa as primary production nodes. Feedstock draws from Saccharum officinarum cane, ceramic membrane filtration equipment, and halal certification audit services. Single-source vulnerability runs through White Nile irrigation infrastructure subject to basin-wide allocation disputes. Distribution runs through institutional procurement channels serving GCC foodservice and Nile Delta confectionery clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers creates niche entry points as multinational beverage buyers consolidate volume with integrated operators while organic and specialty grades remain underserved by compliant suppliers.
For Market Incumbents: Shield institutional share by accelerating ISO 22000 certification timelines for captive milling assets before Egyptian FSSAI-aligned enforcement tightens. Prioritize backward integration into Mozambican cane development to anchor cross-border supply corridors against Tongaat Hulett's regional expansion. Certification investment represents the critical defensive lever as halal mandates filter GCC tender participation. For New Entrants and Emerging Players: Lead with organic certification to capture Gulf retailer and South African supermarket placement premiums where pesticide-residue thresholds exceed existing supplier compliance. Target Sudanese cross-border trade into underpenetrated East African markets where Kenana's irrigation capacity cannot extend. Specialty dark molasses variants for ethnic foodservice channels offer the most penetrable white-space with lowest incumbent saturation. For Investors and Strategic Acquirers: Irrigation-backed estate operators with year-round production capability offer the strongest long-term viability framing across the analysis window. Halal-certified regional specialists with real-time traceability documentation command acquisition premiums as SFDA mandates institutionalize compliance requirements. Watch Nile Basin water allocation negotiations as the inflection indicator that would recalibrate Sudanese expansion economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cane Estates | Secures feedstock consistency against Nile water allocation constraints that cap competitor expansion. |
| ISO 22000 Certification Acceleration | Preserves foodservice channel access as Egyptian FSSAI-aligned enforcement tightens import documentation. |
| Halal Certification Investment | Unlocks GCC institutional tender participation filtered through Saudi SFDA Gulf Standardization Organization criteria. |
| Organic Accreditation Program | Captures premium placement at Gulf retailers imposing pesticide-residue thresholds on retail-format syrup. |
| Membrane Filtration Technology Deployment | Enables dual-stream production of sterile beverage grades and character-retaining specialty variants. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, Egyptian food safety regulator filings, and GCC tender documentation to anchor volume estimates. Conversations with beverage procurement directors, Nile Delta confectionery plant managers, halal certification auditors, and Sudanese irrigation authority planners informed operational assumptions. Secondary validation drew from Kenana Sugar Company disclosures, SFDA regulatory circulars, and South African Department of Health labeling mandates. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include product type tier, end-use application, distribution channel configuration, and physical form state across the projection horizon. CAGRs derived from historical volume trajectories adjusted for Nile water allocation constraints and certification adoption curves. Forecast inputs incorporated membrane filtration technology penetration rates and halal mandate implementation timelines throughout the forecast period.
The analysis sits within stated boundaries; outcomes outside sustained irrigation access and stable regulatory enforcement would require recalibration. Forecasts reflect assumptions around certification timeline adherence and basin water allocation continuity. Practitioners should keep alternative scenarios live as Nile Basin Initiative negotiations and Egyptian FSSAI implementation pacing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sodium Saccharin Market
Sweeteners
Low-Calorie Sweetener Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
Molasses Market
Sweeteners
Allulose Powder Market
Sweeteners
Citrus Molasses Market
Sweeteners
Steviol Glycoside Market
Sweeteners
Raw Beetroot Sugar Market
Sweeteners
Germany Food Sweetener Market
Sweeteners
South Korea Allulose Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
Asia Pacific Food Sweetener Market
Sweeteners
Dextrose Syrup Market
Sweeteners
Smoked Sugar Market
Sweeteners
Coconut Sugar Market
Sweeteners
China Food Sweetener Market