
 Africa Stevia Market | 2026-2036
Africa Stevia Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Stevia Market Outlook
Single-serve sachet and portion-control packaging is repositioning stevia from bulk industrial ingredient to consumer-facing tabletop sweetener across African retail channels. Cargill, Incorporated leverages its regional supply infrastructure to anchor distribution in Southern African markets. PureCircle competes through specialized steviol glycoside extraction capabilities tailored to tropical cultivation conditions. Stevia South Africa (Pty) Ltd dominates local formulation services for beverage producers seeking rapid reformulation support.
Stevia comprises a group of high-intensity sweeteners extracted from Stevia rebaudiana leaves, primarily containing steviol glycosides such as rebaudioside A and stevioside that deliver sweetness at concentrations approximately 200-350 times that of sucrose while contributing negligible caloric content. The compound serves industrial food and beverage manufacturers as a sugar replacement in reduced-calorie product lines. Powdered stevia formulations currently occupy the largest share of product-type revenue due to compatibility with existing dry-mix manufacturing lines across African food processors. Liquid stevia variants represent the fastest-expanding category as beverage producers in Kenya and Nigeria adopt pump-dispense systems for precise dosing in carbonated drink production.
South Africa's Department of Health enforces sugar reduction guidelines through its national food control program, while the country's Bureau of Standards mandates labeling disclosures for non-nutritive sweeteners that shape consumer transparency requirements. The Food and Agriculture Organization's Codex Alimentarius guidelines on steviol glycoside purity specifications influence import acceptance criteria at multiple African national food safety agencies. Stakeholders must monitor evolving national sweetener approval lists and local cultivation pilot programs to determine whether backward integration into stevia leaf sourcing or continued import reliance offers superior margin protection.
Market Dynamics
South Africa's sugar reduction mandates under its national food fortification program are compressing reformulation timelines for beverage and baked goods manufacturers, forcing rapid substitution of cane sugar with steviol glycoside formulations across East and West African production corridors.
Growth Catalysts
- East African beverage procurement:Carbonated drink producers in Kenya and Ethiopia are expanding steviol glycoside sourcing for low-calorie product lines, pulling volume through Mombasa and Djibouti port corridors.
- National food control enforcement:South Africa's Department of Health sugar reduction guidelines are mandating reformulation across packaged food categories, creating regulatory pull for high-intensity sweeteners.
- Lagos-Ibadan manufacturing concentration:Nigerian food processors in this corridor are substituting cane sugar with blended stevia formulations in dairy and baked goods, clustering demand in West Africa's largest urban market.
Market Restraints
- Import dependency for leaf supply:No commercial-scale stevia cultivation exists in Africa, forcing reliance on Paraguayan and Chinese leaf imports subject to currency volatility and shipping cost spikes.
- Rebaudioside M scarcity:Limited global production of this preferred glycoside variant restricts premium formulation options for African beverage producers seeking cleaner taste profiles.
- Codex Alimentarius purity enforcement:Multiple national food safety agencies apply strict steviol glycoside specifications at import, creating acceptance friction for non-certified suppliers.
Strategic Opportunities
- Rwandan cultivation pilots:Highland agricultural zones offer suitable climate for Stevia rebaudiana trials, potentially enabling backward integration into leaf sourcing for regional extractors.
- Single-serve tabletop positioning:Portion-control sachet formats are repositioning stevia from industrial ingredient to consumer-facing retail product across African supermarket and informal trade channels.
- Pump-dispense beverage systems:Kenyan and Nigerian carbonated drink producers are adopting liquid stevia dosing infrastructure, opening fastest-growing product category expansion.
Industry Challenges
- Extraction technology skill scarcity:Local workforce lacks expertise in steviol glycoside purification and Reb-A/Reb-M separation, requiring foreign technical staffing for processing facilities.
- Dual certification burden:Manufacturers must simultaneously satisfy South African Bureau of Standards labeling rules and importing country Codex alignment, extending compliance timelines.
- Legacy cane sugar supply contracts:Long-term purchasing agreements with domestic sugar mills create contractual friction for rapid sweetener substitution in reformulation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Stevia Market |
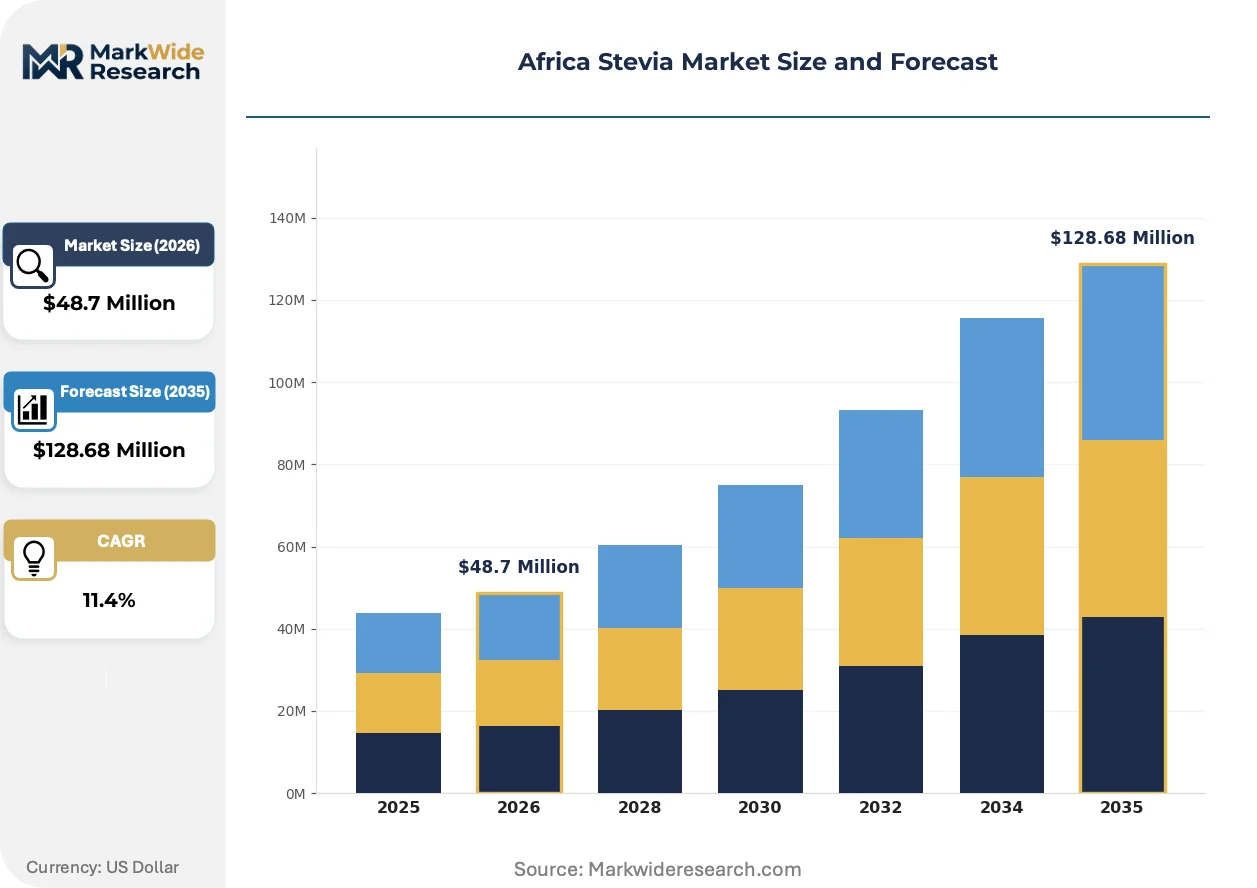
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $128.68 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steviol Glycosides, Liquid Stevia, Powdered Stevia, Blended Stevia End User: Food Manufacturers, Beverage Producers, Pharmaceutical Companies, Dietary Supplement Providers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors Application: Beverages, Bakery Products, Confectionery, Dairy Products |
| Companies Covered | Cargill, Incorporated, Tate & Lyle, PureCircle, Ingredion, Archer Daniels Midland Company, GLG Life Tech Corp, Evolva Holding SA, S&W Seed Company, Stevia South Africa (Pty) Ltd, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Stevia Market Strategic Shifts
Technology convergence between precision fermentation and tropical agricultural adaptation is reshaping how steviol glycosides reach African formulators, while regulatory tightening and retail packaging innovation are compressing traditional supply relationships.
Enzymatic bioconversion of low-grade stevia extracts into high-purity rebaudioside M is consolidating quality tiers in the African market. Beverage manufacturers in Nigeria and Kenya are adopting this processed input faster than regional extractors can scale conventional leaf-based output. The technology is consolidating supplier margins toward biotech-enabled processors with fermentation capabilities.
South Africa's Bureau of Standards non-nutritive sweetener labeling mandates are forcing disclosure granularity on packaged goods. Manufacturers must now specify steviol glycoside subtypes and concentrations per serving, increasing formulation documentation burdens. The beverage sector is responding by consolidating supplier relationships toward certified extractors with batch-traceable documentation systems.
Food processors in the Lagos-Ibadan corridor are compressing procurement cycles from annual cane sugar contracts to quarterly stevia formulation trials. This behavioral shift is displacing long-term commodity purchasing departments with agile sourcing functions embedded in product development teams. The pattern is most visible among Nigerian dairy and bakery manufacturers racing to meet retail chain sugar-reduction deadlines.
Africa Stevia Market Segmentation
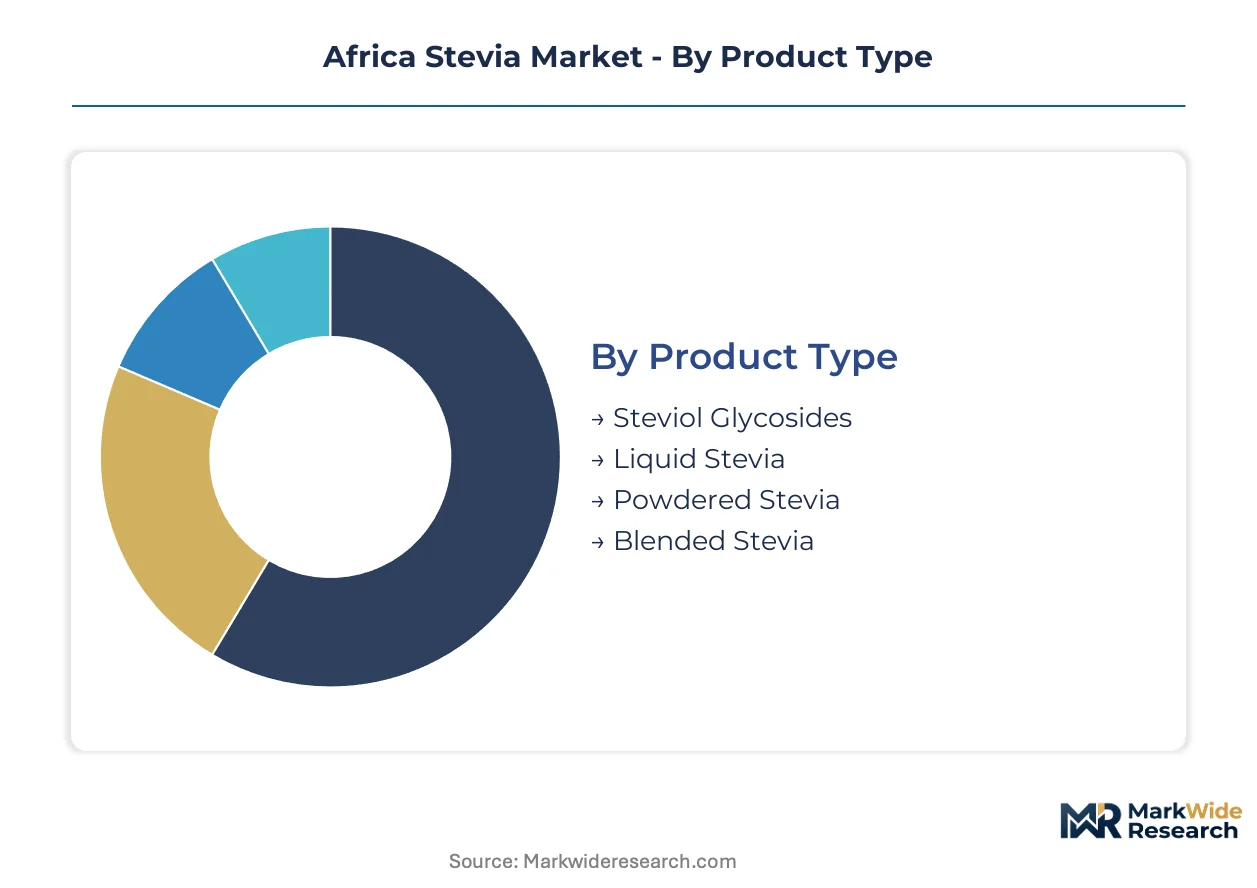
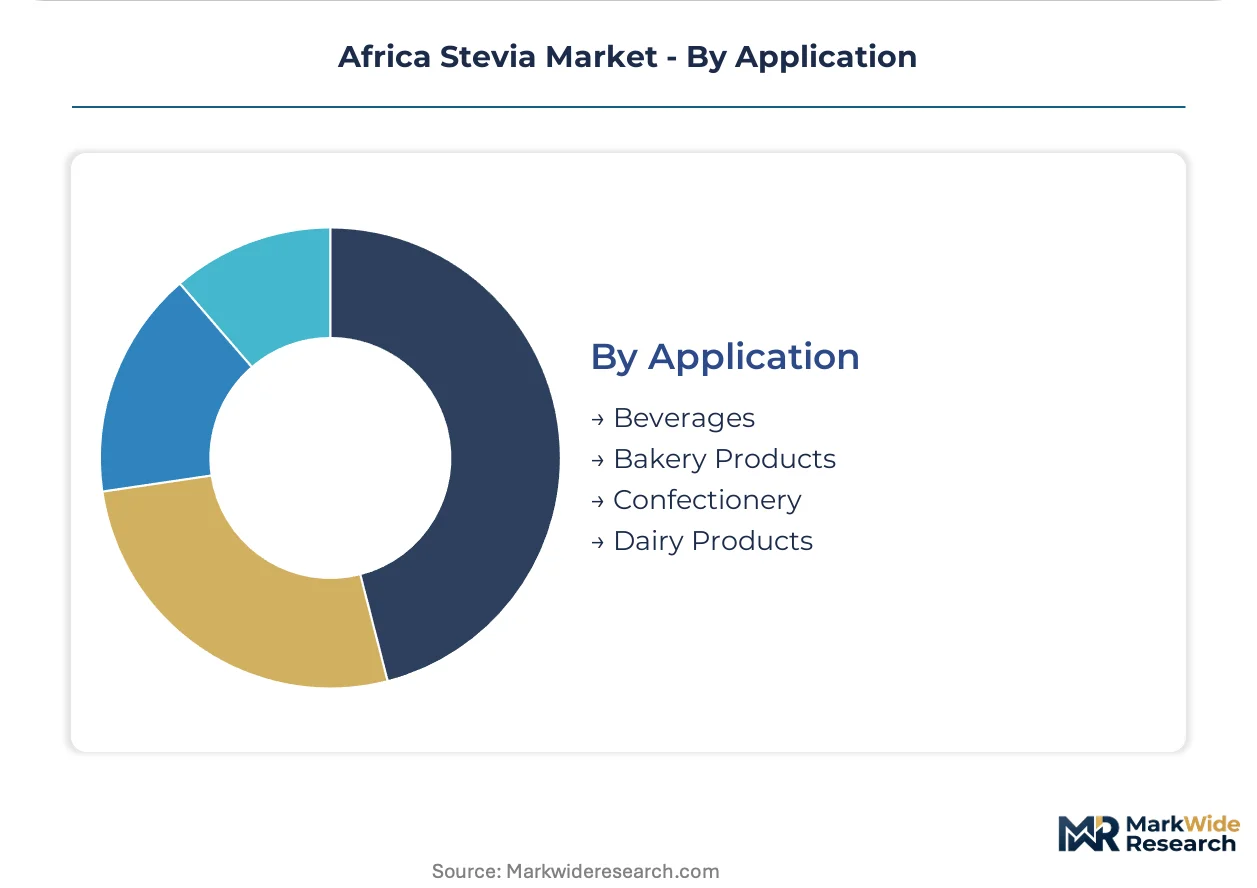
Segmentation reveals how capital deployment and technical requirements vary sharply across stevia formats and customer types. Manufacturers must align production infrastructure with the specific glycoside purity and dosing precision each segment demands.
Product Type:
Capital intensity peaks in extraction and purification infrastructure, with fermentation-based glycoside production requiring the heaviest upfront investment.
- Steviol Glycosides:High-purity extracts containing rebaudioside A and stevioside serve as the foundational input for downstream formulation. Beverage producers in Kenya and Nigeria source these for precise dosing in carbonated drink lines where consistency is non-negotiable.
- Liquid Stevia:Alcohol or water-based solutions enable pump-dispense integration in manufacturing settings. Kenyan carbonated drink producers are adopting this format fastest as they retrofit production lines for automated sweetener injection.
- Powdered Stevia:Spray-dried formulations compatible with existing dry-mix equipment dominate current procurement volumes across African food processors.
- Blended Stevia:Combinations with bulking agents like erythritol address volume-for-volume sugar replacement in bakery applications.
Most installed capacity flows through powdered stevia. Expansion is steepest in liquid stevia.
End User:
Customer type determines formulation complexity, with pharmaceutical and supplement applications demanding documentation standards that food and beverage customers rarely match.
- Food Manufacturers:Bakeries and packaged food processors across Nigeria's Lagos-Ibadan corridor drive blended stevia procurement for reformulated cookies, biscuits, and cereals.
- Beverage Producers:Carbonated and still drink manufacturers in Kenya, Ethiopia, and South Africa represent the largest volume pull for high-purity glycosides.
- Pharmaceutical Companies:Tablet and syrup formulators require certified excipient-grade stevia with full batch traceability for pediatric and diabetic product lines.
- Dietary Supplement Providers:Protein powder and meal replacement manufacturers source stevia for flavor masking in functional nutrition products.
Procurement volume concentrates among beverage producers. Technical specification intensity is highest for pharmaceutical companies.
Distribution Channel:
Channel selection reflects buyer scale and urgency, with bulk manufacturers bypassing retail entirely while small food processors rely on intermediaries for technical support.
- Online Retail:E-commerce platforms serve tabletop sweetener consumers and small commercial buyers seeking sachet and bottle formats with delivery to secondary cities.
- Supermarkets:Mass retail chains in South Africa and Nigeria stock consumer-facing stevia brands for the health-conscious household segment.
- Specialty Stores:Health food retailers and pharmacy chains cater to diabetic and weight-management consumers seeking premium glycoside formulations.
- Wholesale Distributors:Industrial chemical and ingredient distributors dominate B2B volume, supplying Mombasa and Lagos manufacturing corridors with bulk glycoside shipments.
Transaction value flows predominantly through wholesale distributors. Customer acquisition is expanding fastest in online retail.
Application:
Application dictates thermal stability requirements, with bakery and confectionery demanding heat-resistant glycoside variants that beverage formulators can ignore.
- Beverages:Carbonated drinks, juices, and ready-to-drink teas represent the dominant application by volume, with Kenyan and Nigerian producers leading reformulation timelines.
- Bakery Products:Heat-stable stevia formulations enable sugar reduction in bread, cakes, and pastries without Maillard reaction interference.
- Confectionery:Hard candies and chewing gum manufacturers require glycosides with clean taste profiles and minimal bitter aftertaste.
- Dairy Products:Yogurt and flavored milk processors in South Africa and Nigeria adopt stevia for low-calorie positioning in premium dairy lines.
Production volume concentrates in beverages. Reformulation activity is accelerating fastest in dairy products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stevia cultivation originated in Paraguay's indigenous Guaraní communities before industrial extraction scaled in China and Southeast Asia. African demand emerged later through South African health policy and East African beverage manufacturing. The continent now imports purified glycosides while piloting domestic leaf production.
South Africa
Beverage reformulation drives glycoside consumption in Johannesburg and Cape Town manufacturing zones. The Department of Health enforces sugar reduction targets through its national food fortification program. Durban-based processors are retrofitting dry-mix lines for blended stevia formulations in breakfast cereals and baked goods.
Nigeria
Dairy and bakery manufacturers in the Lagos-Ibadan corridor are substituting cane sugar with steviol glycoside blends. The country's national food safety agency applies Codex Alimentarius purity standards at Lagos port entry. Kano food processors are testing heat-stable glycoside variants for bread and pastry applications.
Kenya
Carbonated drink producers in Nairobi and Mombasa are expanding liquid stevia procurement for automated dosing systems. The Kenya Bureau of Standards mandates labeling disclosures for non-nutritive sweeteners in packaged beverages. Mombasa port corridors are pulling volume through Djibouti for Ethiopian bottling plants.
Ethiopia
Addis Ababa beverage factories are sourcing high-purity rebaudioside A for low-calorie product lines. The Ethiopian Food and Drug Administration aligns import criteria with Codex glycoside specifications. Hawassa industrial park manufacturers are trialing stevia-sweetened ready-to-drink tea formulations for export.
Rwanda
Highland agricultural zones in Musanze and Rubavu are hosting Stevia rebaudiana cultivation pilots. The Rwanda Agriculture Board monitors crop adaptation for potential regional leaf supply. Kigali-based extractors are assessing backward integration feasibility against continued Asian import reliance.
Africa Stevia Market Competitive Environment
Premium-margin players sit above commodity-margin players across extraction technology and certification depth. The vendor base stratifies between multinational ingredient conglomerates with fermentation capabilities and regional formulators serving rapid reformulation needs. Three archetypes dominate: biotechnology-enabled glycoside producers, tropical cultivation specialists, and local formulation service providers. Capacity expansion and strategic distribution partnerships constitute the dominant competitive moves as manufacturers secure port corridor access.
Within the multinational tier, Cargill, Incorporated and Tate & Lyle occupy positions anchored by regional supply infrastructure and beverage industry relationships. PureCircle exemplifies the cultivation-specialist archetype with steviol glycoside extraction capabilities. Stevia South Africa (Pty) Ltd sits within the local formulation services tier, supporting beverage producers with rapid reformulation support. These three represent distinct strategic positions rather than direct substitutes.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Tate & Lyle |
| PureCircle |
| Ingredion |
| Archer Daniels Midland Company |
| GLG Life Tech Corp |
| Evolva Holding SA |
| S&W Seed Company |
| Stevia South Africa (Pty) Ltd |
| Others |
Value Chain & Pricing Dynamics
Specialized extraction technicians concentrated in China's Jiangsu and Shandong provinces create labor-cost differentials that widen pricing-tier spreads between fermentation-derived rebaudioside M and conventional leaf-extracted stevioside across African procurement channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs steviol glycoside transactions in African markets. Premium tiers attach to certified organic extracts with full batch traceability demanded by South African pharmaceutical formulators. Price differentiation hinges on glycoside purity grades and Codex Alimentarius certification status. Cost compression in standard-tier leaf extracts is intensifying because Chinese processors are expanding enzymatic bioconversion capacity. Beverage manufacturers in Kenya and Nigeria exhibit the highest price sensitivity, while pharmaceutical companies in Johannesburg accept substantial premiums for excipient-grade documentation.
Supply Chain Analysis
Container freight rates from Shanghai to Mombasa and Lagos fluctuate with Red Sea routing disruptions, compressing margins for importers of Paraguayan and Chinese leaf supply. Geographic supply concentration centers on China, Paraguay, and India as the primary extraction origins for African-bound glycosides. Raw material dependencies encompass Stevia rebaudiana leaf stock, fermentation feedstocks for bioconversion, and analytical reagents for purity verification. Single-source vulnerability pervades the rebaudioside M segment where fewer than five global processors hold viable capacity. Distribution runs through industrial chemical wholesalers supplying Mombasa and Lagos manufacturing corridors with bulk glycoside shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa stevia market represents a late-cycle quality story as beverage reformulation deadlines in South Africa and Nigeria shift procurement toward certified extracts with documented glycoside subtypes and concentrations.
For Market Incumbents: To counter enzymatic bioconversion technology consolidation by Chinese fermentation specialists, Cargill and PureCircle must deepen backward integration into Rwandan highland cultivation pilots and secure exclusive offtake agreements with emerging African leaf processors. Certification investment in dual South African Bureau of Standards and Codex Alimentarius compliance systems anchors premium positioning against commodity-grade imports. For New Entrants and Emerging Players: Wholesale distributors serving Nigeria's Lagos-Ibadan corridor present the most accessible entry channel for regional formulators lacking direct Asian procurement relationships. White-space targets concentrate in single-serve tabletop sachet retail formats across South African supermarket chains and Kenyan informal trade channels. A technical service partnership with local beverage producers seeking rapid reformulation support offers the strongest go-to-market angle. For Investors and Strategic Acquirers: Biotechnology-enabled ingredient conglomerates are the most active acquirer in this space, seeking fermentation capabilities that bypass leaf supply volatility. Long-term viability over a five-to-ten year window rests on whether Rwandan cultivation pilots achieve commercial scale or African demand remains tethered to Asian extraction. The signal to watch is South African Department of Health enforcement intensity on sugar reduction timelines, which would accelerate premium glycoside procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Rwandan highland pilots reduce dependency on Paraguayan leaf imports subject to currency volatility. |
| Enzymatic Bioconversion Scale-Up | Fermentation-based rebaudioside M production consolidates supplier margins toward biotech-enabled processors. |
| Dual Certification Investment | Simultaneous South African Bureau of Standards and Codex compliance extends addressable market access. |
| Single-Serve Retail Format Launch | Portion-control sachets reposition stevia from industrial ingredient to consumer-facing tabletop sweetener. |
| Pump-Dispense System Partnership | Kenyan and Nigerian carbonated drink producers adopt liquid stevia dosing infrastructure for precise automated injection. |
Study Parameters
Coverage spans East Africa, West Africa, and Southern Africa, with primary inputs from each region combined with secondary validation. The research team conducted interviews with beverage formulation managers at Kenyan and Nigerian carbonated drink producers, procurement leads at South African pharmaceutical companies, regulatory affairs specialists navigating Bureau of Standards compliance, and agricultural extension officers monitoring Rwandan cultivation pilots. Secondary sources include Kenya Bureau of Standards labeling directives, South African Department of Health food fortification program documentation, Codex Alimentarius steviol glycoside specifications, and customs records tracking glycoside shipments through Mombasa and Lagos ports. Bottom-up volume estimates from individual processor procurement patterns triangulate against top-down market sizing from regional import data.
Granularity-level framing applies distinct modeling approaches across product type, end user, and distribution channel dimensions. The analytical framework projects volume and value across the analysis window by segmenting steviol glycosides, liquid stevia, powdered stevia, and blended formulations separately. Beverage producer demand is modeled independently from pharmaceutical and dietary supplement procurement patterns. CAGRs are derived from weighted average growth assumptions calibrated to regulatory enforcement timelines and reformulation completion rates. Industry-specific forecast inputs encompass South African sugar reduction mandate implementation schedules and Kenyan carbonated drink production capacity expansions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Rwandan cultivation pilot results, Red Sea shipping route stability, and South African enforcement intensity on sugar reduction targets. Forecasts reflect assumptions about continued Codex Alimentarius alignment across national food safety agencies and sustained Chinese fermentation capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Coconut Sugar Market
Sweeteners
Russia Food Sweetener Market
Sweeteners
France Food Sweetener Market
Sweeteners
Raw Beetroot Sugar Market
Sweeteners
Erythritol Market
Sweeteners
Isomaltulose Market
Sweeteners
Maltitol Market
Sweeteners
South America Stevia Market
Sweeteners
South Korea Allulose Market
Sweeteners
Reduced Sugar Products Market
Sweeteners
Sucrose Acetate Isobutyrate Market
Sweeteners
Muscovado Sugar Market
Sweeteners
Glucose Syrup Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
Resistant Maltodextrin Market
Sweeteners
Isomaltooligosaccharide Market