
 Zero-Calorie Oil Market | 2026-2036
Zero-Calorie Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Zero-Calorie Oil Market Analytics
Buyer concentration across food manufacturers and restaurant chains is pivoting toward consolidated procurement contracts that favor suppliers with national distribution networks. Chosen Foods leverages its avocado oil supply chain expertise to anchor shelf presence in premium retail channels. Pompeian competes through Italian heritage positioning and broad cooking-oil portfolio breadth. Mazola dominates corn-oil-derived zero-calorie formulations in mid-market grocery segments.
Zero-calorie oil comprises lipid-based or fat-mimetic formulations engineered to deliver lubrication, browning, and flavor-carrying functions at negligible metabolizable energy, typically achieved through emulsion structuring, olestra-type sucrose polyester chemistry, or high-dilution spray application below five calories per serving. These oils serve commercial kitchens and home cooks seeking to reduce caloric density without sacrificing cooking performance. Spray formats lead unit volume due to portion-control precision and reduced waste in high-frequency cooking environments, while liquid oils capture margin pools among health-focused consumers prioritizing ingredient transparency. Emulsions represent the fastest-growing product type as food manufacturers reformulate processed goods to meet clean-label and reduced-calorie specifications simultaneously.
The FDA's nutrition labeling regulations and the USDA's dietary guidelines shape permissible health claims and serving-size declarations that directly influence product positioning and retail placement eligibility. State-level menu-labeling mandates in California and New York extend compliance obligations to restaurant chains, expanding commercial demand for zero-calorie cooking inputs. Stakeholders must monitor evolving EPA guidance on aerosol propellants and emerging state plastic-packaging restrictions that could force simultaneous reformulation of both product chemistry and delivery systems.
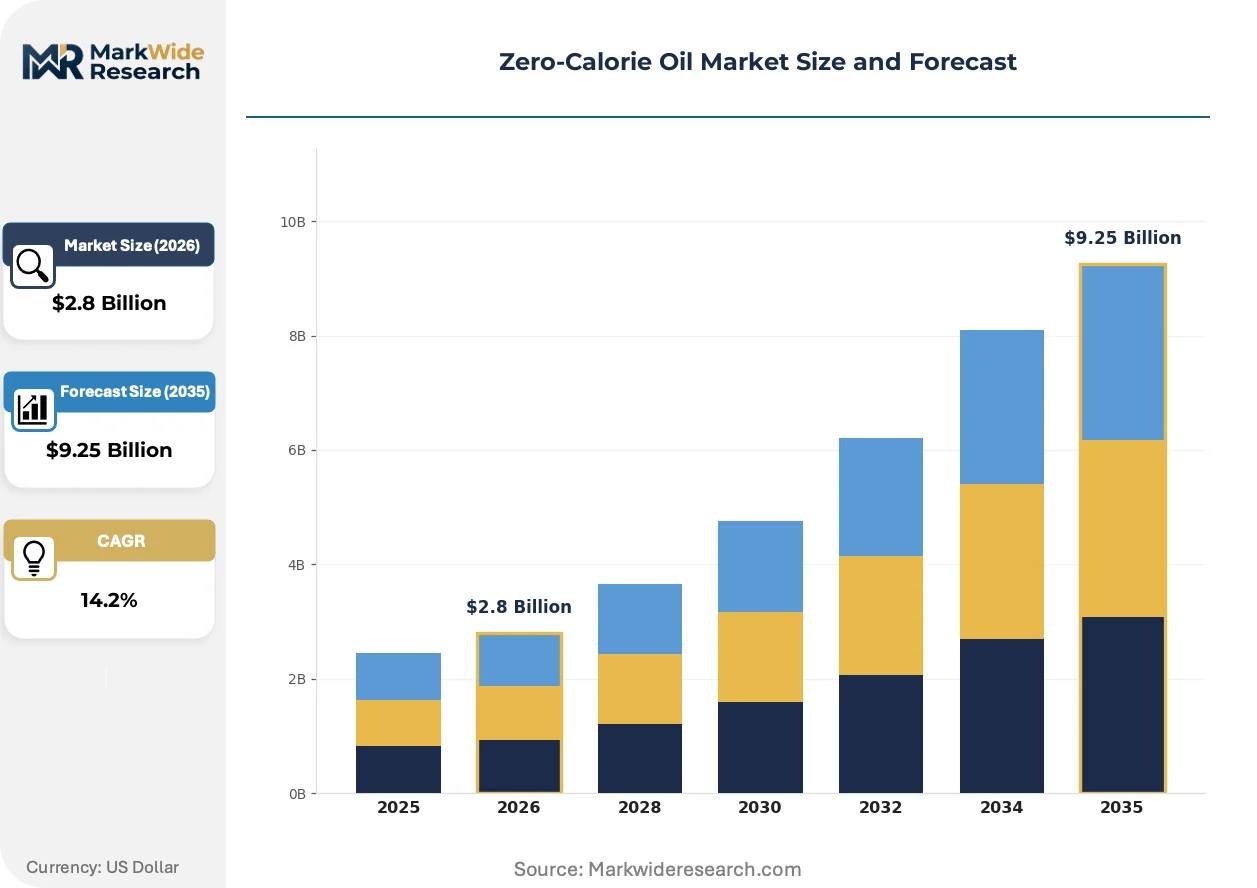
Market Dynamics
Zero-calorie oil manufacturers face intensifying pressure from the FDA's updated nutrition labeling requirements, which mandate stricter serving-size declarations and compress allowable health-claim language. This regulatory compression forces simultaneous reformulation of product chemistry and packaging formats.
Growth Catalysts
- Menu-labeling mandates:California and New York state laws extend compliance obligations to restaurant chains, expanding commercial demand for zero-calorie cooking inputs.
- Health-conscious home cooking:Sustained consumer pivot toward caloric reduction in residential kitchens pulls spray-format and liquid products through retail channels.
- Clean-label reformulation:Food manufacturers accelerate adoption of emulsion-based zero-calorie oils to meet simultaneous reduced-calorie and ingredient-transparency specifications.
Market Restraints
- Olestra chemistry limitations:Sucrose polyester formulations face persistent consumer skepticism due to historical digestive tolerance concerns.
- Aerosol propellant dependency:Spray formats rely on hydrocarbon propellants subject to evolving EPA guidance, creating supply uncertainty.
- Avocado oil input volatility:Premium segment dependence on avocado oil exposes margins to agricultural commodity price swings.
Strategic Opportunities
- Plastic-packaging innovation:Emerging state restrictions on single-use plastics create first-mover advantage for suppliers developing alternative delivery systems.
- Commercial foodservice expansion:Catering services and institutional kitchens represent underpenetrated volume pools for bulk liquid formulations.
- Dual-carbon alignment:China's national dual carbon goals incentivize low-energy-density food ingredients in processed goods manufacturing.
Industry Challenges
- Emulsion stability expertise:Food manufacturers lack sufficient formulation chemists capable of structuring lipid-mimetic systems at scale.
- Dual compliance timelines:Simultaneous reformulation of product chemistry and aerosol propellants strains R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zero-Calorie Oil Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.25 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Liquid Oils, Solid Oils, Emulsions Use Case: Cooking, Baking, Marinating, Grilling Packaging Type: Bottles, Pouches, Cans, Jars End User: Home Cooks, Restaurants, Catering Services, Food Manufacturers |
| Companies Covered | Chosen Foods, La Tourangelle, PAM, Pompeian, Spectrum Naturals, Smart Balance, Ansar Healthy Living, Mazola, Bertolli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zero-Calorie Oil Market Evolving Landscape
Active reformulation across spray, liquid, and emulsion formats is compressing traditional caloric density without sacrificing functional performance. Manufacturers are racing to align chemistry innovation with tightening packaging regulations.
Micro-encapsulation technology is integrating oleogel structuring into spray-format zero-calorie oils. Quick-service restaurants in the United States are piloting these formulations for high-frequency griddle applications. This convergence is integrating portion-control precision with extended shelf stability, compressing waste rates in commercial kitchens.
REACH chemical registration requirements in Europe are tightening scrutiny on sucrose polyester imports and olestra-derived ingredients. The European Chemicals Agency's updated hazard classifications force reformulation of legacy zero-calorie chemistries. Food manufacturers exporting to EU markets are accelerating clean-label emulsion development to preempt compliance disruption.
Restaurant procurement departments are consolidating supplier contracts around national distribution networks with verified calorie-certification protocols. Mid-market grocery segments are displacing fragmented local oil suppliers with centralized direct-store-delivery arrangements. This consolidation is most visible in United States foodservice, where chain operators demand uniform ingredient documentation across multi-state footprints.
Zero-Calorie Oil Market Segmentation
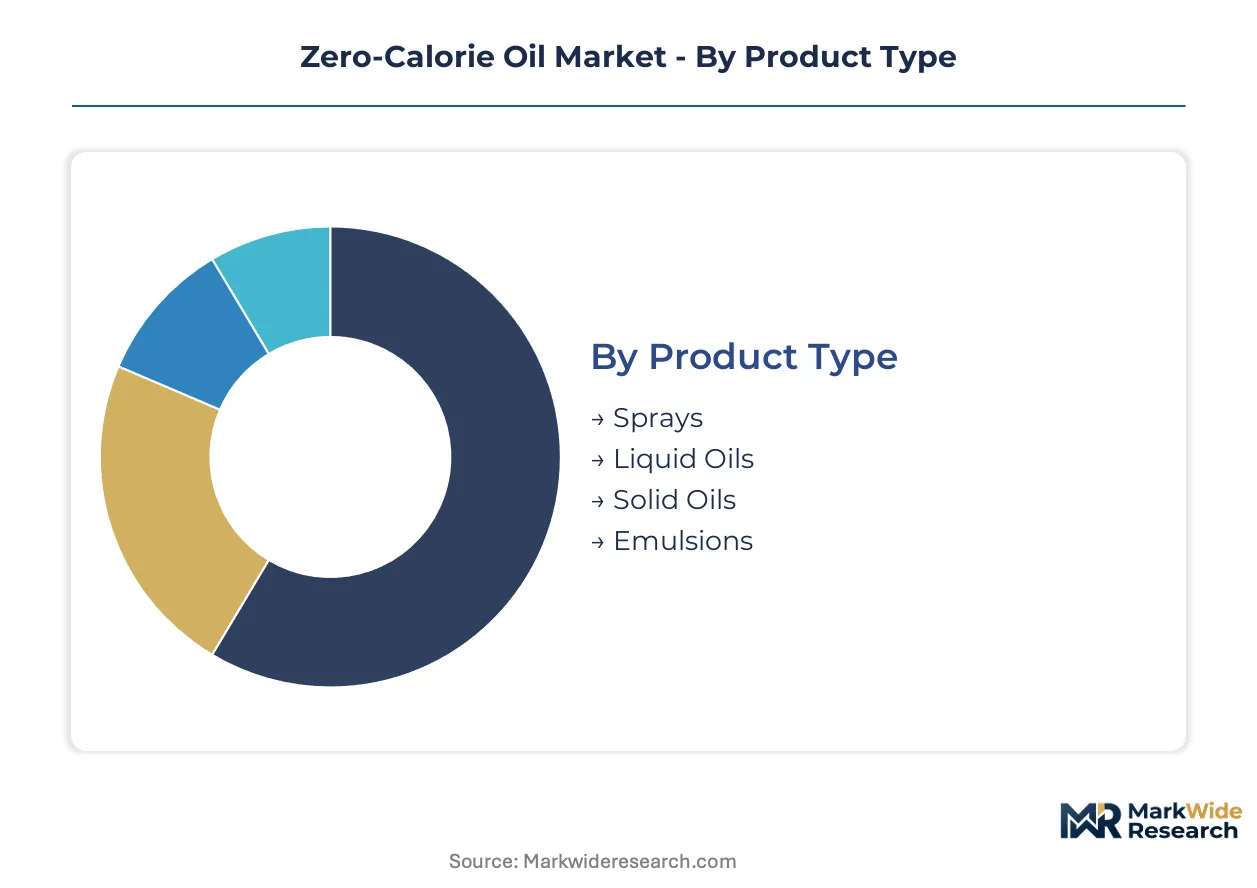
Zero-calorie oil manufacturers structure product portfolios around four intersecting dimensions: delivery format, culinary application, containment system, and buyer sophistication. Each axis creates distinct margin profiles and compliance obligations that reshape competitive positioning across retail and foodservice channels.
Product Type:
Spray formats operate as standalone consumer-facing systems with embedded propellant and metering technology, while emulsions embed deeply into processed food manufacturing workflows requiring ingredient integration.
- Sprays:Aerosol-dispensed formulations combine hydrocarbon propellants with sub-five-calorie serving precision. Demand concentrates in United States home kitchens and quick-service restaurant griddle stations where portion control and waste reduction drive procurement.
- Emulsions:Water-in-oil structured systems deliver lipid-mimetic functionality for clean-label reformulation. Food manufacturers in California and New York accelerate adoption to satisfy simultaneous menu-labeling mandates and reduced-calorie specifications.
- Liquid Oils:Pourable zero-calorie formulations for sautéing and dressing applications.
- Solid Oils:Spoonable and spreadable formats for baking and topping use cases.
Volume placements concentrate in sprays; the faster expansion belongs to emulsions.
Use Case:
Cooking applications dominate unit economics through high-frequency replenishment, while baking commands premium positioning through performance-critical formulation requirements.
- Cooking:Sautéing and pan-frying applications demand thermal stability above smoke-point thresholds. Restaurants in California deploy zero-calorie cooking oils to comply with state menu-labeling mandates while maintaining griddle throughput.
- Baking:Creaming and tenderizing functions require fat-mimetic structuring that preserves crumb texture. Commercial bakeries in New York metropolitan area pilot emulsion-based zero-calorie formulations to reduce caloric density without compromising product integrity.
- Marinating:Flavor-carrying and surface-coating applications for protein preparation.
- Grilling:High-heat searing and anti-stick functionality for open-flame cooking environments.
Restaurants and catering services anchor cooking volume; baking applications are climbing the fastest as clean-label reformulation accelerates.
Packaging Type:
Cost tiers separate premium glass containment from commodity flexible formats, with sustainability mandates now forcing convergence on circular-material alternatives.
- Bottles:Rigid PET and glass containment for liquid zero-calorie oils with transparency and shelf-stability requirements. Mid-market grocery segments in the United States favor bottle formats for home cook visibility and controlled pouring.
- Pouches:Flexible laminated films reduce material intensity and shipping cube for institutional buyers. Catering services expanding procurement of zero-calorie oils specify pouches for bulk liquid formulations in high-volume kitchen environments.
- Cans:Metal containment for spray-format propellant systems and oxygen-sensitive formulations.
- Jars:Wide-mouth glass or plastic containment for solid oil scooping and spreading applications.
Home cooks and restaurants drive bottle placements; pouches are gaining share fastest through foodservice consolidation.
End User:
Customer sophistication tiers separate formulation-naive residential buyers from procurement departments demanding certificate-of-analysis documentation and national distribution scale.
- Home Cooks:Health-conscious residential consumers purchasing through retail channels for caloric reduction in family meal preparation. Spray formats lead unit volume in this segment due to portion-control precision and reduced waste.
- Restaurants:Chain and independent foodservice operators with multi-state compliance obligations. Menu-labeling mandates in California and New York extend procurement requirements to zero-calorie cooking inputs with verified calorie-certification protocols.
- Catering Services:Institutional and event foodservice providers with batch-cooking scale and cost-control priorities.
- Food Manufacturers:Processed goods producers reformulating to meet FDA nutrition labeling requirements and clean-label specifications simultaneously.
Restaurants and catering services concentrate volume placements; food manufacturers represent the steepest expansion trajectory as emulsion adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households and restaurant chains concentrate procurement of zero-calorie oils through spray and liquid formats. FDA nutrition labeling mandates and state menu-labeling laws in California and New York compress allowable health claims and reshape retail placement eligibility. The USDA dietary guidelines reinforce caloric reduction messaging that sustains consumer pull across residential and commercial channels.
United States
Health-conscious home cooking trends and quick-service restaurant expansion drive spray-format demand through retail and foodservice channels. California and New York state menu-labeling mandates extend compliance obligations to chain operators, forcing verified calorie-certification protocols. Metropolitan clusters in Los Angeles and New York City pilot emulsion-based zero-calorie formulations for clean-label reformulation in commercial bakeries.
Germany
REACH chemical registration requirements tighten scrutiny on sucrose polyester imports and olestra-derived ingredients entering processed food manufacturing. The European Chemicals Agency's updated hazard classifications force reformulation of legacy zero-calorie chemistries. Industrial food processing corridors in Bavaria accelerate clean-label emulsion development to maintain EU market access.
China
National dual carbon goals incentivize low-energy-density food ingredients across processed goods manufacturing. SAMR nutrition labeling standards align with clean-label specifications that favor emulsion-based fat mimetic systems. Yangtze River Delta food manufacturers expand procurement of zero-calorie oil emulsions to meet simultaneous export compliance and domestic sustainability targets.
Japan
METI industrial standards and PMDA food additive regulations shape permissible formulation chemistries for lipid-mimetic systems. Health-conscious aging demographics sustain residential demand for portion-controlled spray formats. Osaka-Kobe industrial clusters develop micro-encapsulation technologies for oleogel structuring in high-frequency commercial kitchen applications.
United Kingdom
FSA calorie reduction targets and NHS healthy eating campaigns compress permissible caloric density in manufactured foods and restaurant offerings. London metropolitan restaurant chains consolidate procurement around national distribution networks with verified documentation. Southeast England food technology clusters pilot plastic-alternative packaging for spray-format delivery systems ahead of emerging single-use restrictions.
Zero-Calorie Oil Market Competitive Landscape
United States producers anchor one tier of supply; European specialists hold formulation chemistry advantages in emulsion structuring. The vendor base separates into three concentration levels: multinational oil processors with national distribution networks, regional avocado and olive oil specialists leveraging agricultural heritage positioning, and private-label manufacturers serving mid-market grocery consolidation. Three archetypes dominate: spray-format aerosol specialists, clean-label emulsion developers, and portfolio-diversified cooking oil houses. Competitive moves concentrate on M&A for distribution scale and simultaneous reformulation of product chemistry alongside packaging alternatives.
Within the heritage-positioned tier, Pompeian and Bertolli occupy positions shaped by Mediterranean culinary association and broad cooking-oil portfolio breadth. Chosen Foods anchors the avocado-oil-specialist archetype through supply chain expertise in premium retail channels. Mazola exemplifies the mid-market grocery segment through corn-oil-derived zero-calorie formulations and established supermarket placement. These three represent distinct competitive vectors: geographic heritage, agricultural input specialization, and commodity-scale distribution.
| Leading Market Players |
|---|
| Chosen Foods |
| La Tourangelle |
| PAM |
| Pompeian |
| Spectrum Naturals |
| Smart Balance |
| Ansar Healthy Living |
| Mazola |
| Bertolli |
| Others |
Value Network & Pricing Analysis
Formulation chemist concentration in Germany's industrial processing corridors and the United States' food technology clusters drives labor-cost differentials that widen pricing-tier spreads between emulsion-specialist suppliers and commodity-scale aerosol manufacturers.
Pricing Analysis
Volume placements concentrate in spray formats while emulsions capture premium-margin pools. Three-tier pricing structure across premium, standard, and economy levels separates avocado-oil-derived formulations from corn-oil-based alternatives and private-label commodity sprays. Pricing pressure stems from EPA guidance uncertainty on hydrocarbon propellants forcing simultaneous chemistry and packaging reformulation. Food manufacturers exhibit highest price sensitivity due to bulk procurement scale, while health-conscious home cooks in premium retail channels show lowest elasticity.
Supply Chain Analysis
Reverse-logistics flows for refillable spray systems and bulk pouch returns are emerging in institutional catering channels seeking to reduce packaging waste compliance costs. Raw material sourcing draws from Mexico and California for avocado oil, the United States Corn Belt for commodity feedstocks, and Bavaria for emulsion structuring agents. Single-source vulnerability concentrates in olestra-derived sucrose polyester chemistry subject to REACH registration disruption. Distribution runs through national grocery networks for retail spray formats and direct-store-delivery arrangements for foodservice liquid and emulsion volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around suppliers with simultaneous chemistry and packaging reformulation capabilities, as FDA and state menu-labeling mandates force weaker players without R&D scale toward exit.
For Market Incumbents: Cement national distribution network coverage to defend against regional avocado oil specialists expanding beyond premium retail. Deepen backward integration into emulsion structuring chemistry to preempt REACH-driven supply disruption. Prioritize aerosol propellant alternatives ahead of EPA guidance finalization to capture first-mover positioning in spray-format innovation. For New Entrants and Emerging Players: Begin with institutional catering services and commercial bakeries in menu-labeling states as underpenetrated volume pools lacking verified calorie-certification protocols. Target emulsion-based clean-label formulations where incumbent capacity constraints create white-space opportunity. Pursue direct technical sales to food manufacturer R&D departments rather than retail channel slotting contests. For Investors and Strategic Acquirers: Re-rating potential sits with clean-label emulsion developers given FDA nutrition labeling compression forcing simultaneous reduced-calorie and ingredient-transparency reformulation. Long-term viability favors suppliers with dual competence in lipid-mimetic chemistry and sustainable packaging systems. Monitor EPA propellant guidance timeline and California plastic-packaging restriction implementation as inflection signals for delivery-system disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Emulsion Chemistry Scale-Up | Clean-label reformulation demand from California and New York food manufacturers accelerates capacity requirements. |
| Aerosol Propellant Transition | EPA guidance evolution creates competitive differentiation for hydrocarbon-alternative spray systems. |
| Direct-Store-Delivery Expansion | Mid-market grocery consolidation favors suppliers with national logistics footprints over fragmented local distributors. |
| Backward Integration into Avocado Supply | Agricultural commodity price volatility exposure compresses margins for non-integrated premium segment competitors. |
| Menu-Labeling Compliance Certification | California and New York state mandates create procurement gatekeeping function for verified documentation protocols. |
Research Methodology
Trade databases, FDA filing records, and state regulatory registers formed the secondary backbone, supplemented by primary interviews with food manufacturer R&D directors, restaurant chain procurement officers, emulsion formulation chemists, and retail category buyers. Bottom-up volume estimates triangulated against top-down market sizing derived from customs data and grocery channel audit records.
Historical trendline analysis across spray, liquid, and emulsion delivery formats established baseline growth patterns, with segmentation modeling across product type, use case, packaging format, and end-user sophistication tiers. CAGRs were derived from weighted regression across the projection horizon incorporating FDA regulatory timeline assumptions and state menu-labeling adoption curves.
Agricultural commodity price shocks, EPA propellant guidance revision, and REACH chemical reclassification are the dominant revision risks that could compress or extend growth trajectories. Practitioners should monitor California plastic-packaging restriction implementation and SAMR nutrition labeling alignment in China for early signals of delivery-system disruption and geographic demand shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Collagen Casings Market
Ingredients
Carotenes Market
Ingredients
Konjac Flour Market
Ingredients
Passion Fruit Powder Market
Ingredients
Europe Feed Yeast Market
Ingredients
Vegan Baking Ingredients Market
Ingredients
Feed Ingredients Market
Ingredients
Coconut Derivatives Market
Ingredients
Pet Food Premix Market
Ingredients
EPA and DHA Omega-3 Ingredient Market
Ingredients
Spray-Dried Isolate Market
Ingredients
Low Calorie Cooking Oil Market
Ingredients
Xylooligosaccharide Market
Ingredients
Wheat Malt Market
Ingredients
Cognitive Ingredients Market
Ingredients
South America Agar Market