
 2-Ethyl Hexanol Market | 2026-2036
2-Ethyl Hexanol Market Size, Share, and Industry Trends Forecast 2026-2036
2-Ethyl Hexanol Market Outlook
Multi-source procurement for propylene feedstock is realigning how 2-ethyl hexanol producers manage margin volatility across the oxo-alcohol chain. BASF SE leverages backward integration into cracker operations to sustain cost discipline at its Ludwigshafen complex. Dow Inc. anchors North American supply through its Texas Gulf Coast infrastructure, while SABIC competes on scale from its Jubail manufacturing base with direct pipeline access to Saudi ethylene.
2-Ethyl hexanol is a branched-chain C8 alcohol produced via propylene hydroformylation and subsequent hydrogenation, with a purity specification typically exceeding 99.5% and a boiling point of 184-185°C; it functions primarily as a chemical building block for plasticizers, coatings, and specialty solvents. The plasticizer segment dominates volume consumption as di-2-ethylhexyl phthalate and alternative esters anchor flexible PVC demand across construction and automotive end uses. Chemical intermediate applications represent the fastest-growing category as manufacturers develop non-phthalate plasticizer routes to meet evolving product safety standards.
REACH registration requirements in Europe and EPA toxic substance controls in the United States shape formulation choices by restricting legacy phthalate concentrations in consumer-facing applications. China's GB standards and MEES environmental compliance protocols drive domestic producers toward cleaner oxo-alcohol process technologies with lower emission profiles. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation timelines and secure alternative ester certifications before compliance deadlines tighten.
Market Dynamics
Propylene feedstock volatility and the accelerating shift from phthalate to non-phthalate plasticizers are restructuring margin capture across the oxo-alcohol value chain, forcing producers to recalibrate integration strategies and regional supply positioning.
Growth Catalysts
- REACH phthalate restrictions:European ECHA classifications on endocrine-disrupting substances are compelling PVC compounders to reformulate around 2-ethyl hexanol-based adipate and trimellitate esters.
- Construction sector recovery in China:Infrastructure stimulus and automotive wire harness demand are absorbing expanded domestic oxo-alcohol capacity through captive plasticizer offtake.
- Low-emission oxo process technology:Advanced hydrogenation catalysts are reducing carbon intensity per ton, aligning output with EU Green Deal embedded carbon thresholds for chemical imports.
Market Restraints
- Propylene cost volatility:Steam cracker operating rate cuts in Western Europe and naphtha price swings are compressing oxo-alcohol spreads without long-term feedstock contracts.
- Supply concentration in Middle East:Saudi ethane-based ethylene pipeline access grants SABIC and regional competitors structural feedstock cost advantages that naphtha-dependent producers cannot match.
- Technical limitation in bio-based routes:Fermentation-derived C8 alcohols remain cost-prohibitive at scale, blocking premium positioning for sustainability-driven buyers.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic wire and cable manufacturing incentives are creating localized demand for non-phthalate plasticizer feedstock as OEMs localize supply chains.
- Coating solvent convergence:Waterborne acrylic and polyurethane systems are incorporating 2-ethyl hexanol esters as coalescing agents, opening formulations beyond traditional PVC applications.
- EU CSRD supply chain disclosure:Mandatory Scope 3 emissions reporting is rewarding producers with verified low-carbon process certifications in customer procurement scorecards.
Industry Challenges
- Process control engineering talent:Advanced hydroformylation unit operation requires specialized expertise that aging workforces in Western Europe and North America are struggling to replenish.
- Multi-jurisdiction certification timelines:Securing EPA TSCA, REACH, and China MEE registrations simultaneously for new ester derivatives extends commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-Ethyl Hexanol Market |
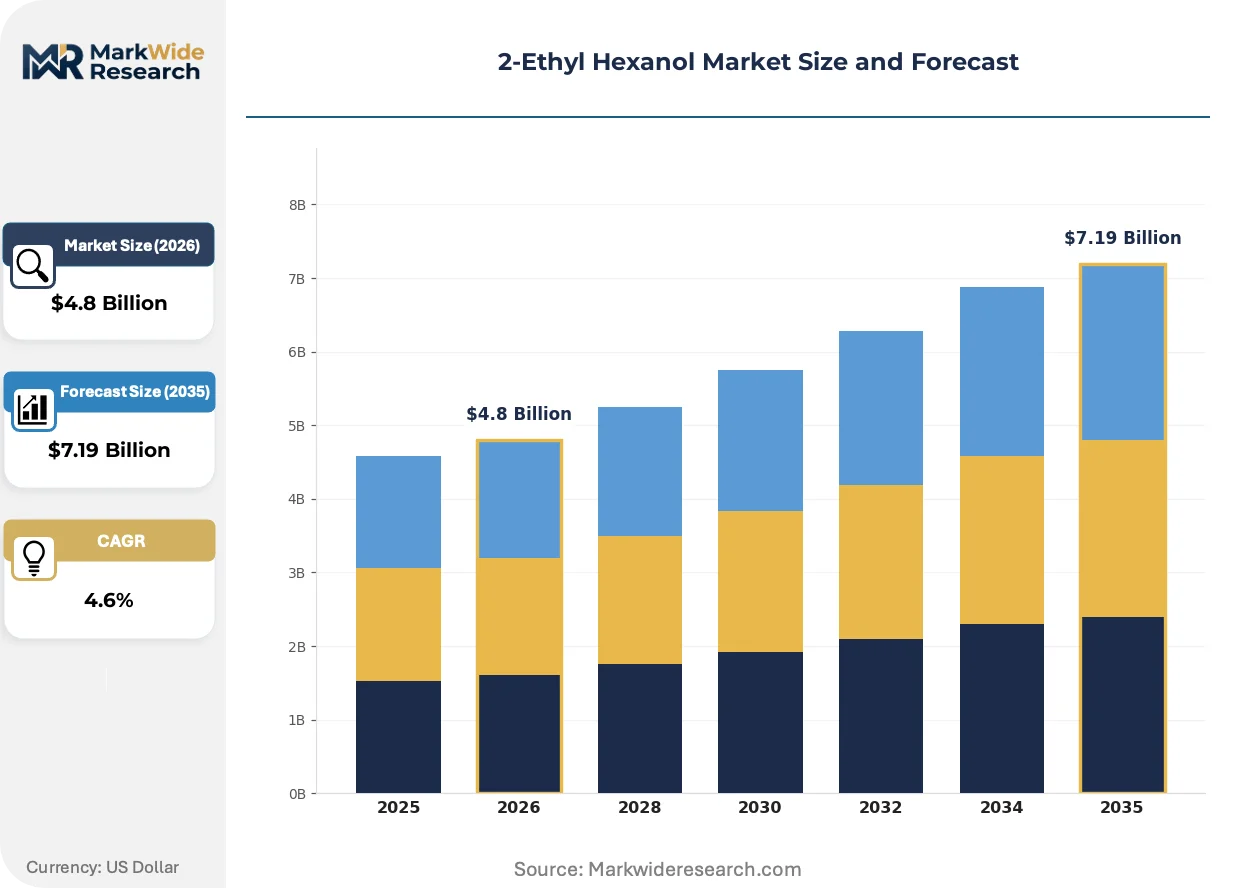
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Plasticizer, Chemical Intermediate, Adhesive Application: Coatings, Cosmetics, Detergents, Textile End User: Construction, Automotive, Personal Care, Pharmaceuticals Distribution Channel: Direct Sales, Wholesalers, Retailers, Online Platforms |
| Companies Covered | BASF SE, Eastman Chemical Company, Dow Inc., SABIC, Sinopec, Mitsubishi Chemical Corporation, LG Chem, Ltd., INEOS Holdings Ltd., Formosa Plastic Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Ethyl Hexanol Market Strategic Shifts
Process intensification and regulatory chemistry are converging to redefine competitive advantage, with technology adoption rates now determined by compliance velocity rather than standalone efficiency metrics.
Membrane-based propylene purification is unifying feedstock quality standards across regional oxo-alcohol plants, enabling consistent hydroformylation yields previously achievable only at integrated petrochemical complexes. Specialty chemical producers in Germany and Japan are retrofitting standalone units with this technology to compete on specification reliability. The structural consequence is compressing the premium historically commanded by fully backward-integrated suppliers.
REACH authorization requirements for di-2-ethylhexyl phthalate are forcing compounders to validate alternative plasticizer performance in medical device and childcare applications. ECHA's sunset date enforcement is accelerating substitution timelines, with automotive interior specifications leading the transition. Tier-1 suppliers are now requiring certified non-phthalate ester documentation upstream of formulation commitments.
Automotive OEMs are consolidating plasticizer procurement through direct masterbatch supplier relationships, bypassing traditional distributor channels for volume commitments. This disintermediation concentrates negotiating leverage with compounders possessing in-house esterification and technical service capabilities. The pattern is most pronounced in Germany and South Korea, where Just-in-Sequence manufacturing demands real-time formulation adjustments.
2-Ethyl Hexanol Market Segmentation
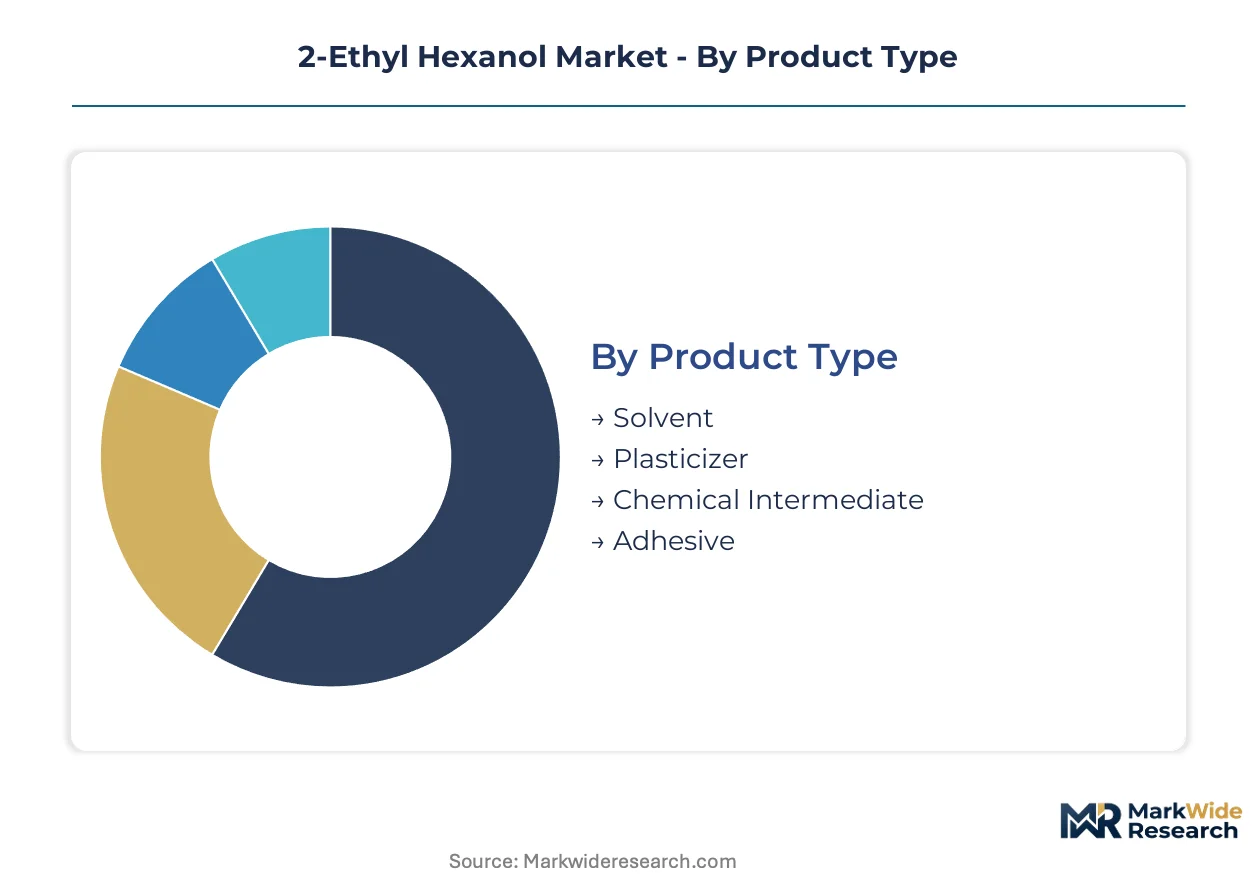
Segmentation in 2-ethyl hexanol reveals how formulation specifications diverge across regulatory jurisdictions and end-use performance requirements. Understanding these divides allows producers to align capacity investments with the highest-margin application clusters.
Product Type:
Standardization dominates commodity solvent and plasticizer grades, while chemical intermediate and adhesive segments demand tighter purity tolerances and custom esterification protocols.
- Solvent:Technical-grade 2-ethyl hexanol serves as a coalescing agent in waterborne coatings and a carrier solvent for agricultural formulations. Demand concentrates in Germany's automotive refinish sector where VOC regulations under EU F-Gas Regulation restrict conventional hydrocarbon alternatives.
- Plasticizer:Di-2-ethylhexyl phthalate and non-phthalate esters anchor flexible PVC demand across wire insulation and flooring applications. China's construction stimulus is absorbing expanded domestic oxo-alcohol capacity through captive plasticizer offtake for infrastructure projects.
- Chemical Intermediate:Feedstock for adipate and trimellitate esters used in medical device and childcare applications requiring REACH-compliant non-phthalate certification.
- Adhesive:Specialized grades for pressure-sensitive tapes and sealants with low residual aldehyde specifications.
Leading the category by volume: Plasticizer. Expanding most quickly: Chemical Intermediate.
Application:
Volume scale separates industrial coatings from niche personal care uses, with margin structure inverting toward specialty formulations.
- Coatings:Architectural and industrial formulations employ 2-ethyl hexanol esters as coalescing agents to lower minimum film formation temperature in waterborne acrylic systems. South Korea's automotive OEMs specify certified low-VOC grades for Just-in-Sequence manufacturing.
- Cosmetics:Ultra-high purity grades function as emollients and solvent carriers in fragrance compounds and skincare formulations. EU ECHA scrutiny on endocrine-disrupting substances is forcing reformulation validation timelines.
- Detergents:Surfactant intermediate for ethoxylated alcohols in household and industrial cleaning products.
- Textile:Softening agent and dye carrier for synthetic fiber processing.
Dominant by tonnage: Coatings. Steepest expansion trajectory: Cosmetics.
End User:
Construction and automotive buyers negotiate on scale and specification reliability, while personal care and pharmaceutical segments pay premiums for traceability documentation.
- Construction:PVC flooring, wall coverings, and waterproofing membranes consume plasticizer-grade material in bulk volumes. India's infrastructure stimulus is creating localized demand clusters around Mumbai and Delhi industrial corridors.
- Automotive:Wire harness insulation and interior trim specifications are transitioning to certified non-phthalate esters ahead of ECHA sunset dates. Tier-1 suppliers in Germany and South Korea now require upstream documentation of alternative plasticizer routes.
- Personal Care:Fragrance and cosmetic formulators demand batch-level purity certificates and contaminant screening.
- Pharmaceuticals:Excipient-grade material for oral and topical drug delivery systems with US FDA and EMA compliance documentation.
Construction leads volume. Pharmaceuticals climb fastest on regulatory substitution.
Distribution Channel:
Direct relationships concentrate in automotive and construction, while fragmented personal care buyers rely on distributor technical service.
- Direct Sales:Long-term offtake agreements with integrated PVC compounders and automotive Tier-1 suppliers. BASF SE and Dow Inc. anchor North American and European supply through pipeline and railcar commitments.
- Wholesalers:Regional distributors stock standard solvent and plasticizer grades for mid-tier coatings and adhesive manufacturers.
- Retailers:Limited presence for small-volume specialty grades in laboratory and pilot-scale quantities.
- Online Platforms:Emerging channel for technical documentation access and sample ordering, though bulk transactions remain relationship-driven.
Direct Sales commands volume. Online Platforms gain share fastest on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene availability and oxo-alcohol integration density vary sharply across production geographies. China, Germany, the United States, Saudi Arabia, and South Korea concentrate capacity and shape trade flows through distinct feedstock advantages and regulatory postures.
China
Domestic propylene supply from coal-to-olefins and PDH units supports massive oxo-alcohol capacity expansion. GB standards and MEE environmental compliance protocols enforce cleaner process technologies. Ningbo and Nanjing industrial clusters host integrated plasticizer manufacturing absorbing captive 2-ethyl hexanol output for construction and automotive wire harness demand.
Germany
Ludwigshafen's cracker-integrated oxo-alcohol complex anchors European supply with pipeline-connected feedstock security. REACH authorization deadlines for phthalate plasticizers accelerate reformulation toward adipate and trimellitate esters. The Rhine-Neckar chemical cluster concentrates technical service capabilities for automotive Tier-1 suppliers demanding certified non-phthalate documentation.
United States
Texas Gulf Coast ethylene and propylene infrastructure supports oxo-alcohol production with shale-advantaged feedstock costs. EPA TSCA requirements shape alternative plasticizer commercialization timelines for consumer-facing applications. Houston and Corpus Christi chemical corridors concentrate export-oriented capacity serving Latin American plasticizer compounders.
Saudi Arabia
Jubail's ethane-based ethylene pipeline grants structural cost advantages through direct cracker integration. SABIC operates at scale with minimal feedstock price volatility compared to naphtha-dependent competitors. The Eastern Province industrial city anchors Middle Eastern supply serving South Asian and African plasticizer markets through dedicated shipping terminals.
South Korea
Yeosu and Ulsan petrochemical complexes produce oxo-alcohol for automotive wire harness and interior trim specifications. MFDS chemical safety standards align with ECHA sunset dates, accelerating non-phthalate validation. Just-in-Sequence manufacturing demands from Hyundai and Kia concentrate technical service requirements around real-time formulation adjustments.
2-Ethyl Hexanol Market Competitive Environment
Backward integration into cracker and propylene operations dominates the current landscape as producers defend margin structures against feedstock volatility. The market structure consolidates around three tiers: fully integrated petrochemical majors with pipeline feedstock access, regional oxo-alcohol specialists with merchant propylene supply, and captive producers serving internal plasticizer demand. Strategic archetypes include feedstock-integrated volume leaders, specification-focused specialty suppliers, and construction-driven regional champions. Competitive moves concentrate on securing long-term propylene offtake contracts and accelerating non-phthalate ester certification timelines ahead of regulatory deadlines.
Among European-integrated majors, BASF SE anchors the feedstock-integrated archetype through its Ludwigshafen complex operations. Dow Inc. represents North American Gulf Coast positioning with Texas infrastructure advantages. SABIC exemplifies the Middle Eastern scale-driven model with Jubail manufacturing and ethane pipeline economics. Mitsubishi Chemical Corporation and LG Chem, Ltd. occupy positions within the Asia-Pacific specialist tier, each reflecting distinct national industrial structures and regional demand access patterns.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Dow Inc. |
| SABIC |
| Sinopec |
| Mitsubishi Chemical Corporation |
| LG Chem, Ltd. |
| INEOS Holdings Ltd. |
| Formosa Plastic Group |
| Others |
Value Chain & Pricing Dynamics
Automotive Tier-1 suppliers in Germany and South Korea negotiate contract-based long-term offtake agreements that compress spot market liquidity and anchor pricing around specification reliability rather than commodity benchmarks. This buyer concentration forces producers to bundle technical service and certification documentation into base pricing, unbundling only logistics and storage as variable adders.
Pricing Analysis
Technical service bundling dominates contract structures, with REACH-compliant certification and batch-level traceability documentation included in standard quotes while dedicated technical support and emergency supply guarantees carry surcharges. Price differentiation hinges on purity grade and ECHA registration status, with pharmaceutical-grade material commanding substantial premiums over technical solvent grades. Cost compression in standard plasticizer grades is intensifying because of propylene feedstock volatility and expanded Chinese domestic capacity. Construction sector buyers exhibit highest price sensitivity due to volume scale and captive supply alternatives, while pharmaceutical and personal care segments prioritize specification certainty over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from automotive OEMs require Tier-1 compounders to qualify minimum two 2-ethyl hexanol suppliers per production region, fragmenting volume commitments across BASF, Dow, SABIC, and regional Asian producers. Manufacturing concentrates in China, Germany, and Saudi Arabia, with feedstock economics determining competitive positioning. Production draws from propylene hydroformylation, with hydrogen and synthesis gas as critical co-inputs. Single-source vulnerability around specialized hydrogenation catalyst suppliers poses structural risk. Distribution runs through pipeline and railcar networks for integrated majors, with regional distributors handling fragmented specialty grade demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH authorization timelines for phthalate alternatives create a barrier-to-entry moat for producers with validated non-phthalate ester certifications and ECHA-registered supply chains.
For Market Incumbents: Extend certification coverage ahead of ECHA sunset date enforcement to capture reformulation demand from medical device and childcare application compounders. Deepen backward integration into propylene supply through long-term offtake contracts or cracker joint ventures to defend margin structures against naphtha price volatility. Lock in automotive Tier-1 direct supply relationships before alternative ester qualification windows close. For New Entrants and Emerging Players: The premium-to-economy price gap in pharmaceutical-grade material offers entry opportunity for specialty producers with US FDA and EMA compliance capabilities. Target India's PLI-driven automotive wire harness manufacturing clusters with localized technical service presence. Penetrate through certified non-phthalate intermediate supply to compounders lacking in-house esterification capacity. For Investors and Strategic Acquirers: The window for entry favors regional oxo-alcohol specialists with merchant propylene access and established automotive supply relationships in undersupplied geographies. Mid-term viability centers on producers with demonstrated regulatory compliance velocity and low-carbon process certifications aligned with EU CSRD disclosure requirements. Watch for ECHA enforcement acceleration on di-2-ethylhexyl phthalate authorization withdrawals as inflection signal for substitution demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Long-term cracker offtake contracts with SABIC or Dow anchor feedstock cost discipline against naphtha volatility. |
| Non-Phthalate Ester Certification Investment | REACH-compliant adipate and trimellitate validation opens medical device and automotive interior substitution demand. |
| Regional Capacity Expansion in India | PLI scheme automotive incentives create localized supply advantage for wire harness plasticizer feedstock. |
| Low-Carbon Process Technology Retrofit | Advanced hydrogenation catalysts align output with EU Green Deal embedded carbon thresholds for chemical imports. |
| Direct Supply Agreement with Tier-1 Compounders | Automotive OEM disintermediation concentrates negotiating leverage with producers possessing technical service capabilities. |
Study Parameters
Document review covered customs and trade flow databases, ECHA REACH registration filings, and SEC 10-K disclosures from listed chemical producers, complemented by interviews with plant operations managers at oxo-alcohol facilities, procurement leads at PVC compounders, and technical directors at plasticizer formulation houses. Secondary validation drew from ACC and Cefic industry reports, MEE environmental compliance filings, and automotive OEM supplier qualification documentation. Bottom-up capacity and consumption estimates were triangulated against top-down value chain analysis.
Cross-referencing historical propylene-to-oxo-alcohol spread patterns with expert panel input on regulatory enforcement timelines shaped the projection framework across the analysis window. Segmentation modeling incorporated product grade tier, end-use industry vertical, regional production hub concentration, and certification status dimensions. CAGRs were derived from demand elasticity coefficients applied to construction and automotive sector output forecasts, with feedstock cost assumptions and regulatory substitution pace as primary sensitivity inputs.
Inputs from ECHA registration databases and automotive supplier qualification records were available through the study window; gaps in real-time propylene contract pricing and confidential Tier-1 compounder inventory levels introduce uncertainty bands around near-term consumption estimates. Forecasts reflect assumptions on REACH enforcement velocity, China infrastructure stimulus continuity, and Middle East ethane feedstock cost persistence. Deviation in ECHA sunset date implementation or sudden propylene supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Mancozeb Market
Bulk Chemicals
Aluminum Sulfate Market
Bulk Chemicals
India Chlorine Market
Bulk Chemicals
Global Vinyl Chloride Monomer Market
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
Stilbene Market
Bulk Chemicals
Sodium Bromide Market
Bulk Chemicals
Sodium Dichromate Market
Bulk Chemicals
Benzyl Acetate Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
North America Acetic Acid Market
Bulk Chemicals
North America Acrylamide Monomer Market
Bulk Chemicals
Heavy Alkyl Benzenes Market
Bulk Chemicals
Dextrin Market
Bulk Chemicals
Chlorotoluenes Market