
 Global Butylated Hydroxytoluene Market | 2026-2036
Global Butylated Hydroxytoluene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Butylated Hydroxytoluene Market Foresight
Natural tocopherol alternatives are realigning antioxidant economics across food and polymer applications. BASF SE leverages its integrated phenolics chain to sustain cost leadership in industrial-grade supply. Eastman Chemical Company anchors North American demand through specialized lubricant additive formulations. Camlin Fine Science dominates pharmaceutical-grade production with tight impurity controls.
Butylated hydroxytoluene is a synthetic lipophilic phenolic antioxidant with the molecular formula C15H24O, manufactured through alkylation of p-cresol with isobutylene under acid catalysis, primarily functioning to interrupt free-radical oxidation in organic substrates. Food Grade BHT commands the largest volume share due to widespread deployment in edible oils and cereals, though Pharmaceutical Grade generates superior margins from stringent USP-NF monograph compliance. Plastic Stabilizers represent the fastest-growing application as polyolefin producers seek thermal degradation protection amid higher processing temperatures.
FDA food additive regulations under 21 CFR 182.3173 govern permissible BHT concentrations in edible products, while REACH restrictions in Europe constrain residual limits in polymer contact applications. China's SAMR enforces GB standards for food-grade antioxidant purity that exceed legacy industrial specifications. Stakeholders must monitor evolving EFSA re-evaluation timelines for synthetic antioxidants and calibrate formulation portfolios between BHT and natural substitute blends accordingly.
Market Dynamics
Antioxidant economics are restructuring around regulatory divergence between synthetic phenolics and natural alternatives, with formulation portfolios splitting across jurisdictions rather than converging on global standards.
Growth Catalysts
- REACH compliance deadlines:European polymer processors are accelerating BHT procurement ahead of anticipated EFSA re-evaluation timelines, front-loading inventory positions before potential restriction scenarios materialize.
- Polyolefin processing temperatures:Higher extrusion speeds in packaging film manufacturing are elevating thermal stabilizer loadings, with BHT remaining cost-competitive against hindered amine alternatives at elevated temperature thresholds.
- India:FSSAI enforcement of antioxidant purity standards in edible oil refining is displacing informal supply channels, consolidating volume toward certified domestic producers capable of USP-NF documentation.
Market Restraints
- Isobutylene feedstock volatility:Cracker output fluctuations and refinery configuration shifts are compressing alkylation margins unpredictably, particularly for non-integrated phenolics producers lacking captive p-cresol supply.
- Natural tocopherol substitution:Vitamin E-derived antioxidants are capturing clean-label positioning in premium cereal and snack applications, constraining BHT volume expansion in brand-sensitive consumer categories.
- China GB standard enforcement:SAMR inspection protocols for food-grade BHT are rejecting legacy industrial material, forcing processor qualification costs that disadvantage smaller compounders.
Strategic Opportunities
- Pharmaceutical-grade niche:USP-NF monograph compliance for BHT in parenteral formulations remains underserved outside Western supply bases, creating margin expansion potential for certified Asian producers.
- Brazil:ANVISA's updated food additive positive lists are formalizing antioxidant usage in processed meat applications previously operating under regulatory ambiguity, opening volume growth in Latin America's largest protein processing market.
- Biopolymer stabilization:PLA and PHA degradation kinetics require tailored phenolic antioxidant packages, with BHT-blend formulations offering performance validation opportunities ahead of standardization.
Industry Challenges
- Analytical chemistry talent scarcity:GC-MS and HPLC method expertise for residual impurity quantification at ppb thresholds is concentrating at specialized contract laboratories, extending internal QC capability buildout timelines.
- Multi-jurisdiction dossier maintenance:Simultaneous FDA food additive notifications, REACH registrations, and FSSAI import clearances are fragmenting regulatory affairs bandwidth, particularly for mid-scale producers without dedicated compliance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Butylated Hydroxytoluene Market |
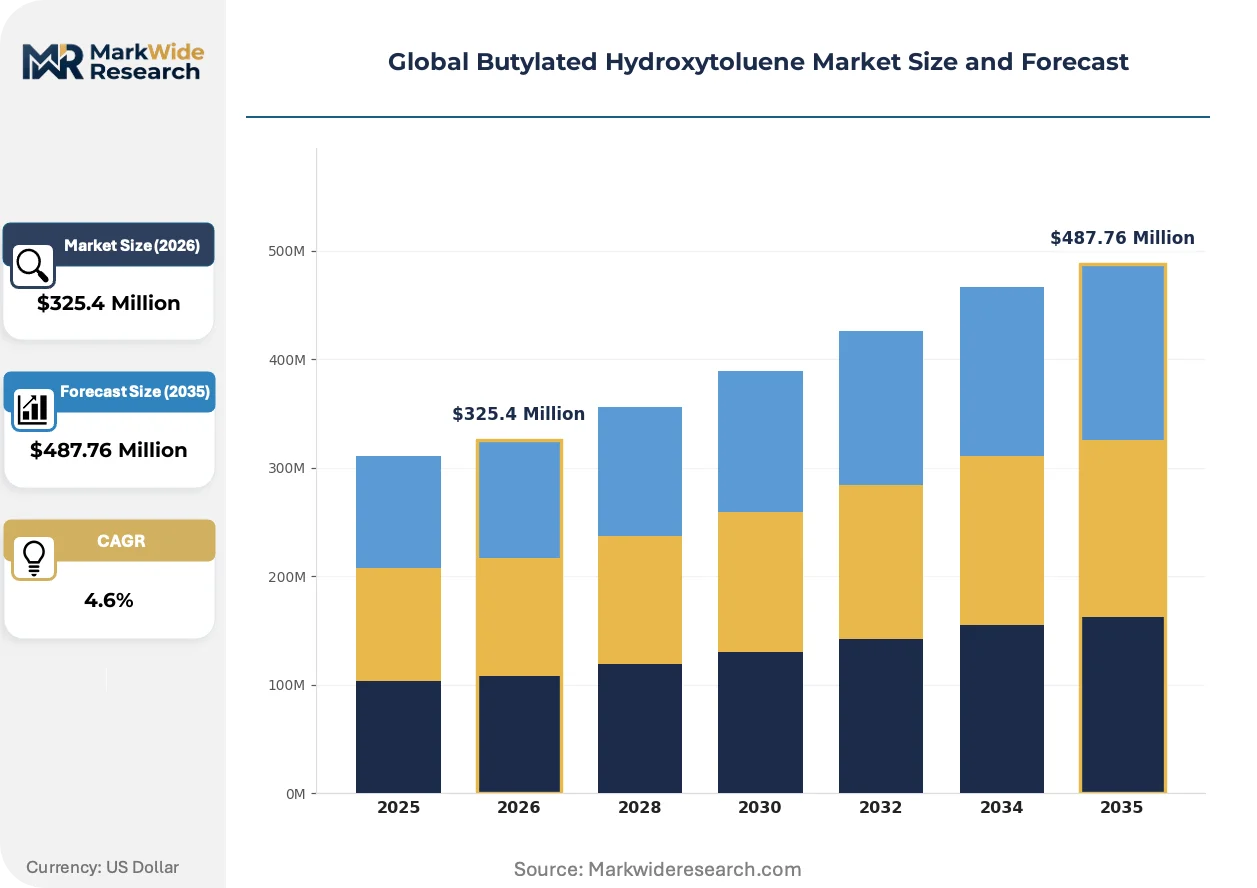
| Market Size in 2026 | $325.4 Million |
| Market Size in 2035 | $487.76 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Cosmetic Grade, Industrial Grade Application: Food Preservation, Animal Feed, Lubricants Additive, Plastic Stabilizers, Fuel Antioxidants End User Industry: Food Processing, Animal Nutrition, Automotive Lubricants, Polymer Manufacturing, Petroleum Refining Packaging Type: Drums, Carboys, Bags, Bulk Containers |
| Companies Covered | BASF SE, Kemin Industries, Sasol Limited, Honshu Chemical Industry Co., Ltd., Camlin Fine Science, Eastman Chemical Company, Oxiris Chemicals S.A., SI Group, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Butylated Hydroxytoluene Market Shifts & Advancements
Formulation science is pivoting toward synergistic antioxidant blends that preserve BHT's cost efficiency while diluting its regulatory exposure through combination with natural or less scrutinized actives.
Microencapsulation technology for controlled-release antioxidant delivery is electrifying shelf-life extension protocols in breakfast cereal and baked goods. Kellogg and General Mills procurement teams are piloting lipid-coated BHT systems that reduce surface migration and permit lower total loadings. This technology is electrifying competitive positioning by decoupling performance from concentration, blunting the natural substitute threat in cost-sensitive categories.
REACH restriction proposals under ECHA SVHC candidate listing procedures are tightening residual limits for BHT in food-contact polymers. German and French packaging converters are pre-emptively reformulating toward BHT-free stabilizer packages to secure retailer acceptance ahead of formal adoption. High-barrier multilayer films for meat and cheese applications are most affected, with converters accelerating alternative phenolic qualification programs.
Direct-procurement relationships between polyolefin producers and antioxidant compounders are displacing traditional distributor intermediaries in Asia-Pacific manufacturing corridors. SABIC and Reliance Industries are negotiating multi-year offtake agreements with phenolics specialists, extracting volume pricing in exchange for technical collaboration on customized stabilizer packages. This consolidation is most visible in Gujarat and eastern Saudi Arabia, where integrated petrochemical complexes are co-locating compounding operations.
Global Butylated Hydroxytoluene Market Segmentation
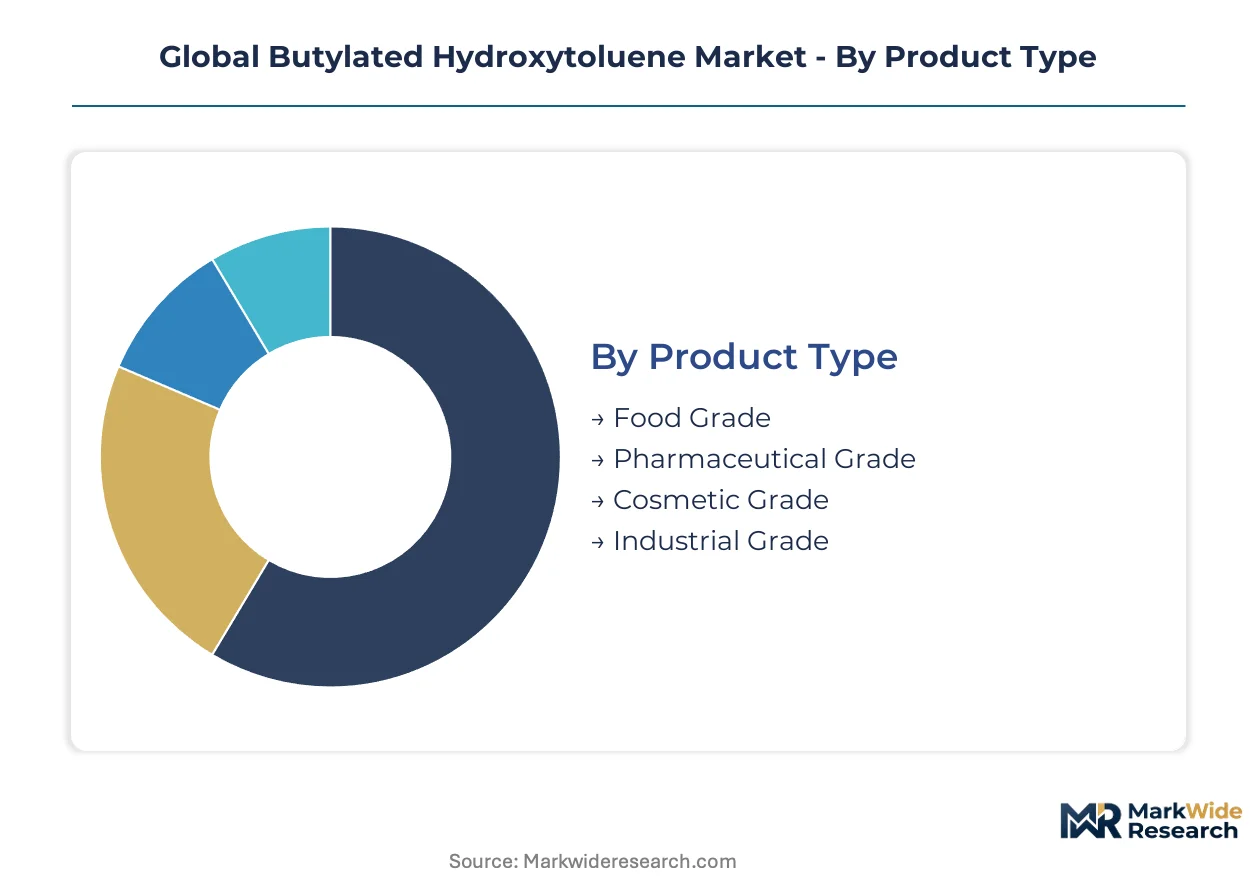
BHT procurement patterns diverge sharply across purity grades and end-use specifications, with regulatory compliance thresholds determining supplier qualification rather than commodity pricing alone. Formulation scientists and procurement officers evaluate antioxidant portfolios through distinct technical lenses that reshape volume allocation across the value chain.
Product Type:
Upgrade cycles in BHT procurement track tightening purity mandates from FDA, EFSA, and China's SAMR, forcing compounders to requalify supply sources as specifications harden.
- Food Grade:Complies with 21 CFR 182.3173 limits for edible oils, cereals, and snack foods. Volume concentrates in Asia-Pacific edible oil refineries, particularly China and India, where FSSAI and GB standard enforcement is displacing informal supply channels toward certified producers.
- Pharmaceutical Grade:Meets USP-NF monograph specifications for parenteral and topical formulations with tight impurity controls at ppb thresholds. Demand concentrates in Western pharmaceutical manufacturing, though certified Asian producers are capturing margin expansion opportunities in underserved supply bases.
- Cosmetic Grade:Conforms to cosmetic directive purity requirements for personal care antioxidant applications.
- Industrial Grade:Serves polymer stabilization and fuel additive applications with less stringent residual specifications.
Volume placements concentrate in Food Grade; the faster expansion belongs to Pharmaceutical Grade.
Application:
Cost tier differentiation separates commodity antioxidant deployments from specialized formulations commanding technical collaboration premiums.
- Food Preservation:Deploys BHT in edible oils, breakfast cereals, and baked goods to interrupt lipid oxidation. Demand clusters in North American and European branded food manufacturing, where clean-label pressures from natural tocopherol alternatives constrain volume in premium categories.
- Plastic Stabilizers:Protects polyolefins against thermal degradation during high-speed extrusion. Growth concentrates in packaging film manufacturing across Germany, France, and Saudi Arabia, where higher processing temperatures elevate stabilizer loadings and REACH pre-compliance drives reformulation urgency.
- Animal Feed:Preserves fat-soluble vitamins and prevents rancidity in compound feeds.
- Lubricants Additive:Extends oxidative stability in engine and industrial oils.
- Fuel Antioxidants:Inhibits gum formation in gasoline and diesel storage.
Food Preservation commands the largest volume base; Plastic Stabilizers are climbing the fastest as polyolefin processing intensifies.
End User Industry:
Customer type fragmentation splits procurement between multinational formulators with dedicated regulatory affairs infrastructure and mid-scale compounders outsourcing compliance documentation.
- Food Processing:Edible oil refiners and cereal manufacturers constitute the foundational demand base.
- Polymer Manufacturing:Polyolefin producers negotiate direct multi-year offtake agreements with antioxidant specialists, extracting volume pricing through technical collaboration on customized stabilizer packages.
- Animal Nutrition:Compound feed mills integrate BHT into vitamin premix formulations.
- Automotive Lubricants:Blenders formulate crankcase and transmission fluids with oxidative stability packages.
- Petroleum Refining:Fuel terminals dose storage and distribution systems with antioxidant additives.
Food Processing retains the deepest volume footprint; Polymer Manufacturing is gaining share fastest through direct procurement consolidation.
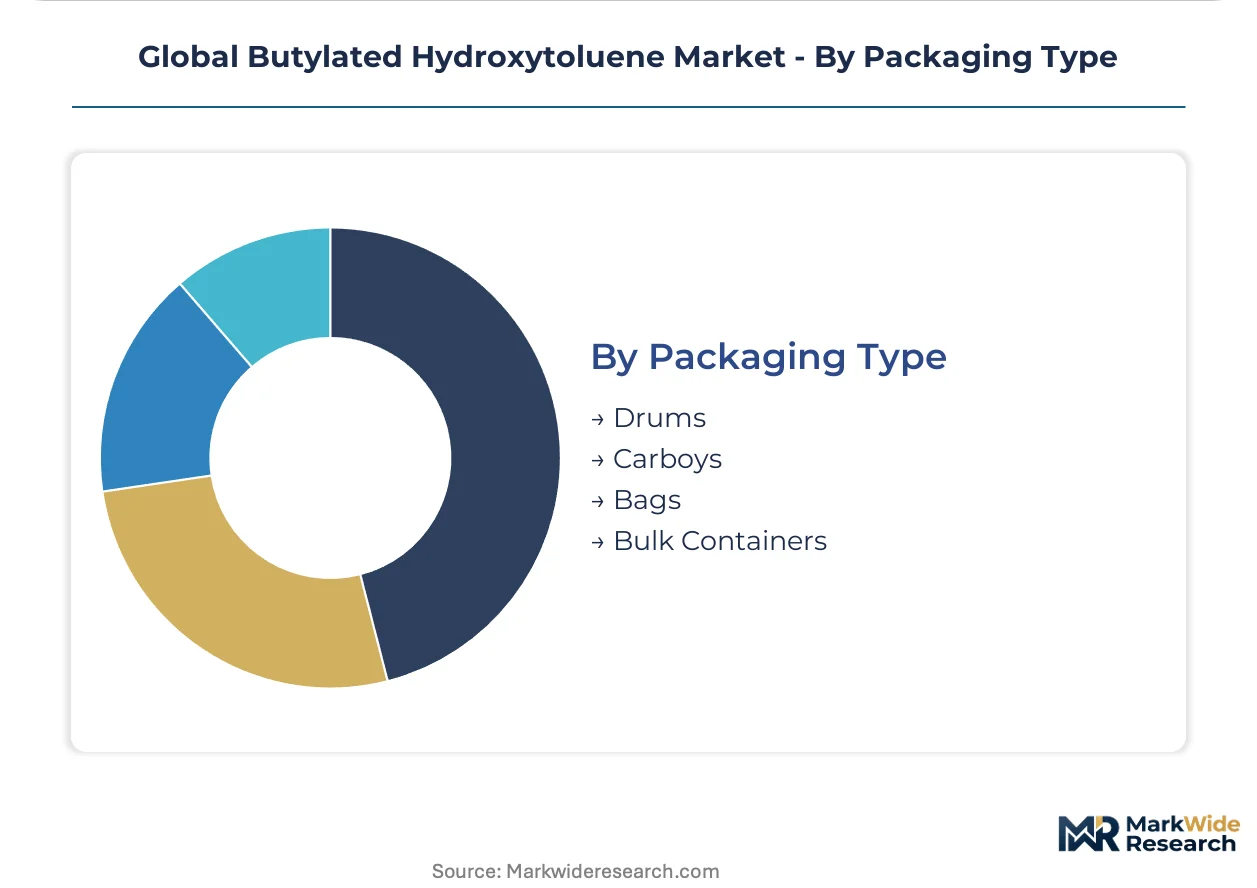
Packaging Type:
Supply concentration in drum and bulk formats reflects the liquid-to-solid handling economics of phenolic antioxidant logistics.
- Drums:Standard 200-liter steel containers serve mid-scale compounders and regional distributors.
- Bulk Containers:ISO tank and flexitank deliveries support integrated petrochemical complexes in Gujarat and eastern Saudi Arabia where compounding operations co-locate with polymer production.
- Carboys:Smaller plastic vessels accommodate pharmaceutical and cosmetic laboratory-scale procurement.
- Bags:Multi-wall paper or PE sacks handle solid BHT formulations for powder blending operations.
Drum shipments dominate current volume; Bulk Containers are expanding most quickly as direct producer relationships displace distributor intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Gujarat and eastern Saudi Arabia concentrate phenolics compounding operations alongside integrated petrochemical complexes, drawing direct procurement relationships from polyolefin producers seeking volume pricing and technical collaboration on customized stabilizer packages.
United States
Edible oil refiners and cereal manufacturers anchor North American antioxidant consumption, with FDA 21 CFR 182.3173 compliance governing permissible concentrations in branded food products. Kellogg and General Mills procurement teams pilot microencapsulated BHT systems for shelf-life extension. Midwest manufacturing corridors around Chicago sustain lubricant additive blending demand.
Germany
REACH pre-compliance drives packaging film converters toward alternative stabilizer qualification ahead of ECHA SVHC candidate listing formalization. Higher extrusion speeds in multilayer barrier film production elevate thermal stabilizer loadings. Bavarian and North Rhine-Westphalian polymer processing clusters accelerate BHT-free reformulation to secure retailer acceptance.
China
SAMR GB standard enforcement rejects legacy industrial material in food-grade applications, consolidating volume toward certified domestic producers capable of USP-NF documentation. Yangtze River Delta edible oil refineries displace informal supply channels. Integrated petrochemical complexes in Zhejiang and Jiangsu co-locate compounding operations with direct producer relationships.
India
FSSAI antioxidant purity enforcement in edible oil refining consolidates procurement toward certified domestic producers with documentation capabilities. Gujarat's Special Economic Zones concentrate phenolics supply alongside polymer manufacturing growth. Maharashtra-based pharmaceutical formulators drive pharmaceutical-grade demand for parenteral applications.
Brazil
ANVISA's updated food additive positive lists formalize antioxidant usage in processed meat applications previously operating under regulatory ambiguity. São Paulo and Paraná protein processing corridors open volume growth in Latin America's largest meatpacking market. Domestic compounders qualify supply chains for export-oriented beef and poultry operations.
Global Butylated Hydroxytoluene Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated phenolics producers commanding industrial-grade supply through captive p-cresol positions while pharmaceutical-grade niches concentrate around USP-NF documentation specialists. Three archetypes dominate: backward-integrated chemical majors with alkylation assets, purity-focused pharmaceutical-grade specialists, and regional compounders serving distributor channels. Competitive moves center on multi-year offtake agreements with polyolefin producers and microencapsulation technology licensing for controlled-release formulations.
Within the integrated chemical major tier, BASF SE exemplifies cost leadership through phenolics chain control, while Eastman Chemical Company anchors North American lubricant additive positioning. Camlin Fine Science occupies the pharmaceutical-grade documentation specialist archetype. These three entities represent distinct competitive vectors: scale-driven feedstock integration, regional formulation expertise, and compliance-driven purity certification.
| Leading Market Players |
|---|
| BASF SE |
| Kemin Industries |
| Sasol Limited |
| Honshu Chemical Industry Co., Ltd. |
| Camlin Fine Science |
| Eastman Chemical Company |
| Oxiris Chemicals S.A. |
| SI Group |
| LANXESS |
| Others |
Supply & Pricing Matrix
Microencapsulation technology for controlled-release antioxidant delivery is simultaneously compressing cost-per-unit economics and consolidating procurement power toward compounders with proprietary coating capabilities. This production-method transition rewards phenolics specialists capable of technical collaboration on customized stabilizer packages while squeezing commodity-grade suppliers into volume-based margin erosion.
Pricing Analysis
Volume concentrates in Food Grade BHT while margins accrue to Pharmaceutical Grade. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects USP-NF certification costs and ppb-threshold analytical requirements. Price differentiation hinges on impurity documentation capabilities and volume scale. Cost compression in industrial-grade supply is intensifying because non-integrated producers face isobutylene feedstock volatility without captive p-cresol positions. Edible oil refiners exhibit highest price sensitivity; parenteral pharmaceutical formulators show least.
Supply Chain Analysis
Certification and qualification gating through FDA 21 CFR 182.3173, REACH registrations, and China's GB standards fragments supplier bases by documentation capability. Supply concentrates in China, India, and Germany, with Yangtze River Delta and Gujarat Special Economic Zones anchoring phenolics compounding. Raw material dependencies draw from p-cresol, isobutylene, and acid catalyst feedstocks. Single-source vulnerability runs through concentrated alkylation capacity at integrated petrochemical complexes. Distribution runs through direct-procurement relationships displacing traditional distributor channels in Asia-Pacific manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Butylated Hydroxytoluene Market functions as a vertical-integration race where captive p-cresol supply and proprietary microencapsulation technology determine cost leadership. Players are pursuing backward integration into phenolics feedstocks as the decisive upstream lever.
For Market Incumbents: Lock in multi-year offtake agreements with polyolefin producers before EFSA re-evaluation timelines accelerate alternative stabilizer qualification. Defend margin position by acquiring microencapsulation technology licenses or specialist compounders, as controlled-release formulations decouple performance from concentration and blunt natural tocopherol substitution threats. Prioritize REACH pre-compliance investments in German and French packaging converter relationships. For New Entrants and Emerging Players: Pharmaceutical-grade USP-NF documentation capabilities in underserved Asian supply bases offer a technology-first wedge. Target parenteral formulation compounders in India and Southeast Asia lacking qualified domestic sources. Penetrate through analytical chemistry service partnerships that extend internal QC timelines for mid-scale producers. Biopolymer stabilization for PLA and PHA degradation kinetics presents adjacent white-space with performance validation runway ahead of standardization. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated chemical majors seeking phenolics chain completeness. Long-term viability across the analysis window favors certified producers with USP-NF documentation infrastructure and established SAMR/FSSAI clearance capabilities. Target acquisition archetype: mid-scale Asian compounders with pharmaceutical-grade qualification momentum and underutilized alkylation capacity. Watch EFSA re-evaluation timelines as inflection indicator for synthetic antioxidant restriction scenarios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into p-Cresol | BASF SE sustains cost leadership through captive phenolics feedstock control. |
| Microencapsulation Technology Licensing | Kellogg procurement pilots reduce surface migration and permit lower antioxidant loadings. |
| Pharmaceutical-Grade Certification Investment | Camlin Fine Science captures margin expansion in USP-NF parenteral formulation supply. |
| Long-Term Supply Agreement with Polyolefin Producers | SABIC and Reliance Industries extract volume pricing through direct procurement consolidation. |
| REACH Pre-Compliance Reformulation Partnership | German packaging converters secure retailer acceptance ahead of ECHA SVHC formal adoption. |
Research Methodology
Document review covered FDA 21 CFR filings, EFSA scientific opinions, REACH registration dossiers, and SAMR GB standard protocols, complemented by interviews with phenolics plant managers, edible oil refinery procurement leads, pharmaceutical formulation scientists, polymer processing technical directors, and antioxidant distribution channel partners. Secondary validation drew from customs/trade data, SEC 10-K disclosures, and industry association technical bulletins. Bottom-up volume triangulation across grade tiers and applications converged with top-down macroeconomic anchoring.
Output metrics span product type, application, end-use industry, and packaging format dimensions across the projection horizon. CAGRs derive from regression-based trajectory fitting against historical consumption patterns and elasticity-adjusted demand drivers. Forecast inputs incorporate polyolefin processing temperature escalation curves, EFSA re-evaluation timeline scenarios, and biopolymer commercialization ramp rates.
Several conditions sit outside the modeled scope, including abrupt isobutylene supply disruptions from cracker configuration shifts, unilateral antioxidant bans in major food-contact jurisdictions, and breakthrough natural antioxidant cost parity. Forecasts reflect documented assumptions regarding regulatory stability and feedstock availability. A model refresh is warranted upon material change in EFSA synthetic antioxidant re-evaluation outcomes or SAMR enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Europe Citric Acid Market
Additives
Tragacanth Market
Additives
Tackifier Market
Additives
Sodium Citrate Anhydrous Market
Additives
Humectants Market
Additives
Global Glass Additives Market
Additives
Nucleotide Premix Market
Additives
Glacial Acetic Acid Market
Additives
Citrate Ester Market
Additives
Lactic Acid Ester Market
Additives
Hydroxyethyl Cellulose Market
Additives
Global Mold Release Agents Market
Additives
Ultraviolet Light Stabilizer Market
Additives
Lubricant Additives Market
Additives
Crystal Growth Modifier Market
Additives
Antiscalants/Scale Inhibitors Market