
 Impact Modifier Market | 2026-2036
Impact Modifier Market Size, Share, and Industry Trends Forecast 2026-2036
Impact Modifier Market Analysis
Compatibilization chemistry is rewriting how polymer formulators achieve ductility without sacrificing heat resistance. Dow Inc. leverages its ethylene copolymer portfolio to anchor positions in automotive TPO systems. Kaneka Corporation specializes in MBS core-shell technology for transparent PVC applications. Arkema SA competes through bio-based acrylic modifier platforms targeting packaging sustainability mandates.
Impact modifiers are functional additives engineered into polymer matrices to absorb mechanical stress and prevent brittle fracture, typically comprising core-shell particles of 50-500 nanometers that initiate controlled crazing or shear yielding under load. Their primary industrial purpose centers on transforming inherently brittle thermoplastics into durable materials capable of withstanding impact, thermal cycling, and long-term weathering in structural applications. Polyolefin modifiers dominate volume consumption due to polypropylene's ubiquity in automotive lightweighting programs, while thermoplastic grades capture expanding specification work in appliance housings and consumer electronics. Construction applications represent a maturing but high-margin outlet where acrylic and MBS modifiers command premium positioning in vinyl siding and window profile formulations.
REACH registration requirements in Europe constrain import pathways for unregistered modifier chemistries, while China's SAMR enforces GB standard compliance for automotive interior emissions and fogging performance. EPA toxicity evaluations under TSCA influence modifier substitution patterns in US consumer goods and building products. Formulators must monitor regulatory divergence between jurisdictions to avoid reformulation penalties and supply disqualifications.
Market Dynamics
Automotive OEM specification tightening for high-impact polypropylene bumpers and interior panels is forcing modifier suppliers to reformulate for simultaneous impact resistance, heat stability, and low VOC emissions. China's GB standards for material safety and recyclability are compressing compliance timelines, while East China manufacturing clusters concentrate demand among domestic EV producers and export-tier suppliers.
Growth Catalysts
- GB Standard Compliance Mandates:China's SAMR enforcement of automotive interior emissions and fogging performance thresholds compels modifier suppliers to invest in low-VOC acrylic and MBS formulations for domestic EV supply chains.
- Polypropylene Lightweighting:Automotive OEMs in Asia-Pacific are expanding specification requirements for high-impact polypropylene bumpers and interior panels to meet fuel efficiency and electrification weight targets.
- East China Manufacturing Concentration:Demand clusters in Shanghai, Jiangsu, and Zhejiang provinces serve domestic EV producers and export-tier suppliers, creating procurement scale effects for qualified modifier vendors.
Market Restraints
- Naphtha-Derived Feedstock Volatility:Acrylic and MBS modifier production depends on petrochemical intermediates whose pricing fluctuates with crude oil and regional refinery operating rates.
- REACH Registration Barriers:ECHA registration requirements constrain import pathways for unregistered modifier chemistries into Europe, disqualifying smaller Asian suppliers from specification work.
- Compatibilizer Substitution Threat:Reactive extrusion technologies using maleic anhydride-grafted polyolefins can partially displace core-shell impact modifiers in select polypropylene applications.
Strategic Opportunities
- India Automotive Localization:PLI scheme incentives for domestic EV and component manufacturing create specification openings for impact modifiers in bumper and dashboard applications as OEMs localize supply chains.
- Bio-Based Acrylic Platforms:EU Green Deal sustainability mandates and packaging sector requirements for renewable content position bio-derived modifier chemistries for premium positioning in food contact and consumer goods.
- Digital Formulation Tools:Machine learning-driven rheology prediction is compressing development cycles for custom modifier blends, enabling faster OEM qualification and reducing physical prototyping costs.
Industry Challenges
- Multijurisdictional Compliance Talent:Formulators require specialists capable of navigating simultaneous REACH, GB standard, and TSCA requirements to avoid reformulation penalties and supply disqualifications.
- OEM Qualification Timeline Compression:Automotive specification cycles for new EV platforms demand modifier validation in 12-18 month windows versus historical 24-36 month programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impact Modifier Market |
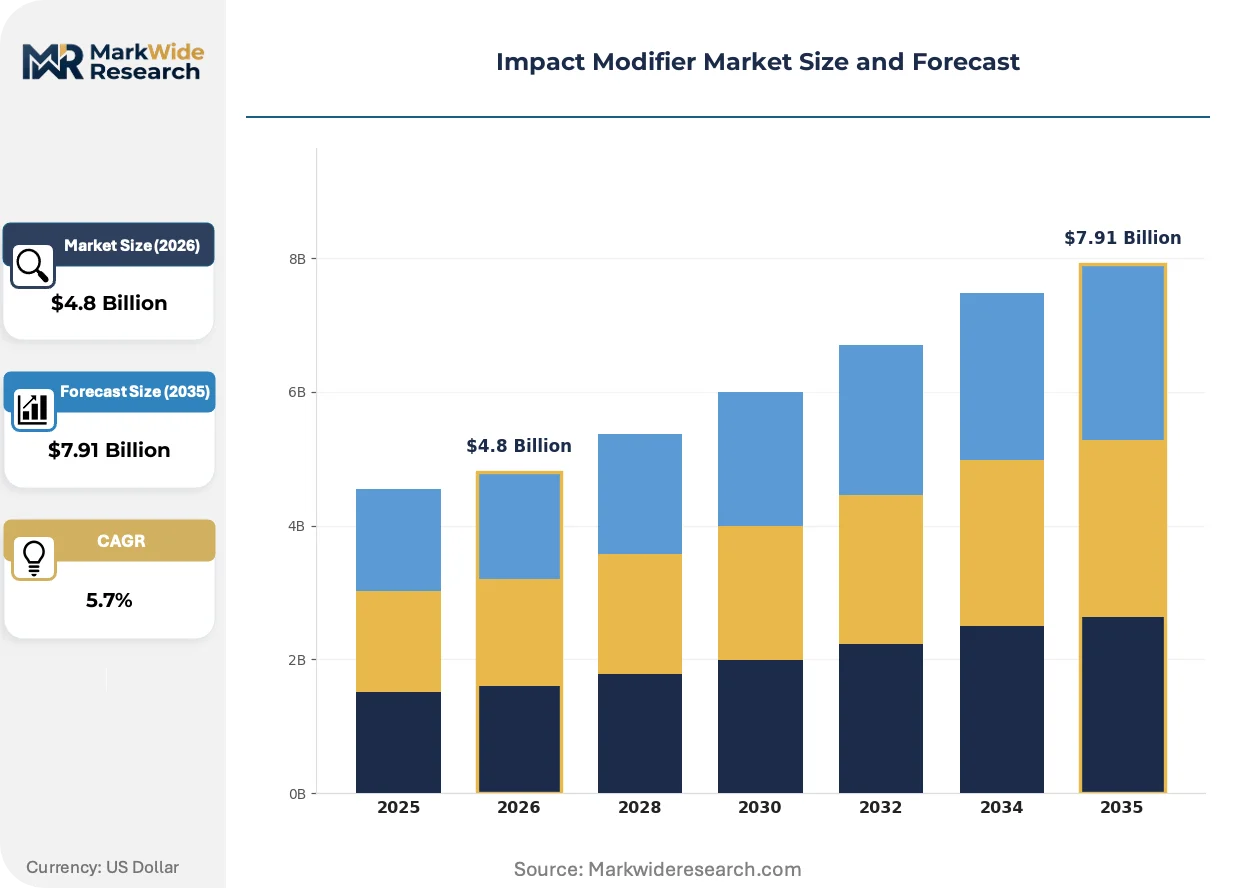
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic, Thermosetting, Polyolefin, Styrenic Application: Automotive, Electronics, Packaging, Construction Material: Polymer Blends, Copolymers, Additives, Compounds End User: Manufacturers, OEMs, Distributors, Fabricators |
| Companies Covered | Dow Inc., Lanxess AG, Kaneka Corporation, Arkema SA, Mitsubishi Chemical Corporation, LG Chem Ltd., BASF SE, Wacker Chemie AG, Shandong Ruifeng Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impact Modifier Market Emerging Trajectories
Compatibilization chemistry and digital formulation tools are rewriting how polymer formulators achieve ductility without sacrificing heat resistance. Three developments are restructuring competitive positioning and procurement patterns across automotive, packaging, and construction applications.
Core-shell particle engineering is digitizing modifier design workflows. Advanced simulation platforms now model crazing and shear yielding initiation at 50-500 nanometer scales, enabling predictive formulation before physical compounding. Automotive TPO suppliers in Germany and Japan are adopting these tools to compress OEM qualification timelines from 36 months toward 18 months. The technology is digitizing how formulators balance impact resistance against fogging performance and thermal cycling durability.
REACH registration requirements in Europe constrain import pathways for unregistered modifier chemistries. ECHA enforcement of substance data sharing and hazard classification creates structural barriers for Asian suppliers lacking European legal entity representation. Formulators serving automotive interior specifications are responding by consolidating qualified raw material sources and investing in EU-based toll manufacturing to maintain specification eligibility.
Specification-driven procurement is consolidating modifier vendor pools at major automotive OEMs. Tier-1 compounders now require modifier suppliers to demonstrate simultaneous compliance with China's GB standards, EPA TSCA evaluations, and OEM-specific material data systems. Japanese and South Korean automotive suppliers are most advanced in this integration, using unified material passports that trace additive content across recycling loops and end-of-life recovery pathways.
Impact Modifier Market Segmentation
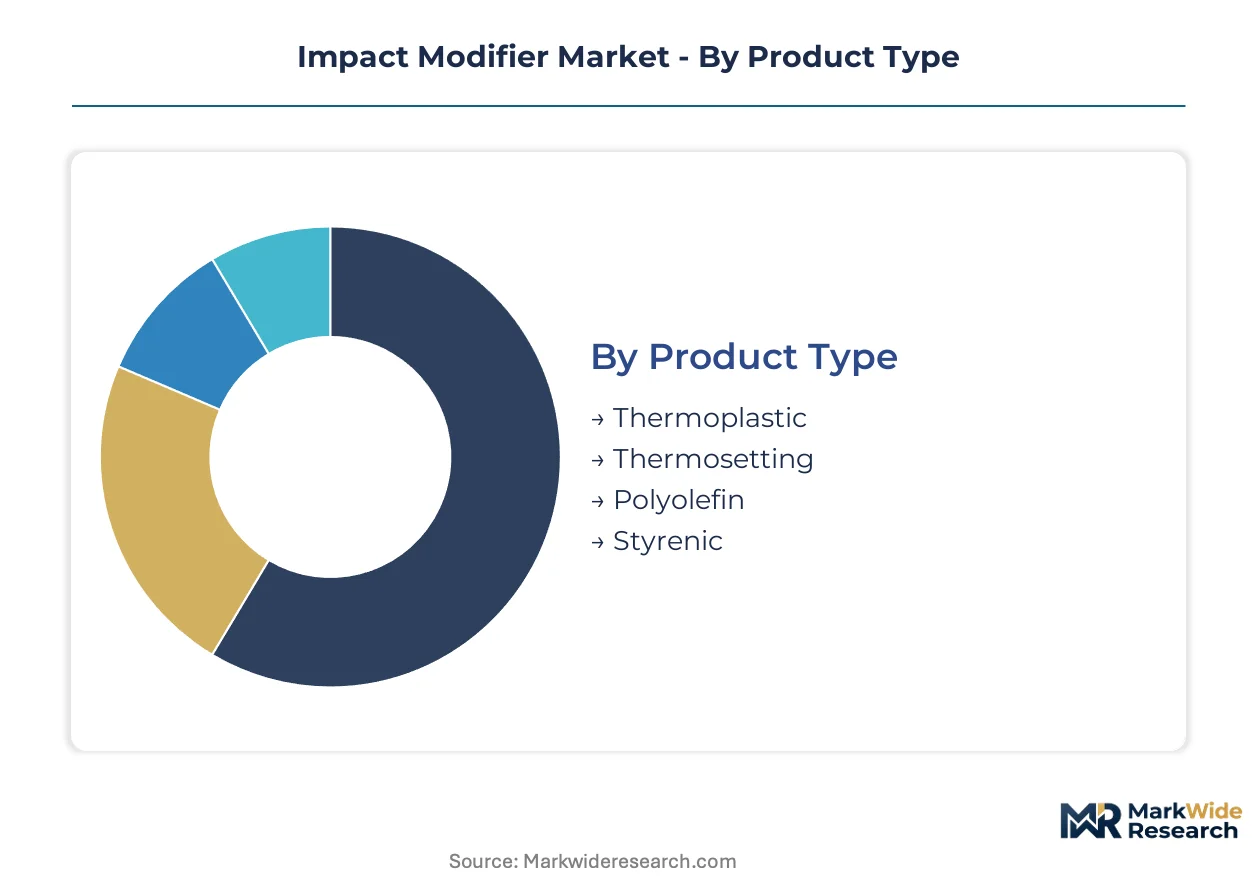
Impact modifier procurement patterns diverge sharply across product chemistry, application performance requirements, and supply chain position. Understanding these segment boundaries clarifies where formulation investments concentrate and which customer relationships command premium positioning.
Product Type:
Cost tier determines formulation accessibility and performance ceiling across the four modifier chemistries.
- Thermoplastic:Core-shell acrylic and MBS particles deliver controlled crazing initiation in PVC and engineering plastics. Automotive interior specifications in Germany and Japan concentrate demand here, driven by OEM mandates for low-VOC emissions combined with dashboard impact resistance.
- Polyolefin:Ethylene-based elastomers grafted onto polypropylene backbones dominate bumper and fascia applications. East China manufacturing clusters serving BYD, NIO, and export-tier suppliers represent the densest demand concentration, pressured by GB standard compliance timelines for recyclability.
- Thermosetting:Epoxy-compatible toughening agents for composite matrices and electronic encapsulants.
- Styrenic:ABS and SAN modifiers for appliance housings and consumer electronics.
Polyolefin commands the established base. The steepest expansion runs through Thermoplastic.
Application:
End-use performance specifications dictate modifier selection criteria and qualification complexity.
- Automotive:High-impact polypropylene systems for bumpers, door panels, and instrument clusters must simultaneously satisfy crash energy absorption, thermal cycling durability, and interior emissions thresholds. China's SAMR enforcement of GB standards for fogging performance compresses supplier validation windows.
- Construction:Acrylic and MBS modifiers in vinyl siding and window profiles command premium pricing due to weathering resistance requirements. North American housing starts and European renovation cycles drive regional demand variation.
- Electronics:Flame-retardant compatibilized formulations for laptop housings and server chassis.
- Packaging:Bio-based acrylic platforms responding to EU Green Deal renewable content mandates.
Automotive absorbs the largest formulation volumes. Packaging is climbing the fastest on sustainability-driven specification changes.
Material:
Supply chain position determines margin capture and technical service intensity.
- Copolymers:Ethylene-octene and ethylene-butene elastomers produced via metallocene catalysis anchor automotive TPO systems. Dow Inc. and ExxonMobil maintain supply concentration here, with qualification pathways favoring long-term polymerization partnerships over spot procurement.
- Additives:Masterbatch concentrates and liquid dispersions enable downstream compounders to fine-tune impact resistance without capital-intensive reactor investments.
- Polymer Blends:Pre-compounded modifier-resin systems for direct injection molding.
- Compounds:Fully formulated materials ready for OEM specification.
Copolymers retain the deepest specification entrenchment. Additives are gaining share fastest among regional compounders seeking formulation flexibility.
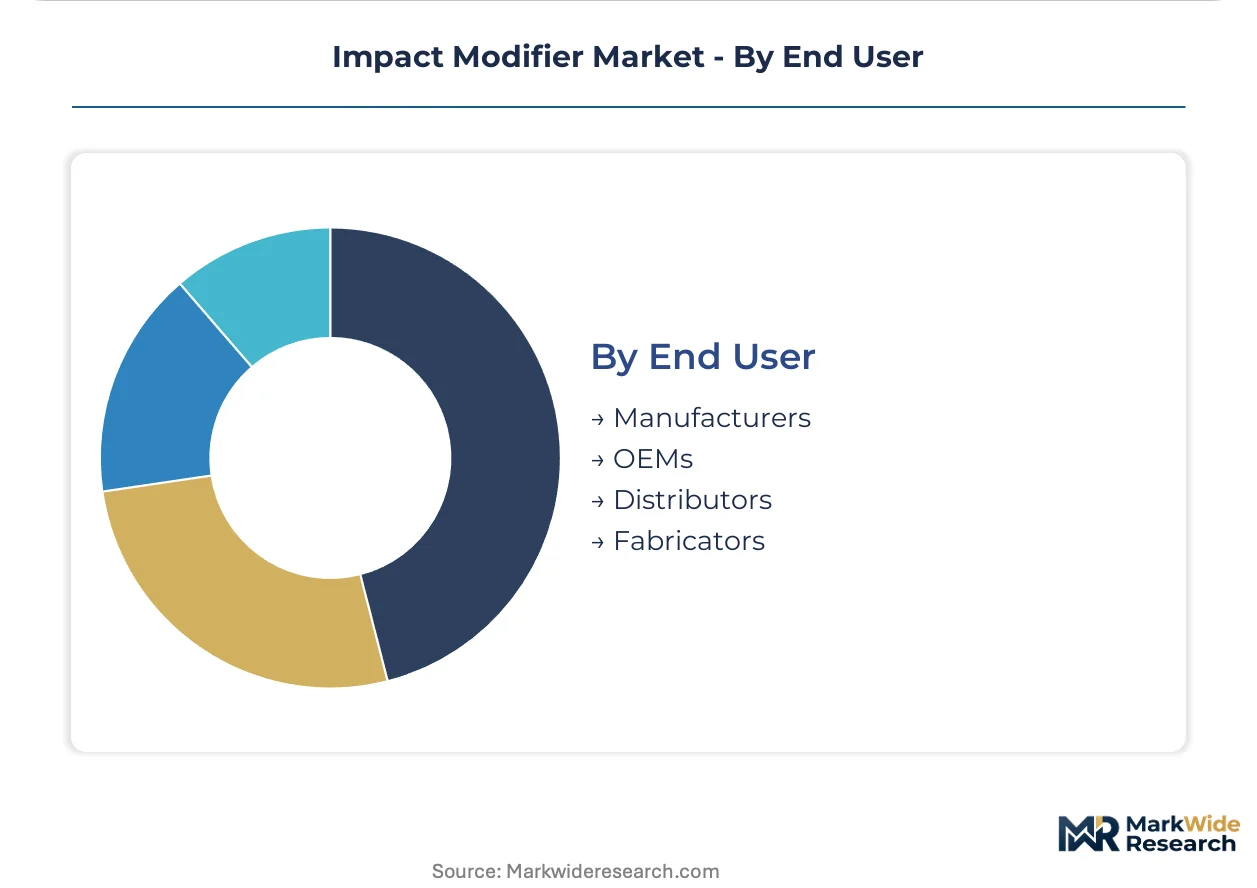
End User:
Customer type structures pricing power, technical collaboration depth, and contract duration.
- OEMs:Automotive and appliance manufacturers specify modifier performance directly, often mandating dual-source qualification and material passport traceability. Japanese and South Korean OEMs lead in unified data systems spanning recycling loops.
- Manufacturers:Tier-1 and Tier-2 compounders blend modifiers into pellet form for downstream processors.
- Distributors:Regional inventory holders serving mid-size processors with standardized grades.
- Fabricators:End-stage converters purchasing modified compounds for extrusion or molding.
OEMs anchor the highest-value relationships. Manufacturers represent the broadest volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and packaging compounders concentrate procurement power across distinct manufacturing geographies, with regulatory divergence creating qualification barriers that reshape supplier access.
China
East China manufacturing clusters in Shanghai, Jiangsu, and Zhejiang provinces absorb the densest modifier volumes for domestic EV producers and export-tier automotive suppliers. SAMR enforcement of GB standards for automotive interior emissions and fogging performance compresses compliance timelines for acrylic and MBS formulations. BYD and NIO qualification programs in Shenzhen and Hefei are forcing modifier vendors to demonstrate simultaneous recyclability and low-VOC performance.
Germany
Automotive TPO suppliers in Stuttgart and Munich regions specify high-impact polypropylene systems for bumper and dashboard applications serving BMW, Mercedes-Benz, and Volkswagen platforms. ECHA registration requirements under REACH constrain import pathways for unregistered modifier chemistries, favoring established European polymerization partnerships. BASF and Lanxess anchor qualification pathways that favor long-term supply agreements over spot procurement.
United States
EPA toxicity evaluations under TSCA influence modifier substitution patterns in consumer goods and building products, particularly vinyl siding formulations in the Southeast and Midwest construction corridors. Dow Inc. leverages its ethylene copolymer portfolio to anchor positions in automotive TPO systems serving Detroit-area OEMs. Gulf Coast petrochemical infrastructure supports acrylic and MBS modifier production with feedstock integration advantages.
Japan
METI-coordinated material passport initiatives trace additive content across recycling loops, with automotive suppliers in Toyota City and Yokohama leading unified data system adoption. Kaneka Corporation's MBS core-shell technology serves transparent PVC applications in consumer electronics and medical packaging. Japanese OEMs mandate dual-source qualification and 12-18 month validation windows for new EV platform specifications.
India
PLI scheme incentives for domestic EV and component manufacturing create specification openings in Maharashtra and Tamil Nadu automotive corridors. BIS standards for material safety are tightening compliance thresholds as Maruti Suzuki and Tata Motors localize supply chains. Mumbai and Chennai compounders seek formulation flexibility through masterbatch concentrates rather than capital-intensive reactor investments.
Impact Modifier Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where polymerization scale separates volume leaders from formulation innovators. The vendor base clusters around three strategic archetypes: integrated petrochemical majors with captive elastomer supply, core-shell technology specialists with nanoscale particle engineering capabilities, and regional compounders with formulation flexibility for mid-tier processors. Competitive moves concentrate on backward integration into metallocene catalyst technologies and geographic expansion through EU-based toll manufacturing to maintain REACH specification eligibility.
Within the integrated petrochemical tier, Dow Inc. and BASF SE anchor positions through ethylene copolymer portfolios and global polymerization networks. Kaneka Corporation exemplifies the core-shell specialization archetype with MBS technology platforms, while Arkema SA occupies a position in bio-based acrylic modifier development. Shandong Ruifeng Chemical Co., Ltd. represents regional Chinese suppliers seeking qualification pathways into East China EV supply chains.
| Leading Market Players |
|---|
| Dow Inc. |
| Lanxess AG |
| Kaneka Corporation |
| Arkema SA |
| Mitsubishi Chemical Corporation |
| LG Chem Ltd. |
| BASF SE |
| Wacker Chemie AG |
| Shandong Ruifeng Chemical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European ethylene elastomer production is tightening supply discipline among polyolefin modifier suppliers and amplifying pricing power for qualified REACH-registered vendors serving automotive TPO specifications.
Pricing Analysis
Cost-plus contracts indexed to naphtha and ethylene monomer benchmarks dominate long-term supply agreements between modifier producers and Tier 1 compounders. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified automotive grades from general-purpose packaging modifiers and commodity construction additives. Cost compression in standard-grade MBS formulations is intensifying because East Chinese producers are expanding metallocene capacity. Tier 1 automotive compounders show lowest price sensitivity due to qualification lock-in effects, while regional fabricators purchasing masterbatch concentrates exhibit highest elasticity.
Supply Chain Analysis
Naphtha-derived petrochemical intermediates feed acrylic and MBS modifier production, with Gulf Coast crackers in the United States, Rotterdam-integrated complexes in the Netherlands, and Zhejiang refinery corridors in China anchoring upstream supply. Specialty modifier output draws from ethylene, butadiene, and methyl methacrylate feedstocks. Single-source vulnerability concentrates in metallocene catalyst supply controlled by limited technology licensors. Distribution runs through direct mill-to-compounder relationships for automotive specifications, with regional distributors serving construction and packaging segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
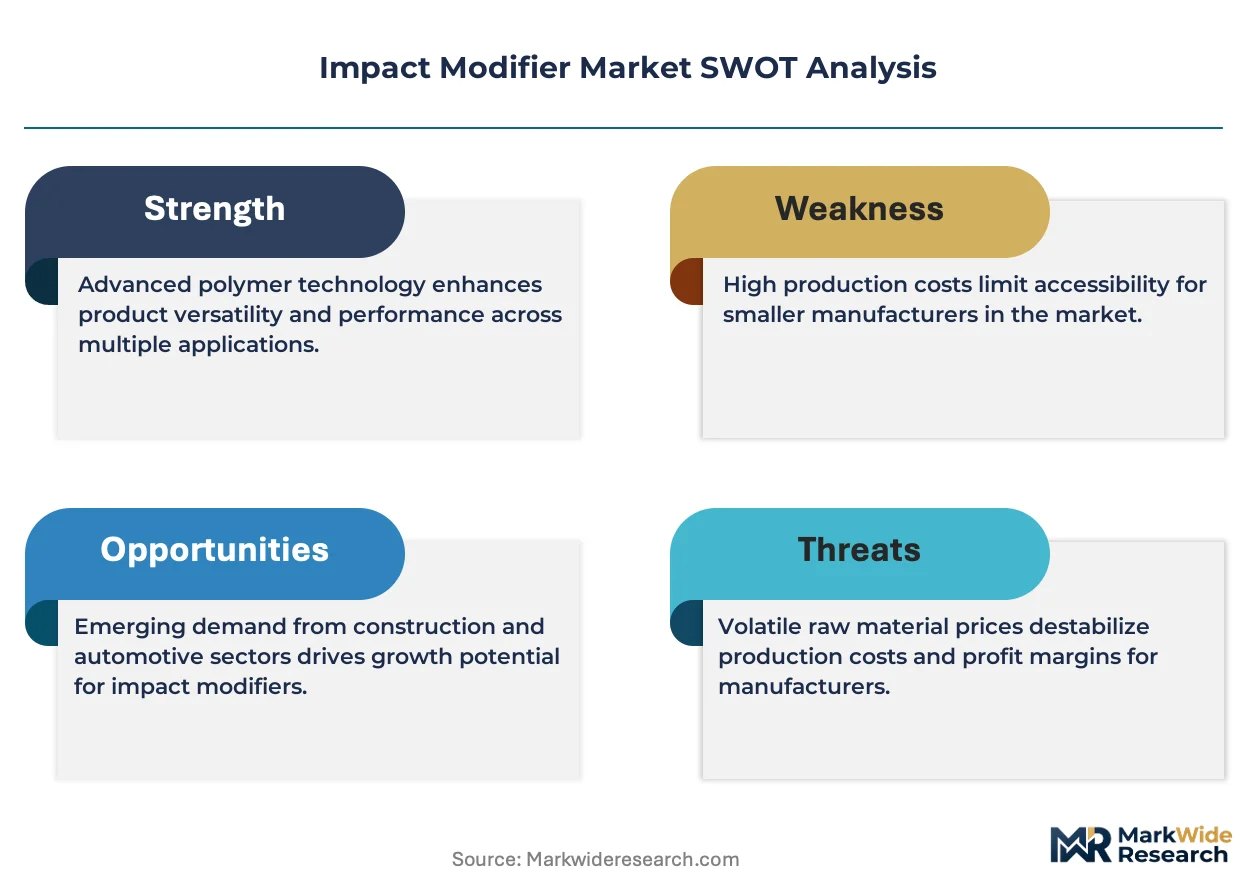
Regulatory entrenchment around REACH registration and GB standard compliance creates durable defensive moats for incumbent modifier suppliers, as OEM qualification timelines and substance data sharing requirements raise structural barriers against unregistered competitors.
For Market Incumbents: Pre-empt compatibilizer substitution threats by accelerating bio-based acrylic platform development for EU Green Deal packaging mandates. Secure backward integration into metallocene catalyst technology to reduce licensing exposure. Expand toll manufacturing presence in Germany and the Netherlands to maintain REACH specification eligibility as ECHA enforcement tightens.
For New Entrants and Emerging Players: Build out formulation capabilities targeting India's PLI-scheme automotive corridor in Maharashtra and Tamil Nadu, where localization requirements are displacing imported modifier volumes. Establish masterbatch concentrate partnerships with Mumbai and Chennai compounders seeking flexibility without reactor investments. Position around BIS standard compliance as Maruti Suzuki and Tata Motors accelerate supply chain localization.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification-driven procurement is concentrating vendor pools at major automotive OEMs, with unified material passport requirements favoring scale players with multi-jurisdictional compliance capabilities. Target acquisition archetypes: regional compounders with established OEM qualification pathways but limited catalyst technology. Watch for inflection in SAMR enforcement intensity around GB standard fogging performance thresholds as the signal compressing supplier validation windows further.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallocene Catalysts | Reduces licensing exposure to W. R. Grace and Univation Technologies for polyolefin modifier production. |
| EU-Based Toll Manufacturing Expansion | Maintains REACH specification eligibility as ECHA substance data sharing requirements tighten import pathways. |
| Bio-Based Acrylic Platform Development | Positions for EU Green Deal renewable content mandates in food contact and consumer goods packaging. |
| Digital Formulation Tool Deployment | Compresses OEM qualification timelines from historical benchmarks toward 12-18 month EV platform windows. |
| India Automotive Corridor Localization | Captures PLI scheme specification openings as Maruti Suzuki and Tata Motors displace imported modifier volumes. |
Methodological Framework
A spread of perspectives from polymer plant managers, automotive Tier 1 procurement leads, distribution channel partners, and technical R&D directors converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and vehicle production databases. Bottom-up volume estimates from compounder consumption patterns were triangulated against top-down demand projections from automotive platform specifications and construction activity indices.
Demand-supply balance modeling across the analysis window integrated polypropylene lightweighting penetration rates, GB standard compliance timeline compression, and compatibilizer substitution threat vectors. Segmentation dimensions included product chemistry tier, end-use application performance requirements, material supply chain position, and customer type pricing power structure. CAGRs were derived from fitted growth curves calibrated to historical qualification cycle data and OEM platform launch schedules. Forecast inputs incorporated SAMR enforcement intensity scenarios and ECHA registration pathway bottlenecks.
Stress conditions across naphtha price volatility, REACH registration timeline delays, and compatibilizer technology substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and OEM qualification protocol stability. Cross-checking against IHS Markit vehicle production databases and Cefic chemical output indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Metal Modifiers Market
Additives
Global Synthetic Tackifier Market
Additives
Defoaming Coating Additives Market
Additives
Global Cement and Concrete Additives Market
Additives
Antioxidant and Stabilizer Agents Market
Additives
Polymeric Plasticizer Market
Additives
Calcium Stearate Market
Additives
Calcium Tartrate Market
Additives
1,4 Butanediol Derivatives Market
Additives
Global Pearlizing Agent Market
Additives
Sorbitan Oleate Market
Additives
Chelating Agents Market
Additives
Global Corrosion Inhibitor Market
Additives
Global Cement Additives Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
Feed Additives Market