
 Hydroxyethyl Cellulose Market | 2026-2036
Hydroxyethyl Cellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxyethyl Cellulose Market Intelligence
High-purity, low-salt grades for pharmaceutical applications is bifurcating the market. This shift creates distinct value tiers based on molecular weight, purity, and degree of substitution. Ashland leverages its specialization in personal care formulations, offering specific grades for cosmetic products. Dow sustains its market position through extensive manufacturing scale and a broad distribution network, while Shin-Etsu Chemical competes on advanced R&D in cellulose ether derivatives.
Hydroxyethyl cellulose is a non-ionic, water-soluble polymer derived from cellulose treated with ethylene oxide under alkaline conditions. Its primary industrial purpose is to function as a rheology modifier, controlling the viscosity and stability of aqueous systems. Demand from the paints end-use industry for powder forms remains a significant volume driver, particularly in architectural coatings. However, use as a thickening agent and stabilizer in cosmetics represents the fastest-growing application, especially for gel and liquid formulations.
European chemical regulations under REACH dictate substance registration, evaluation, and authorization requirements for HEC producers and importers. In the United States, the FDA's oversight of excipients in pharmaceuticals and ingredients in cosmetics via its GRAS list governs grade purity. Future competitive advantage will depend on developing bio-based or modified HEC variants that meet stringent environmental and performance standards in key end-use markets.
Market Dynamics
The central structural force shaping the hydroxyethyl cellulose market is its bifurcation into distinct value tiers. This division is driven by purity requirements for pharmaceutical applications and regulatory pressure from frameworks like the EU Green Deal favoring bio-based ingredients in consumer goods.
Growth Catalysts
- EU Green Deal Framework:Mandates for sustainable sourcing and biodegradability in Europe are accelerating the replacement of synthetic polymers with bio-based thickeners like HEC, particularly within the personal care and cosmetics industries.
- Chinese Construction Sector:Large-scale domestic demand for architectural paints and coatings in China's construction industry sustains high-volume consumption of standard-grade HEC, providing a stable demand floor for manufacturers.
- Pharmaceutical Excipient Demand:The increasing use of HEC as a binder and controlled-release agent in oral solid dosage forms creates a high-value, recession-resistant demand stream for specialized, high-purity grades.
Market Restraints
- Ethylene Oxide Price Volatility:As a key petrochemical-derived raw material, fluctuating ethylene oxide prices directly impact HEC production costs, creating persistent margin pressure and pricing uncertainty for manufacturers.
- Competition from Hydrocolloids:In less demanding applications, particularly in food and some personal care segments, HEC faces substitution threats from other natural and synthetic thickeners like guar gum, xanthan gum, and carbomers.
- REACH Compliance Burden:For producers and importers in the European Union, the substance registration, evaluation, and authorization requirements under REACH present significant administrative and financial barriers to market access.
Strategic Opportunities
- Bio-based HEC Variants:Developing HEC from alternative cellulose sources or through greener synthesis routes opens access to premium markets where customers prioritize sustainability metrics and reduced environmental impact.
- Southeast Asian Construction Boom:Rapid urbanization and infrastructure development in countries like Vietnam and Indonesia represent a significant growth opportunity for HEC use in cementitious materials and architectural coatings.
- 3D Printing of Pharmaceuticals:The convergence of 3D printing and drug delivery creates a niche for highly customized HEC grades designed for precise rheology control in printable, personalized medicine formulations.
Industry Challenges
- Pharmaceutical Grade Certification:Meeting the stringent purity standards for pharmaceutical excipients, such as those governed by the FDA's GRAS list or USP monographs, requires substantial investment in advanced purification technology and quality assurance systems.
- Supply Chain Concentration Risk:A heavy reliance on cellulose pulp and manufacturing capacity located in China exposes the global supply chain to geopolitical tensions and disruptions from local environmental regulations.
- Expertise in Cellulose Chemistry:A scarcity of chemical engineers with specialized knowledge in cellulose ether modification hinders the pace of innovation for next-generation HEC products with tailored performance characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxyethyl Cellulose Market |
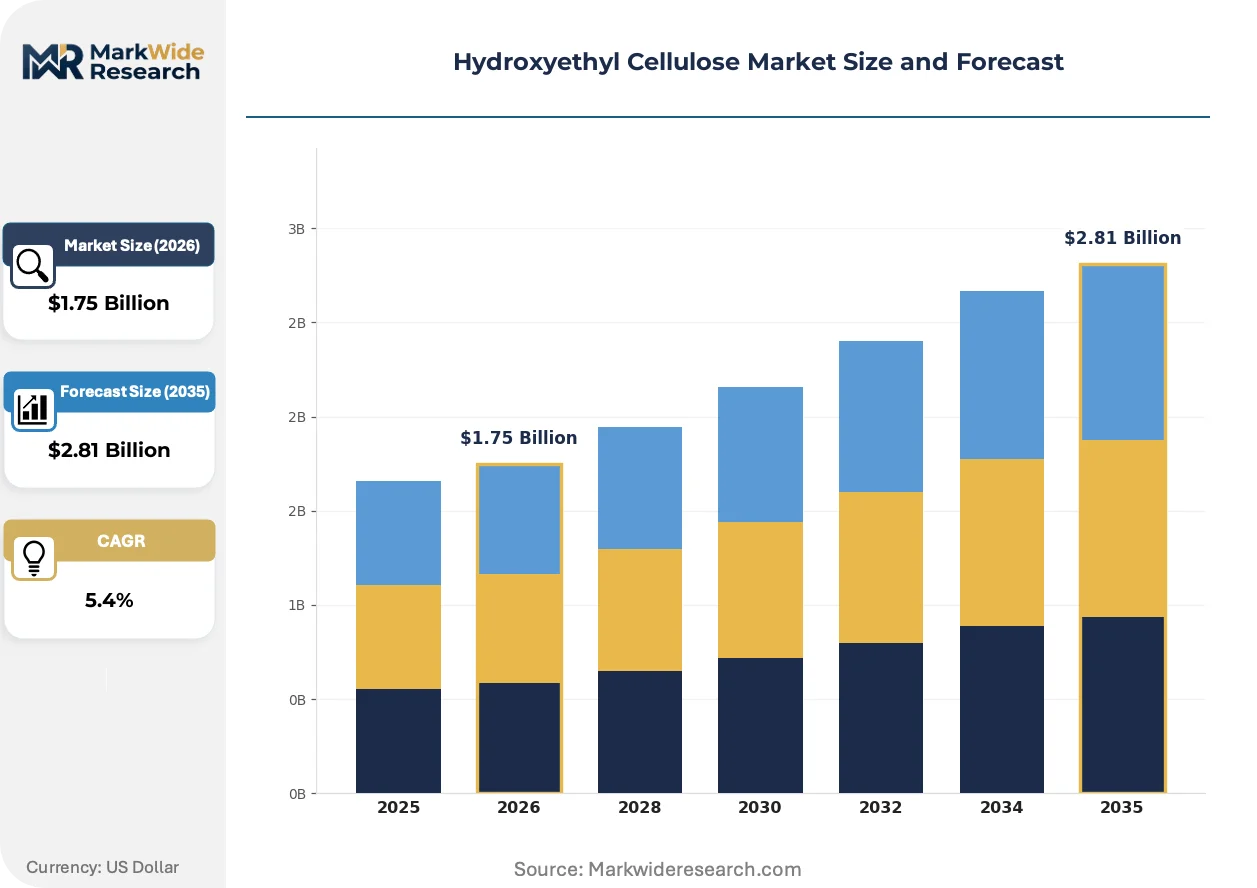
| Market Size in 2026 | $1.75 Billion |
| Market Size in 2035 | $2.81 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Gel, Granules, Liquid End Use Industry: Cosmetics, Pharmaceuticals, Food, Paints Functionality: Thickening Agent, Stabilizer, Emulsifier, Binder Formulation Type: Aqueous, Non-aqueous, Suspensions, Emulsions |
| Companies Covered | AkzoNobel, Lotte Fine Chemical, Ashland, SE Tylose, Sumitomo Seika Chemicals, Dow, Daicel Corporation, Zhejiang Haishen New Materials, Shin-Etsu Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxyethyl Cellulose Market Strategic Shifts & Innovations
The market's evolution reflects a transition from HEC as a commodity thickener toward its use as a specialized functional ingredient. This shift is driven by demands for greater performance differentiation, sustainability, and precise rheological control in advanced applications.
Enzyme-modified HEC is an innovative product that allows for controlled viscosity reduction after application. This technology is being adopted in the oil and gas industry for hydraulic fracturing fluids and in niche personal care products to create unique textures. This targeted functionality is decomposing the traditional one-size-fits-all approach, enabling formulators to design time-dependent viscosity profiles without harsh chemical additives.
The U.S. FDA’s heightened scrutiny of excipients and impurities in drug products directly impacts purity requirements for HEC. This regulatory pressure compels manufacturers to invest in sophisticated purification processes to minimize residual salts and byproducts like ethylene glycol. Consequently, the high-purity pharmaceutical-grade segment is most affected, with suppliers competing on documented compliance with USP/NF monographs.
Buyers in the personal care sector are shifting from purchasing HEC as a simple raw material to specifying desired sensory profiles and performance outcomes. This behavior disrupts the traditional commodity sales model, compelling suppliers to provide formulation support and application-specific grades. This trend is most pronounced in the European and North American cosmetics markets, where brands use texture and feel as key product differentiators.
Hydroxyethyl Cellulose Market Segmentation
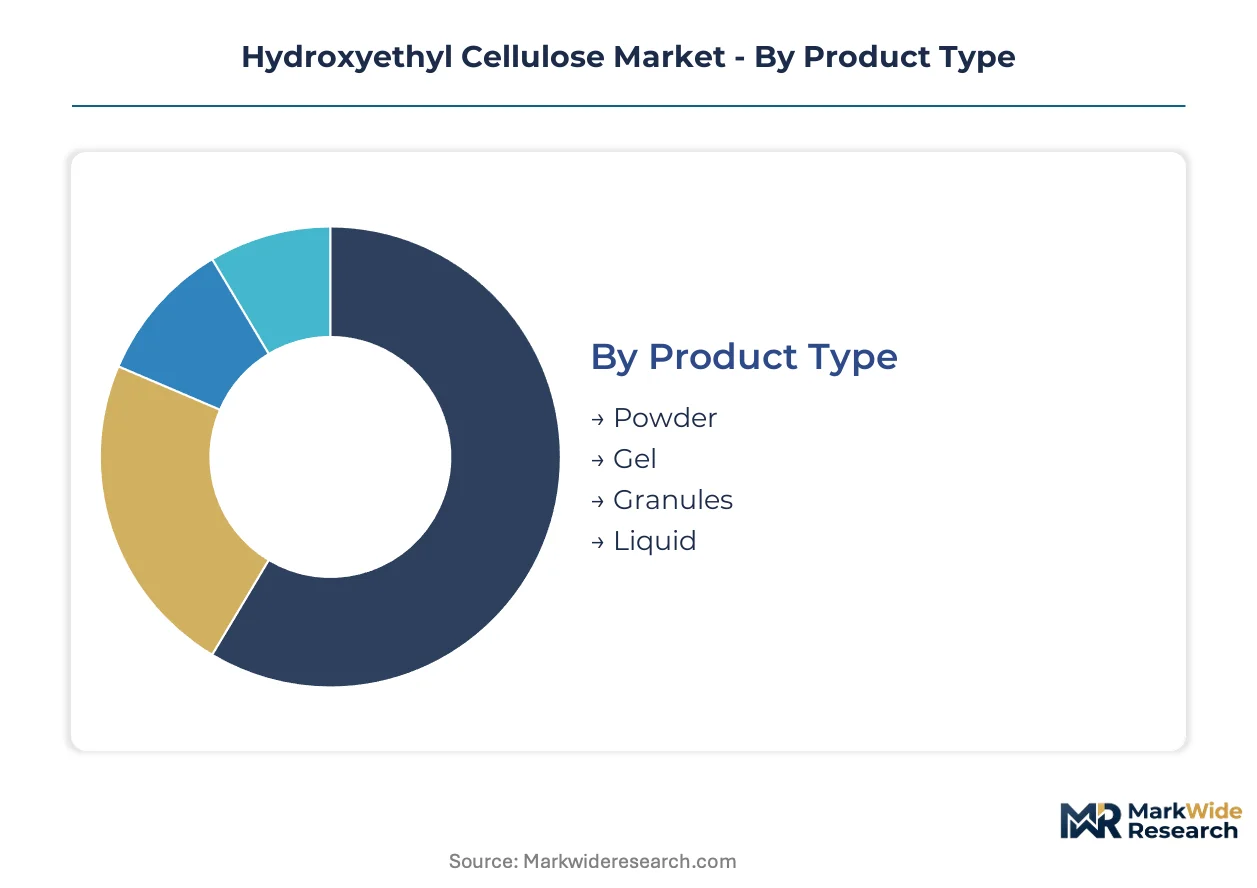
The hydroxyethyl cellulose market segments based on product form, end-use application, functional role, and formulation type. This granular segmentation allows manufacturers to target specific customer needs with tailored HEC grades, differentiating products beyond basic viscosity modification.
Product Type:
The product type segments face varying degrees of substitution pressure from alternative thickeners or delivery formats.
- Powder:This is a dry, granular form of HEC, typically supplied in bulk for industrial applications. Demand remains robust in the paints and construction sectors, particularly in China, due to its cost-effectiveness and ease of storage and transport for large-scale projects.
- Liquid:Pre-dissolved HEC solutions offer convenience and consistent viscosity, reducing formulation time for end-users. Demand is expanding in personal care and cosmetics, where formulators prioritize ease of integration and precise rheological control in final products.
- Gel:This semi-solid form of HEC delivers specific tactile properties and sustained release characteristics. Gel formulations find niche applications in medical devices and specialized personal care products requiring unique textures.
- Granules:Granular HEC offers improved dust-free handling and controlled dissolution rates compared to fine powders. This form is often preferred in applications requiring precise dosing and minimal airborne particles.
Powder anchors the volume base while Liquid gains share at the steepest rate.
End Use Industry:
Volume drivers vary significantly across the end-use industry segments, impacting HEC grade specifications and pricing.
- Cosmetics:HEC serves as a thickening agent, stabilizer, and film-former in a wide array of personal care products, including shampoos, lotions, and makeup. Formulators are increasingly specifying bio-based HEC variants to meet consumer demand for natural ingredients and sustainability mandates like the EU Green Deal.
- Paints:In architectural coatings and industrial paints, HEC acts as a rheology modifier, preventing sag and improving brushability. China's large-scale construction industry provides a stable, high-volume consumption base for standard-grade HEC in this sector.
- Pharmaceuticals:High-purity HEC functions as an excipient, binder, and controlled-release agent in oral solid dosage forms and ophthalmic solutions. Stringent regulatory requirements from the FDA and EMA drive demand for specialized, low-salt grades with documented compliance.
- Food:HEC is used as a thickener, stabilizer, and emulsifier in certain food and beverage applications, contributing to texture and shelf stability. Regulatory approvals and specific purity standards govern its use in this sensitive sector.
Demand for Cosmetics drives innovation, while Paints provides market stability.
Functionality:
Margin differentiation within HEC products correlates strongly with the specific functional role they perform in an application.
- Thickening Agent:This is the primary function of HEC, controlling the viscosity of aqueous solutions across diverse industries. The paints and personal care sectors consume significant volumes of HEC for its effective thickening properties.
- Binder:HEC binds active and inactive ingredients together in pharmaceutical tablets and granules, ensuring structural integrity. High-purity HEC grades are critical for this function in drug manufacturing.
- Stabilizer:HEC helps prevent phase separation and particle sedimentation in suspensions and emulsions, maintaining product homogeneity. This functionality is crucial in cosmetics and food products.
- Emulsifier:HEC assists in blending immiscible liquids, such as oil and water, creating stable emulsions. Cosmetic and pharmaceutical formulations frequently leverage HEC for its emulsifying capabilities.
The core utility of Thickening Agent underpins market volume, but specialized uses like Binder command premium pricing.
Formulation Type:
Customer type preferences significantly influence the required formulation type of HEC, impacting product development and supply chains.
- Aqueous:HEC is highly soluble in water, making it suitable for water-based systems like architectural paints and many personal care products. Ease of dispersion and dissolution are key factors for formulators.
- Emulsions:HEC stabilizes oil-in-water and water-in-oil emulsions, preventing separation and contributing to product texture. Complex cosmetic creams and lotions frequently utilize HEC in emulsion systems.
- Non-aqueous:Specialized HEC grades are adapted for use in non-water-based systems, though this application is less common. These formulations require specific HEC modifications to ensure solubility and performance.
- Suspensions:HEC maintains the uniform dispersion of solid particles within a liquid medium, preventing settling. Pharmaceutical suspensions and certain industrial coatings benefit from HEC's role in this formulation type.
Aqueous formulations dominate current consumption, while Emulsions applications represent an expanding technical frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for hydroxyethyl cellulose varies significantly, with pharmaceutical buyers exhibiting minimal price sensitivity for high-purity grades, while industrial users in paints and coatings prioritize cost-effectiveness for standard volumes. This bifurcation creates distinct regional market dynamics and investment priorities for HEC producers. Different regulatory frameworks also shape regional competitive landscapes.
China
China's robust domestic demand for architectural paints and construction materials drives substantial consumption of standard-grade HEC. The Chinese government's dual carbon goals are encouraging manufacturers to explore greener production methods for cellulose derivatives. Major industrial clusters in the Yangtze River Delta and Pearl River Delta sustain large-scale HEC manufacturing and end-use applications.
United States
The United States market focuses on high-value HEC grades for pharmaceuticals and specialized personal care formulations. The FDA's stringent oversight of excipients and cosmetic ingredients mandates high purity and documented compliance for HEC suppliers. Research and development activities in states like New Jersey and California target advanced HEC variants for novel drug delivery systems.
Germany
Germany represents a key European market, with strong demand for HEC in high-performance coatings and personal care products. The EU Green Deal framework and REACH regulations compel producers to offer sustainably sourced and compliant HEC grades. Chemical companies in the Rhine-Main region are investing in bio-based HEC research and greener synthesis routes.
India
India's expanding construction sector and a rapidly growing personal care market contribute to its increasing HEC consumption. The country's national pharmaceutical regulator, CDSCO, influences purity standards for HEC used in drug formulations. Manufacturing hubs in Gujarat and Maharashtra are seeing increased capacity for HEC production to meet rising domestic requirements.
Japan
Japan's market for HEC emphasizes advanced functionality and high-purity grades, particularly in specialty chemicals and pharmaceuticals. METI promotes innovation in bio-based materials, encouraging the development of sustainable HEC variants. Research institutions and chemical manufacturers in the Kanto region are leading efforts in cellulose ether modification for tailored applications.
Hydroxyethyl Cellulose Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the hydroxyethyl cellulose market, creating a tiered competitive structure. The industry features large-scale commodity producers alongside specialized manufacturers focusing on high-purity and functionalized grades. Strategic partnerships and targeted R&D investments are common competitive moves among these diverse players.
At the scale-driven end, Dow maintains its market position through extensive manufacturing capacity and a broad distribution network across various industrial applications. Ashland leverages its specialization in personal care formulations, offering specific HEC grades tailored for cosmetic products. Shin-Etsu Chemical exemplifies a focus on advanced R&D, competing through innovative cellulose ether derivatives and high-purity offerings.
| Leading Market Players |
|---|
| AkzoNobel |
| Lotte Fine Chemical |
| Ashland |
| SE Tylose |
| Sumitomo Seika Chemicals |
| Dow |
| Daicel Corporation |
| Zhejiang Haishen New Materials |
| Shin-Etsu Chemical |
| Others |
Cost & Logistics Intelligence
Average 60-day lead times for specialized HEC grades reflect a supply chain bifurcated by purity and performance, directly influencing pricing power for high-value applications. This stratification creates distinct market dynamics for manufacturers.
Pricing Analysis
Long-term contract bundling often drives lifetime value for HEC suppliers, especially for consistent industrial buyers. The dominant pricing structure is a hybrid of per-unit transactional sales for standard grades and value-based contracts for high-purity, specialized HEC. Price differentiation stems from the specific purity grade required (e.g., pharmaceutical versus industrial) and the volume scale of procurement. Pricing softness stems from persistent ethylene oxide price volatility, impacting overall production costs. Pharmaceutical buyers exhibit minimal price sensitivity for compliant grades, while architectural paint manufacturers prioritize cost-effectiveness.
Supply Chain Analysis
Consistent 45-day inventory holdings across the HEC market are heavily influenced by manufacturing concentration. Geographic supply concentrates primarily in China, with additional capacity in Europe and North America. Raw material dependencies hinge on cellulose pulp sourcing and the availability of petrochemical-derived ethylene oxide. A significant structural risk is supply chain concentration in China, exposing the market to potential geopolitical tensions and local regulatory disruptions. Distribution runs through a mix of direct sales for large industrial accounts and specialized chemical distributors for smaller volume and niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydroxyethyl cellulose market is at a platform-economics inflection point, driven by the emergence of bio-based ingredient ecosystems demanding tailored performance. This shift redefines value creation beyond basic rheology modification.
For Market Incumbents:
Consolidate market share through strategic investments in advanced purification technologies for pharmaceutical-grade HEC. Expand bio-based HEC production capacity, particularly in regions like Europe, to mitigate the threat from competing hydrocolloids and comply with EU Green Deal mandates. Deepen R&D in cellulose chemistry to develop next-generation variants.
For New Entrants and Emerging Players:
Anchor in niche applications requiring precise rheology control, such as 3D printing of pharmaceuticals or enzyme-modified HEC for specific textural outcomes. The most penetrable segment is specialized personal care formulations in North America, seeking unique sensory profiles. A strong go-to-market angle involves offering rapid formulation support and documented sustainability certifications.
For Investors and Strategic Acquirers:
Long-term, this sits as a specialty chemicals play because of sustained demand from essential applications and high-growth potential in bio-based solutions. Target acquisition archetypes include companies innovating in greener synthesis routes or those with advanced purification capabilities for high-purity excipients. Increased M&A activity for bio-based HEC startups serves as a key inflection indicator to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint and aligns with EU Green Deal mandates for HEC producers. |
| Capacity Expansion | Addresses growing demand in Southeast Asian construction and ensures supply stability. |
| Joint Venture | Accelerates development of bio-based HEC variants with shared R&D expertise. |
| Regulatory Approval Pathway | Secures market access for high-purity HEC grades in pharmaceutical applications under FDA oversight. |
| Product Launch | Introduces enzyme-modified HEC for specialized oil and gas or personal care applications. |
Research Approach
A spread of perspectives from HEC manufacturers, personal care formulators, pharmaceutical R&D leads, and construction material specifiers converged on the working assumptions. Primary interviews were triangulated with extensive secondary research from chemical industry reports, regulatory filings like REACH, trade association publications, and company annual reports. This approach ensured a robust bottom-up and top-down validation of market dynamics.
The hydroxyethyl cellulose market segmentation dimensions modeled include product form, end-use application, functional role, and regional production capacity. An analytical framework projected market evolution across the analysis window by correlating historical growth with future demand drivers. Compound annual growth rates were derived from historical trend analysis and projected demand-supply gaps. Key forecast inputs included ethylene oxide price trends and construction spending forecasts in China.
Decision-makers should treat outputs as directional under current regulatory frameworks and raw material cost stability; material deviation would warrant model refresh. Forecasts reflect assumptions regarding technological advancements and stable geopolitical conditions. Significant shifts in petrochemical prices or unforeseen changes in EU Green Deal mandates represent key risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Potassium Nitrate Market
Additives
Dishwashing Additives Market
Additives
Global Feed Acidifiers Market
Additives
Ammonium Phosphatide Market
Additives
Antiblock Agents Market
Additives
Epoxy Type Stabilizers Market
Additives
Antiknock Agents Market
Additives
Anti-Foaming Agent Market
Additives
Performance Minerals Additives Market
Additives
Silage Additives Market
Additives
South Africa Acidulants Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Lactic Acid Ester Market
Additives
Chelating Agents Market
Additives
Global Inorganic Corrosion Inhibitors Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market