
 N-Hexanol Market | 2026-2036
N-Hexanol Market Size, Share, and Industry Trends Forecast 2026-2036
N-Hexanol Market Outlook
Technical-grade supply contracts with embedded purity certification and lot-traceability documentation is broadening what buyers evaluate beyond base pricing. Sasol leverages its Fischer-Tropsch integration to sustain cost-advantaged supply of high-purity N-hexanol for European coating compound manufacturers. BASF SE anchors its position through backward integration into cracker-derived C6 alcohol streams, while Eastman Chemical Company differentiates via specialized solvent blends targeting pharmaceutical synthesis applications.
N-hexanol is a six-carbon primary alcohol with the molecular formula C6H14O, typically produced through ethylene oligomerization followed by hydroformylation and hydrogenation, or via natural fatty alcohol reduction; it functions primarily as a chemical intermediate and solvent in industrial formulations. The chemical intermediate segment dominates volume flows due to entrenched demand from plasticizer and coating compound manufacturers, while the flavors and fragrances category commands premium pricing through stringent purity grades. Direct sales channels control bulk procurement for agrochemical and paints and coatings end users, whereas distributor networks serve fragmented personal care and specialty pharmaceutical buyers.
EPA solvent emission regulations under the Clean Air Act constrain volatile organic compound content in coating formulations, pushing N-hexanol suppliers toward higher-purity grades and alternative application development. REACH registration requirements in Europe mandate comprehensive toxicological dossiers, elevating compliance costs for non-integrated importers. China's SAMR enforces GB standards for industrial chemical quality, creating divergent specification tiers across export markets. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with evolving compliance thresholds.
Market Dynamics
REACH compliance in Europe and EPA solvent emission standards in the United States are forcing specialty chemical manufacturers toward higher-purity N-hexanol grades with embedded lot-traceability documentation, reshaping supplier qualification criteria beyond base pricing metrics.
Growth Catalysts
- Plasticizer manufacturing expansion:Specialty chemical producers in China are scaling procurement of N-hexanol as a chemical intermediate for coating compound and surfactant formulations.
- REACH registration mandates:European ECHA requirements for comprehensive toxicological dossiers are elevating compliance barriers that favor integrated producers with captive feedstock supply.
- Fischer-Tropsch integration:Synthetic fuel technology pathways are enabling cost-advantaged production of high-purity C6 alcohol streams for pharmaceutical synthesis applications.
Market Restraints
- Ethylene feedstock volatility:Cracker-derived C6 alcohol production faces margin compression from olefin price swings tied to naphtha and natural gas liquid markets.
- Supply concentration in South Africa:Fischer-Tropsch based N-hexanol capacity clusters with integrated energy-chemical complexes, creating geographic single-source risk for European coating compound manufacturers.
- Natural fatty alcohol competition:Palm kernel and coconut oil derived C6-C8 alcohols compete in flavors and fragrances applications where renewable sourcing commands premium positioning.
Strategic Opportunities
- Pharmaceutical solvent specialization:Specialized solvent blends targeting active pharmaceutical ingredient synthesis command pricing premiums through stringent USP-NF and EP monograph compliance.
- India surfactant manufacturing:Domestic personal care and industrial cleaning compound producers under BIS quality standards are expanding local C6 alcohol refining capacity.
- EPA Clean Air Act alignment:Volatile organic compound emission constraints in coating formulations create pull for lower-VOC N-hexanol alternatives in architectural and industrial paints.
Industry Challenges
- Analytical certification timelines:REACH Annex XV dossier preparation and substance evaluation procedures extend product registration cycles by 18-36 months for non-integrated importers.
- Legacy formulation integration:Coating compound manufacturers face reformulation complexity when substituting higher-purity N-hexanol grades into established alkyd and epoxy resin systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | N-Hexanol Market |
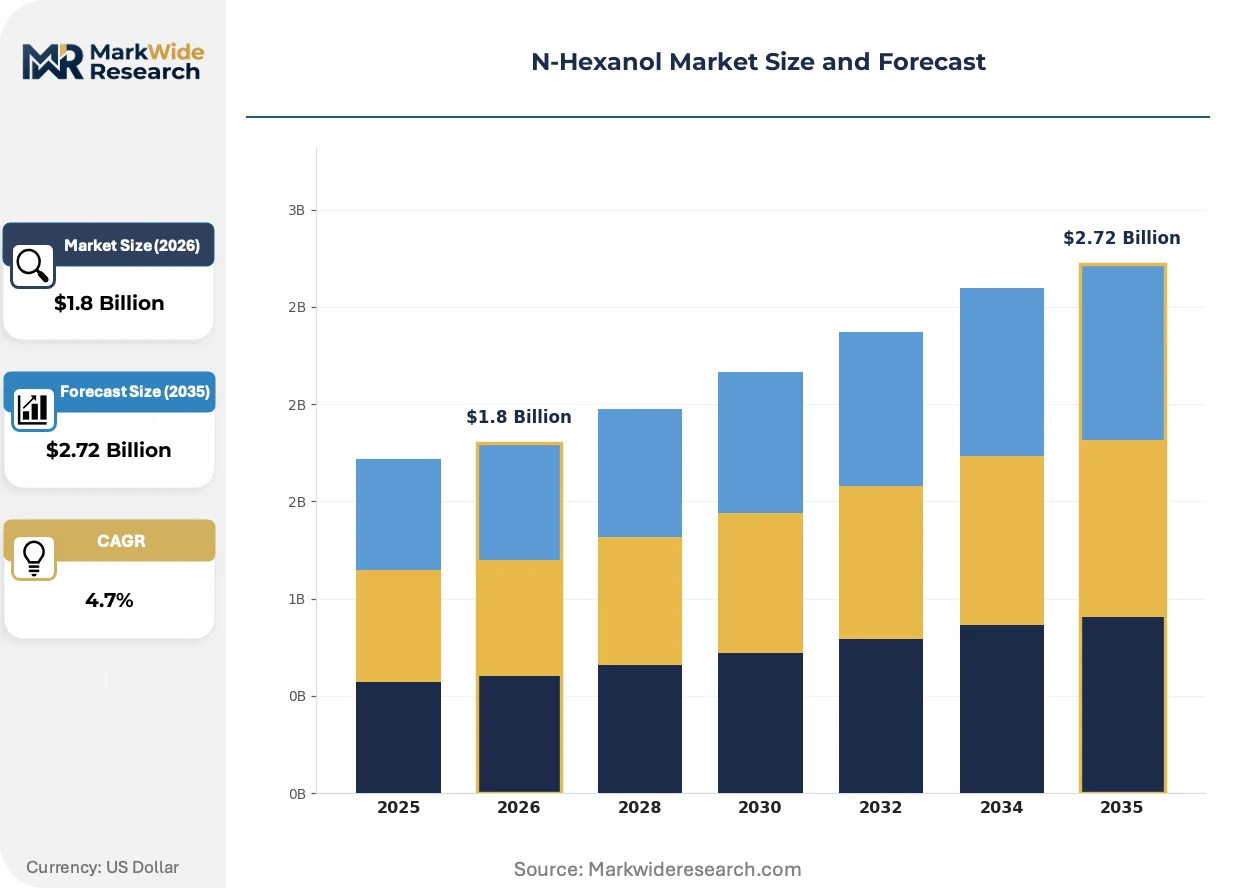
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Solvent, Chemical Intermediate, Flavors & Fragrances, Surfactants End Use Industry: Paints & Coatings, Pharmaceuticals, Agrochemicals, Personal Care Distribution Channel: Direct Sales, Distributors, Online Retail, Third-Party Vendors Application: Solvent in Chemical Synthesis, Coating Compounds, Plasticizers, Emulsifying Agents |
| Companies Covered | Sasol, BASF SE, Merck KGaA, Godavari Biorefineries, Nanjing Chemical Material Corporation, Yancheng Hongtai Bioengineering, Eastman Chemical Company, Honeywell International Inc., Triveni Interchem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
N-Hexanol Market Strategic Shifts
Process intensification in C6 alcohol refining and regulatory divergence across major chemical markets are compressing traditional supply arrangements while opening specialized high-purity segments.
Membrane separation technology for N-hexanol purification is absorbing capital allocation from European and Asian specialty chemical producers. Pharmaceutical synthesis and electronic-grade solvent buyers are adopting ceramic and polymeric membrane systems at pilot scale. This diffusion is absorbing market share from conventional distillation-based purification, compressing energy intensity differentials between integrated and merchant producers.
EPA solvent emission regulations under the Clean Air Act are constraining volatile organic compound thresholds in industrial coating formulations. Coating compound manufacturers face reformulation mandates or permit restrictions in high-ozone nonattainment areas. Architectural and automotive refinish segments in California, Texas, and Ohio are responding with low-VOC N-hexanol blends and alternative oxygenated solvent systems.
Direct sales channel expansion is displacing distributor networks for bulk agrochemical and paints and coatings procurement. Fragmented personal care and specialty pharmaceutical buyers still rely on regional chemical distributors, but volume concentration among multinational formulators enables supplier-managed inventory arrangements. China and India exhibit the fastest channel compression as domestic surfactant producers scale purchases of locally refined feedstock.
N-Hexanol Market Segmentation
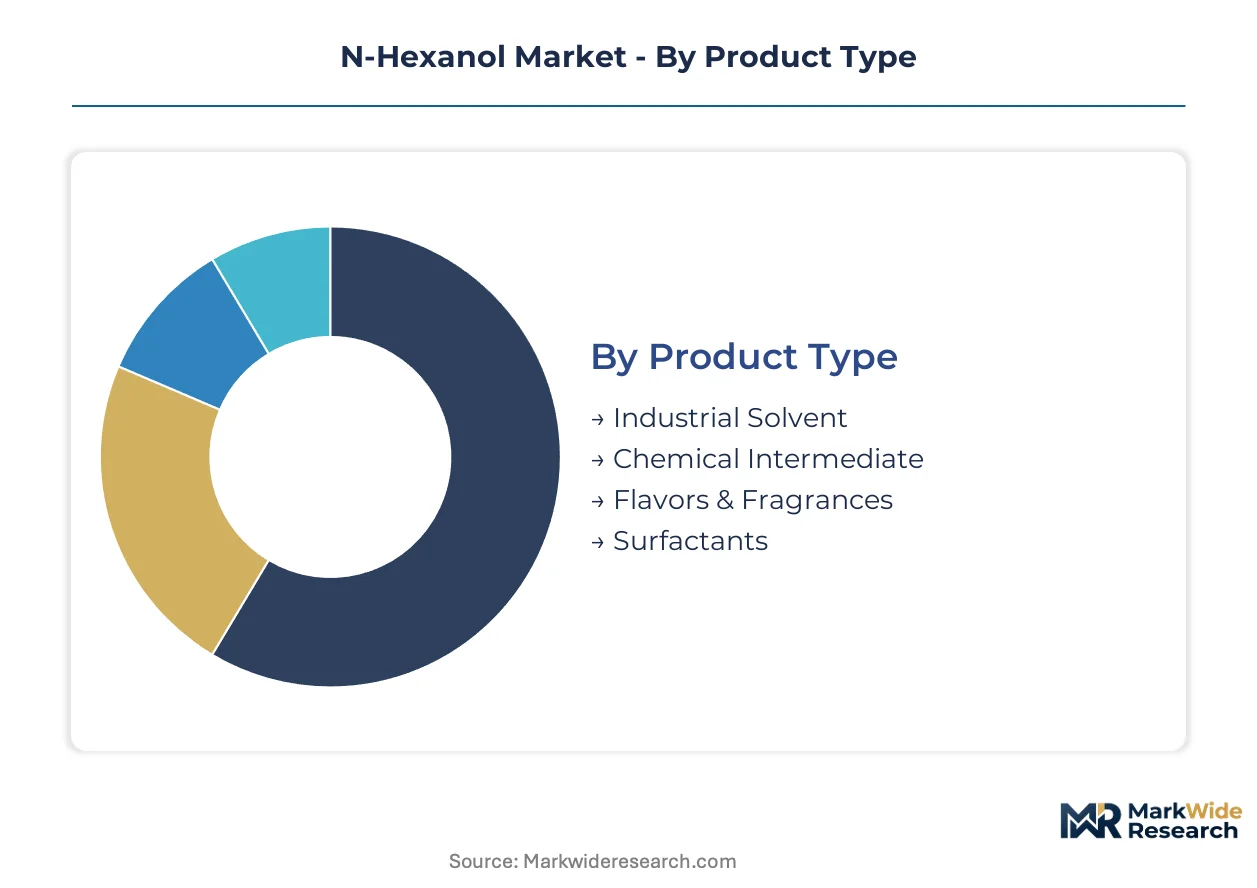
N-hexanol's dual role as commodity feedstock and precision solvent creates divergent specification requirements across end-use categories. Segmentation strategy must align purity grades with regulatory thresholds in target jurisdictions.
Product Type:
Chemical intermediate grades embed directly into downstream synthesis chains, while standalone solvent applications demand discrete lot certification and traceability documentation.
- Chemical Intermediate:Primary C6 alcohol streams hydroformylated from ethylene oligomerization serve plasticizer and coating resin manufacturers. Procurement concentrates in China where domestic surfactant producers scale purchases of locally refined feedstock under GB quality standards.
- Industrial Solvent:Technical-grade material functions as reaction medium and extraction solvent in agrochemical synthesis. EPA Clean Air Act VOC constraints in California, Texas, and Ohio are pushing coating compound manufacturers toward higher-purity grades with reformulation mandates.
- Flavors & Fragrances:USP-NF and EP monograph-compliant grades command premium positioning through stringent purity certification.
- Surfactants:Ethoxylated C6 alcohols feed personal care and industrial cleaning compound formulations under divergent regional specifications.
Volume placements concentrate in Chemical Intermediate; the faster expansion belongs to Flavors & Fragrances.
End Use Industry:
Margin structures vary sharply between bulk coating applications and regulated pharmaceutical synthesis environments.
- Paints & Coatings:Architectural and automotive refinish segments absorb the largest solvent volumes. REACH compliance in Europe and evolving EPA emission standards are tightening purity specifications and reshaping supplier qualification criteria beyond base pricing.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis demands specialized solvent blends with embedded USP-NF and EP monograph documentation. Direct sales channels control bulk procurement as multinational formulators enable supplier-managed inventory arrangements.
- Agrochemicals:Technical-grade N-hexanol serves as reaction medium for pesticide intermediate production.
- Personal Care:Ethoxylated surfactant applications in shampoos and cleansers rely on distributor networks serving fragmented buyers.
Revenue concentration sits with Paints & Coatings; Pharmaceuticals claims the steepest expansion trajectory.
Distribution Channel:
Channel selection tracks purchase scale and formulation complexity, with bulk consumers bypassing intermediaries.
- Direct Sales:Bulk agrochemical and paints and coatings procurement flows through supplier-managed inventory arrangements. Volume concentration among multinational formulators in China and India exhibits the fastest channel compression.
- Distributors:Fragmented personal care and specialty pharmaceutical buyers still rely on regional chemical distributors for technical support and smaller lot sizes.
- Third-Party Vendors:Merchant traders serve spot market demand and non-integrated importers facing REACH registration barriers.
- Online Retail:Laboratory-scale and research-grade quantities move through digital platforms for academic and R&D procurement.
Transaction value pools in Direct Sales; Distributors retain the most complex service requirements.
Application:
Functional role determines purity tier and certification burden more than molecular identity.
- Plasticizers:Phthalate and non-phthalate plasticizer manufacturers represent the dominant volume sink for C6 alcohol feedstock. Specialty chemical producers in China are scaling procurement as domestic coating compound production expands.
- Solvent in Chemical Synthesis:Reaction medium applications in pharmaceutical and agrochemical manufacturing require ceramic and polymeric membrane purification systems at pilot scale.
- Coating Compounds:Alkyd and epoxy resin systems face reformulation complexity when substituting higher-purity grades.
- Emulsifying Agents:Surfactant intermediate production for personal care and industrial cleaning compounds operates under BIS quality standards in India.
Feedstock absorption peaks in Plasticizers; specialized solvent synthesis commands the highest unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in South Africa and Germany, while consumption pulls toward China and the United States. This geographic mismatch creates freight-logistics premiums and shapes regional pricing tiers. Regulatory divergence between ECHA, EPA, and SAMR compliance frameworks fragments specification standards across trade corridors.
United States
Coating compound manufacturers in California, Texas, and Ohio absorb technical-grade volumes for architectural and automotive refinish applications. EPA Clean Air Act VOC constraints in high-ozone nonattainment areas force reformulation toward higher-purity grades. The Gulf Coast petrochemical corridor anchors cracker-derived C6 alcohol capacity serving domestic plasticizer producers.
Germany
REACH registration mandates elevate compliance barriers for non-integrated importers, favoring producers with captive feedstock supply and comprehensive toxicological dossiers. The Rhine-Ruhr industrial cluster hosts integrated chemical complexes supplying European coating and pharmaceutical synthesis markets. ECHA substance evaluation procedures extend product registration cycles, compressing margins for merchant traders.
China
Domestic surfactant and coating compound producers under SAMR-enforced GB quality standards scale purchases of locally refined N-hexanol feedstock. The Yangtze River Delta concentration of specialty chemical manufacturers drives volume absorption for plasticizer intermediate production. Provincial environmental inspections under MEE oversight tighten wastewater discharge standards for C6 alcohol refiners.
India
Personal care and industrial cleaning compound producers under BIS quality standards expand local C6 alcohol refining capacity to reduce import dependency. The Gujarat chemical belt hosts emerging merchant capacity targeting ethoxylated surfactant applications. Domestic agrochemical synthesis operations in Maharashtra absorb technical-grade volumes for pesticide intermediate production.
South Africa
Fischer-Tropsch integrated energy-chemical complexes sustain cost-advantaged production of high-purity C6 alcohol streams for export markets. Sasol's Secunda complex anchors global supply of synthetic fuel pathway N-hexanol. Geographic single-source risk concentrates for European coating compound manufacturers dependent on South African merchant supply.
N-Hexanol Market Competitive Environment
Capital-heavy producers compete with asset-light distributors across specification tiers. The vendor base stratifies between integrated petrochemical majors, regional refiners, and merchant traders serving spot demand. Three archetypes dominate: Fischer-Tropsch integrated synthetics producers, cracker-derived alcohol specialists, and natural fatty alcohol reducers. Competitive moves concentrate on backward integration into captive feedstock and membrane purification technology licensing.
Among Fischer-Tropsch integrated producers, Sasol anchors cost-advantaged supply through synthetic fuel technology pathways. BASF SE and Eastman Chemical Company occupy positions within the cracker-derived and specialized solvent blend tiers respectively, exemplifying divergent strategic postures between commodity scale and pharmaceutical-grade specialization. Merck KGaA represents the precision-grade archetype serving monograph-compliant applications.
| Leading Market Players |
|---|
| Sasol |
| BASF SE |
| Merck KGaA |
| Godavari Biorefineries |
| Nanjing Chemical Material Corporation |
| Yancheng Hongtai Bioengineering |
| Eastman Chemical Company |
| Honeywell International Inc. |
| Triveni Interchem |
| Others |
Value Chain & Pricing Dynamics
Ethylene feedstock index volatility cascades through N-hexanol supply chains, compressing margins for cracker-dependent producers while amplifying cost advantages for Fischer-Tropsch integrated suppliers serving European coating compound manufacturers.
Pricing Analysis
Margin tightening in technical-grade N-hexanol reflects ethylene price swings tied to naphtha and natural gas liquid markets. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and intermediate-grade levels separates USP-NF monograph-compliant material from standard coating formulations. Cost-down pressure on merchant traders accelerates because REACH Annex XV dossier preparation extends registration cycles. Bulk agrochemical buyers exhibit highest price sensitivity; pharmaceutical synthesis customers accept premiums for embedded lot-traceability documentation.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke patterns for N-hexanol cargo flows. Supply concentrates in South Africa, Germany, and China, with Fischer-Tropsch integrated capacity at Sasol's Secunda complex and cracker-derived streams along the Rhine-Ruhr and Gulf Coast corridors. Raw material dependencies draw from ethylene oligomerization feedstock, natural fatty alcohol reduction bases, and hydroformylation catalyst systems. Single-source vulnerability concentrates for European coating manufacturers dependent on South African merchant supply. Distribution runs through direct sales channels for bulk procurement and regional chemical distributors for fragmented personal care buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
N-hexanol market positioning hinges on backward integration into captive C6 alcohol feedstock supply, with membrane purification technology licensing emerging as the decisive capability differentiator across specification tiers.
For Market Incumbents: Hedge against natural fatty alcohol competition by securing Fischer-Tropsch integration or cracker-derived captive supply. Invest in ceramic membrane purification systems to defend pharmaceutical-grade positioning against emerging Asian refiners. Channel control through supplier-managed inventory arrangements with multinational coating compound manufacturers reinforces volume concentration advantages. For New Entrants and Emerging Players: Regional chemical distributors serving fragmented personal care and specialty pharmaceutical buyers present the most penetrable channel entry point. Target India surfactant manufacturing under BIS quality standards, where domestic C6 alcohol refining capacity expansion creates procurement gaps. A technical-grade toll refining partnership with established Fischer-Tropsch producers enables qualification without feedstock integration. For Investors and Strategic Acquirers: Distressed-cycle entries favor membrane technology licensors in Germany and Japan facing margin compression from energy cost inflation. Mid-cap pharmaceutical solvent specialists with USP-NF monograph compliance and established direct sales relationships offer viable acquisition profiles. Watch EPA Clean Air Act enforcement intensity in California, Texas, and Ohio as the inflection indicator for low-VOC N-hexanol blend demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Feedstock | Eliminates ethylene price volatility exposure for cracker-dependent producers serving coating compound manufacturers. |
| Membrane Purification Technology Licensing | Ceramic and polymeric systems absorb capital allocation from European and Asian specialty chemical producers. |
| Long-term Supply Agreement with Pharmaceutical Formulators | Direct sales channel expansion displaces distributor networks for USP-NF monograph-compliant solvent procurement. |
| Joint Venture in India Surfactant Manufacturing | Domestic C6 alcohol refining capacity under BIS standards reduces import dependency for personal care compound producers. |
| Green Manufacturing Transition to Lower-VOC Grades | EPA Clean Air Act alignment in high-ozone nonattainment areas creates pull for reformulated coating solvents. |
Study Parameters
Independent corroboration across primary interviews with plant managers at Fischer-Tropsch integrated complexes, procurement leads at downstream plasticizer manufacturers, distribution channel partners in European coating compound markets, and technical R&D directors at membrane separation technology developers underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical producers, and REACH registration dossiers submitted to ECHA. Bottom-up volume modeling triangulates against top-down ethylene derivative consumption estimates.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. Segmentation dimensions modeled include grade tier (pharmaceutical, industrial, intermediate), end-use industry (paints and coatings, pharmaceuticals, agrochemicals, personal care), and regional production hub (South Africa, Germany, China, United States, India). CAGRs derive from ethylene feedstock demand elasticity, plasticizer manufacturing capacity expansion trajectories, and regulatory compliance cost pass-through assumptions.
Caveats apply where ethylene price volatility, REACH substance evaluation timeline extensions, or SAMR enforcement intensity shifts could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Acetylacetone Market
Organic Chemicals
Phenol Market
Organic Chemicals
N-Pentane Market
Organic Chemicals
Synthetic Camphor Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
Pyridine Derivatives Market
Organic Chemicals
Gamma-Butyrolactone (GBL) Market
Organic Chemicals
Heterocyclic and Fluoro Organic Compounds Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
2-Methylbutanoic Acid Market
Organic Chemicals
High Purity Metal Organics Market
Organic Chemicals
Synthetic Antioxidants Market
Organic Chemicals
Dioxolane Market
Organic Chemicals
Acetic Acid Market
Organic Chemicals
Phenolic Board Market