
 North America Pectin Market | 2026-2036
North America Pectin Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pectin Market Intelligence
The EPA's Clean Label Initiative and major retailer sustainability mandates is pivoting North American food processors toward plant-derived stabilizers. Cargill Incorporated leverages its integrated citrus peel supply chain to secure raw material continuity. CP Kelco anchors production capacity through controlled fermentation and extraction infrastructure. DuPont de Nemours Inc. differentiates via specialized amidated pectin grades for low-sugar applications.
Pectin is a complex polysaccharide rich in galacturonic acid units, extracted primarily from citrus peel and apple pomace through acid hydrolysis at controlled temperature and pH, functioning as a gelling agent, thickener, and stabilizer across food, pharmaceutical, and cosmetic systems. High methoxyl pectin dominates conventional jam and preserve applications where rapid set and firm gel strength remain essential. Low methoxyl pectin captures expanding share in reduced-sugar and dairy-alternative formulations where calcium-reactive gelling enables clean-label positioning. Citrus pectin commands premium positioning in nutraceutical channels due to standardized molecular weight fractions and documented functional bioactivity.
The FDA governs pectin as GRAS for food applications while the USDA enforces organic certification standards that constrain permissible extraction solvents and processing aids. Health Canada regulates pectin purity specifications through its Food and Drug Regulations, creating dual compliance obligations for cross-border suppliers. Stakeholders must monitor evolving EPA bio-based chemical designations and state-level extended producer responsibility frameworks that could reshape raw material sourcing economics and waste stream valorization requirements.
Market Dynamics
The North America pectin market pivots on regulatory mandates from the FDA and USDA that systematically displace synthetic hydrocolloids with plant-derived alternatives, forcing reformulation across processed food categories.
Growth Catalysts
- Clean-label mandates:The FDA's GRAS designation for pectin accelerates substitution of artificial stabilizers in conventional jam and preserve manufacturing.
- Plant-based dairy expansion:Low methoxyl pectin captures formulation share in oat and almond milk systems requiring calcium-reactive gelling without synthetic additives.
- USDA organic certification:Constrained solvent protocols create premium positioning for citrus peel pectin extracted through acid hydrolysis compliant with federal organic standards.
Market Restraints
- Citrus peel supply concentration:Raw material sourcing clusters in Florida and California citrus processing corridors, exposing processors to climate volatility and harvest fluctuation.
- Acid hydrolysis energy intensity:Controlled temperature and pH extraction demands sustained thermal input, elevating unit economics against fermentation-derived alternatives.
- Health Canada purity specifications:Cross-border suppliers face dual compliance testing under Food and Drug Regulations, extending certification timelines for Canadian market entry.
Strategic Opportunities
- Midwest dairy-alternative corridor:Wisconsin and Minnesota processing hubs underutilize low methoxyl pectin for clean-label yogurt and cheese analog applications.
- EPA bio-based chemical designation:Emerging federal classification frameworks could unlock procurement preferences for pectin in institutional foodservice channels.
- Nutraceutical molecular weight fractionation:Standardized citrus pectin isolates with documented bioactivity penetrate dietary supplement distribution through specialized ingredient brokers.
Industry Challenges
- Galacturonic acid assay standardization:Analytical method variance between USP and AOAC protocols creates batch release disputes and customer qualification friction.
- Legacy jam equipment retrofit:High methoxyl pectin rapid-set behavior requires kettle and filling line recalibration, compressing adoption timelines for smaller preserve manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pectin Market |
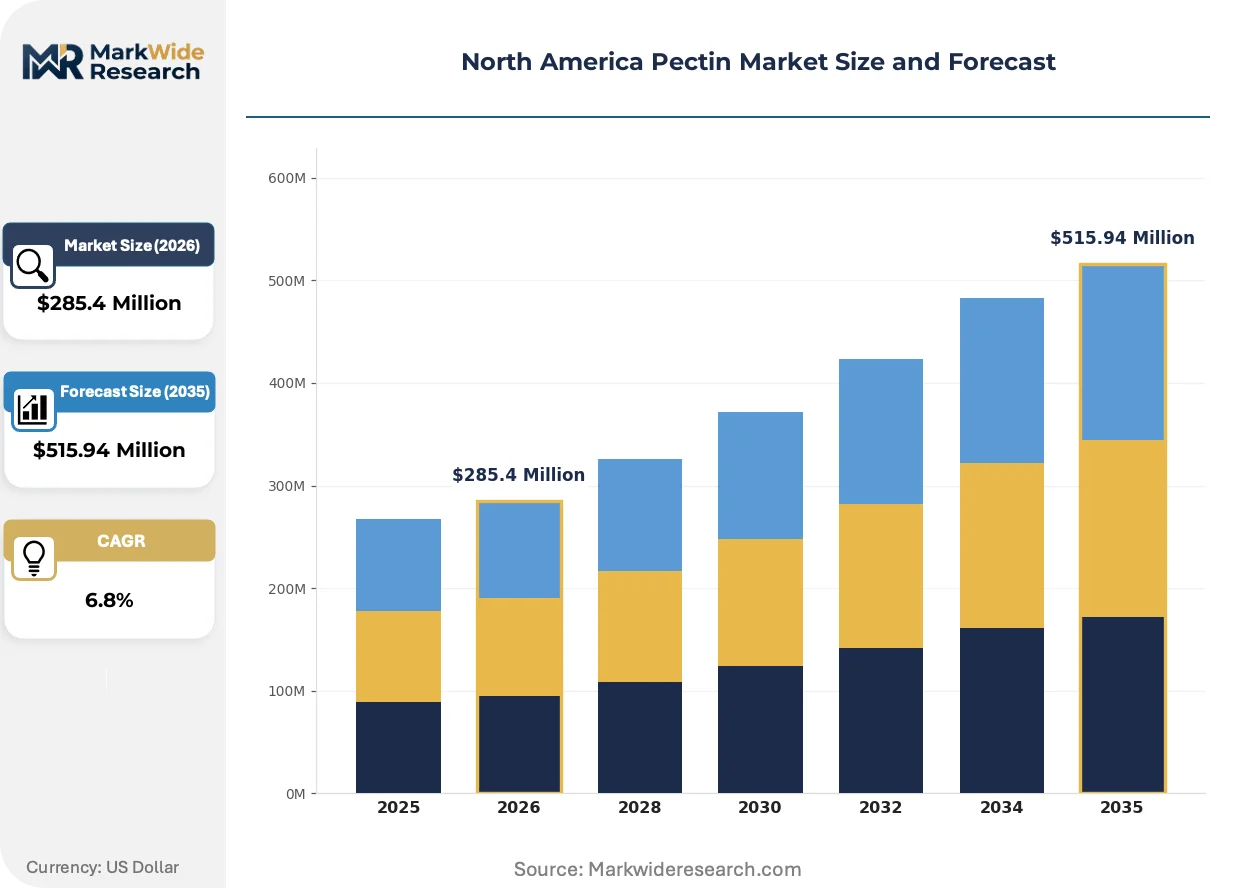
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Methoxyl Pectin, Low Methoxyl Pectin, Amidated Pectin, Citrus Pectin Application: Food & Beverages, Pharmaceuticals, Personal Care, Nutraceuticals End User: Food Manufacturers, Beverage Producers, Cosmetic Companies, Pharmaceutical Firms Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Herbstreith and Fox Corporate Group, International Flavors & Fragrances, Cargill Incorporated, DuPont de Nemours Inc., Silvateam S.p.A., Ingredion Incorporated, CP Kelco, CEAMSA, Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pectin Market Strategic Shifts & Innovations
Continuous extraction monitoring systems are compressing pectin production variability while regulatory bio-based designations restructure procurement hierarchies across North American food manufacturing.
Enzymatic precision processing is automating molecular weight control during citrus peel extraction, enabling real-time adjustment of esterification degrees. Mid-tier preserve manufacturers in the US Northeast are adopting these sensor-integrated systems to reduce batch rejection rates. The technology is automating quality assurance labor, shifting competitive advantage toward facilities with captive laboratory infrastructure.
The EPA's advancing bio-based chemical procurement guidelines are mandating federal foodservice contractors to document renewable content percentages. This policy compresses synthetic hydrocolloid eligibility for school nutrition and military ration programs. Low methoxyl pectin suppliers with third-party bio-content certification capture preferential vendor status in these channels.
Direct formulation partnerships between pectin processors and regional dairy-alternative startups are displacing traditional ingredient distributor intermediation. These arrangements embed technical service teams within customer R&D facilities, accelerating clean-label product development cycles. The pattern concentrates in California and New York metropolitan areas where plant-based beverage innovation clusters.
North America Pectin Market Segmentation
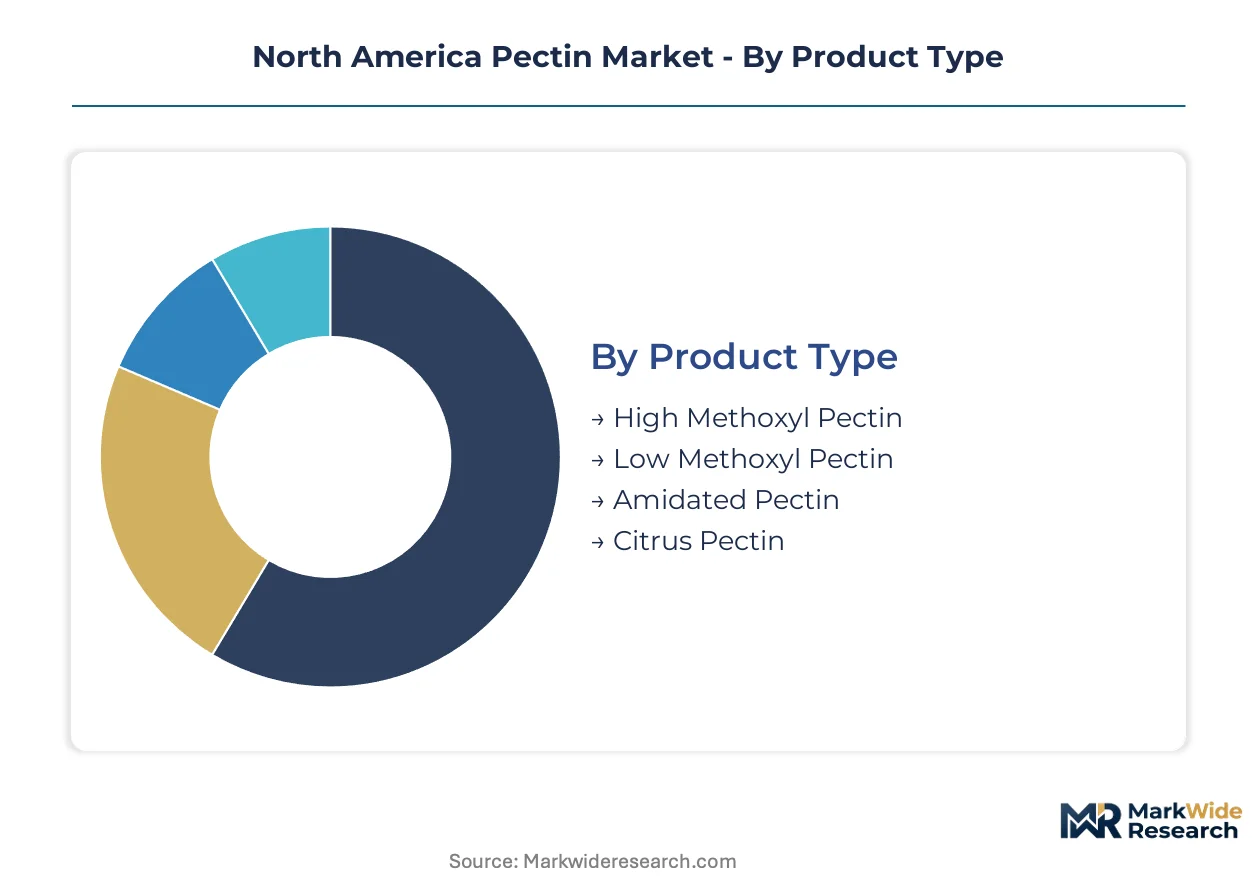
North American pectin procurement bifurcates sharply between commodity-grade stabilizers for mass-market preserves and premium molecular-weight fractions for nutraceutical applications. FDA GRAS status governs food-grade segments while Health Canada purity specifications impose dual testing burdens on cross-border suppliers. Each segment carries distinct certification timelines that reshape customer qualification economics.
Product Type:
Certification intensity escalates from conventional food-grade pectin through pharmaceutical-grade citrus isolates, with amidated variants requiring specialized FDA food additive petitions for novel gelling applications.
- High Methoxyl Pectin:Rapid-set gelling polysaccharide with degree of esterification above 50%, extracted through acid hydrolysis of citrus peel under controlled thermal conditions. Demand concentrates in Midwest and Northeast jam manufacturing corridors where legacy kettle equipment favors conventional rapid-set behavior. USDA organic certification protocols constrain permissible extraction solvents, extending lead times for premium preserve formulations.
- Low Methoxyl Pectin:Calcium-reactive gelling agent with degree of esterification below 50%, enabling gel formation without high sugar solids. Wisconsin and Minnesota dairy-alternative processing hubs underutilize this grade for clean-label oat milk and yogurt analog applications. EPA bio-based procurement guidelines position certified low methoxyl grades for federal foodservice contracts.
- Amidated Pectin:Modified polysaccharide with amidated galacturonic acid residues, delivering enhanced calcium sensitivity for low-sugar systems.
- Citrus Pectin:Standardized molecular-weight fractions with documented bioactivity, commanding nutraceutical channel premiums through specialized ingredient brokers.
High methoxyl pectin sits at the top of the volume ranking, with low methoxyl pectin climbing the fastest.
Application:
Application segments distribute across cost tiers, with pharmaceutical and nutraceutical channels absorbing price premiums for analytical-grade material while food and beverage procurement optimizes per-unit gelling efficiency.
- Food & Beverages:Dominant consumption channel spanning conventional preserves, dairy alternatives, and clean-label beverages. FDA GRAS designation streamlines formulation approval, though organic certification adds solvent-protocol compliance costs. Northeast and Midwest processing corridors concentrate manufacturing demand.
- Pharmaceuticals:Excipient applications in controlled-release tablet matrices and suspension stabilizers. USP monograph compliance and batch-specific galacturonic acid assays elevate qualification friction versus food-grade material.
- Personal Care:Rheology modifier for emulsion stability in topical formulations, typically sourcing lower-purity technical grades.
- Nutraceuticals:Molecular-weight-fractionated isolates for immune modulation and detoxification claims, penetrating dietary supplement distribution through specialized brokers.
Food and beverages commands absolute volume leadership, with nutraceuticals gaining share fastest on premium pricing acceptance.
End User:
Customer type determines procurement modality, with multinational food manufacturers negotiating long-term supply agreements while regional dairy-alternative startups favor direct technical service partnerships.
- Food Manufacturers:Large-scale preserve and bakery producers with established acid-hydrolysis pectin specifications. Clean-label reformulation mandates from major retailers drive substitution of synthetic stabilizers.
- Beverage Producers:Plant-based dairy and functional drink formulators requiring calcium-reactive gelling without high solids. California and New York metropolitan innovation clusters concentrate demand.
- Cosmetic Companies:Formulators of natural-positioned emulsions and gels, typically sourcing through distributors rather than direct processor relationships.
- Pharmaceutical Firms:Dosage form developers with stringent USP compliance requirements and extended vendor qualification protocols.
Food manufacturers anchor procurement volume, with beverage producers expanding most quickly on plant-based segment growth.
Distribution Channel:
Channel selection correlates with customer scale and technical service requirements, embedding pectin processors directly within R&D facilities for strategic accounts while commodity grades flow through traditional intermediaries.
- Direct Sales:Preferred by multinational food and pharmaceutical manufacturers with volume commitments and captive technical service needs. Direct partnerships embed formulation scientists within customer R&D facilities.
- Distributors:Traditional intermediaries serving mid-tier preserve manufacturers and regional cosmetic formulators with standardized grade offerings.
- Online Retail:Emerging channel for small-batch food entrepreneurs and research-scale pharmaceutical procurement, typically limited to technical-grade and sample quantities.
- Wholesalers:Bulk aggregation for foodservice and institutional channels, increasingly constrained by EPA bio-based content documentation requirements.
Direct sales holds volume primacy, with distributor relationships expanding most quickly among mid-tier regional processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pectin extraction technology first scaled commercially in the United States during the early twentieth century, leveraging abundant citrus peel waste from Florida's juice processing industry. This established North America as the foundational geography for industrial pectin manufacturing before European and Asian competitors emerged.
United States
Florida and California citrus processing corridors supply the dominant share of raw material feedstock for domestic pectin extraction. The FDA's GRAS designation streamlines formulation approvals for food manufacturers, though USDA organic certification adds solvent-protocol compliance costs. Midwest dairy-alternative processing hubs in Wisconsin and Minnesota are expanding low methoxyl pectin uptake for clean-label oat milk and yogurt analog applications.
Canada
Cross-border suppliers face dual compliance testing under Health Canada Food and Drug Regulations purity specifications, extending certification timelines for market entry. The country's food manufacturers concentrate in Ontario and Quebec, importing pectin primarily for preserve and bakery applications. Toronto and Montreal metropolitan areas host regional distribution nodes serving mid-tier processors with standardized grade offerings.
Mexico
Emerging demand from the country's processed food sector is pivoting toward natural stabilizers as major retailers implement clean-label procurement mandates. The national food safety regulator enforces additive purity standards that align with US FDA frameworks, facilitating integrated North American supply chains. Guadalajara and Mexico City processing clusters represent the primary consumption nodes for hydrocolloid imports.
North America Pectin Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification grade and application specialization dimensions. The North American pectin market exhibits moderate consolidation, with integrated agricultural processors and specialized hydrocolloid manufacturers occupying distinct tier positions. Three archetypes dominate: citrus peel supply chain integrators, fermentation-based extraction specialists, and molecular-weight fractionation experts for nutraceutical channels. Capacity expansion in low methoxyl grades and direct technical service partnerships with dairy-alternative startups constitute the prevailing competitive moves.
Within the integrated supply chain tier, Cargill Incorporated anchors raw material security through captive citrus peel sourcing. CP Kelco exemplifies controlled fermentation and extraction infrastructure specialization. DuPont de Nemours Inc. occupies a position amidating pectin specialists serving reduced-sugar formulation requirements.
| Leading Market Players |
|---|
| Herbstreith and Fox Corporate Group |
| International Flavors & Fragrances |
| Cargill Incorporated |
| DuPont de Nemours Inc. |
| Silvateam S.p.A. |
| Ingredion Incorporated |
| CP Kelco |
| CEAMSA |
| Tate & Lyle PLC |
| Others |
Cost & Logistics Intelligence
Captive citrus peel sourcing through Florida and California juice processing corridors anchors supply security and pricing power for integrated pectin manufacturers. This backward integration into raw material streams insulates dominant processors from spot market volatility while enabling grade-based price stratification that smaller compounders cannot replicate.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade levels governs North American pectin transactions. Price differentiation hinges on USP monograph compliance and USDA organic certification status, with certified organic citrus pectin commanding substantial premiums over conventional acid-hydrolyzed grades. Cost compression in commodity food-grade segments is intensifying because mid-tier preserve manufacturers consolidate supplier relationships. Beverage producers seeking calcium-reactive low methoxyl grades exhibit the highest price sensitivity, while pharmaceutical excipient buyers prioritize batch consistency over unit cost.
Supply Chain Analysis
Citrus peel feedstock rests on Florida and California agricultural processing infrastructure, with secondary sourcing from Mexican and Brazilian citrus corridors during harvest gaps. Raw material dependencies include sulfuric acid for hydrolysis, calcium salts for low methoxyl demethylation, and standardized enzyme preparations for molecular weight control. Single-source vulnerability concentrates in Florida citrus processing, where hurricane exposure and citrus greening disease threaten annual peel availability. Distribution runs through direct technical service partnerships for multinational food manufacturers and regional distributor networks for mid-tier preserve processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America pectin market functions as a stable compounder, with FDA and USDA clean-label mandates generating steady substitution demand that outpaces macroeconomic cyclicality.
For Market Incumbents: Lock in raw material security through long-term peel supply agreements with Florida and California citrus processors, insulating against climate-driven harvest volatility. Expand low methoxyl production capacity in Midwest dairy-alternative corridors before fermentation-derived hydrocolloids capture formulation share in oat milk systems. Prioritize USP certification investment to defend pharmaceutical excipient margins against European citrus pectin imports. For New Entrants and Emerging Players: Enter via nutraceutical molecular weight fractionation, where specialized ingredient brokers absorb premium pricing for standardized bioactive isolates with documented immune modulation claims. Target underpenetrated cosmetic emulsion channels in California and New York metropolitan areas, where natural-positioned rheology modifiers command technical-grade premiums without food-grade regulatory burdens. Pursue direct formulation partnerships with plant-based yogurt startups seeking embedded technical service. For Investors and Strategic Acquirers: Roll-up economics work for regional pectin compounders with captive laboratory infrastructure because enzymatic precision processing automation is compressing batch rejection rates and shifting competitive advantage toward facilities with real-time quality assurance capabilities. Over a multi-year holding period, consolidation of mid-tier processors with USDA organic certification creates platform value through cross-selling into federal foodservice channels. Watch EPA bio-based chemical designation timelines as the critical inflection signal for institutional procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citrus Peel Supply | Captive raw material access from Florida processors insulates against climate-driven harvest volatility and spot price spikes. |
| Low Methoxyl Capacity Expansion | Midwest production hubs near Wisconsin oat milk processors reduce freight costs and accelerate customer technical service response. |
| USP Pharmaceutical Certification Investment | Excipient-grade compliance opens controlled-release tablet matrix applications with higher margins than food-grade commodities. |
| Enzymatic Precision Processing Deployment | Real-time esterification degree control reduces batch rejection rates and shifts advantage toward laboratory-integrated facilities. |
| Direct Technical Service Partnerships | Embedded R&D collaboration with New York and California dairy-alternative startups displaces traditional distributor intermediation. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with citrus processing plant managers, hydrocolloid procurement leads at multinational food manufacturers, FDA regulatory affairs specialists, and dairy-alternative startup formulation scientists with secondary validation. Secondary sources included FDA GRAS notices, USDA organic certification databases, Health Canada Food and Drug Regulations, EPA bio-based procurement guidelines, and SEC filings from publicly traded ingredient suppliers. Bottom-up demand modeling across end-use segments triangulated against top-down supply capacity assessments.
Segment-weighting approaches distributed value and volume projections across high methoxyl, low methoxyl, amidated, and citrus pectin grades, with additional stratification by food and beverage, pharmaceutical, personal care, and nutraceutical applications. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion schedules throughout the forecast period. Industry-specific forecast inputs incorporated EPA bio-based designation timelines, USDA organic certification growth trajectories, and plant-based dairy alternative formulation adoption curves.
Inputs from FDA regulatory filings and citrus industry harvest reports were available through the study window; gaps in real-time enzymatic processing cost data introduce uncertainty bands around margin projections for precision-extraction facilities. Forecasts reflect documented assumptions regarding clean-label mandate enforcement continuity and citrus greening disease progression rates. A small set of triggers—including EPA bio-based procurement rule finalization and Florida hurricane severity indices—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Dipotassium Guanylate Market
Additives
Europe UV Stabilizers Market
Additives
Clouding Agents Market
Additives
Ballast Tank Corrosion Inhibitors Market
Additives
Sodium Citrate Dihydrate Market
Additives
Ethoxyquin Market
Additives
Pearlizers Market
Additives
Global Silica-Based Matting Agents Market
Additives
Global Mold Release Agents Market
Additives
Additives for Floor Coatings Market
Additives
Sodium Citrate Anhydrous Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market
Additives
China Feed Additives Market
Additives
Global Butyric Acid Derivatives Market
Additives
Refining Additives Market