
 Ethyl Acetate Market | 2026-2036
Ethyl Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Ethyl Acetate Market Intelligence
The shift towards long-term tolling agreements for feedstock supply is narrowing the competitive field for new entrants. This capital-intensive environment favors established producers. Celanese Corporation leverages its significant manufacturing scale to manage input cost volatility. Eastman Chemical Company specializes in high-purity grades for pharmaceutical applications, while INEOS Group controls key upstream petrochemical assets.
Ethyl acetate is an organic compound with the formula CH3COOCH2CH3, produced through the esterification of ethanol and acetic acid. Its primary industrial function is as a versatile, low-toxicity solvent. The paints and coatings application remains the largest consumption segment, driven by its fast evaporation rate. Demand for pharmaceutical grade ethyl acetate is growing, commanding higher margins due to stringent purity requirements.
Regulatory frameworks like Europe's REACH and the US EPA's volatile organic compound (VOC) limits directly influence solvent selection in end-use industries. In China, compliance with GB standards for chemical purity and safety is mandatory for market access. Producers must now decide whether to invest in bio-based production routes or optimize existing petrochemical-based processes to remain competitive.
Market Dynamics
The ethyl acetate market is defined by a fundamental tension between established petrochemical production routes and emerging bio-based alternatives. This bifurcation, driven by regulatory pressures for sustainability and the persistent volatility of fossil fuel feedstocks, is forcing producers to make critical long-term capital allocation decisions.
Growth Catalysts
- Bio-based Mandates:Regulatory frameworks, particularly the EU Green Deal, create strong incentives for the adoption of bio-based ethyl acetate in consumer-facing products like cosmetics and food packaging, pulling demand for greener solvent alternatives.
- Paints and Coatings Formulation:The global paints and coatings industry's continuous need for effective, fast-evaporating, and low-toxicity solvents sustains a large, foundational demand base for ethyl acetate in industrial and architectural applications.
- Chinese Industrial Expansion:China's massive and growing chemical manufacturing sector acts as a significant demand center, with domestic consumption in adhesives, inks, and coatings applications absorbing substantial production volume.
Market Restraints
- Feedstock Price Volatility:The market is directly exposed to price fluctuations in its primary feedstocks, ethanol and acetic acid, which are subject to the volatilities of both agricultural commodity markets and petrochemical price cycles.
- Solvent Substitution Risk:In certain price-sensitive applications, ethyl acetate faces competition from other solvents like methyl ethyl ketone (MEK), acetone, and toluene, which can be substituted based on formulation cost and performance requirements.
- Stringent VOC Regulations:Increasingly strict volatile organic compound (VOC) limits, such as those enforced by the US EPA, can constrain the use of ethyl acetate in certain coatings and cleaning products, pushing end-users toward exempt solvents or water-based systems.
Strategic Opportunities
- High-Purity Electronics Grade:Developing and marketing ultra-high purity ethyl acetate presents an opportunity to serve the electronics industry, where it can be used as a precision cleaning solvent for semiconductor and circuit board manufacturing.
- Advanced Bio-production Pathways:Investment in R&D for producing bio-ethyl acetate from non-food cellulosic biomass or waste streams could unlock significant cost advantages and resolve food-versus-fuel debates, creating a new competitive edge.
- Southeast Asian Market Entry:Targeting emerging industrial economies in Southeast Asia, such as Vietnam and Indonesia, offers growth potential as their manufacturing bases for textiles, footwear, and packaging expand.
Industry Challenges
- Bio-refinery Capital Costs:The significant capital expenditure required to construct new, large-scale bio-based ethyl acetate production facilities poses a high barrier to entry and a substantial financial risk for producers.
- Chemical Registration Timelines:Navigating the complex and time-consuming chemical registration processes, such as Europe's REACH, for new bio-based grades can delay market entry and add considerable administrative overhead.
- Dual Supply Chain Complexity:Managing segregated supply chains for petrochemical and bio-based feedstocks introduces logistical complexities and requires sophisticated inventory management to optimize production and prevent cross-contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethyl Acetate Market |
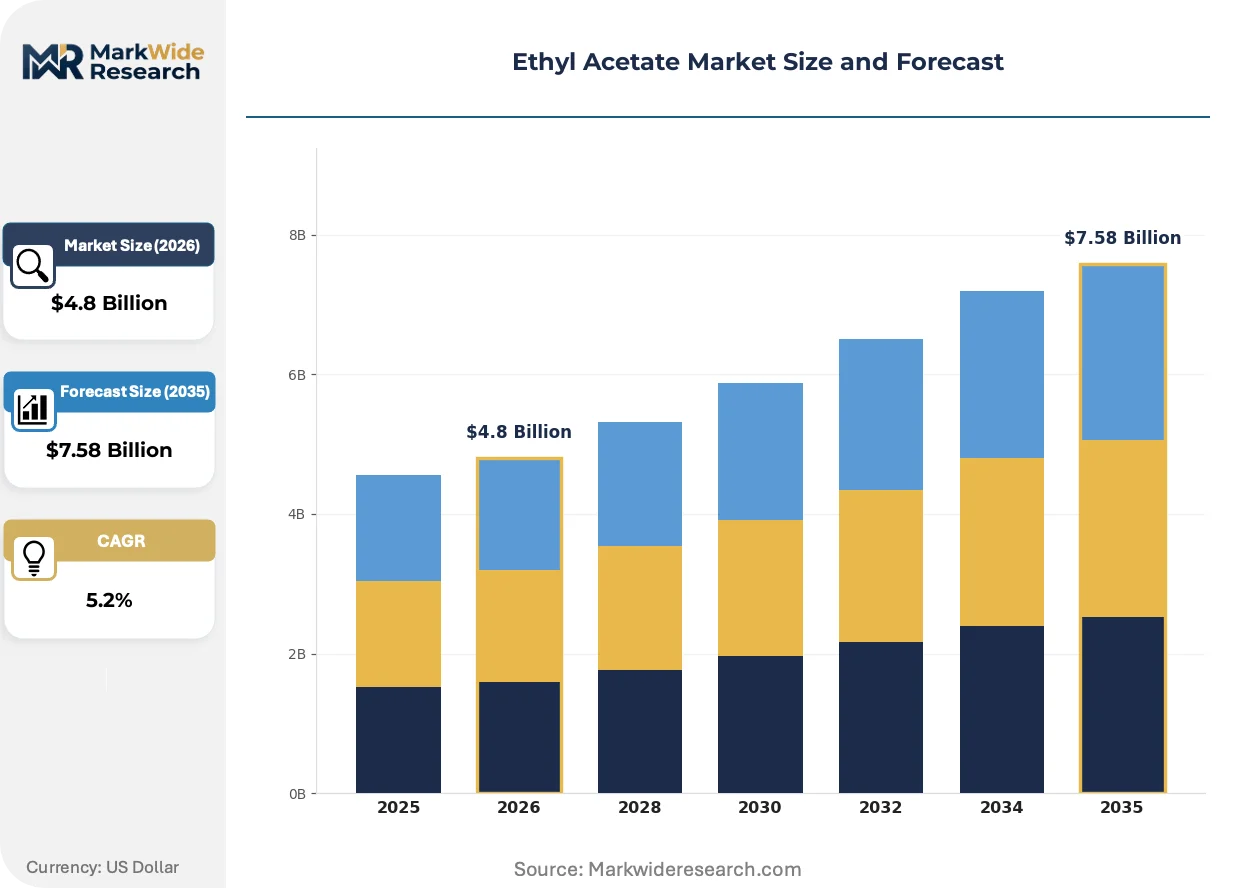
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Food Grade, Technical Grade Application: Adhesives, Paints & Coatings, Pharmaceuticals, Cosmetics, Printing Inks End User Industry: Chemical Manufacturing, Personal Care, Food & Beverage, Agrochemicals Packaging Type: Drums, Bulk Containers, Intermediate Bulk Containers, Bottles |
| Companies Covered | Daicel Corporation, Solvay S.A., Celanese Corporation, Sasol Ltd, BASF SE, Eastman Chemical Company, Jubilant Pharmova Ltd., Sipchem, INEOS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethyl Acetate Market Strategic Shifts & Innovations
Producers are navigating a strategic crossroads, balancing investments in optimizing traditional petrochemical processes against the high-capital, high-reward path of bio-based production. This dynamic is reshaping long-term supply agreements, technology choices, and compliance strategies across the value chain.
Bio-based ethyl acetate production utilizes fermentation of renewable feedstocks like corn or sugarcane to produce ethanol, which is then esterified. Formulators in the cosmetics, food and beverage, and pharmaceutical industries are adopting these grades to meet corporate sustainability goals and consumer demand for green products. The market’s core production philosophy is migrating from a singular reliance on petrochemical esterification to a dual-track system incorporating biorefinery pathways.
China's rigorous enforcement of its national GB standards for chemical purity and safety is a significant regulatory trend. This action compels both domestic and foreign producers to heighten their quality control and process monitoring to secure or maintain market access. The pharmaceutical and food-grade segments are most impacted, necessitating comprehensive documentation and batch testing to demonstrate compliance with these stringent national requirements.
Large-volume buyers, especially in the paints and coatings sector, are increasingly moving from volatile spot market transactions to long-term tolling agreements. This shift supplants purely price-driven purchasing with strategic partnerships designed to ensure supply stability and hedge against feedstock cost fluctuations. This procurement pattern is most evident among major chemical consumers in North America and Europe seeking to de-risk their supply of essential solvents.
Ethyl Acetate Market Segmentation
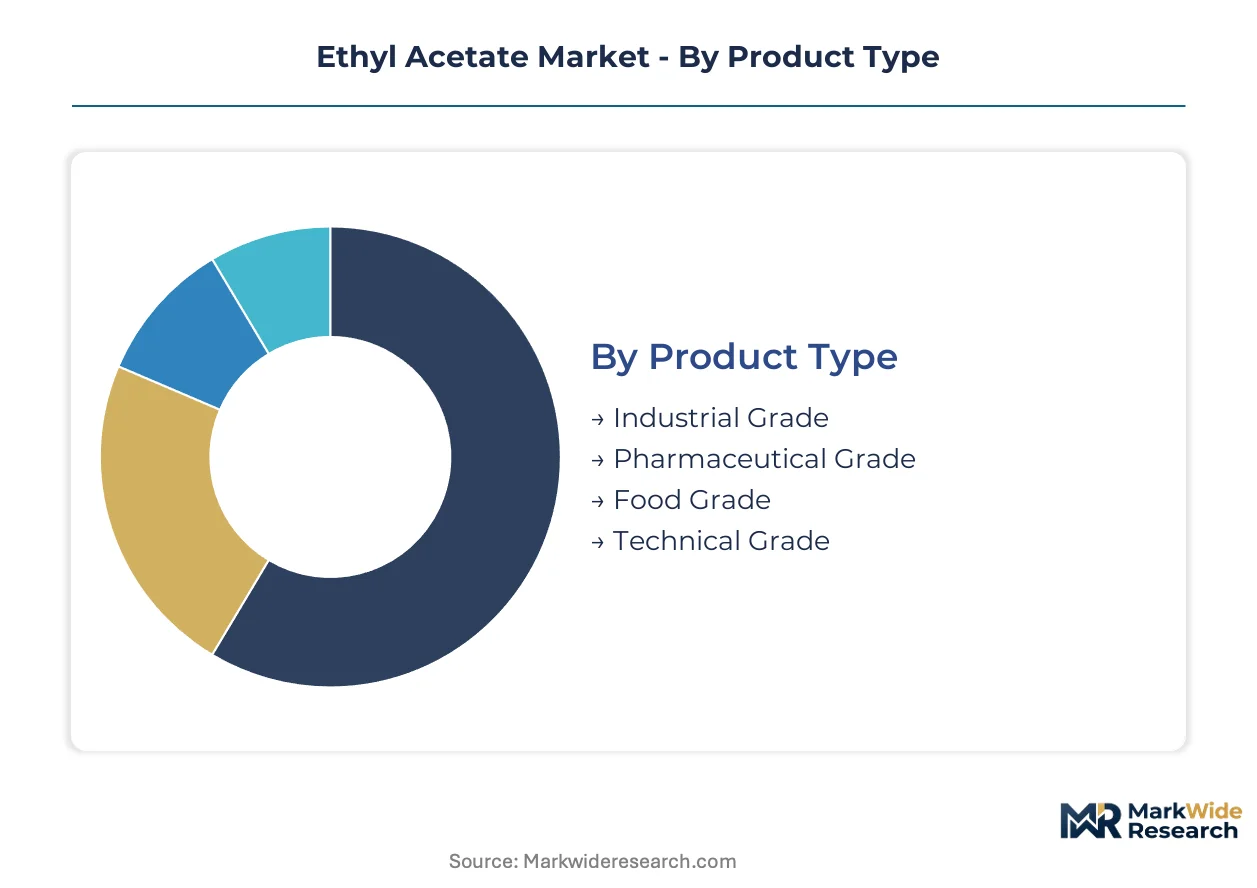
The ethyl acetate market segmentation reflects the diverse end-use requirements and the evolving regulatory landscape impacting solvent choices. Understanding these distinct segments is crucial for producers to align their manufacturing capabilities with specific market demands and compliance standards.
Product Type:
The product type segmentation reveals a mature industrial base alongside emerging high-value niches.
- Pharmaceutical Grade:This grade exhibits extremely high purity, often exceeding 99.5%, with minimal impurities like water or other organic compounds. Demand for this grade is concentrating in India and Ireland, driven by the stringent quality requirements of drug synthesis and extraction processes mandated by regulators like the US FDA and Europe's EMA.
- Industrial Grade:Industrial grade ethyl acetate serves as a foundational solvent for a wide array of manufacturing processes, characterized by its standard purity and cost-effectiveness. Consumption remains robust across chemical manufacturing hubs in China and Germany, where its fast evaporation rate is valued in high-volume production for paints and coatings.
- Food Grade:This specialized grade meets strict food contact material regulations and is employed in flavor extraction, decaffeination, and as a solvent in food additives.
- Technical Grade:Technical grade ethyl acetate offers a lower purity profile than industrial grades, suitable for less sensitive applications where cost is a primary consideration.
Industrial Grade handles the majority of throughput; Pharmaceutical Grade is the fastest mover on share.
Application:
Ethyl acetate applications vary significantly, driven by specific performance requirements and regulatory compliance.
- Paints & Coatings:Ethyl acetate functions as a fast-evaporating solvent in various paint and coating formulations, contributing to smooth film formation and quick drying times. Demand is consistently high in construction and automotive sectors across the United States and Brazil, where its low toxicity profile is preferred over more hazardous alternatives.
- Pharmaceuticals:Within the pharmaceutical industry, ethyl acetate acts as a versatile solvent for reaction, extraction, and purification steps in drug manufacturing. The pharmaceutical industry in Switzerland and Japan drives demand for high-purity grades, requiring compliance with strict pharmacopoeial standards to ensure product safety and efficacy.
- Adhesives:This compound is widely used as a solvent in adhesive formulations, providing good solvency for various resins and contributing to fast setting times.
- Cosmetics:Ethyl acetate serves as a solvent in nail polish removers, perfumes, and other cosmetic products, valued for its ability to dissolve resins and fragrances.
- Printing Inks:In the printing industry, ethyl acetate is a common solvent for flexographic and gravure inks, facilitating rapid drying and excellent print quality.
Demand in Paints & Coatings provides foundational stability, while Pharmaceuticals exhibits the steepest expansion trajectory.
End User Industry:
End-user industries dictate ethyl acetate specifications, reflecting their diverse operational needs and regulatory landscapes.
- Chemical Manufacturing:The chemical manufacturing sector utilizes ethyl acetate extensively as a process solvent, an extraction agent, and an intermediate in synthesizing other chemicals. Large chemical producers in Germany and South Korea represent significant buyers, integrating ethyl acetate into complex production chains for various downstream products.
- Food & Beverage:In the food and beverage industry, ethyl acetate is employed as a solvent for extracting flavors and fragrances, and in decaffeination processes. Producers in France and Italy increasingly seek bio-based variants, driven by consumer demand for natural ingredients and compliance with EU food safety regulations.
- Personal Care:The personal care industry incorporates ethyl acetate into products like nail care formulations and perfumes due to its solvent properties and mild odor.
- Agrochemicals:Ethyl acetate serves as a solvent in the formulation of pesticides and herbicides, aiding in the dissolution and delivery of active ingredients.
The Chemical Manufacturing sector consumes the largest volumes, but the Food & Beverage industry is expanding most quickly.
Packaging Type:
Packaging types reflect both the volume requirements of end-users and the logistics efficiency of the supply chain.
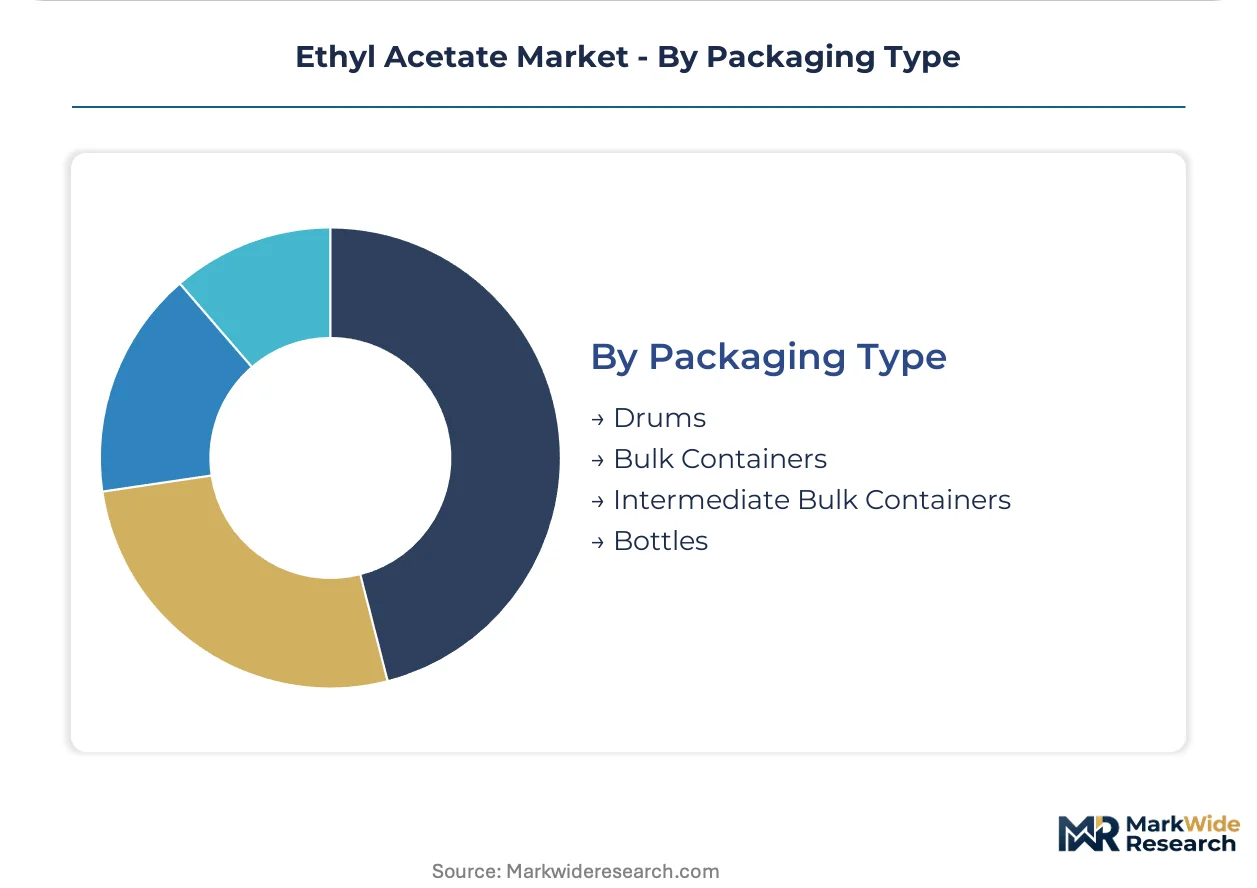
- Bulk Containers:Bulk containers, such as tank trucks and rail cars, facilitate the transport of very large volumes of ethyl acetate directly to major industrial consumers. This packaging type is prevalent among large-scale chemical manufacturers in the United States and Saudi Arabia, optimizing logistics costs for high-volume consumption.
- Drums:Drums typically hold 200-liter volumes and are a standard packaging choice for medium-sized industrial users and chemical distributors. This format offers a balance between transport efficiency and manageable handling for diverse industrial clients across Mexico and Poland.
- Intermediate Bulk Containers:Intermediate Bulk Containers (IBCs) provide a flexible solution for volumes between drums and bulk, often used for specialty applications or mid-sized batches.
- Bottles:Small bottles are primarily used for laboratory applications, research, and very specialized, low-volume industrial processes requiring precise quantities.
Bulk Containers dominate large-scale distribution, while Intermediate Bulk Containers are gaining share for flexible deliveries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global regulatory frameworks, particularly the EU Green Deal, are driving a fundamental shift towards sustainable production methods in the ethyl acetate market. These policies create strong incentives for bio-based alternatives and influence solvent selection across various end-use industries. This dynamic impacts regional market development and investment priorities.
China
China's massive chemical manufacturing sector sustains high demand for industrial grade ethyl acetate in adhesives and coatings. Compliance with national GB standards for chemical purity and safety is mandatory for market access. Chemical production hubs within the Yangtze River Delta continue to absorb substantial volumes.
United States
The United States market sees consistent demand from paints and coatings, driven by construction and automotive sectors. US EPA's volatile organic compound (VOC) limits influence solvent selection in formulation. Gulf Coast petrochemical complexes maintain significant production capacities for industrial solvents.
Germany
Germany's chemical manufacturing sector utilizes ethyl acetate extensively as a process solvent and intermediate. Europe's REACH regulations and the EU Green Deal encourage the adoption of more sustainable chemical processes. The Rhine-Ruhr industrial region remains a key hub for chemical production and innovation.
India
Demand for pharmaceutical grade ethyl acetate is concentrating in India, driven by stringent quality requirements for drug synthesis. India's Central Drugs Standard Control Organization (CDSCO) mandates strict purity standards for pharmaceutical applications. Gujarat's pharmaceutical and chemical clusters are expanding their capacity to meet this specialized demand.
France
French food and beverage producers increasingly seek bio-based ethyl acetate for flavor extraction and decaffeination processes. EU food safety regulations and consumer demand for natural ingredients drive this preference. Brittany's food processing industry provides a growing market for green solvent alternatives.
Ethyl Acetate Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure where established players with significant capital resources dominate. This capital-intensive environment favors large-scale producers and those with integrated feedstock supply. Strategic archetypes include high-volume commodity producers, specialized high-purity suppliers, and vertically integrated petrochemical giants. Competitive moves involve securing long-term feedstock agreements and expanding production capacity to manage input cost volatility.
At the scale-driven end, Celanese Corporation exemplifies a major producer leveraging significant manufacturing scale to manage input cost volatility across its global operations. Eastman Chemical Company occupies a specialized position, focusing on high-purity grades tailored for stringent pharmaceutical applications, which command higher margins due to purity requirements. Meanwhile, INEOS Group represents a vertically integrated petrochemical giant, controlling key upstream assets to ensure stable feedstock supply and enhance competitive advantage in the broader chemical market. These companies collectively shape the competitive dynamics through their distinct operational models.
| Leading Market Players |
|---|
| Daicel Corporation |
| Solvay S.A. |
| Celanese Corporation |
| Sasol Ltd |
| BASF SE |
| Eastman Chemical Company |
| Jubilant Pharmova Ltd. |
| Sipchem |
| INEOS Group |
| Others |
Cost & Logistics Intelligence
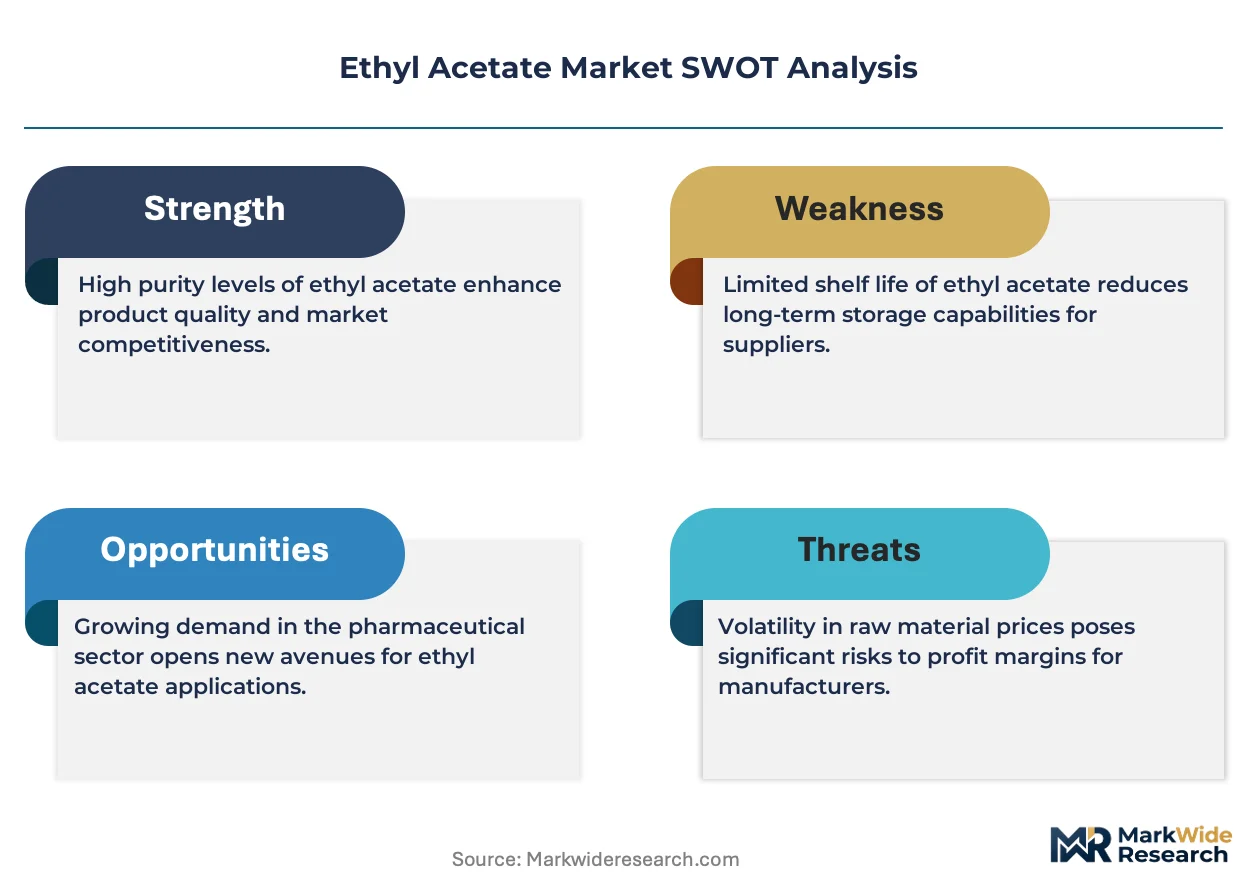
Petrochemical feedstock concentrations in key producing regions directly influence ethyl acetate pricing power, channeling margin pools towards high-purity grades and established producers. This dynamic underscores the importance of supply stability in a market facing bifurcated production pathways.
Pricing Analysis
Certification level, particularly for pharmaceutical and food grades, creates the primary spread across ethyl acetate pricing. The market predominantly utilizes a contract-based long-term offtake model for large industrial buyers, while smaller volumes trade on commodity spot markets. Price differentiation stems from purity requirements, volume scale, and geographic delivery costs. Pricing volatility arises from fluctuations in ethanol and acetic acid feedstock costs. Pharmaceutical and electronics grade buyers exhibit the lowest price sensitivity, prioritizing purity and compliance, whereas industrial grade users remain highly price-sensitive.
Supply Chain Analysis
Feedstock price volatility, particularly for ethanol and acetic acid, represents a significant structural risk across the ethyl acetate supply chain. Geographic supply concentration centers in China, the US Gulf Coast, and Germany, which host large-scale production facilities. The supply chain relies heavily on these raw material inputs, making it susceptible to agricultural commodity and petrochemical price cycles. Distribution runs through direct sales to major industrial consumers and a network of chemical distributors serving smaller, diverse clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ethyl acetate market presents a defensive moat story, underpinned by significant regulatory entrenchment and high switching costs for qualifying new solvents in established applications.
For Market Incumbents:Insulate against feedstock price volatility by securing long-term tolling agreements for ethanol and acetic acid. Invest strategically in bio-based production capabilities to meet evolving sustainability mandates, particularly within the EU Green Deal framework. Optimize existing petrochemical processes to maintain cost competitiveness against emerging alternatives. Celanese Corporation and INEOS Group can leverage their scale to mitigate input cost pressures and maintain market share against solvent substitution risks.
For New Entrants and Emerging Players:Southeast Asian industrial expansion represents a significant geographic underpenetration opportunity for ethyl acetate suppliers. Target high-purity electronics grade applications, where stringent quality requirements command higher margins and a specialized supply chain. Develop advanced bio-production pathways from non-food cellulosic biomass to offer a differentiated, sustainable product. A focused go-to-market angle on compliance with regional GB standards in China or specific EU mandates can secure early market access.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with mid-sized producers possessing established regional distribution networks or specialized high-purity manufacturing capabilities. The market offers long-term viability due to foundational demand from paints and coatings and expanding high-margin pharmaceutical segments. Target companies with proprietary bio-based production technologies or strong positions in emerging markets like India for pharmaceutical grades. A signal to watch is the successful commercial scale-up and cost reduction of non-food bio-ethyl acetate production.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Addresses growing manufacturing demand in Vietnam and Indonesia, reducing regional supply deficits. |
| Backward Integration into Bio-feedstocks | Mitigates feedstock price volatility and aligns production with sustainability mandates. |
| High-Purity Grade Certification Investment | Unlocks access to high-margin pharmaceutical and electronics applications in regulated markets. |
| Long-term Tolling Agreements | Ensures stable feedstock supply and hedges against price fluctuations for large producers. |
| R&D into Non-Food Biomass Conversion | Positions producers for future competitive advantage in green solvent markets. |
Research Approach
Operator-level perspectives from plant managers, procurement leads in paints and coatings, R&D directors in pharmaceutical manufacturing, and regulatory compliance officers anchored the qualitative base for this study. Primary interviews with these industry stakeholders were triangulated with extensive secondary research. Secondary data sources included chemical industry association reports, government environmental agency publications from the US EPA and Europe's ECHA, and company 10-K filings, ensuring a robust data foundation for bottom-up and top-down analysis.
The forecast framework applies scenario-bracketing to project market trajectories across the analysis window. Segmentation dimensions include grade tier, end-use industry, packaging format, and regional production hubs, alongside the critical bifurcation between bio-based and petrochemical routes. Compound annual growth rates were derived through regression analysis of historical trends and projected market drivers. Industry-specific forecast inputs included feedstock price projections and anticipated regulatory enforcement timelines for VOC limits and bio-based mandates.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or energy prices would shift the trajectory of the ethyl acetate market. Forecasts reflect assumptions documented through extensive primary and secondary research. Continuous validation against operating reality is the recommended discipline for market participants.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Tetraethyl Benzene Market
Solvents
Triacetin Market
Solvents
Ionic Liquids Market
Solvents
Solvent Cement Market
Solvents
Natural Distillates Market
Solvents
Global Tert-Butanol Market
Solvents
United States Acetonitrile Market
Solvents
Decanol Market
Solvents
Nitroglycerin Market
Solvents
N-Pentyl Chloride Market
Solvents
Nitromethane Market
Solvents
2-Phenylethanol Market
Solvents
Global Solvent Dyes Market
Solvents
Methyl Diethanolamine Market
Solvents
2 - Ethyl Anthraquinone Market
Solvents
Mono Propylene Glycol Market