
 Global Polyurethane Additives Market | 2026-2036
Global Polyurethane Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyurethane Additives Market Outlook
Buyer concentration among large construction material producers is recalibrating procurement leverage across the polyurethane additives value chain. Huntsman International LLC leverages its integrated isocyanate-additive platform to sustain supply security for insulation system manufacturers. BASF SE anchors European demand through specialized catalyst portfolios tailored to rigid foam applications. Wanhua Chemical Group dominates Asia-Pacific volume with backward integration into MDI and complementary additive production.
Polyurethane additives comprise chemical agents including catalysts, surfactants, stabilizers, and flame retardants that control reaction kinetics, cell structure, and final foam properties during polymerization. These additives determine dimensional stability, thermal resistance, and fire safety performance in end products ranging from refrigerator insulation to automotive seating. Catalyst formulations command concentrated margin pools due to their direct impact on production line throughput and foam quality consistency. Surfactants represent the fastest-growing product category as construction sector demand for spray-applied polyurethane foam intensifies. Flame retardant functionality faces structural transformation as halogen-free alternatives displace legacy chemistries under tightening building codes.
EPA emissions standards and REACH chemical registration requirements in Europe are forcing reformulation investments across the supplier base. China's MEE environmental compliance inspections and GB standards for indoor air quality are redirecting domestic production toward waterborne and low-emission additive systems. India's BIS certification mandates for construction materials are creating parallel compliance pathways for additive suppliers entering that market. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned R&D commitments.
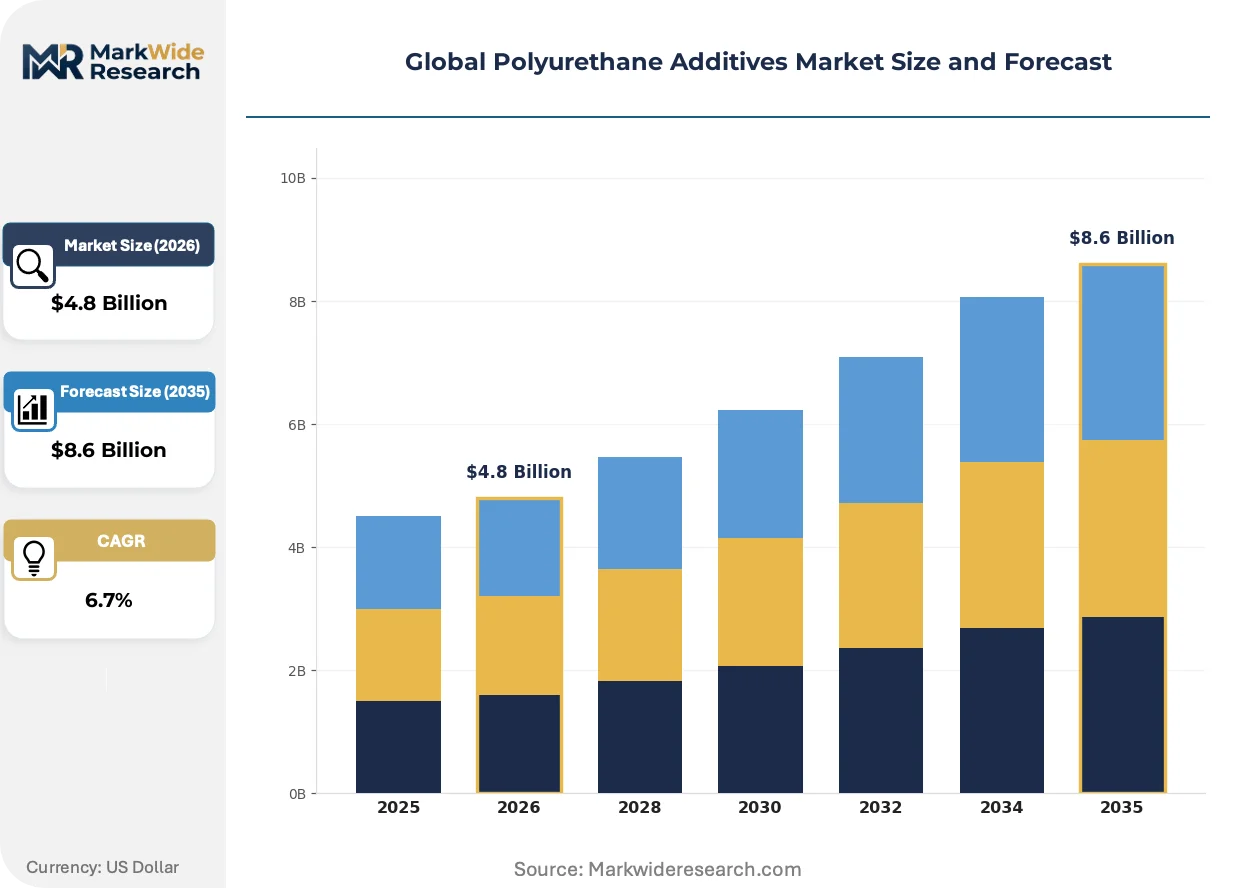
Market Dynamics
REACH compliance deadlines and EPA emissions guidelines are compressing formulation timelines while simultaneously fragmenting the supplier base into specialty and commodity tiers. This regulatory pressure is redrawing competitive boundaries around low-VOC catalyst portfolios and waterborne surfactant systems.
Growth Catalysts
- Building energy codes:Germany's EnEV standards and California's Title 24 mandate high-performance insulation in commercial structures. Rigid foam manufacturers are accelerating catalyst consumption to meet thermal resistance specifications.
- China's dual carbon goals:National emissions reduction targets are redirecting construction material producers toward spray-applied polyurethane systems with lower embodied carbon. Surfactant demand for closed-cell foam applications is intensifying.
- Automotive lightweighting:Seat foam producers are adopting reactive catalyst systems to reduce demold times. This process acceleration is expanding additive volumes per vehicle platform.
Market Restraints
- Tin catalyst cost volatility:Organotin compounds face raw material price swings tied to tin ore supply from Southeast Asian mining operations. Formulators struggle to pass through input cost spikes in contracted construction supply agreements.
- Supply concentration in MDI precursors:Three producers control the majority of European isocyanate supply. Additive specialists without captive MDI access face margin compression during upstream allocation periods.
- Technical limitation in bio-based polyols:Plant-derived feedstocks exhibit inconsistent hydroxyl values. Catalyst systems require recalibration for each bio-polyol batch, slowing production line throughput.
Strategic Opportunities
- India's BIS certification pathway:Mandatory quality standards for construction materials are creating a compliance-driven entry point for flame retardant additive suppliers. Early movers can anchor specification relationships with domestic insulation manufacturers.
- Recyclable foam design:Chemical recycling technologies for polyurethane waste streams are converging with additive innovations. Stabilizer systems enabling reversible polymer networks represent a white space for R&D investment.
- Direct-to-applicator distribution:Spray foam contractors are bypassing traditional distributor channels through manufacturer-direct procurement platforms. Additive suppliers can capture margin pools previously allocated to intermediaries.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in reaction kinetics modeling for multi-component polyurethane systems is concentrated among retiring technical staff. Training pipelines have not kept pace with formulation complexity demands.
- REACH registration timelines:New additive substances face multi-year dossier preparation and evaluation periods. SMEs lack the toxicology testing budgets to register novel chemistries, freezing innovation pipelines.
- Legacy equipment incompatibility:Low-emission waterborne additive systems require heated hose configurations and modified mixing heads. Contractors with capital-constrained operations delay system upgrades, slowing category transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyurethane Additives Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stabilizers, Catalysts, Shock Absorbers, Surfactants End Use Industry: Construction, Automotive, Furniture, Packaging Form: Aqueous, Liquid, Powder, Granular Functionality: Flame Retardants, Antimicrobial Agents, UV Stabilizers, Colorants |
| Companies Covered | Huntsman International LLC, Wanhua Chemical Group, BASF SE, Mitsui Chemicals, The Lubrizol Corporation, Covestro AG, Dow Inc., Air Products Inc., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyurethane Additives Market Strategic Shifts
Digital formulation tools and predictive reaction modeling are compressing development cycles while enabling real-time production adjustments. These capabilities are redistributing value from laboratory-scale expertise toward data-driven process control.
Machine learning algorithms for catalyst selection are converging with robotic high-throughput screening platforms. Automotive seating producers in Germany and Japan are deploying these systems to optimize demold times across variable humidity conditions. The technology is converging with additive manufacturing workflows to enable on-demand foam property customization.
EPA Significant New Alternatives Policy (SNAP) program rulings are disqualifying certain hydrofluorocarbon blowing agents from insulation applications. Formulators are pivoting toward hydrofluoroolefin and hydrocarbon alternatives, requiring surfactant reformulation to maintain cell structure integrity. North American spray foam contractors face equipment retrofit costs and certification requalification timelines.
Consolidated procurement by multi-site construction material producers is compressing supplier negotiation cycles. Large insulation manufacturers in the United States are centralizing additive purchasing through category management functions, displacing plant-level sourcing autonomy. This concentration is most visible in the Southeast where regional production hubs serve national distribution networks.
Global Polyurethane Additives Market Segmentation
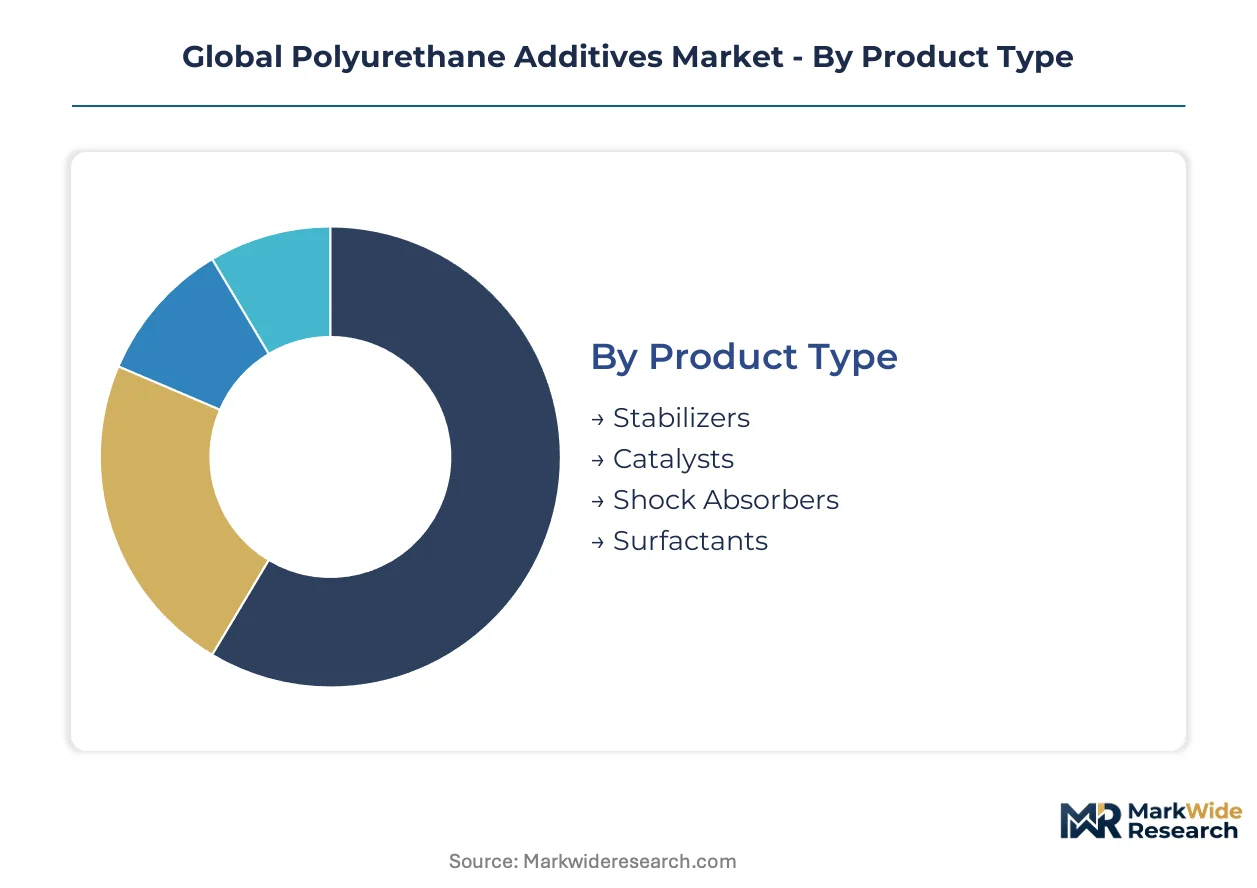
Segmentation reveals how capital deployment and technical specialization diverge across the polyurethane additives value chain. Catalyst and surfactant systems command disproportionate R&D investment due to their direct impact on foam quality and production economics. Formulation complexity varies sharply by end-use, with construction insulation requiring the most rigorous compliance documentation.
Product Type:
Capital intensity peaks in catalyst manufacturing, where reaction kinetics expertise and toxicology registration dossiers create steep barriers to entry. Surfactant production demands specialized alkoxylation capacity with significant upfront chemical processing investment.
- Catalysts:Organometallic and amine-based formulations govern reaction speed, cream time, and gelation profiles in polyurethane polymerization. Demand concentrates in Germany and Japan, where automotive seating producers seek reduced demold cycles to accelerate manufacturing throughput. REACH registration requirements for novel tin-free alternatives are extending development timelines.
- Surfactants:Silicone and non-silicone chemistries control cell structure uniformity and dimensional stability in finished foam. China's construction sector anchors volume growth, as spray-applied polyurethane insulation expands under national energy efficiency mandates. Waterborne surfactant systems require reformulation investment to meet MEE emissions inspections.
- Stabilizers:Antioxidant and hydrolysis-resistant additive packages extend service life in refrigerator insulation and automotive applications.
- Shock Absorbers:Viscoelastic modifiers tune energy dissipation properties for footwear and protective equipment formulations.
Most installed capacity flows through Catalysts. Expansion is steepest in Surfactants.
End Use Industry:
Application-driven segmentation shows construction commanding the longest specification cycles, while automotive rewards rapid formulation iteration. Margin structures diverge accordingly.
- Construction:Rigid foam insulation for commercial and residential building envelopes consumes catalyst and surfactant volumes at scale. California's Title 24 and Germany's EnEV standards mandate thermal resistance thresholds that accelerate additive consumption per square meter of installed insulation. Contractors face equipment retrofit costs when transitioning to low-emission waterborne systems.
- Automotive:Seat foam, headliner, and interior trim applications prioritize demold speed and VOC emissions compliance. Japanese and German OEMs deploy machine learning platforms to optimize catalyst selection across variable humidity production environments. Reactive catalyst systems are gaining share as lightweighting pressures intensify.
- Furniture:Flexible foam for mattresses and upholstered seating emphasizes comfort durability and fire safety certification.
- Packaging:Protective foam inserts and insulated shipping containers require cost-optimized additive loading with consistent performance.
Construction absorbs the highest additive volumes per unit of finished goods. Automotive shows the most rapid formulation turnover.
Form:
Physical state determines handling infrastructure, blending equipment requirements, and logistics economics across the supply chain.
- Liquid:Pumpable additive concentrates dominate high-volume rigid foam production, enabling precise metering and homogeneous dispersion. Most installed capacity flows through this segment.
- Aqueous:Water-based systems align with low-VOC regulatory trajectories in Europe and North America, though heated hose configurations raise contractor capital requirements.
- Powder:Dry-blended additives serve specialized applications where moisture sensitivity or extended shelf life priorities override liquid handling convenience.
- Granular:Solid delivery formats reduce shipping costs for remote construction sites with limited chemical storage infrastructure.
Liquid forms retain the broadest equipment compatibility. Aqueous formulations are climbing the fastest as environmental compliance tightens.
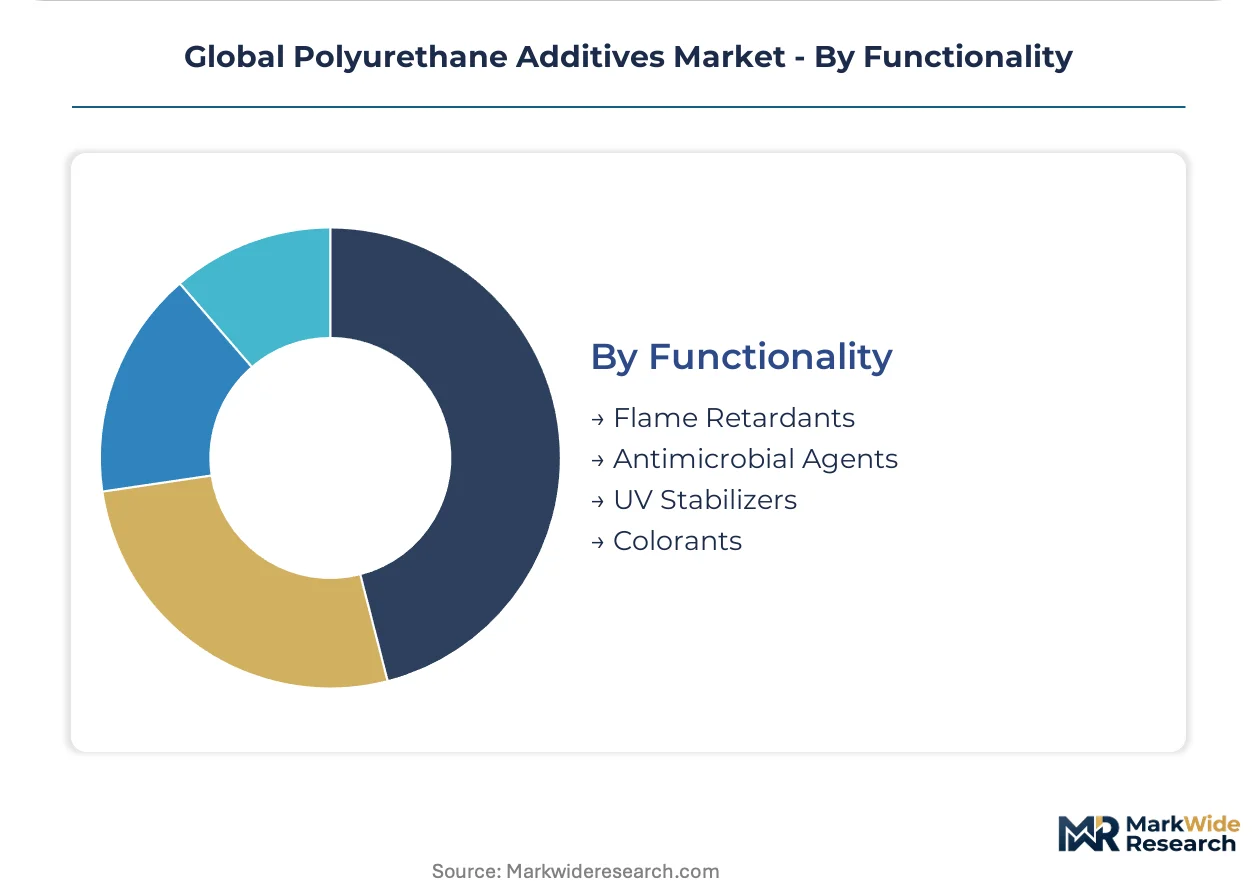
Functionality:
Performance specialization creates distinct competitive arenas with varying technical barriers and pricing power.
- Flame Retardants:Halogen-free phosphorus and nitrogen chemistries are displacing legacy brominated systems under tightening building codes. India's BIS certification for construction materials is creating compliance-driven entry points for suppliers meeting specification thresholds.
- UV Stabilizers:Hindered amine light stabilizers and UV absorbers protect outdoor furniture and automotive exterior components from photodegradation.
- Antimicrobial Agents:Silver-ion and organic biocide systems address hygiene requirements in healthcare furniture and food packaging applications.
- Colorants:Pigment dispersions and soluble dyes enable aesthetic differentiation with minimal impact on foam mechanical properties.
Flame Retardants command the most rigorous certification pathways. UV Stabilizers show the steepest expansion trajectory in outdoor applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists cluster in Germany's Ruhr industrial belt and Japan's Kansai chemical corridor, anchoring technical service capabilities for polyurethane additive producers serving automotive and construction sectors.
United States
Spray-applied polyurethane foam contractors in California and Texas drive surfactant consumption as Title 24 energy codes tighten thermal envelope requirements. EPA SNAP program rulings on hydrofluorocarbon blowing agents force equipment retrofits and certification requalification across the Southeast. Houston-Gulf Coast petrochemical complexes concentrate catalyst blending operations for rigid foam insulation serving national distribution networks.
Germany
Automotive seating manufacturers in Bavaria and Baden-Württemberg deploy reactive catalyst systems to compress demold cycles for lightweight interior components. EnEV building energy standards mandate high-performance insulation in commercial structures, accelerating catalyst and surfactant volumes. Leverkusen and Ludwigshafen chemical clusters anchor European REACH registration expertise for tin-free catalyst alternatives.
China
National dual carbon targets redirect construction material producers toward spray-applied polyurethane systems with lower embodied carbon profiles. MEE environmental compliance inspections and GB standards for indoor air quality redirect production toward waterborne additive systems. Ningbo and Shanghai chemical parks concentrate backward-integrated MDI and complementary additive production under Wanhua Chemical Group's regional supply chain dominance.
India
Mandatory BIS certification for construction materials creates compliance-driven entry points for flame retardant additive suppliers targeting domestic insulation manufacturers. Refrigerator and automotive component producers in Maharashtra and Gujarat absorb stabilizer and catalyst volumes for rigid foam applications. Mumbai-Pune industrial corridor concentrates formulation technical service capabilities for emerging spray foam contractors.
Japan
Automotive OEMs in Toyota City and Nagoya deploy machine learning platforms to optimize catalyst selection across variable humidity production environments. METI industrial standards emphasize VOC emissions compliance in interior trim applications. Osaka-Kobe chemical manufacturing belt maintains specialized alkoxylation capacity for silicone surfactant production serving electronics and packaging foam segments.
Global Polyurethane Additives Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across a tiered supplier structure shaped by captive isocyanate access and formulation service depth. Three producers control the majority of European MDI supply, compressing margin pools for additive specialists without upstream integration during allocation periods. Strategic archetypes include integrated chemical majors with captive MDI platforms, independent additive specialists with toxicology registration expertise, and regional compounders with direct-to-applicator distribution networks. Competitive moves concentrate on low-VOC catalyst portfolio expansion and waterborne surfactant system development.
Among integrated chemical majors, Huntsman International LLC and Covestro AG occupy positions defined by captive isocyanate-additive coordination. BASF SE anchors European demand through specialized catalyst portfolios. Wanhua Chemical Group exemplifies regional supply chain dominance through backward integration into MDI production and complementary additive manufacturing.
| Leading Market Players |
|---|
| Huntsman International LLC |
| Wanhua Chemical Group |
| BASF SE |
| Mitsui Chemicals |
| The Lubrizol Corporation |
| Covestro AG |
| Dow Inc. |
| Air Products Inc. |
| Evonik Industries AG |
| Others |
Value Chain & Pricing Dynamics
Backward integration into MDI production anchors both supply security and pricing power for polyurethane additive producers serving insulation system manufacturers. Wanhua Chemical Group's captive isocyanate platform in Ningbo and Shanghai chemical parks compresses input cost volatility while enabling volume-based price positioning against non-integrated specialists. This structural configuration concentrates margin pools among chemical majors during upstream allocation periods.
Pricing Analysis
Capacity additions in China's chemical parks are reshaping price floors for surfactant systems serving construction spray foam applications. Three-tier pricing structure across premium REACH-registered, standard performance, and economy commodity tiers separates tin-free catalyst portfolios from legacy formulations. Cost compression in the economy tier intensifies because Southeast Asian tin ore supply volatility feeds through to organotin compound pricing. Large construction material producers with consolidated procurement functions exhibit lowest price sensitivity, while capital-constrained spray foam contractors show highest elasticity to equipment retrofit requirements.
Supply Chain Analysis
Reverse-logistics flows for polyurethane waste streams remain underdeveloped, though chemical recycling technology maturation is converging with stabilizer innovations enabling reversible polymer networks. Supply concentration centers on China, Germany, and the United States for catalyst blending and surfactant alkoxylation capacity. Raw material dependencies draw from Southeast Asian tin mining operations, Middle Eastern petrochemical feedstocks, and European specialty chemical intermediates. Single-source vulnerability in MDI precursors creates allocation risk during upstream supply disruptions. Distribution runs through direct-to-applicator platforms that bypass traditional distributor channels for spray foam contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyurethane additives market reads as a late-cycle quality story. Construction sector demand is concentrating toward low-VOC, waterborne systems with premium compliance documentation under tightening energy codes.
For Market Incumbents: Lock in specification relationships with multi-site insulation manufacturers through REACH-registered tin-free catalyst portfolios before compliance deadlines compress supplier options. Defend margin pools by anchoring technical service capabilities in Germany's Ruhr industrial belt and Japan's Kansai chemical corridor where formulation chemist scarcity concentrates expertise. Prioritize backward integration into surfactant alkoxylation capacity to reduce exposure to Southeast Asian raw material volatility. For New Entrants and Emerging Players: The price-point gap between premium REACH-compliant and economy commodity catalyst tiers creates entry space for mid-range formulations targeting India's BIS certification pathway. India's mandatory construction material standards represent the most penetrable geography for flame retardant additive suppliers lacking legacy toxicology registration dossiers. Pursue direct-to-applicator distribution partnerships with emerging spray foam contractors in Maharashtra and Gujarat to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional compounders with direct-to-applicator networks because spray foam contractors are consolidating procurement through manufacturer-direct platforms. Long-term viability over a multi-year horizon favors targets with waterborne surfactant expertise aligned with MEE emissions inspection trajectories. Watch for REACH registration completion timelines as inflection indicators for competitive positioning shifts among tin-free catalyst alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Production | Wanhua Chemical Group's captive supply anchors regional pricing power against non-integrated competitors. |
| REACH Registration Investment | BASF SE's toxicology dossiers for tin-free catalysts secure specification relationships with European insulation manufacturers. |
| Waterborne Surfactant System Development | Low-VOC formulations align with California Title 24 and Germany EnEV energy code compliance trajectories. |
| Direct-to-Applicator Distribution Platform | Manufacturer-direct procurement captures margin pools previously allocated to traditional distributor intermediaries. |
| Chemical Recycling Technology Partnership | Stabilizer innovations enabling reversible polymer networks address emerging polyurethane waste stream valorization requirements. |
Study Parameters
Bottom-up construction and automotive modeling reconciled against top-down catalyst and surfactant production tracking forms the analytical core of this study. Primary interviews with plant managers at rigid foam insulation facilities, procurement leads at automotive seating OEMs, distribution channel partners serving spray foam contractors, and technical R&D directors at additive producers combined with secondary validation. Secondary sources include customs and trade data from chemical import registries, American Chemistry Council and Cefic industry reports, and SEC 10-K filings from diversified chemical majors. Triangulation across these sources ensures consistency between demand-side consumption patterns and supply-side capacity utilization.
Input-output matrices segment volume and value outputs across catalyst, surfactant, stabilizer, and flame retardant product categories by construction, automotive, furniture, and packaging end-use industries. The analytical framework projects expansion across the analysis window using CAGRs derived from regression analysis against building energy code adoption rates, automotive production forecasts, and regulatory compliance timeline modeling. Segmentation dimensions include formulation complexity tier, physical delivery state, functional performance requirement, and regional production hub clustering.
Caveats apply where REACH registration timeline delays, tin ore supply disruptions from Southeast Asian mining operations, or contractor equipment retrofit capital constraints could materially shift the outlook. Forecasts reflect assumptions regarding regulatory enforcement consistency and energy code adoption trajectories. Practitioners should monitor MEE inspection intensity in China, EPA SNAP program ruling implementation pace, and BIS certification completion rates in India for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global PVC Stabilizer Market
Additives
North America Potassium Nitrate Market
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Polysorbate-80 Market
Additives
Chemical Silage Additives Market
Additives
Plastic Fillers Market
Additives
Europe Citric Acid Market
Additives
Anti Crystallizing Agents Market
Additives
United Kingdom Feed Additives Market
Additives
Global Lubricating Oil Additives Market
Additives
Iso-Butyric Acid Market
Additives
Polysaccharides and Oligosaccharides Market
Additives
Global Ester Gum Market
Additives
Citrate Ester Market
Additives
Flux Injection System Market
Additives
Asia-Pacific Water Enhancer Market