
 Crosslinking Agents Market | 2026-2036
Crosslinking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Crosslinking Agents Market Analysis
German specialty chemical producers is restructuring crosslinking agent supply chains toward bio-based feedstocks and closed-loop manufacturing. BASF SE leverages its Ludwigshafen integrated site to sustain captive epichlorohydrin supply for epoxy curing agents. Covestro AG anchors its European polyisocyanate franchise through backward integration into aniline and MDI precursors. Huntsman Corporation competes on thermosetting polyurethane systems for automotive composites, while Evonik Industries differentiates via silane crosslinkers for high-voltage cable insulation.
Crosslinking agents are reactive compounds that form covalent bridges between polymer chains, typically requiring functional group densities above 2.0 eq/kg and cure temperatures between 80°C and 180°C depending on the chemistry, to transform thermoplastic or prepolymer materials into insoluble, dimensionally stable networks for structural and protective applications. Epoxy crosslinkers dominate margin pools in aerospace and electronics verticals where outgassing specifications and thermal cycling resistance command formulation premiums. Polyurethane systems represent the fastest-expanding product category, driven by automotive adhesive and sealant specifications for multi-material bonding. Silane chemistry occupies a specialized tier in construction sealants and photovoltaic encapsulants where moisture-cure mechanisms enable ambient-temperature processing.
REACH registration requirements under ECHA govern substance volumes above one tonne annually in Europe, while EPA TSCA Section 5 premanufacture notifications constrain novel crosslinker introductions in the United States. China's GB standards for indoor air quality and VOC emissions in coatings, enforced by MEE, are redirecting construction-sector procurement toward waterborne and powder delivery modes. Stakeholders must monitor regulatory divergence between EU Green Deal chemical sustainability targets and state-level California Air Resources Board rules to anticipate reformulation mandates that will reshape competitive qualification requirements.
Market Dynamics
Automotive lightweighting mandates in Germany and Japan are compressing cure cycles and elevating thermal performance specifications for epoxy and polyurethane crosslinking systems. This structural demand pull is forcing reformulation investments across coating, adhesive, and composite tiers.
Growth Catalysts
- REACH compliance deadlines:ECHA registration thresholds are accelerating substitution of high-VOC amino resins with waterborne polyisocyanate systems in European industrial coatings.
- China's eastern coastal manufacturing belt:Concentrated automotive OEM and electronics assembler demand is pulling capacity expansion for aliphatic isocyanate curing agents.
- Photovoltaic encapsulant specifications:Moisture-cure silane chemistry is displacing thermal cure systems in solar module manufacturing to reduce energy inputs.
Market Restraints
- Epichlorohydrin supply concentration:Captive production at Ludwigshafen and Caojing sites limits merchant market liquidity for epoxy curing agent feedstocks.
- MDI precursor volatility:Aniline and nitrobenzene cost swings compress margin stability for European polyisocyanate formulators.
- EPA TSCA Section 5:Premanufacture notification timelines extend 18-24 months for novel crosslinker introductions, constraining innovation velocity in the United States.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic manufacturing incentives are opening import-substitution pathways for coating-grade crosslinkers serving automotive refinish.
- EU Green Deal chemical sustainability targets:Bio-based epichlorohydrin mandates are creating qualification premiums for renewable-content curing agents.
- Silane-polyurethane hybrid systems:Convergence of ambient-cure mechanisms with structural adhesion is enabling new construction sealant applications.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in rheology control and cure kinetics is concentrating at integrated producers, constraining independent compounder expansion.
- Multi-certification burden:Simultaneous aerospace outgassing, automotive OEM, and electronics IPC qualification timelines extend 24-36 months for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crosslinking Agents Market |
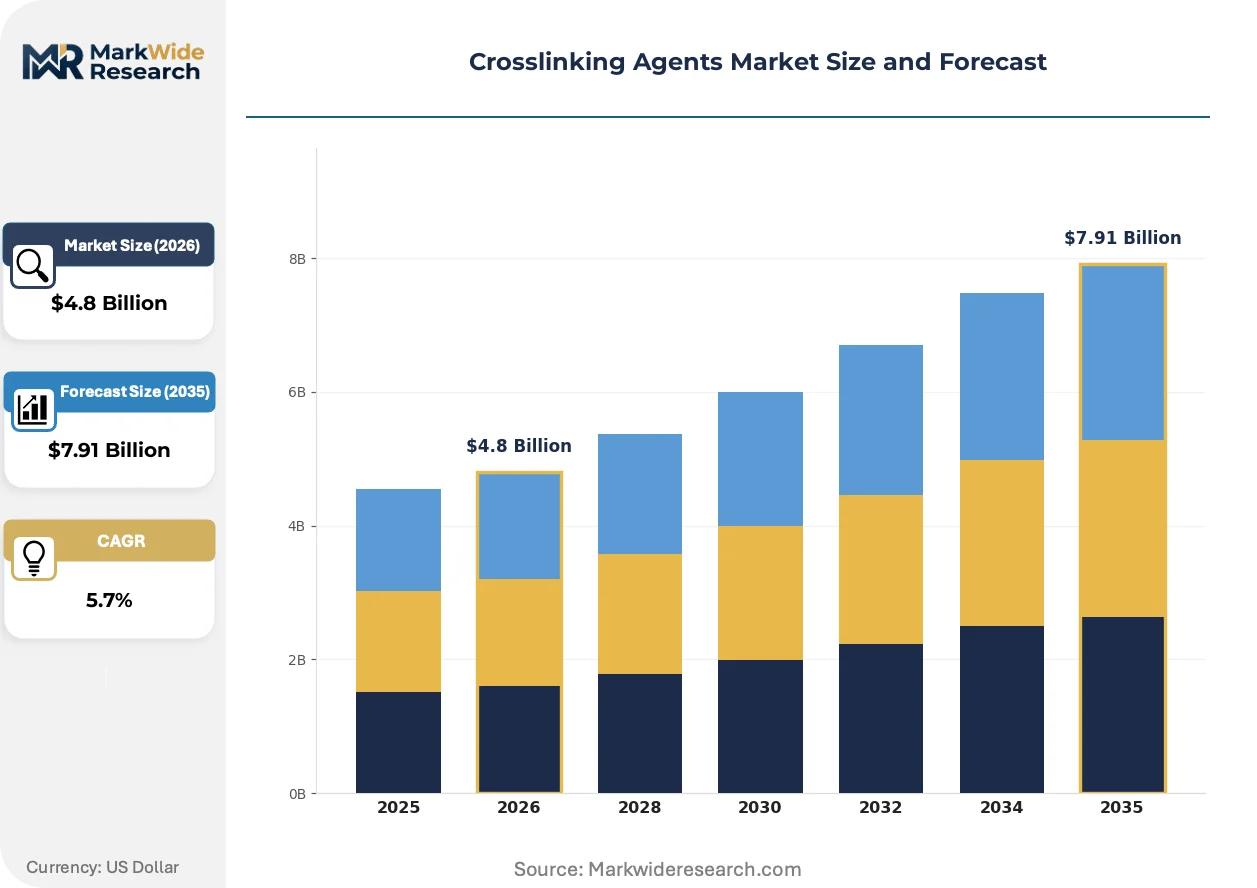
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylates, Epoxy, Polyurethanes, Silanes Application: Adhesives, Coatings, Sealants, Textiles Industry Vertical: Construction, Automotive, Electronics, Aerospace Delivery Mode: Liquid, Powder, Paste, Granules |
| Companies Covered | BASF SE, Covestro AG, Huntsman Corporation, Evonik Industries, Dow Inc., Allnex Group, Wanhua Chemical Group Co., Ltd., Aditya Birla Corporation, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crosslinking Agents Market Emerging Trajectories
Digital formulation platforms and closed-loop manufacturing architectures are compressing development cycles while regulatory pressure on VOC emissions forces chemistry migration toward waterborne and powder delivery systems.
Continuous flow reactor technology for polyisocyanate synthesis is automating temperature and stoichiometry control to reduce batch-to-batch variation. European automotive adhesive formulators are adopting these systems at pilot scale. This automation is compressing qualification timelines for multi-material bonding applications.
REACH authorization requirements under ECHA are restricting Substances of Very High Concern in crosslinking agent supply chains. Industrial coating manufacturers in Germany and France are accelerating substitution programs for formaldehyde-releasing amino resins. Affected suppliers are redirecting R&D toward blocked isocyanate and polycarbodiimide alternatives.
Specification consolidation among tier-one automotive OEMs is compressing approved supplier lists for structural adhesive curing agents. European and Japanese assemblers are consolidating procurement around qualified polyisocyanate systems with documented carbon footprints. This concentration is most visible in battery pack bonding applications where thermal runaway resistance is mandatory.
Crosslinking Agents Market Segmentation
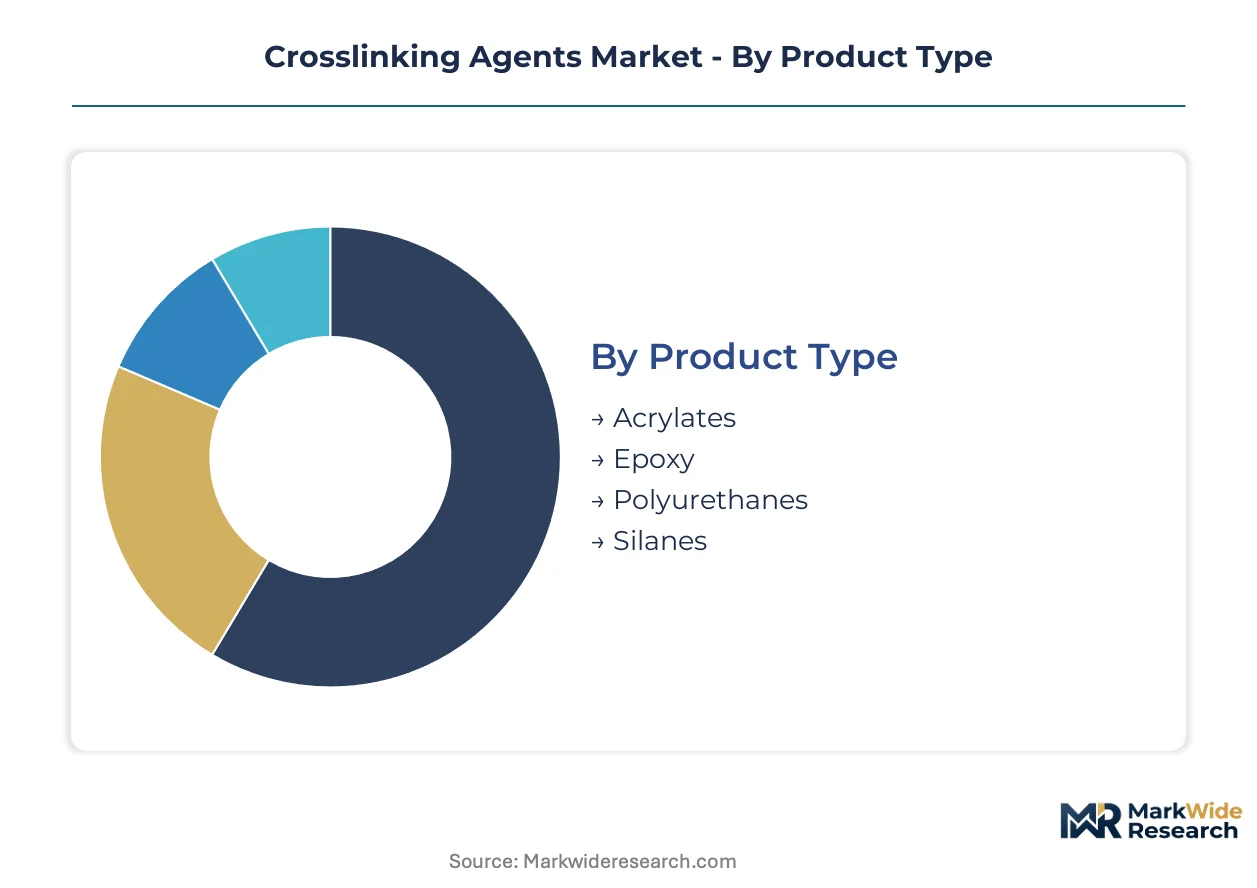
Crosslinking agent procurement varies sharply by performance tier, cure mechanism, and regulatory exposure. Buyers segment suppliers by thermal resistance specifications, VOC compliance grade, and qualification depth for structural versus decorative applications.
Product Type:
Cost tier separates commodity buyers from specification-driven formulators seeking thermal cycling resistance or ambient-cure capability.
- Epoxy:Aromatic and aliphatic amine curing agents dominate aerospace composite and electronics potting applications where outgassing specifications under ESA and IPC standards command formulation premiums. German automotive OEMs specify these systems for battery pack structural adhesives requiring thermal runaway resistance.
- Polyurethanes: Aliphatic and aromatic isocyanate crosslinkers enable rapid cure cycles for multi-material bonding in automotive lightweighting programs. Japanese OEM procurement concentrates on low-viscosity systems for robotic dispensing in body-in-white assembly.
- Acrylates: UV-cure oligomers serve graphic arts and wood coating sectors where line speed economics override thermal resistance requirements.
- Silanes: Moisture-cure alkoxy silanes displace thermal systems in photovoltaic encapsulant manufacturing to reduce energy inputs.
Volume sits with epoxy systems; growth tilts toward polyurethane chemistry.
Application:
Application determines cure kinetics, film thickness tolerance, and certification burden for formulators.
- Coatings:Industrial protective and automotive refinish formulations drive amino resin and blocked isocyanate consumption. REACH authorization deadlines are forcing substitution of formaldehyde-releasing chemistries in German and French manufacturing.
- Adhesives: Structural bonding applications command the highest crosslinker specification grades. Automotive OEM qualification timelines extend 24-36 months for battery pack and carbon fiber composite assembly systems.
- Sealants: Construction and transportation applications favor silane-terminated polyether and polyurethane hybrid systems enabling ambient-temperature cure.
- Textiles: Durable press and crease-resistant finishes consume glyoxal and dimethylol dihydroxyethylene urea crosslinkers under tightening MEE VOC enforcement in China.
Coatings generate the largest volume call; adhesives are climbing the fastest on automotive electrification.
Industry Vertical:
Customer type dictates margin structure through qualification depth and specification stability.
- Automotive:Tier-one adhesive formulators face consolidated approved supplier lists and carbon footprint documentation requirements from European and Japanese assemblers.
- Electronics: PCB potting and encapsulant specifications demand ultra-low ionic content and thermal cycling resistance for 5G infrastructure and electric vehicle inverters.
- Construction: Waterborne and powder delivery modes are displacing solventborne systems under China's GB standards for indoor air quality.
- Aerospace: Outgassing specifications per ASTM E595 constrain supplier pools to qualified specialty chemical producers with captive epichlorohydrin supply.
Automotive commands the steepest expansion trajectory; aerospace maintains the highest margin tier.
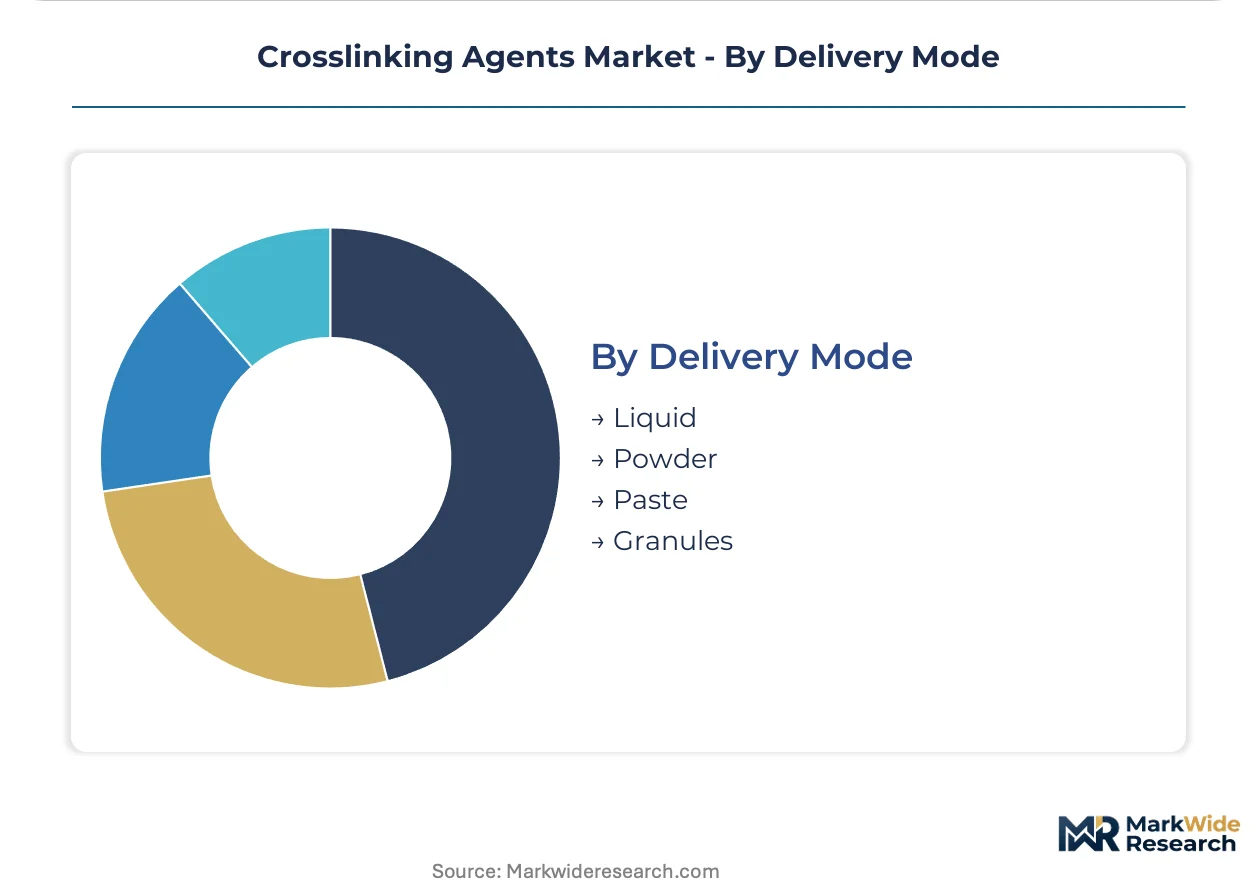
Delivery Mode:
Supply concentration and logistics economics vary by physical form and shelf stability requirements.
- Liquid:Two-component polyurethane and epoxy systems dominate high-volume automotive and industrial coating applications where pot life control is critical.
- Powder: Epoxy and polyester powder coatings are expanding under EPA VOC regulations and EU Green Deal chemical sustainability targets.
- Paste: Thixotropic formulations serve gap-filling adhesive and sealant applications in marine and transportation assembly.
- Granules: Solid amino resins and blocked isocyanates enable precise metering in continuous coating line operations.
Liquid systems anchor current volume; powder formats are gaining share fastest on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Epichlorohydrin production clusters in Ludwigshafen and Caojing anchor crosslinking agent supply chains across three continents. Regional demand patterns diverge sharply between automotive electrification programs, electronics assembly migration, and construction chemical reformulation mandates.
United States
Automotive OEMs in Michigan and Ohio specify thermosetting polyurethane systems for battery pack bonding applications. EPA TSCA Section 5 premanufacture notifications extend 18-24 months for novel crosslinker introductions, constraining innovation velocity. The Gulf Coast petrochemical corridor supplies aniline and MDI precursors to Huntsman Corporation's downstream formulation operations.
Germany
REACH authorization deadlines under ECHA are accelerating substitution of formaldehyde-releasing amino resins with waterborne polyisocyanate alternatives. The country's specialty chemical producers are restructuring supply chains toward bio-based feedstocks and closed-loop manufacturing. BASF SE leverages its Ludwigshafen integrated site to sustain captive epichlorohydrin supply for epoxy curing agents.
China
GB standards for indoor air quality and VOC emissions in coatings, enforced by MEE, redirect construction-sector procurement toward waterborne and powder delivery modes. Demand concentrates in eastern coastal manufacturing provinces where Wanhua Chemical and Allnex have expanded polyisocyanate and amino resin capacity. Automotive OEMs in Shanghai and Jiangsu province drive aliphatic isocyanate consumption for multi-material bonding.
Japan
Lightweighting mandates from METI compress cure cycles and elevate thermal performance specifications for epoxy and polyurethane crosslinking systems. Japanese OEM procurement concentrates on low-viscosity systems for robotic dispensing in body-in-white assembly. The Nagoya-Toyota industrial corridor anchors domestic formulation expertise for carbon fiber composite applications.
India
The PLI scheme for specialty chemicals opens import-substitution pathways for coating-grade crosslinkers serving automotive refinish markets. Domestic manufacturing incentives are pulling capacity investment away from pure merchant import models. Maharashtra and Gujarat industrial zones concentrate formulation demand from tier-one automotive suppliers.
Crosslinking Agents Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based qualification premiums and regional import substitution. The market structures around three archetypes: integrated petrochemical majors with captive feedstock supply, mid-scale regional formulators serving qualified supplier lists, and specialty silane producers targeting electronics and construction verticals. Dominant competitive moves include backward integration into aniline and epichlorohydrin precursors, plus strategic partnerships with automotive OEMs for battery pack bonding qualification.
Within the integrated major tier, BASF SE and Covestro AG exemplify European producers leveraging captive precursor supply to defend margin stability. Wanhua Chemical Group Co., Ltd. anchors Chinese domestic capacity expansion for aliphatic isocyanate curing agents. Among specialty producers, Evonik Industries occupies a position exemplifying silane crosslinker differentiation for high-voltage cable insulation and photovoltaic encapsulant applications.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Huntsman Corporation |
| Evonik Industries |
| Dow Inc. |
| Allnex Group |
| Wanhua Chemical Group Co., Ltd. |
| Aditya Birla Corporation |
| DuPont |
| Others |
Supply Flow & Price Mechanics
Epichlorohydrin spot price volatility cascades through epoxy curing agent tiers, compressing margins at merchant compounders while integrated producers at Ludwigshafen and Caojing defend pricing power through captive supply. This feedstock concentration stratifies procurement costs between specification-grade aerospace formulators and commodity coating buyers.
Pricing Analysis
Technical service bundling separates premium-tier suppliers from unbundled commodity sellers in crosslinking agent procurement. Three-tier pricing structure across aerospace-qualified, automotive-specified, and industrial-grade levels reflects certification depth and thermal resistance guarantees. Price differentiation hinges on REACH registration status and carbon footprint documentation, with European buyers commanding renewable-content premiums. Cost compression in standard-grade epoxy amines intensifies as Chinese capacity expansion floods merchant markets. Automotive OEM adhesive formulators show lowest price sensitivity due to 24-36 month qualification lock-in, while construction coating distributors remain highly sensitive to spot fluctuations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive adhesive demand, while distributor networks serve fragmented construction and refinish segments. Supply concentrates in Germany, China, and the United States, with Ludwigshafen and Caojing anchoring epichlorohydrin availability. Raw material flows draw from aniline, nitrobenzene, and bio-based glycerol feedstocks, with MDI precursor volatility transmitting through polyisocyanate pricing. Single-source vulnerability at specialized silane producers creates qualification bottlenecks for photovoltaic encapsulant manufacturers. Distribution runs through regional chemical distributors with formulation technical support, plus direct mill relationships for top-ten automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
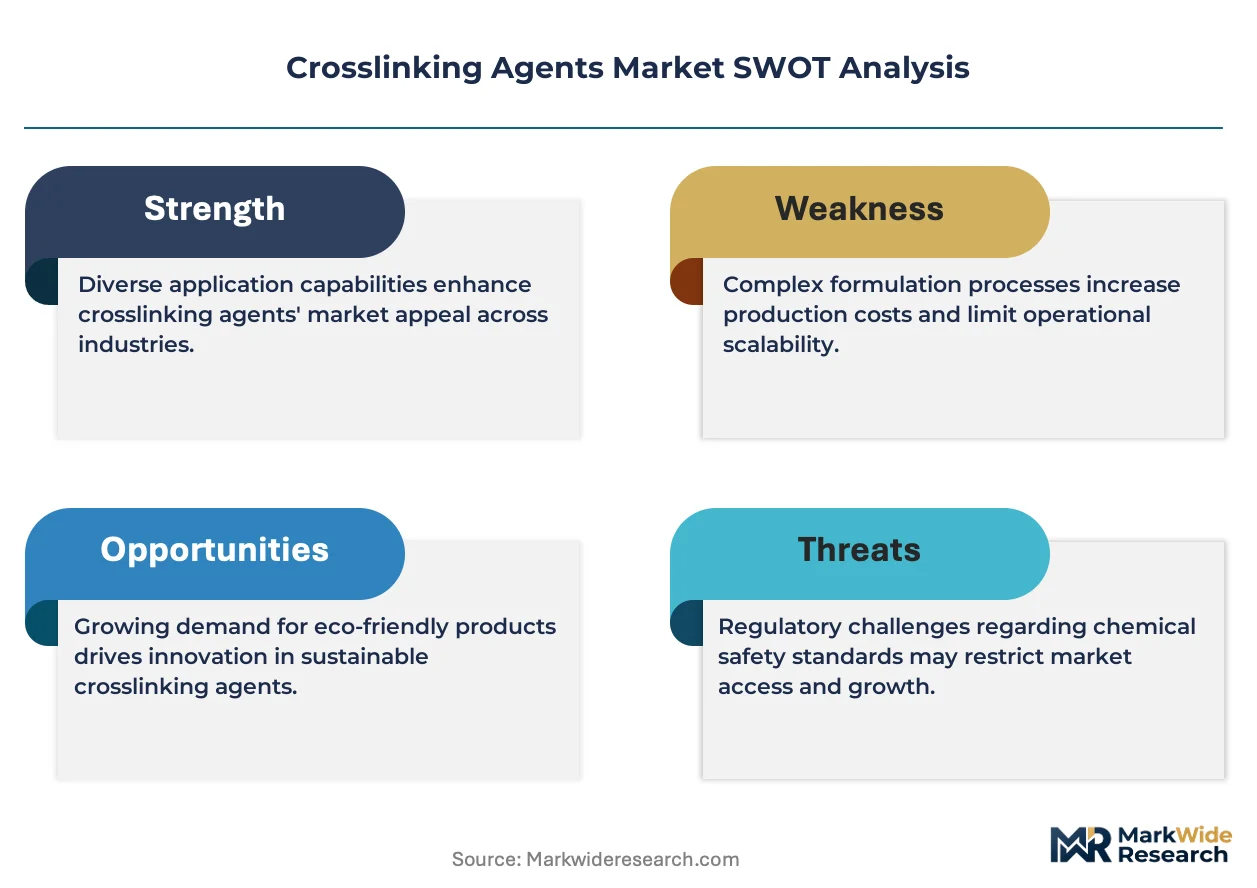
Crosslinking agent competition has become a vertical-integration race, with captive epichlorohydrin and aniline supply separating margin-stable leaders from feedstock-exposed compounders.
For Market Incumbents: Anticipate bio-based feedstock mandates under EU Green Deal chemical sustainability targets by securing renewable epichlorohydrin offtake agreements or fermentation technology partnerships. Defend position by deepening backward integration into aniline precursors to insulate against nitrobenzene cost swings. Prioritize carbon footprint certification investments to maintain approved supplier status with consolidating European and Japanese automotive OEMs. For New Entrants and Emerging Players: REACH authorization deadlines in Europe open a window for formaldehyde-free amino resin substitutes, particularly blocked isocyanate and polycarbodiimide alternatives. Target India's PLI scheme for specialty chemicals to establish import-substitution capacity serving Maharashtra and Gujarat automotive refinish markets. Lead with waterborne polyisocyanate systems that bypass legacy solventborne qualification barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale regional formulators with existing automotive OEM qualifications in Germany or Japan, where consolidation pressure is compressing supplier lists. Long-term viability centers on feedstock security and multi-certification depth rather than volume scale alone. Monitor ECHA Substances of Very High Concern authorization timelines as inflection indicators for substitution-driven M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline Precursors | Covestro AG's captive MDI supply insulates European polyisocyanate margins from nitrobenzene volatility. |
| Bio-Based Epichlorohydrin Capacity Expansion | EU Green Deal mandates create qualification premiums for renewable-content epoxy curing agents. |
| Continuous Flow Reactor Technology Adoption | Automated polyisocyanate synthesis reduces batch variation for robotic automotive adhesive dispensing. |
| Multi-Certification Investment Program | Simultaneous aerospace outgassing and automotive OEM qualification extends competitive moats. |
| Regional Import-Substitution Manufacturing | India's PLI incentives redirect coating-grade crosslinker capacity away from pure merchant import models. |
Methodological Framework
Document review covered customs trade data, SEC 10-K filings, and ECHA registration databases, complemented by interviews with plant managers at integrated chemical sites, procurement leads at Tier 1 automotive adhesive formulators, and technical R&D directors at specialty silane producers. Bottom-up volume estimates triangulated against top-down industry association data from ACC and Cefic. Primary fieldwork validated secondary assumptions on cure kinetics specifications and qualification timeline benchmarks.
Segment-level outputs across the projection horizon reflect modeled interactions between chemistry type, cure mechanism, and end-use vertical. The analytical framework incorporated epoxy, polyurethane, acrylate, and silane product tiers against coatings, adhesives, sealants, and textile applications. CAGRs derived from regression analysis of historical capacity utilization, feedstock cost pass-through elasticities, and regulatory substitution elasticities. Forecast inputs included automotive lightweighting program commitments, photovoltaic installation trajectories, and REACH authorization sunset dates.
The model assumes a particular technology adoption path; alternative pathways for moisture-cure silane systems in solar module manufacturing would alter the outlook if thermal cure innovations reduce energy inputs comparably. Forecasts reflect assumptions on feedstock price stability, regulatory enforcement consistency, and OEM qualification consolidation rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Polyethylene Terephthalate Additives Market
Additives
United States Citric Acid Market
Additives
Asia-Pacific Feed Acidifiers Market
Additives
Americas Coating Additives Market
Additives
Sorbitan Oleate Market
Additives
Global Zinc Stearate Market
Additives
Volatile Corrosion Inhibitors Market
Additives
Caprylyl Glycol Market
Additives
South America Concrete Admixtures Market
Additives
Metal Deactivators Market
Additives
Liquid Thickeners Market
Additives
Thallium Acetate Market
Additives
Competitive Inhibitors Market
Additives
Organic Dispersants Market
Additives
Global Caprylhydroxamic Acid Market
Additives
Tricalcium Citrate Market