
 Food Colors Market | 2026-2036
Food Colors Market Size, Share, and Industry Trends Forecast 2026-2036
Food Colors Market Intelligence
The displacement of synthetic azo dyes like Tartrazine by natural colorants from spirulina, beetroot, and paprika is hardening the cost structure for food manufacturers. Oterra A/S specializes in these natural solutions, focusing on extraction technologies. GNT Group leverages its vertically integrated supply chain for fruit and vegetable concentrates to ensure quality. ADM competes with a broad portfolio including both natural and synthetic options.
Food colors are additives used to offset color loss, correct natural variations, or create appealing visual cues in food and beverage products. These substances are classified as either water-soluble dyes or insoluble pigments and lakes, which are precipitated onto an inert substrate like alumina hydrate. Natural colors represent the fastest-growing product type segment, driven by clean-label demands. Within applications, the beverages category commands a significant share, while confectionery applications require high-stability colors resistant to heat and pH changes.
Regulatory frameworks from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) dictate approved substances and usage levels. In India, the FSSAI sets similar standards, with all three bodies influencing trade and formulation strategies through their pre-market approval processes. Formulators must now navigate the technical challenge of achieving vibrant, stable hues with natural ingredients while managing price volatility in raw material supply chains.
Market Dynamics
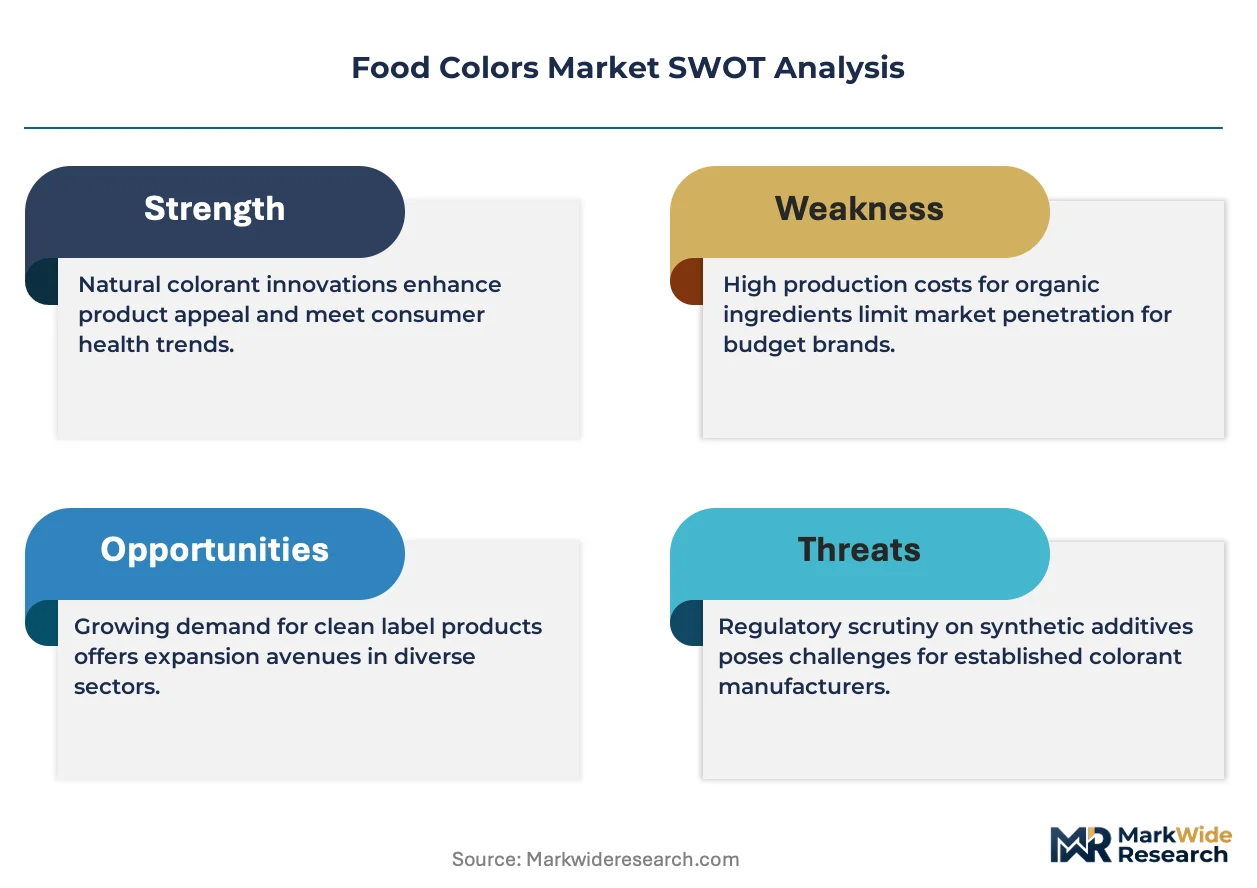
The fundamental tension between consumer demand for clean-label ingredients and the technical, cost, and stability limitations of natural colorants is the central force shaping the food colors market. This dynamic compels manufacturers to innovate in extraction and formulation while navigating volatile agricultural supply chains and divergent international regulations.
Growth Catalysts
- Stricter Regulatory Mandates:The European Food Safety Authority (EFSA) is tightening rules on synthetic additives, which accelerates the transition to natural alternatives in the European Union's food and beverage sector.
- Plant-Based Food Expansion:The rapid growth of the plant-based dairy alternatives segment creates new demand for colors that can mimic the appearance of traditional dairy products using clean-label ingredients.
- Source Material Innovation:Advances in cultivating and processing sources like spirulina provide vibrant blue and green hues previously difficult to achieve with natural ingredients, opening new formulation possibilities.
Market Restraints
- Input Cost Volatility:Raw materials for natural colors, such as turmeric and paprika, are subject to agricultural price swings and climate-related supply disruptions, creating unpredictable cost structures for manufacturers.
- Technical Stability Limits:Many natural colorants exhibit poor stability when exposed to heat, light, or pH changes, limiting their application in products like confectionery and baked goods that require long shelf life.
- Substitution by Flavoring Foods:The use of coloring foodstuffs, such as fruit and vegetable concentrates, acts as a substitute for purified color additives, particularly in markets with a strong clean-label preference like Germany.
Strategic Opportunities
- High-Stability Encapsulation:Developing microencapsulation technologies to protect sensitive natural pigments from degradation offers a significant opportunity to penetrate high-heat application segments like baking and confectionery.
- Clean-Label Pet Food:The humanization of pet food creates an underpenetrated market for natural and simple-ingredient colorants, as consumers increasingly seek clean labels for their pets.
- Geographic Expansion in Asia:Rising consumer income and awareness in Southeast Asian countries present a growth opportunity for natural color suppliers who can offer cost-effective and locally sourced solutions.
Industry Challenges
- Navigating Regulatory Mosaics:Formulators face long and complex approval timelines when launching products globally, as they must independently satisfy the distinct requirements of the FDA, EFSA, and FSSAI.
- Formulation Expertise Scarcity:A skills gap exists in finding technicians who can achieve target shades and ensure stability using natural colorants, which are less predictable than their synthetic counterparts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Colors Market |
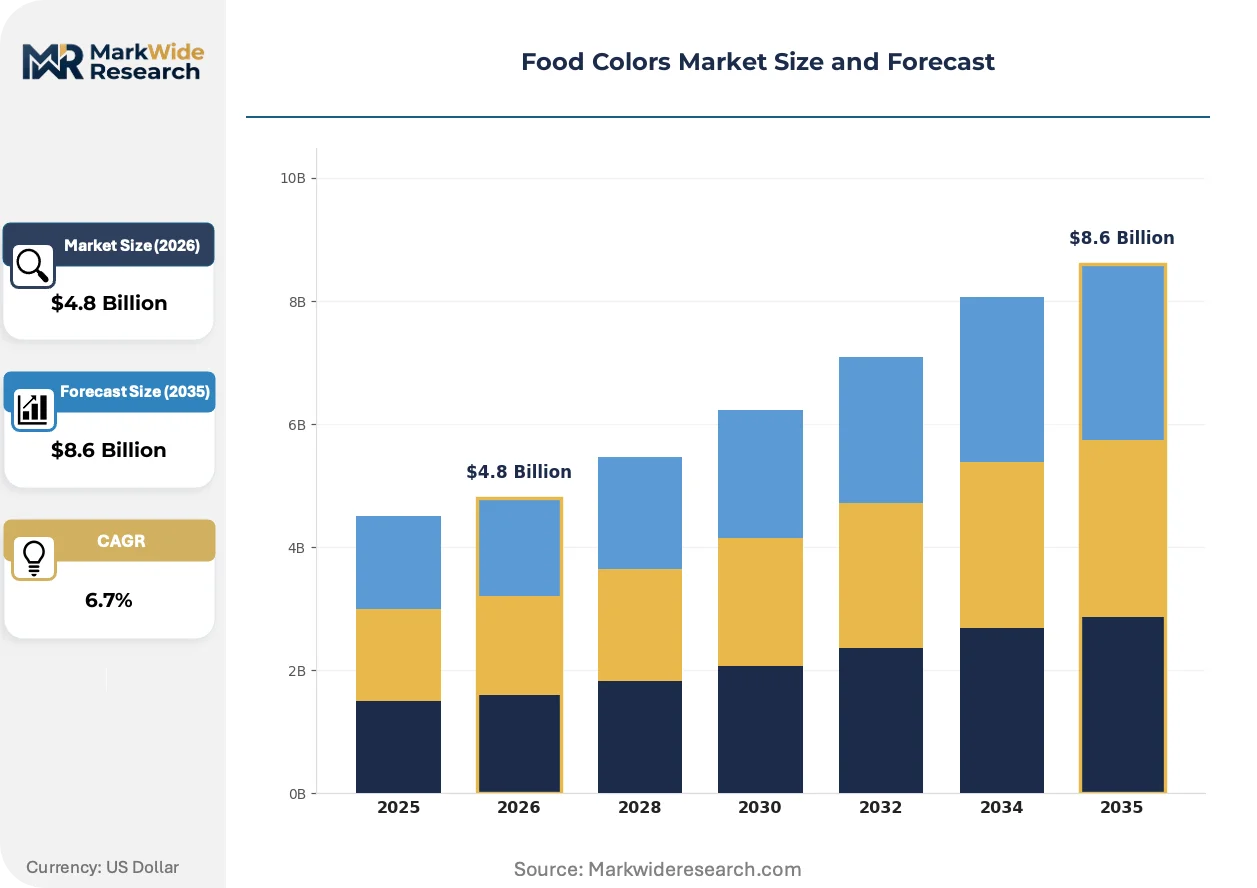
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colors, Synthetic Colors, Blends, Specialty Colors, Certified Colors Form: Liquid, Powder, Gel, Paste, Spray Application: Beverages, Confectionery, Bakery Products, Dairy Alternatives, Sauces & Dressings End User: Food Processing Units, Beverage Manufacturers, Bakery Units, Confectionery Makers, Catering Services |
| Companies Covered | Sensient Technologies Corporation, Oterra A/S, GNT Group, ADM, Givaudan, Döhler GmbH, International Flavors & Fragrances Inc., San-Ei Gen F.F.I., Inc., ROHA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Colors Market Strategic Shifts & Innovations
Formulation science is undergoing a significant recalibration as the industry shifts its focus from synthetic chemistry to agricultural science and advanced extraction. This pivot impacts everything from raw material sourcing and processing technology to final product stability and regulatory compliance, defining a new competitive landscape.
Microencapsulation technology provides a protective barrier for sensitive color molecules. Food and beverage manufacturers, particularly in the confectionery and beverage sectors, are adopting this technology to improve product quality. This process is integrating formerly unstable natural pigments into product categories with harsh processing conditions, expanding their viability and market reach.
The U.S. Food and Drug Administration (FDA) maintains a dual regulatory pathway for color additives, classifying them as either subject to certification or exempt. This distinction creates significant compliance and formulation hurdles for companies operating in multiple international markets. The beverage and dairy alternative segments are most affected, often requiring separate product formulations to meet the FDA's specific standards.
A notable shift in consumer preference is the demand for colors derived from recognizable food sources, often labeled as "fruit and vegetable concentrates." This trend disrupts the business model for suppliers focused solely on purified pigments, favoring those with upstream control over agricultural supply. This behavior is most prominent in European markets, especially Germany, where clean-label messaging strongly influences purchasing decisions.
Food Colors Market Segmentation
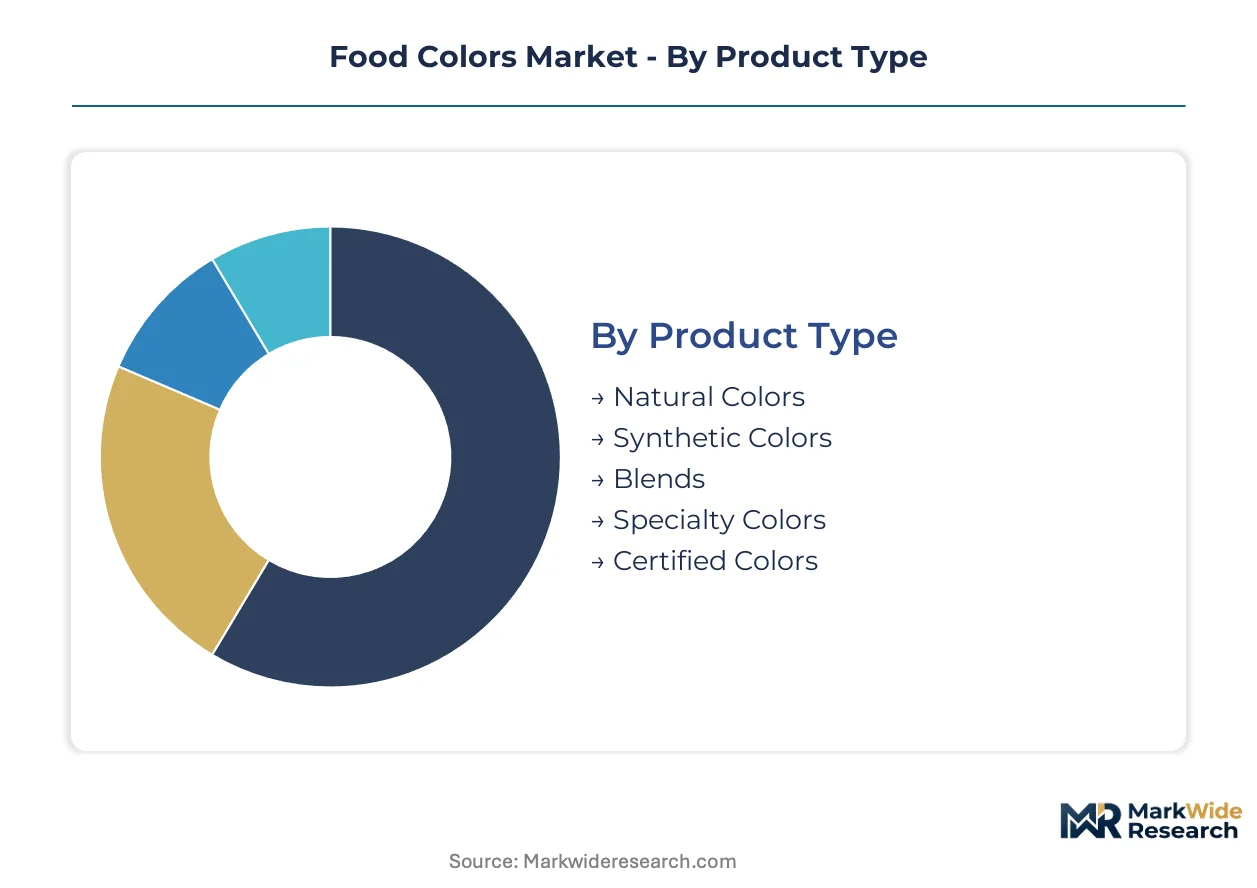
Understanding the varied segments within the food colors market illuminates distinct demand drivers and technological requirements. This segmentation highlights how different product types, physical forms, and end-use applications shape formulation strategies and procurement decisions for manufacturers globally.
Product Type:
The technological sophistication and source material define distinct product type segments within the food colors market.
- Natural Colors:These colorants derive from plant, animal, or mineral sources, extracted through physical or chemical processes. Demand is concentrating in European markets, particularly Germany, driven by stringent clean-label mandates from the EFSA.
- Synthetic Colors:Artificially produced color additives offer high color strength, stability, and cost-effectiveness. Application remains significant in specific confectionery products, where their vibrant hues are critical for visual appeal.
- Blends:Combinations of two or more colorants optimize hue, stability, or cost for specific food applications.
- Specialty Colors:These are customized formulations designed for niche applications requiring unique color properties or processing tolerance.
- Certified Colors:Synthetic dyes approved by regulatory bodies like the FDA, requiring batch-by-batch certification for purity and safety.
Mature deployment sits with Synthetic Colors. Newer deployment is concentrated in Natural Colors.
Form:
The physical consistency of food colors dictates their suitability for various manufacturing processes and product formulations.
- Liquid:These forms offer ease of dispersion and consistent color distribution in water-based systems, widely used in beverage manufacturing. Their precise dosing capabilities reduce formulation errors and ensure batch-to-batch consistency.
- Powder:Highly concentrated and stable, powder forms are preferred for dry mixes, bakery applications, and products requiring extended shelf life. They offer excellent stability against degradation from light and heat during storage.
- Gel:Highly concentrated and viscous, gel colors are ideal for decorating and specific confectionery applications requiring precise color placement.
- Paste:Offering rich color intensity, paste forms find use in icing, fondant, and specific bakery products where moisture content is controlled.
- Spray:Applied externally, spray colors provide surface coloration for confectionery and baked goods, enhancing visual appeal quickly.
Volume concentration is highest in Powder and Liquid forms, reflecting their broad utility across the food industry.
Application:
Diverse application segments impose distinct functional requirements on food colorants, influencing stability, solubility, and processing tolerance.
- Beverages:This category commands a significant share, requiring water-soluble dyes that maintain stability against light and pH changes. The plant-based dairy alternatives segment creates new demand for colors mimicking traditional dairy appearances.
- Dairy Alternatives:The rapid growth of plant-based milk, yogurt, and cheese substitutes drives demand for natural colors. Formulators must achieve appealing visual cues using clean-label ingredients, often facing technical challenges with stability.
- Confectionery:These products require high-stability colors resistant to heat and pH changes, often utilizing synthetic options or encapsulated natural pigments.
- Bakery Products:Colors in bakery items must withstand high temperatures during baking, making heat-stable natural pigments or synthetic dyes essential.
- Sauces & Dressings:Colorants in these applications enhance visual appeal and maintain consistency, needing good dispersion properties and pH stability.
The Dairy Alternatives segment exhibits the steepest expansion trajectory, driven by consumer health trends and plant-based innovation.
End User:
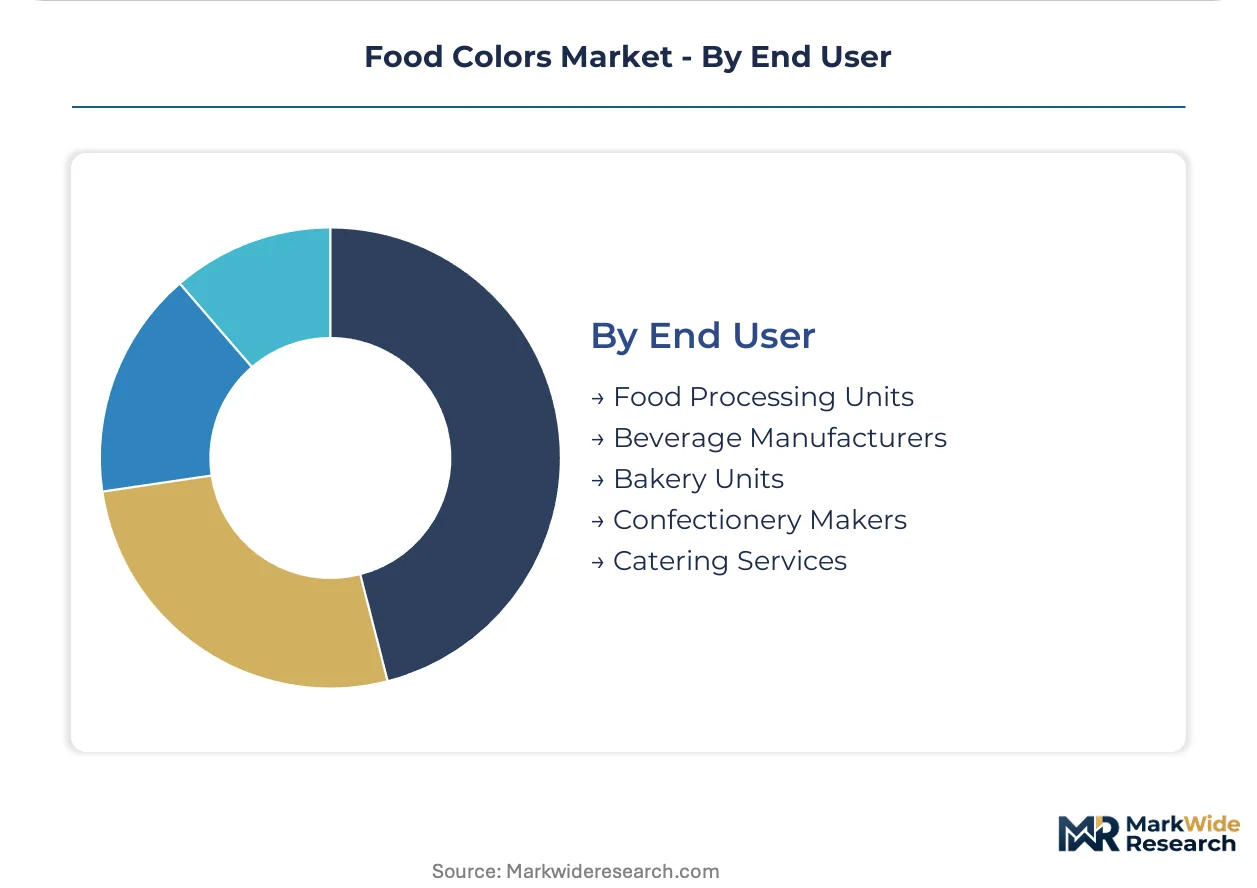
The operational scale and product focus of end-user entities shape procurement patterns and colorant specifications.
- Food Processing Units:These large-scale operations integrate colorants into a wide array of packaged foods, from snacks to ready meals. Their procurement emphasizes bulk quantities, consistent quality, and adherence to global regulatory standards.
- Beverage Manufacturers:Specializing in liquid products, these entities require highly soluble and stable colorants to maintain visual clarity and appeal over shelf life. Regulatory compliance for specific drink categories, like those from the FDA, is paramount.
- Bakery Units:These users require heat-stable colorants for doughs, fillings, and icings, ensuring color integrity through baking processes.
- Confectionery Makers:Focus on vibrant, stable colors for candies, chocolates, and gums, often needing specialized formulations for gloss and texture.
- Catering Services:Procurement is often for smaller batches of ready-to-eat foods, emphasizing ease of use and visual appeal for immediate consumption.
Procurement scale and technical requirements are most complex for Food Processing Units, while Catering Services prioritize convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clean-label mandates, particularly in the European Union, are driving the concentration of natural food colorant demand and innovation. Regulatory shifts and consumer preferences for recognizable ingredients shape regional market dynamics significantly. This focus compels manufacturers to adapt formulations and sourcing strategies across diverse global markets.
Germany
Consumer demand for natural colorants and fruit and vegetable concentrates is particularly strong in Germany. The European Food Safety Authority (EFSA) mandates stricter labeling requirements, accelerating the shift from synthetic to natural alternatives. Major food processing hubs in Bavaria and North Rhine-Westphalia lead the adoption of clean-label color solutions.
United States
The United States market exhibits a growing preference for plant-based food alternatives, which fuels demand for natural colors. The U.S. Food and Drug Administration (FDA) maintains specific regulatory pathways for color additives, influencing formulation strategies. Food manufacturing clusters in California and the Midwest are actively seeking stable, natural color solutions for new product development.
India
Rising consumer income and health awareness in India are driving increased interest in natural food ingredients. The Food Safety and Standards Authority of India (FSSAI) sets national standards for color additives, impacting local and international suppliers. Major food processing centers in Maharashtra and Gujarat are expanding their use of natural colorants in various product categories.
Vietnam
Economic growth and an expanding middle class in Vietnam present a significant opportunity for natural color suppliers. Regional trade agreements and evolving food safety regulations, often aligned with broader ASEAN standards, guide market entry strategies. Ho Chi Minh City's burgeoning food and beverage sector requires cost-effective and locally sourced natural color solutions.
Food Colors Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting varied market entry strategies. The food colors market structure ranges from highly specialized natural extractors to broad portfolio ingredient suppliers. Key strategic archetypes include natural color solution providers, integrated concentrate producers, and diversified ingredient companies. Competitive moves often center on M&A activities to acquire specialized technologies and geographic expansion to tap into emerging clean-label markets.
Specialists in natural color solutions, such as Oterra A/S, focus on advanced extraction technologies for vibrant hues. GNT Group exemplifies players with vertically integrated supply chains for fruit and vegetable concentrates, ensuring consistent quality. ADM occupies a position as a diversified ingredient provider, offering both natural and synthetic options to a wide customer base.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| Oterra A/S |
| GNT Group |
| ADM |
| Givaudan |
| Döhler GmbH |
| International Flavors & Fragrances Inc. |
| San-Ei Gen F.F.I., Inc. |
| ROHA Group |
| Others |
Cost & Logistics Intelligence
Consumer preference for clean-label ingredients is compelling food color suppliers to invest in natural alternatives, which hardens cost structures and influences pricing strategies. This shift demands responsive supply chains capable of managing agricultural input volatility.
Pricing Analysis
Lead-time-driven pricing structures offer premiums for rapid delivery of specialized natural colorants. The dominant model is contract-based long-term offtake for natural colorants, while synthetic colors often trade on commodity spot markets. Price differentiation stems from certification level, particularly FDA-certified colors, and the volume scale of procurement. Pricing pressure stems from the rising cost of natural raw materials. Food Processing Units exhibit lower price sensitivity for high-stability natural solutions compared to Catering Services.
Supply Chain Analysis
Dual-sourcing requirements from major food processors mitigate risk for critical colorant inputs. Geographic supply for natural colorants concentrates in regions like Southeast Asia for spirulina and India for turmeric. Raw material dependencies include agricultural crops such as beetroot, paprika, and specific algae strains. A structural risk is climate-related supply disruptions impacting agricultural yields. Distribution runs through a network of specialized ingredient distributors and direct sales from large manufacturers like ADM.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food colors market is evolving into a vertical-integration race, driven by the need for upstream control over agricultural sourcing for natural pigments. Companies are pursuing advanced extraction technologies to secure consistent quality and supply.
For Market Incumbents:Hedge against volatile raw material costs by securing long-term contracts with diverse agricultural suppliers. Invest in microencapsulation R&D to overcome technical stability limits of natural colorants, a persistent threat to wider adoption. Expand production capacity for high-demand natural sources like spirulina in strategic geographies. This strengthens competitive positioning against emerging specialized extractors.
For New Entrants and Emerging Players:Capture niche opportunities in the clean-label pet food segment, which remains largely underpenetrated. Target the Southeast Asian market, particularly Vietnam, with cost-effective and locally sourced natural color solutions. Focus on developing high-stability natural blue and green hues, which present significant formulation challenges for incumbents. A direct-to-consumer model for smaller food manufacturers could provide a viable go-to-market angle.
For Investors and Strategic Acquirers:The window for entry favors strategic acquirers seeking to consolidate specialized natural colorant technologies. Long-term viability hinges on companies demonstrating robust intellectual property in extraction and stabilization processes. Target acquisition archetypes include mid-cap firms with proprietary microencapsulation or advanced botanical extraction capabilities. A signal to watch is the successful commercialization of highly stable natural blue pigments.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Natural Pigments | Increases supply of clean-label colorants to meet rising consumer demand. |
| Backward Integration into Raw Material Sourcing | Secures consistent quality and reduces price volatility for essential agricultural inputs. |
| Investment in Microencapsulation Technology | Extends application viability of sensitive natural colors into high-heat products. |
| Strategic Partnerships for Distribution | Expands market reach into emerging clean-label geographies like Southeast Asia. |
| New Product Development for Plant-Based Dairy | Addresses specific visual requirements for rapidly expanding plant-based dairy alternatives. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary research involved interviews with R&D directors, procurement leads at Food Processing Units, and regulatory affairs specialists. This approach combined bottom-up market sizing with top-down validation. Expert insights from ingredient suppliers like Oterra A/S further refined data points.
Market volume and value were modeled at a granular level by product type, physical form, and end-use application. The analytical framework projected growth across the analysis window based on historical trends and future demand drivers. Compound annual growth rates were derived from a weighted average of segment-specific expansion rates. Key forecast inputs included regulatory mandates from the EFSA and consumer adoption rates of plant-based dairy alternatives.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen regulatory shifts or agricultural supply shocks. These projections reflect current market dynamics and known technological trajectories. Deviation in raw material price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Modified Flour Market
Ingredients
Sunflower Oil Market
Ingredients
Feed Premix Market
Ingredients
Bread Flour Market
Ingredients
Fluid Lecithin Market
Ingredients
Coconut Derivatives Market
Ingredients
Non-GMO Oil Market
Ingredients
Global Dairy Protein Ingredients Market
Ingredients
Camelina Oil Market
Ingredients
Savory Ingredients Market
Ingredients
Hydrogenated Starch Market
Ingredients
Europe Corn Glucose Market
Ingredients
Commercial Flour Market
Ingredients
Wheat Germ Oil Market
Ingredients
North America Dairy Protein Ingredients Market
Ingredients
Bleached Flour Market