
 United States Gelatin Market | 2026-2036
United States Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
United States Gelatin Market Analytics
Asset-light toll manufacturing and third-party rendering partnerships are reshaping capital deployment across the United States gelatin value chain. Darling Ingredients leverages vertical integration from rendering to collagen peptide production across multiple US facilities. GELITA AG sustains technology leadership in hydrolyzed gelatin grades for pharmaceutical encapsulation. Rousselot competes through specialized fish-source gelatin positioned for kosher and halal certification requirements.
Gelatin is a thermally reversible hydrocolloid derived from partial hydrolysis of collagen, with bloom strength ranging from 50 to 300 grams defining its gel-forming capacity; it functions primarily as a gelling agent, stabilizer, and film-former across food and pharmaceutical matrices. Powdered gelatin occupies the dominant volume position due to its shelf stability and ease of scaling in industrial batch processing. Pharmaceutical companies represent the fastest-growing end-user channel as hard-shell capsule demand expands alongside generic drug manufacturing. Bovine-source gelatin retains margin concentration from established pharmaceutical validation dossiers, though fish-source alternatives gain traction in specialized dietary applications.
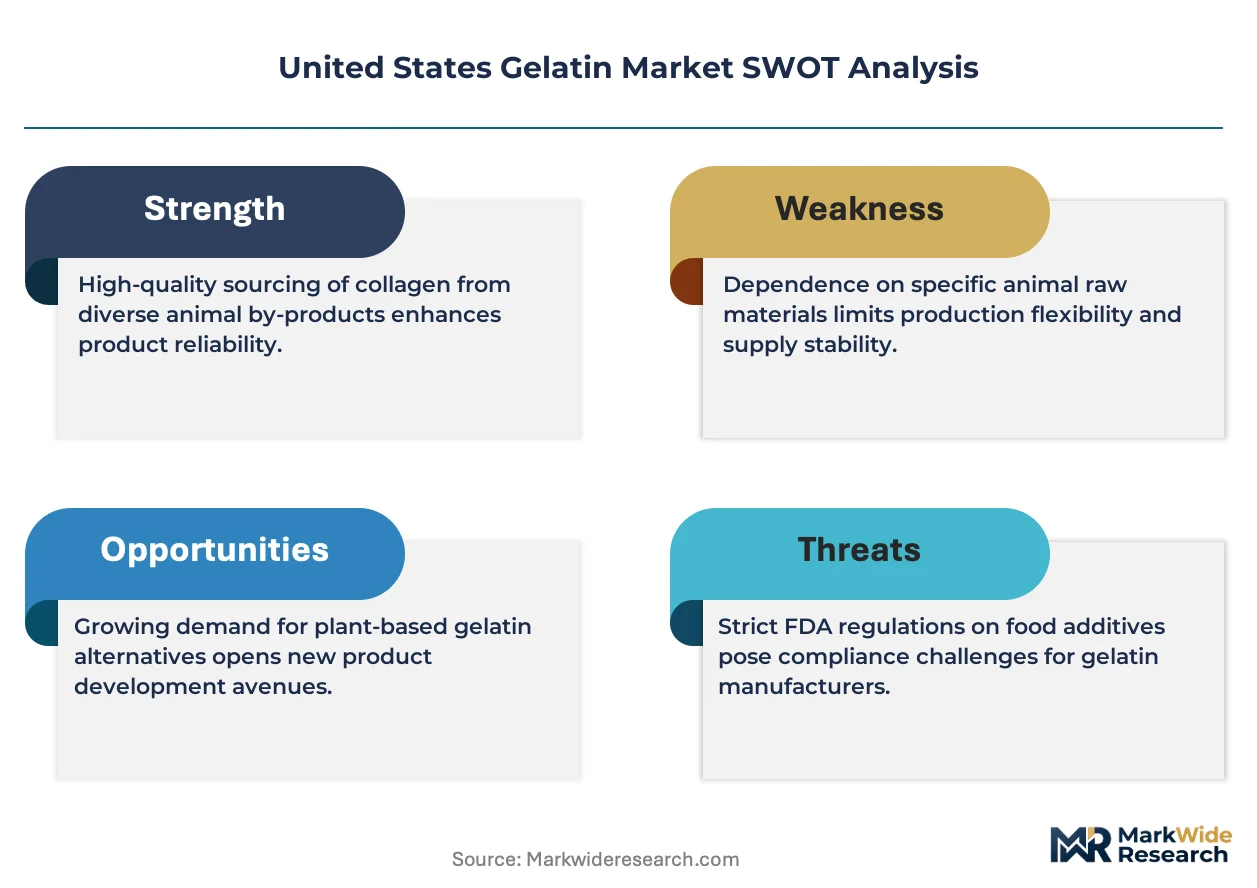
The FDA enforces bovine spongiform encephalopathy safeguards through specified risk material prohibitions, while USDA inspectors monitor rendering facility compliance under Hazard Analysis Critical Control Point frameworks. These dual oversight layers elevate compliance costs for domestic processors but simultaneously restrict lower-standard imports from entering pharmaceutical supply chains. Stakeholders must monitor emerging state-level labeling initiatives in California and New York that could mandate enhanced source disclosure beyond current federal requirements.
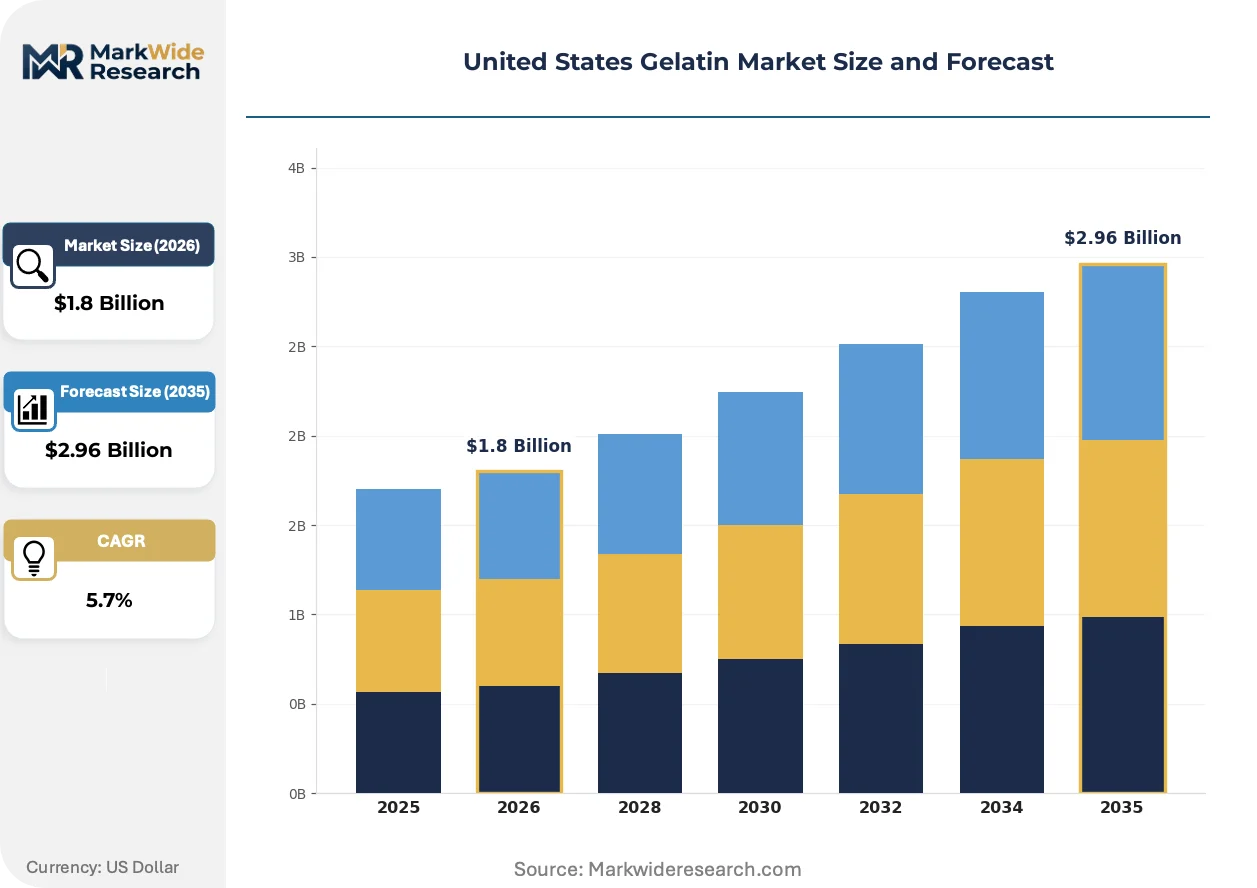
Market Dynamics
Pharmaceutical encapsulation demand is compressing gelatin supply chains toward bovine-source validation dossiers, while FDA traceability mandates force rendering facilities into dual-layer compliance investments that reshape capital deployment patterns across domestic processors.
Growth Catalysts
- Capsule manufacturing expansion:Hard-shell capsule production lines at New Jersey and Pennsylvania pharmaceutical clusters pull specialized hydrolyzed gelatin grades into dedicated supply contracts.
- FDA BSE safeguards:Specified risk material prohibitions create quality-tier separation that rewards domestic processors with validated pharmaceutical dossiers over import competition.
- Collagen peptide diversification:Rendering-to-peptide processing technology unlocks margin capture in nutraceutical applications beyond traditional gelatin extraction.
Market Restraints
- Bovine raw material concentration:Cattle hide and bone supply clusters in Midwest rendering facilities, creating geographic dependency for pharmaceutical-grade extraction.
- Porcine substitution barriers:Religious dietary restrictions block porcine-source gelatin from kosher and halal pharmaceutical markets, fragmenting addressable demand.
- USDA HACCP compliance costs:Rendering facility inspection protocols elevate fixed cost structures that disadvantage smaller regional processors.
Strategic Opportunities
- Fish-source certification gaps:Kosher and halal gelatin alternatives remain underdeveloped in domestic pharmaceutical supply chains despite growing dietary compliance requirements.
- California labeling mandates:State-level source disclosure initiatives could create first-mover advantage for processors with transparent bovine supply chain documentation.
- Toll manufacturing partnerships:Asset-light processing agreements allow pharmaceutical companies to outsource gelatin conversion without captive rendering investments.
Industry Challenges
- Bloom strength calibration talent:Gel-forming capacity testing requires specialized laboratory expertise that concentrates in legacy pharmaceutical manufacturing regions.
- Dual FDA-USDA audit timelines:Simultaneous compliance verification for rendering and pharmaceutical-grade production extends facility qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Gelatin Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Gelatin, Sheet Gelatin, Granulated Gelatin, Instant Gelatin End User: Food Industry, Pharmaceutical Companies, Cosmetics Sector, Nutraceuticals Source: Porcine Source, Bovine Source, Fish Source, Vegetable Source Application: Food & Beverages, Medical Devices, Dietary Supplements, Confectionery |
| Companies Covered | Darling Ingredients, GELITA AG, Nitta Gelatin, Rousselot, Ajinomoto, Weishardt Group, Tessenderlo Group, Sterling Gelatin, PB Leiner, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Gelatin Market Evolving Landscape
Digital traceability systems are penetrating gelatin supply chains as pharmaceutical buyers demand real-time documentation of bovine sourcing and rendering facility compliance status.
Blockchain-enabled batch tracking is digitizing the chain-of-custody documentation that FDA BSE protocols require for pharmaceutical-grade gelatin. Major capsule manufacturers now mandate supplier integration with distributed ledger platforms that record cattle origin, rendering dates, and laboratory bloom strength testing. This transparency infrastructure is compressing audit timelines while excluding smaller processors lacking IT investment capacity.
USDA inspectors are intensifying Hazard Analysis Critical Control Point enforcement at rendering facilities that supply pharmaceutical gelatin streams. The agency's 2024 facility audit expansion is forcing processors to deploy dedicated compliance personnel and automated temperature monitoring systems. Midwest rendering operations face the steepest adjustment costs as they retrofit legacy equipment for continuous data logging.
Pharmaceutical procurement teams are consolidating gelatin supplier relationships around processors with integrated rendering-to-extraction capabilities. Generic drug manufacturers in the Northeast corridor now favor single-source contracts that bundle raw material security with validated pharmaceutical dossiers. This buyer concentration is squeezing toll manufacturers that lack captive bovine supply or in-house peptide hydrolysis technology.
United States Gelatin Market Segmentation
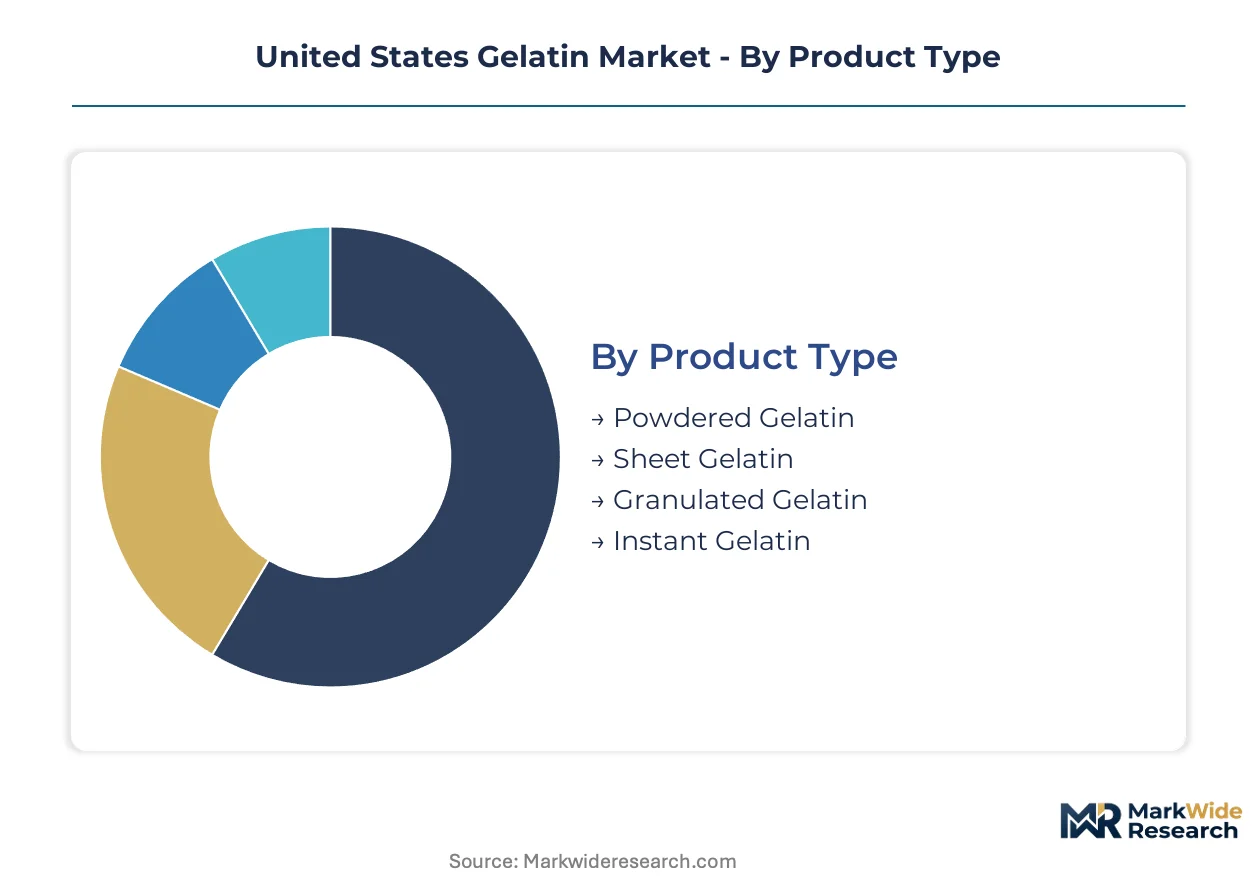
Segmentation in the United States gelatin market reveals how pharmaceutical validation requirements, religious dietary compliance, and industrial processing economics create distinct demand corridors. Each dimension carries regulatory and supply chain implications that reshape procurement patterns across end-use industries.
Product Type:
Mature formats dominate industrial procurement while emerging formats target convenience-driven niches.
- Powdered Gelatin:Dehydrated protein matrix with bloom strength calibrated to 50-300 gram specifications enables precise industrial batch scaling. Pharmaceutical manufacturers in New Jersey and Pennsylvania clusters specify powdered grades for hard-shell capsule production lines where moisture control determines shelf stability. Powdered gelatin retains volume leadership; instant gelatin holds the steepest expansion curve.
- Sheet Gelatin:Pre-portioned leaf format delivers standardized gel strength per sheet, eliminating weighing errors in premium confectionery and restaurant kitchens. Northeast foodservice distributors stock sheet gelatin for high-end patisserie accounts where consistency outweighs unit cost premiums.
- Granulated Gelatin:Intermediate particle size dissolves faster than standard powder while maintaining bloom integrity, serving mid-tier food manufacturers seeking processing efficiency without instant-grade premiums.
- Instant Gelatin:Pre-gelatinized cold-water soluble format eliminates heating steps, penetrating home baking and quick-service beverage applications where preparation speed drives purchase decisions.
Powdered gelatin commands industrial procurement volumes; instant formats are climbing the fastest in consumer-direct channels.
End User:
Cost tier stratification separates validated pharmaceutical supply from commodity food applications.
- Food Industry:Mass-market confectionery, dairy stabilization, and meat processing absorb standard-grade gelatin where bloom strength consistency matters more than traceability documentation. Midwest meatpacking corridors source bovine gelatin for canned ham and aspic applications.
- Pharmaceutical Companies:Hard-shell capsule and tablet coating applications demand FDA-validated bovine-source dossiers with BSE risk material documentation. Generic drug manufacturers concentrate procurement around Northeast manufacturing clusters where dual FDA-USDA audit capabilities filter supplier eligibility. Pharmaceutical companies represent the segment gaining share fastest; cosmetics sector procurement remains the most price-sensitive tier.
- Cosmetics Sector:Film-forming and moisture-binding properties drive gelatin incorporation into masks and hair treatments, though plant-based alternatives constrain growth in clean-beauty-positioned brands.
- Nutraceuticals:Collagen peptide extraction from gelatin hydrolysate serves functional food and supplement markets, with rendering-to-peptide processing technology unlocking margin capture beyond traditional gelatin extraction.
Pharmaceutical procurement carries the highest compliance cost burden; nutraceuticals demonstrate the most rapid application expansion.
Source:
Geographic supply concentration and religious certification requirements fragment sourcing strategies.
- Bovine Source:Cattle hide and bone collagen from Midwest rendering facilities supplies pharmaceutical-grade extraction with established FDA validation pathways. Bovine source retains volume leadership; fish source holds the steepest expansion curve.
- Porcine Source:Pig skin collagen offers higher gel strength per unit but faces exclusion from kosher and halal markets, limiting addressable demand in religiously observant populations and export corridors.
- Fish Source:Marine collagen addresses kosher and halal certification gaps while penetrating clean-label positioning, though domestic pharmaceutical validation dossiers remain underdeveloped relative to bovine alternatives.
- Vegetable Source:Pectin and carrageenan alternatives serve vegan-positioned products but lack the thermoreversible gel properties that define gelatin functionality in pharmaceutical encapsulation.
Bovine sourcing anchors pharmaceutical supply security; fish alternatives are expanding most quickly in dietary supplement applications.
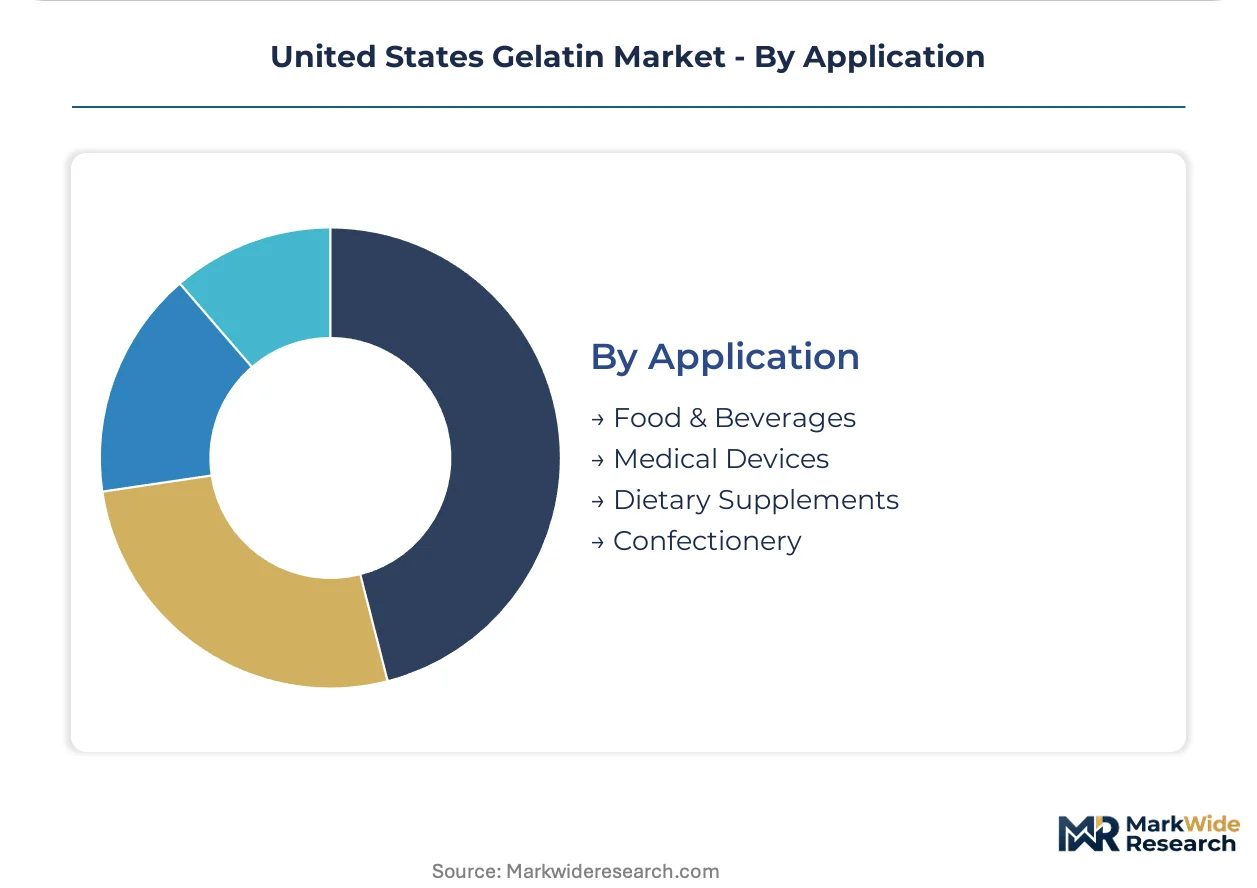
Application:
Margin structure separates medical-device-grade validation from commodity food processing.
- Food & Beverages:Gelling, stabilizing, and clarifying functions span confectionery, dairy, and beverage applications where cost-per-gel-unit drives supplier selection.
- Medical Devices:Hemostatic sponges and wound dressings require absorbable gelatin formulations with biocompatibility certification, commanding premium pricing over food-grade equivalents.
- Dietary Supplements:Collagen peptide powders and soft-gel encapsulation serve functional wellness markets, with rendering-to-peptide vertical integration capturing margin from raw material through finished ingredient.
- Confectionery:Gummy candies and marshmallows depend on specific bloom strength ranges for texture control, with Pennsylvania and New Jersey manufacturing clusters driving regional demand concentration.
Food and beverage applications retain volume leadership; medical devices demonstrate the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade gelatin commands premium pricing in the Northeast corridor while Midwest rendering operations absorb margin compression from USDA compliance costs. This pricing-power asymmetry reflects divergent regulatory exposure and end-use concentration across domestic supply chains.
Northeast Corridor
Hard-shell capsule manufacturing clusters in New Jersey and Pennsylvania pull specialized hydrolyzed gelatin grades through dedicated supply contracts. FDA BSE safeguard enforcement creates quality-tier separation that rewards processors with validated pharmaceutical dossiers. Bloom strength calibration laboratories concentrate in legacy pharmaceutical regions around Philadelphia and northern New Jersey.
Midwest Rendering Belt
Cattle hide and bone supply from Midwest packing facilities feeds pharmaceutical-grade extraction with established USDA HACCP pathways. Rendering facility inspection protocols elevate fixed cost structures that disadvantage smaller regional processors. Chicago and Omaha processing centers face retrofit investments for automated temperature monitoring and continuous data logging systems.
Southeast Pharmaceutical Growth
Generic drug manufacturing expansion in North Carolina and Georgia is pulling gelatin procurement southward from traditional Northeast anchors. State economic development incentives for life sciences manufacturing are accelerating facility construction. Research Triangle Park and suburban Atlanta pharmaceutical campuses are negotiating toll manufacturing partnerships for gelatin conversion capacity.
California Labeling Frontier
State-level source disclosure initiatives in California are mandating enhanced bovine supply chain documentation beyond current federal requirements. Nutraceutical and dietary supplement manufacturers in Los Angeles and San Francisco Bay Area clusters are demanding transparent rendering-to-extraction records. Clean-label positioning is accelerating fish-source gelatin trials for kosher and halal compliance.
Pacific Northwest Niche
Specialized dietary supplement manufacturers in Oregon and Washington are sourcing marine collagen alternatives for vegan-adjacent positioning. Portland and Seattle functional food clusters are testing fish-source gelatin validation pathways for pharmaceutical-grade applications. Regional rendering infrastructure remains underdeveloped relative to bovine-dependent Midwest supply chains.
United States Gelatin Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the gelatin value chain, creating a tiered structure where rendering-to-extraction capabilities determine supplier eligibility. The vendor base concentrates around processors with validated pharmaceutical dossiers and dual FDA-USDA audit capabilities. Three archetypes dominate: vertically integrated rendering specialists, toll manufacturing intermediaries, and fish-source certification pioneers. Competitive moves center on backward integration into rendering assets and strategic partnerships with pharmaceutical procurement teams.
Among the integrated processor tier, Darling Ingredients and GELITA AG exemplify divergent strategic positioning within pharmaceutical supply chains. Darling Ingredients anchors the rendering-to-peptide vertical integration archetype across multiple domestic facilities. GELITA AG occupies the technology leadership position in hydrolyzed gelatin grades for encapsulation applications. Rousselot represents the specialized sourcing vector, positioned around fish-source alternatives for kosher and halal market requirements.
| Leading Market Players |
|---|
| Darling Ingredients |
| GELITA AG |
| Nitta Gelatin |
| Rousselot |
| Ajinomoto |
| Weishardt Group |
| Tessenderlo Group |
| Sterling Gelatin |
| PB Leiner |
| Others |
Value Network & Pricing Analysis
FDA BSE safeguard enforcement creates a dual-layer compliance chokepoint that simultaneously widens pharmaceutical-grade pricing spreads and compresses Midwest rendering operations into validated supply tiers. This regulatory risk vector forces domestic processors to absorb fixed-cost investments that import competitors cannot replicate, embedding quality-tier separation directly into procurement economics.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across pharmaceutical gelatin procurement. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated bovine-source dossiers from commodity food-grade alternatives. Cost compression in standard tiers is intensifying because toll manufacturers lack captive rendering assets to defray USDA HACCP compliance burdens. Generic drug manufacturers demonstrate the highest price sensitivity; medical device hemostatic applications show the least.
Supply Chain Analysis
Darling Ingredients, GELITA AG, and Rousselot concentrate pharmaceutical-grade extraction capacity across domestic toll manufacturing partnerships. Cattle hide and bone supply clusters in the United States Midwest; fish-source alternatives draw from Pacific Northwest marine rendering infrastructure. Single-source vulnerability rests on Midwest bovine raw material concentration where packing facility consolidation has reduced supplier diversity. Distribution runs through dedicated pharmaceutical supply contracts rather than spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical procurement consolidation around single-source contracts with integrated rendering-to-extraction capabilities has shifted buyer power toward generic drug manufacturers in the Northeast corridor. This buyer-side concentration fragments leverage for smaller toll processors lacking validated dossiers.
For Market Incumbents: Pre-empt fish-source certification gaps by securing kosher and halal validation pathways before pharmaceutical buyers mandate dietary compliance alternatives. Lock in backward integration into Midwest rendering assets to secure raw material security against cattle supply volatility. Prioritize blockchain-enabled batch tracking integration to compress FDA audit timelines and exclude IT-limited regional competitors.
For New Entrants and Emerging Players: The Southeast pharmaceutical growth corridor offers the most penetrable geographic entry point as North Carolina and Georgia generic manufacturing expansion outpaces established Northeast supply relationships. Target toll manufacturing partnerships with Research Triangle Park and suburban Atlanta facilities seeking gelatin conversion capacity without captive rendering investments. Lead with transparent bovine supply chain documentation to capture California labeling mandate premiums.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated rendering specialists with validated pharmaceutical dossiers. Long-term viability hinges on dual FDA-USDA audit capabilities that create regulatory moats against import competition. Monitor fish-source gelatin validation pathway progress as the inflection signal for kosher and halal market penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rendering Assets | Captive bovine supply secures raw material access against Midwest packing facility consolidation. |
| Blockchain-Enabled Batch Tracking Deployment | Distributed ledger documentation compresses FDA BSE audit timelines for pharmaceutical buyers. |
| Fish-Source Kosher and Halal Certification | Marine collagen alternatives penetrate religious dietary compliance gaps in pharmaceutical supply chains. |
| Toll Manufacturing Partnership Expansion | Asset-light processing agreements allow Southeast pharmaceutical clusters to outsource gelatin conversion. |
| Collagen Peptide Hydrolysis Technology Investment | Rendering-to-peptide processing captures nutraceutical margin beyond traditional gelatin extraction. |
Research Methodology
A spread of perspectives from pharmaceutical procurement managers, USDA compliance officers, rendering facility operators, and capsule manufacturing engineers converged on the working assumptions driving supply chain concentration patterns. Primary fieldwork combined structured interviews across these stakeholder roles with secondary validation from FDA BSE guidance documents, USDA HACCP inspection records, SEC 10-K filings from publicly traded processors, and pharmaceutical supply chain trade publications. Bottom-up volume modeling from end-use applications triangulated against top-down macroeconomic drivers.
Demand-supply balance dynamics across the analysis window anchored the quantitative framework. Segmentation dimensions modeled include product type tier, end-use industry channel, source material origin, and regional manufacturing cluster. CAGRs were derived from trend extrapolation of validated pharmaceutical dossier growth against food-grade commodity stagnation. Key forecast inputs incorporated generic drug manufacturing capacity expansion in the Northeast and Southeast corridors alongside collagen peptide nutraceutical application development.
The forecast holds incumbent behavior within observed patterns; aggressive moves by fish-source certification pioneers or state-level labeling mandate early adopters would shift outcomes beyond projected ranges. Quarterly review of pharmaceutical buyer blockchain integration mandates and USDA facility audit expansion timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bakery Ingredients Market
Ingredients
Tomato Concentrate Market
Ingredients
Injection Grade Soybean Oil Market
Ingredients
Fish Gelatin Market
Ingredients
North America Corn Starch Market
Ingredients
Custom Dry Ingredients Blends Market
Ingredients
Vegan Ingredients Market
Ingredients
Germany Protein Market
Ingredients
Plant Based Premix Market
Ingredients
GCC Egg Powder Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
Cooking Oils and Fats Market
Ingredients
Beverage Ingredients Market
Ingredients
Arachidonic Acid Market
Ingredients
Vital Wheat Gluten Market
Ingredients
Jojoba Oil Market