
 Chicory Root Fiber Market | 2026-2036
Chicory Root Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Chicory Root Fiber Market Analytics
The capital-intensity divergence between integrated chicory processors and toll manufacturers is unwinding competitive stability in the prebiotic fiber supply base. BENEO GmbH leverages backward integration into Belgian chicory farming to sustain margin control across the inulin value chain. Cosucra Groupe Warcoing anchors its position through specialized oligofructose production from Western European root supply. Cargill competes via global ingredient distribution networks that extend chicory fiber access into Asian and Latin American formulation markets.
Chicory root fiber comprises non-digestible carbohydrates extracted from Cichorium intybus roots, primarily inulin and oligofructose, which resist human digestive enzymes while selectively fermenting in the colon to promote bifidobacteria proliferation. The extraction process typically involves hot water diffusion followed by enzymatic hydrolysis to tailor chain-length profiles for specific functional applications. Inulin currently leads product-type value capture due to its fat-mimetic properties in dairy alternatives and clean-label positioning, while oligofructose represents the faster-growing segment driven by lower sweetness intensity suitable for savory applications. Bakery products constitute a mature application channel with established formulation protocols, whereas dietary supplements concentrate margin pools through direct-to-consumer prebiotic positioning.
The European Food Safety Authority's health claim authorization process shapes inulin marketing boundaries, while FDA GRAS status governs US market entry thresholds for novel oligofructose formulations. REACH compliance and evolving EU organic certification standards further condition extraction facility investments and raw material sourcing protocols. Stakeholders must monitor regulatory divergence between jurisdictions on prebiotic definition and fiber quantification methodology to align R&D pipelines with enforceable claim frameworks.
Market Dynamics
The EU's updated FIC Regulation on prebiotic labeling claims is forcing inulin suppliers to rebuild substantiation dossiers while simultaneously tightening the competitive filter on marginal producers. This regulatory compression is reshaping supply base stability across Western Europe.
Growth Catalysts
- Clean-label bakery reformulation:German and Belgian bakers are substituting conventional wheat-based fibers with chicory-derived alternatives to meet consumer transparency expectations.
- REACH compliance integration:Extraction facilities achieving full chemical registration status in Belgium and the Netherlands secure preferential access to EU-wide distribution networks.
- Hot water diffusion optimization:Advanced enzymatic hydrolysis protocols are tailoring inulin chain-length profiles for fat-mimetic applications in dairy alternatives.
Market Restraints
- Raw material geographic concentration:Chicory cultivation clusters in Belgium, Germany, and the Netherlands create weather-dependent supply vulnerability.
- EFSA health claim substantiation costs:The European Food Safety Authority's authorization process imposes multi-year dossier development expenses on inulin marketers.
- Polydextrose substitution pressure:Synthetic soluble fibers compete on price in cost-sensitive savory applications where oligofructose sweetness intensity is less critical.
Strategic Opportunities
- Asian formulation market penetration:FDA GRAS status for novel oligofructose formulations enables US-origin suppliers to access Japanese and South Korean dietary supplement channels.
- Savory application white space:Lower-sweetness oligofructose profiles are displacing maltodextrin in reduced-sodium soup and sauce formulations.
- EU organic certification premium capture:Evolving organic extraction standards allow certified Belgian processors to command price premiums in Scandinavian retail.
Industry Challenges
- Colonic fermentation research talent scarcity:Prebiotic mechanism-of-action studies require specialized microbiome scientists in short supply across European R&D clusters.
- Extraction facility capex intensity:Hot water diffusion and enzymatic hydrolysis equipment upgrades demand substantial capital deployment in REACH-compliant installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chicory Root Fiber Market |
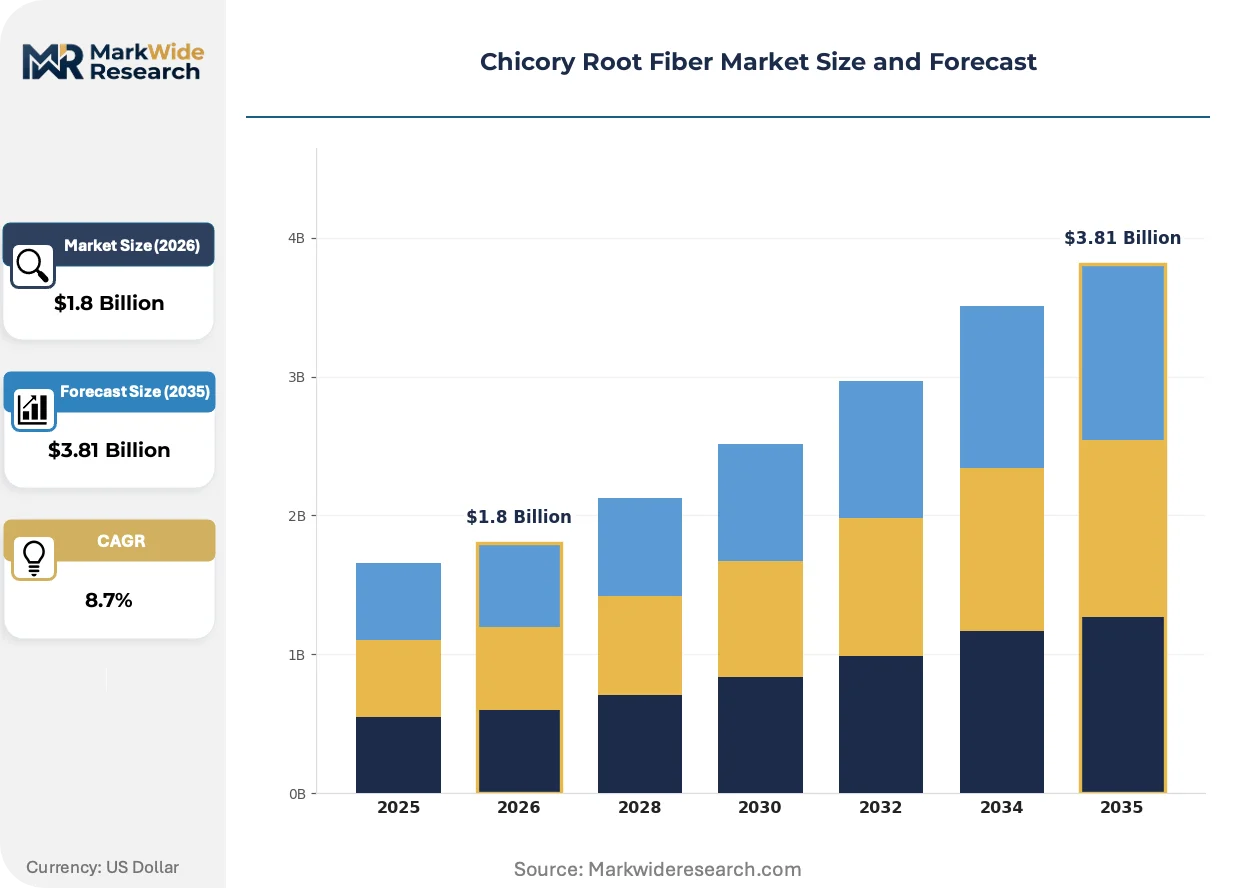
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inulin, Oligofructose, Whole Chicory Root, Powder Application: Food & Beverages, Dietary Supplements, Bakery Products, Confectionery End User: Health Conscious Consumers, Manufacturers, Food Service Providers, Retailers Distribution Channel: Online, Supermarkets, Health Food Stores, Specialty Retailers |
| Companies Covered | BENEO GmbH, Cosucra Groupe Warcoing, Sensus, Ingredion Incorporated, Cargill, Kerry Group, Roquette Frères, FrieslandCampina, Leroux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chicory Root Fiber Market Evolving Landscape
Chicory root fiber processing is undergoing functional specialization as chain-length customization enables precise application targeting. Three developments are compressing the competitive landscape.
Enzymatic hydrolysis tailoring is fragmenting the traditional inulin-oligofructose product boundary. Dairy alternative formulators in Germany and the Netherlands are adopting mid-chain-length fractions that balance fat-mimetic performance with digestive tolerance. This technical segmentation is compressing margins on standardized long-chain inulin while creating premium capture opportunities for processors with precision hydrolysis control.
REACH substance evaluation protocols are extending registration timelines for novel oligofructose variants. The European Chemicals Agency's dossier requirements are forcing extraction facilities to consolidate compliance investments in Belgian and Dutch integrated operations. Smaller toll manufacturers without captive chicory supply are exiting the prebiotic fiber value chain rather than absorbing regulatory compliance costs.
Direct-to-consumer prebiotic positioning is shortening the distribution path for chicory fiber ingredients. Dietary supplement brands in Germany and Belgium are sourcing oligofructose directly from processors rather than through traditional ingredient distributors. This channel compression is visible most acutely in online supplement retail, where clean-label claims require traceability to specific extraction facilities.
Chicory Root Fiber Market Segmentation
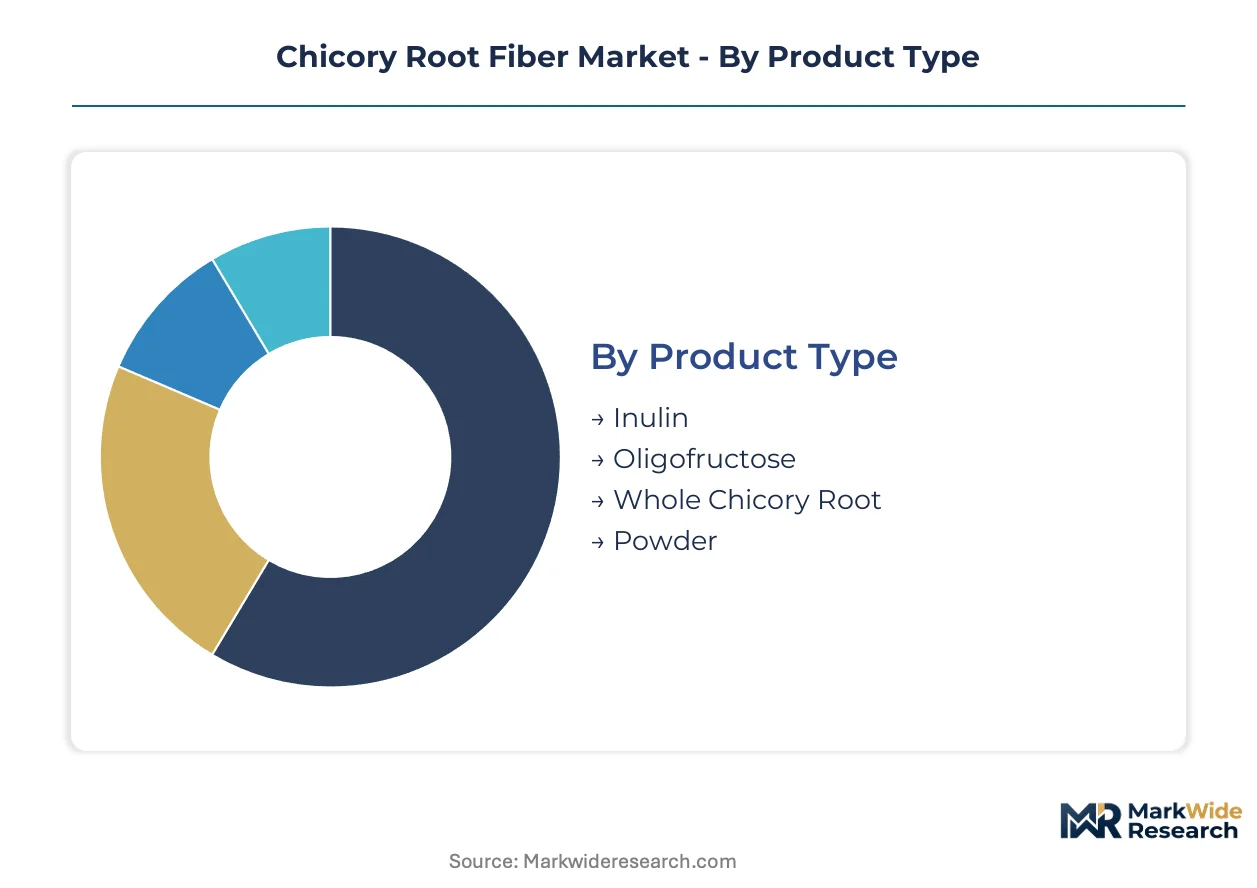
Chicory root fiber markets fragment across extraction technology, application specificity, and channel access. Each dimension carries distinct margin profiles and regulatory exposure that reshape supplier positioning.
Product Type:
Substitution pressure from synthetic soluble fibers concentrates on standardized grades, while tailored chain-length fractions defend premium positioning through functional specificity.
- Inulin:Long-chain non-digestible carbohydrates extracted through hot water diffusion, valued for fat-mimetic properties in dairy alternatives. German and Dutch formulators in clean-label yogurt and plant-based cream segments drive specification demand for specific degree-of-polymerization ranges.
- Oligofructose:Shorter-chain fractions produced via controlled enzymatic hydrolysis of inulin, offering lower sweetness intensity for savory applications. Belgian processors supply reduced-sodium soup manufacturers seeking maltodextrin displacement without sweetness interference.
- Whole Chicory Root:Minimally processed dried root material serving traditional herbal applications and niche functional food formulations.
- Powder:Standardized particle-size distributions for bulk ingredient handling in industrial bakery and supplement manufacturing.
Inulin anchors the volume base while oligofructose gains share at the steepest rate.
Application:
Application maturity determines formulation protocol standardization and the intensity of technical service requirements from chicory fiber suppliers.
- Food & Beverages:Broadest demand channel spanning dairy alternatives, beverages, and functional foods where prebiotic positioning commands label differentiation. REACH-compliant Belgian and Dutch extraction facilities supply major European reformulation programs.
- Dietary Supplements:Highest margin application channel with direct-to-consumer prebiotic positioning and EFSA health claim substantiation requirements. German and Belgian brands source oligofructose directly from processors for online retail traceability.
- Bakery Products:Mature application with established wheat-fiber substitution protocols in German clean-label reformulation.
- Confectionery:Sugar reduction and fiber fortification in reduced-calorie candy and chocolate applications.
Dietary supplements concentrate margin pools while food and beverages sustain volume throughput.
End User:
End-user sophistication shapes procurement patterns from spot-market ingredient buying to integrated supply partnerships with extraction facilities.
- Health Conscious Consumers:Direct purchasers of finished prebiotic supplements and functional foods, driving traceability demands back to specific Belgian and Dutch extraction sites.
- Manufacturers:Industrial formulators in bakery, dairy, and savory segments specifying chain-length profiles for functional performance. German and Belgian manufacturers dominate procurement volume.
- Food Service Providers:Institutional and restaurant chain operators incorporating chicory fiber into menu development for nutritional positioning.
- Retailers:Private-label brand owners sourcing ingredients for store-brand prebiotic and functional food lines.
Manufacturers anchor procurement volume while health conscious consumers accelerate specification intensity fastest.
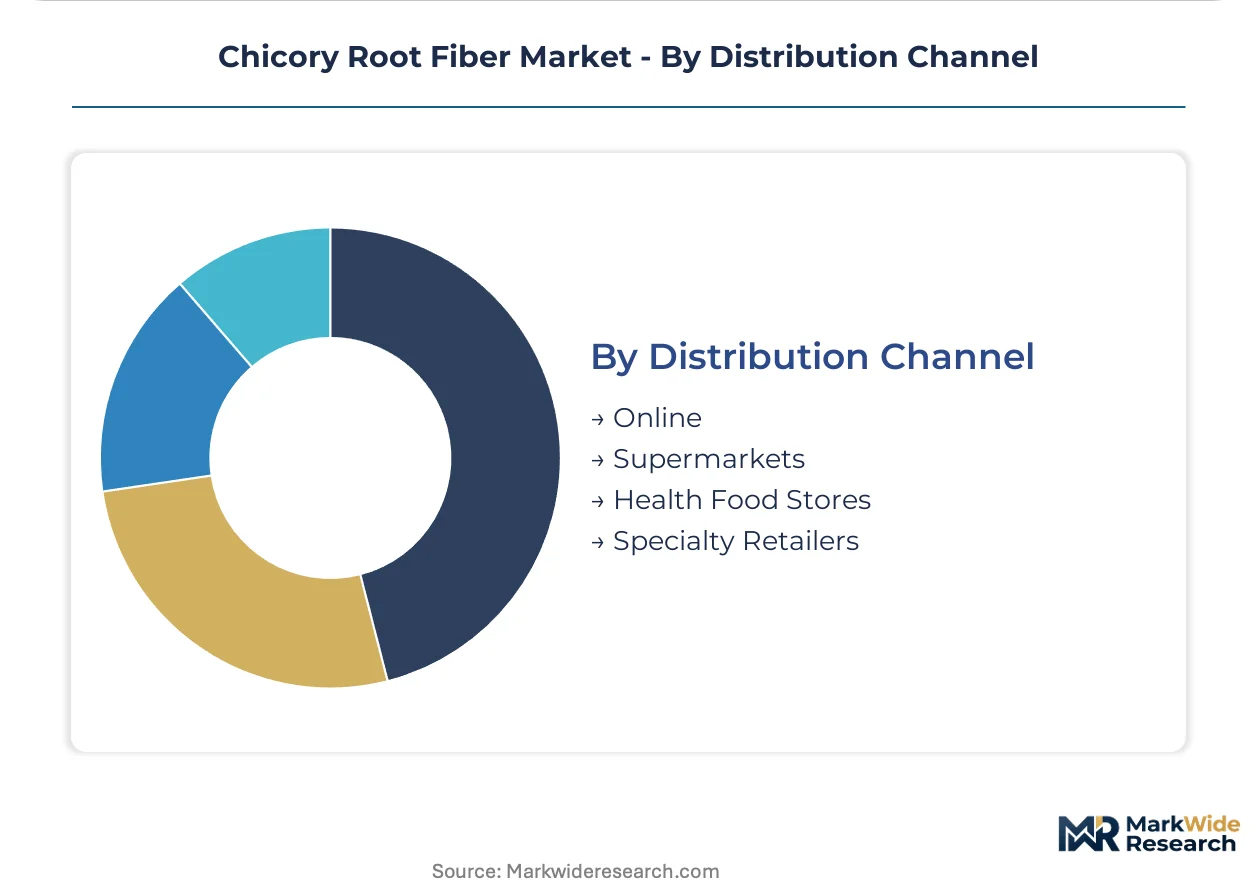
Distribution Channel:
Channel structure determines traceability depth and the compression of traditional ingredient distributor margins.
- Online:Direct processor-to-brand sales accelerating in German and Belgian dietary supplement retail, enabled by clean-label traceability requirements and shortened supply chains.
- Supermarkets:Mass retail channel for finished consumer products containing chicory fiber, with private-label penetration driving volume.
- Health Food Stores:Specialty retail channel emphasizing organic certification and prebiotic health claims with premium positioning.
- Specialty Retailers:Professional ingredient supply to small-scale formulators and regional food manufacturers.
Supermarkets move the largest product volumes while online channels expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry between Belgian integrated processors and Asian toll manufacturers is compressing margin capture in divergent directions. Western European extraction facilities command premiums through REACH-compliant captive chicory supply. Asian distributors absorb margin erosion from synthetic fiber substitution pressure in cost-sensitive savory applications.
Belgium
Clean-label bakery reformulation and oligofructose specialization drive Belgian processor margins. EFSA health claim substantiation requirements filter marginal prebiotic suppliers from the Flemish extraction cluster. Integrated operations in the Warcoing region sustain backward integration into chicory farming for margin control across the inulin value chain.
Germany
Dairy alternative fat-mimetic applications and direct-to-consumer supplement channels concentrate German demand. REACH substance evaluation protocols extend registration timelines for novel oligofructose variants from Bavarian extraction facilities. Cologne-Düsseldorf industrial corridors anchor formulation partnerships between processors and clean-label yogurt manufacturers.
Netherlands
Hot water diffusion optimization and enzymatic hydrolysis tailoring attract Dutch technical investment. ECHA dossier requirements force consolidation of compliance investments in Rotterdam-Antwerp port corridor extraction sites. Gelderland cultivation clusters support integrated processing operations with preferential EU-wide distribution access.
United States
FDA GRAS status for novel oligofructose formulations enables US-origin supplier access to dietary supplement channels. USDA organic certification standards condition raw material sourcing protocols for Midwestern extraction facility investments. Chicago-based ingredient distributors extend chicory fiber access into Latin American formulation markets.
Japan
Prebiotic positioning in functional foods and lower-sweetness savory applications drives Japanese oligofructose specification. METI standards govern novel fiber ingredient approval timelines for Tokyo-Osaka formulation corridors. Yokohama port facilities handle bulk import logistics for domestic supplement manufacturers seeking traceable European extraction sources.
Chicory Root Fiber Market Competitive Landscape
Concentration sits with integrated European processors controlling captive chicory supply and REACH-compliant extraction infrastructure. The vendor base stratifies across three tiers: backward-integrated Belgian specialists with farming operations, global ingredient distributors leveraging network scale, and toll manufacturers facing regulatory compliance exit pressure. Strategic moves center on enzymatic hydrolysis precision investments and direct processor-to-brand channel compression in supplement retail.
Among integrated European specialists, BENEO GmbH and Cosucra Groupe Warcoing exemplify the captive-supply archetype through Belgian extraction infrastructure. Cargill occupies a position representing global distribution network leverage for geographic market extension. These three anchors illustrate the competitive divergence between margin-defended integrated processing and scale-driven ingredient logistics.
| Leading Market Players |
|---|
| BENEO GmbH |
| Cosucra Groupe Warcoing |
| Sensus |
| Ingredion Incorporated |
| Cargill |
| Kerry Group |
| Roquette Frères |
| FrieslandCampina |
| Leroux |
| Others |
Value Network & Pricing Analysis
REACH substance evaluation protocols gate both supply qualification and price differentiation simultaneously, forcing extraction facilities to consolidate compliance investments in Belgian and Dutch integrated operations while marginal toll manufacturers absorb cost disadvantages that compress their pricing flexibility.
Pricing Analysis
Configured-to-order pricing for tailored chain-length fractions commands substantial premiums over standardized inulin grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and enzymatic hydrolysis precision. Cost compression in economy-grade standardized inulin is intensifying because polydextrose substitution pressure from synthetic soluble fibers. Manufacturers in cost-sensitive savory applications exhibit highest price sensitivity, while dietary supplement brands sourcing directly for clean-label traceability show lowest.
Supply Chain Analysis
Strategic stockpiling of chicory root inventory dominates procurement behavior among integrated Belgian processors facing weather-dependent harvest volatility. Supply concentrates in Belgium, Germany, and the Netherlands where cultivation clusters support captive extraction operations. Raw material flows draw from Cichorium intybus farming, hot water diffusion equipment, and enzymatic hydrolysis catalysts. Single-source vulnerability from geographic concentration of chicory cultivation creates structural exposure to climate disruption. Distribution runs through Rotterdam-Antwerp port corridor extraction sites with preferential EU-wide network access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across enzymatic hydrolysis specialization tiers as direct-to-consumer supplement channels shorten supply chains and create niche entry points for traceability-focused processors.
For Market Incumbents: Fortify margin control through backward integration into Gelderland and Warcoing region chicory farming operations. Expand precision hydrolysis capacity to defend against specialty chemical entrants targeting mid-chain-length dairy alternative applications. Prioritize EFSA health claim dossier completion before regulatory substantiation requirements tighten further. For New Entrants and Emerging Players: EU organic certification fast-tracks offer penetration leverage into Scandinavian retail premium capture. Target savory application white space in reduced-sodium soup and sauce formulations where lower-sweetness oligofructose displaces maltodextrin. Pursue direct processor-to-brand supply partnerships with German online supplement retailers demanding extraction facility traceability. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across REACH-compliant extraction infrastructure as ECHA dossier requirements extend registration timelines. Five-to-ten year viability favors integrated Belgian specialists with captive chicory supply over toll manufacturers facing compliance exit pressure. Monitor colonic fermentation research talent scarcity as inflection indicator for R&D pipeline sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chicory Farming | Belgian processors secure margin control across the inulin value chain through Warcoing region cultivation. |
| Precision Enzymatic Hydrolysis Investment | Mid-chain-length fraction customization enables fat-mimetic performance targeting in German dairy alternatives. |
| EFSA Health Claim Dossier Development | Substantiation completion gates marketing boundaries for prebiotic positioning in European supplement channels. |
| Direct-to-Consumer Channel Compression | Processor-to-brand sales shorten supply chains for German online retailers demanding extraction traceability. |
| REACH Compliance Facility Consolidation | Registration investments in Rotterdam-Antwerp corridor sites secure preferential EU-wide distribution network access. |
Research Methodology
The analysis maps extraction technology tiers, application specificity segments, and channel access structures, each validated through primary interviews with extraction facility operations managers, chicory farming cooperative representatives, dietary supplement brand procurement directors, and EFSA regulatory affairs consultants. Secondary validation draws from REACH registration databases, EFSA health claim authorization records, EU organic certification registries, and Belgian agricultural ministry cultivation statistics. Bottom-up volume modeling triangulates against top-down value chain assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, application channel, end-user sophistication, and distribution structure dimensions alongside chain-length customization intensity. CAGRs derive from segment-level growth trajectory aggregation. Forecast inputs incorporate enzymatic hydrolysis precision adoption curves and regulatory substantiation timeline assumptions.
Underlying assumptions cover EFSA authorization progression rates and climate stability in Benelux cultivation regions, with deviation risk concentrated in regulatory divergence on prebiotic definition and fiber quantification methodology. Practitioners should keep alternative scenarios live as EU FIC Regulation enforcement patterns and synthetic fiber substitution dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Africa Sodium Reduction Ingredients Market
Ingredients
Europe Malt Ingredient Market
Ingredients
Agar Agar Flakes Market
Ingredients
Murumuru Butter Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Middle East and Africa Pea Starch Market
Ingredients
Global Hydrolyzed Wheat Protein Market
Ingredients
Avocado Powder Market
Ingredients
Cheese Cultures Market
Ingredients
Global Starch Derivatives Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
Global Pine Pollen Powder Market
Ingredients
Modified Flour Market
Ingredients
Europe Pea Starch Market
Ingredients
Compressed Yeast Market
Ingredients
Global Egg Yolk Oil Market