
 Casein and Caseinates Market | 2026-2036
Casein and Caseinates Market Size, Share, and Industry Trends Forecast 2026-2036
Casein and Caseinates Market Intelligence
Subscription-based technical support for protein fractionation equipment is rebalancing how dairy processors monetize casein output over multi-year contracts. FrieslandCampina leverages its New Zealand milk pool to anchor global caseinate supply chains. Arla Foods sustains competitive positioning through specialized micellar casein production for pharmaceutical-grade applications. Fonterra Co-operative Group dominates Oceania's rennet casein exports with integrated farm-to-ingredient traceability systems.
Casein and caseinates denote milk-derived protein complexes extracted through acid or rennet precipitation, comprising alpha, beta, and kappa fractions with molecular weights ranging from 19 to 24 kilodaltons, functioning primarily as emulsifiers, gelling agents, and slow-release nitrogen sources in formulated foods. Caseinates retain the largest share of value given their superior solubility and neutral flavor profile in processed dairy and beverage applications. Micellar casein captures the fastest expansion trajectory within protein supplements as athletes and clinical nutrition programs prioritize sustained amino acid release over whey hydrolysate spikes. Rennet casein maintains stable demand from mozzarella manufacturers seeking stretch and melt consistency.
The European Food Safety Authority sets maximum residue limits for heavy metals in dairy protein isolates, while the FDA enforces Grade A Pasteurized Milk Ordinance standards for casein destined for U.S. infant formula. India's FSSAI mandates BIS certification for imported caseinates entering the nutraceutical channel, tightening market access for non-compliant suppliers. Stakeholders must monitor evolving protein labeling requirements and carbon intensity disclosures across multiple jurisdictions to preserve formulation partnerships and retail shelf placement.
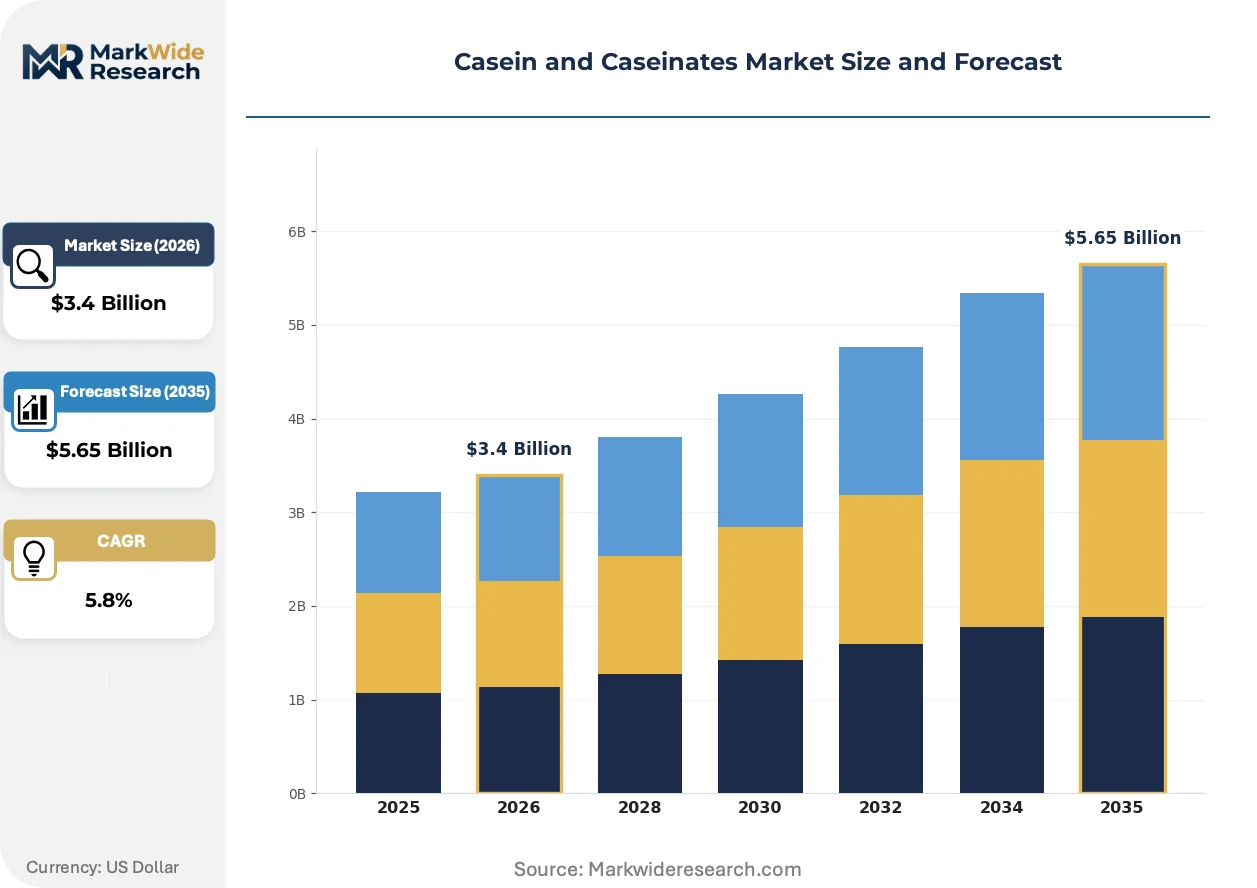
Market Dynamics
The casein and caseinates market pivots on protein fractionation technology maturation, which is compressing extraction costs and enabling smaller dairy processors to compete with established ingredient suppliers previously protected by capital barriers.
Growth Catalysts
- Sports nutrition formulation:Athletes and clinical nutrition programs prioritize micellar casein for sustained amino acid release, displacing whey hydrolysate in overnight recovery products and medical foods.
- REACH chemical disclosure:The European Union's tightened rules on food-grade additive transparency are accelerating supplier consolidation toward compliant processors with integrated traceability systems.
- India:FSSAI-mandated BIS certification for imported caseinates is creating premium positioning for certified suppliers while filtering non-compliant entrants from the nutraceutical channel.
Market Restraints
- Skim milk powder price volatility:Input cost swings for the primary feedstock compress margin predictability for caseinate manufacturers without backward integration into milk pooling.
- Oceania supply concentration:Rennet casein production clusters in New Zealand and Australia, exposing buyers to climate-driven milk supply disruptions and currency fluctuation risks.
- Plant protein substitution:Pea and fava protein isolates are capturing share in processed dairy alternatives, pressuring casein pricing in emulsification applications where functionality gaps have narrowed.
Strategic Opportunities
- Germany's precision nutrition corridor:Demand concentrates among contract manufacturers serving pharmaceutical-grade micellar casein applications, creating anchor customer relationships for qualified suppliers.
- Subscription equipment servicing:Technical support contracts for protein fractionation systems are rebalancing processor monetization toward recurring revenue streams and multi-year supply agreements.
- Carbon intensity disclosures:EU CSRD and emerging U.S. SEC climate rules are creating first-mover advantage for casein suppliers with verified farm-to-ingredient emissions data.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA Grade A Pasteurized Milk Ordinance compliance for infant formula-bound casein requires 18-24 month validation cycles, constraining capacity reallocation speed.
- Cross-jurisdictional labeling fragmentation:Divergent protein content declaration rules between EFSA, FDA, and FSSAI force SKU proliferation and reformulation costs for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Casein and Caseinates Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casein, Micellar Casein, Caseinates, Rennet Casein Application: Dairy Products, Protein Supplements, Bakery, Confectionery End User: Food Industry, Pharmaceutical Sector, Nutraceuticals, Cosmetics Packaging Type: Bags, Drums, Tetra Paks, Bulk Containers |
| Companies Covered | FrieslandCampina, Fonterra Co-operative Group, Arla Foods, Groupe Lactalis, Kerry Group, Lactalis Ingredients, Saputo, Westland Milk Products, AMCO Proteins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Casein and Caseinates Market Strategic Shifts & Innovations
Membrane filtration advances and enzymatic processing refinements are redrawing competitive boundaries between commodity caseinate suppliers and specialized micellar casein producers serving performance nutrition and clinical markets.
Microfiltration ceramic membranes with molecular weight cut-offs between 10 and 50 kilodaltons are decentralizing protein fractionation capacity from centralized dairy cooperatives toward regional processing facilities. Mid-scale dairy processors in the Netherlands and Denmark are deploying these systems to capture margin previously retained by ingredient traders. The technology is decentralizing supply chain power toward processors with proximity to urban demand clusters rather than raw material dominance.
EFSA's evolving heavy metal residue limits for dairy protein isolates are tightening testing protocols and disqualifying suppliers with inconsistent upstream milk quality controls. Manufacturers serving European infant formula brands face batch-level documentation requirements that smaller exporters cannot sustain. Pharmaceutical-grade casein applications bear the highest compliance burden, driving qualified supplier lists toward vertically integrated operations with captive laboratory testing.
Direct procurement relationships between sports nutrition brands and micellar casein processors are compressing traditional ingredient distributor roles. Ready-to-mix protein format manufacturers in Germany and the United Kingdom are negotiating multi-year offtake agreements that lock volume and quality specifications. This channel restructuring is most visible in precision nutrition manufacturing corridors where formulation partnerships determine retail shelf placement.
Casein and Caseinates Market Segmentation
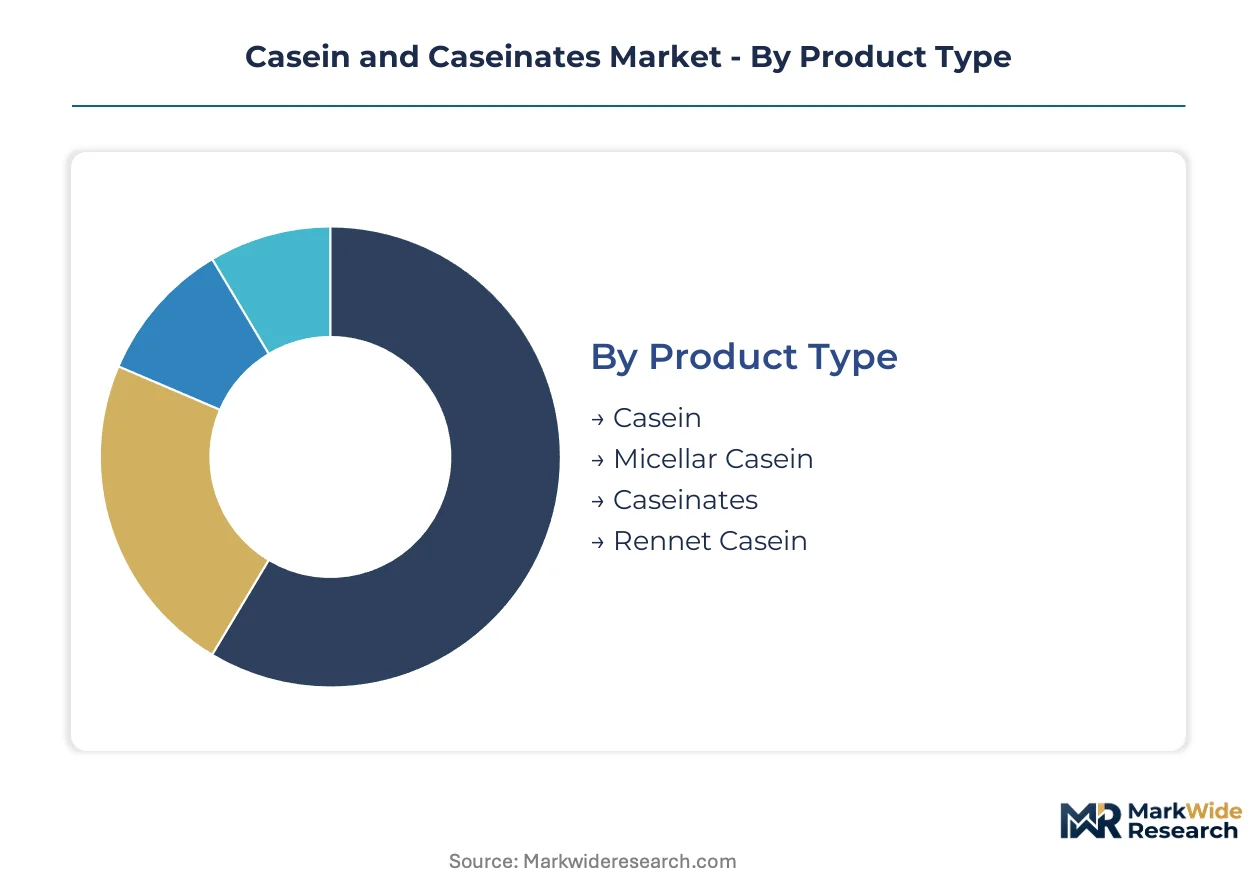
Casein and caseinates exhibit divergent margin profiles and capital requirements across product grades, driving supplier specialization between commodity caseinate production and pharmaceutical-grade micellar casein extraction. Segmentation clarity enables processors to align fractionation investments with customer certification demands and end-use pricing power.
Product Type:
Capital intensity varies sharply across extraction methods, with membrane-based micellar separation requiring multi-million dollar ceramic filtration systems while acid precipitation casein operates on conventional dairy equipment.
- Casein:Acid-precipitated protein complexes containing alpha, beta, and kappa fractions serve as foundational emulsifiers in processed cheese and industrial adhesives. Demand clusters in mozzarella manufacturing corridors across Wisconsin and Lombardy, where stretch and melt specifications tolerate lower solubility than caseinate alternatives.
- Micellar Casein:Native protein structures preserved through microfiltration deliver sustained amino acid release kinetics prized by sports nutrition formulators. Germany's precision nutrition contract manufacturers anchor demand, with multi-year offtake agreements locking volume specifications ahead of retail shelf placement decisions.
- Caseinates:Alkali-treated derivatives achieve superior water solubility and neutral flavor profiles, dominating beverage fortification and infant formula applications. Sodium and calcium variants split demand by end-use compatibility requirements.
- Rennet Casein:Enzyme-coagulated fractions retain calcium phosphate micelle structure for specific cheese stretching properties. Production concentrates in New Zealand's integrated dairy cooperatives with captive farm-to-ingredient traceability systems.
Caseinates absorb the bulk of installed capacity; micellar casein is expanding most quickly.
Application:
Application tiering follows protein functionality requirements, with clinical and performance nutrition commanding price premiums over commodity food processing uses.
- Dairy Products:Processed cheese, yogurt fortification, and cream cheese applications leverage casein's emulsification and water-binding capacity. European dairy processors in the Netherlands and Denmark dominate formulation partnerships with retail private label programs.
- Protein Supplements:Ready-to-mix powders and medical foods prioritize micellar casein's slow-release nitrogen profile for overnight recovery and clinical nutrition. Sports nutrition brands in the United Kingdom and Germany negotiate direct procurement relationships that compress traditional ingredient distributor margins.
- Bakery:Dough conditioning and shelf-life extension applications exploit casein's film-forming properties. Industrial bakeries in France and Spain integrate caseinate into frozen dough systems for consistent texture control.
- Confectionery:Whipped aeration and fat replacement functions in chocolate and candy manufacturing utilize caseinate emulsification. Premium confectionery producers in Belgium and Switzerland specify low-ash grades for flavor neutrality.
Dairy applications command the largest volume commitments; protein supplements generate the steepest expansion trajectory.
End User:
End-user segmentation tracks regulatory burden intensity, with pharmaceutical and nutraceutical channels imposing validation timelines that filter supplier participation.
- Food Industry:Commercial dairy processors, bakery conglomerates, and meat alternative manufacturers constitute the foundational demand base. EFSA heavy metal residue limits and FDA Grade A Pasteurized Milk Ordinance standards bifurcate supplier qualification between European and North American food manufacturing.
- Pharmaceutical Sector:Enteral nutrition, drug delivery matrices, and surgical tissue adhesives require GMP-certified micellar casein with batch-level documentation. Validation cycles of 18-24 months constrain capacity reallocation and entrench incumbent supplier relationships.
- Nutraceuticals:Sports nutrition, weight management, and clinical dietary supplements drive specification toward sustained-release protein kinetics. India's FSSAI-mandated BIS certification for imported caseinates creates premium positioning for compliant suppliers.
- Cosmetics:Skin conditioning and film-forming applications in hair care and topical formulations utilize hydrolyzed casein fractions. Korean and Japanese beauty manufacturers specify low-molecular-weight derivatives for permeability optimization.
Food industry procurement absorbs the majority of commodity caseinate output; pharmaceutical sector qualification barriers protect margin premiums for verified suppliers.
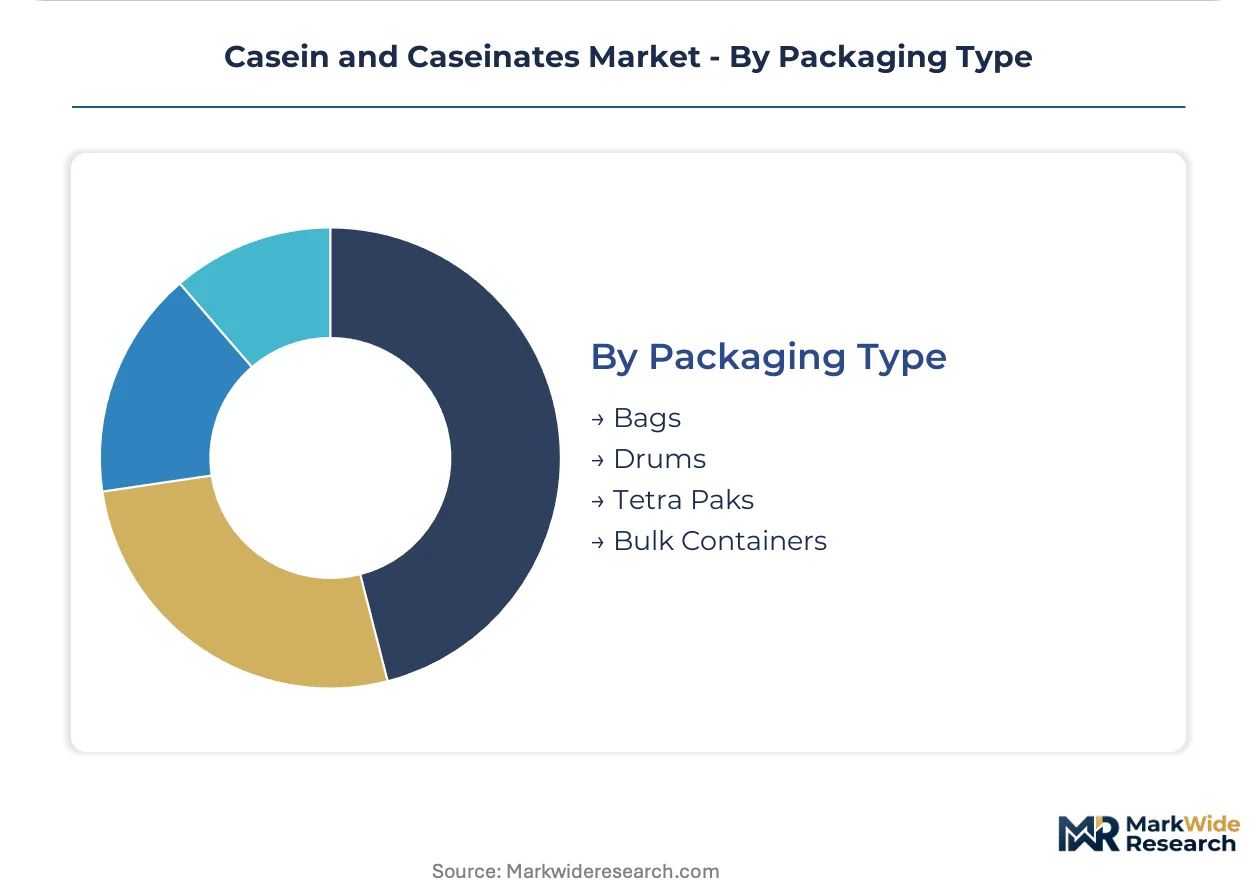
Packaging Type:
Packaging selection correlates with customer scale and contamination sensitivity, from bulk dairy processor deliveries to aseptic pharmaceutical presentations.
- Bags:Multi-layer laminated sacks with moisture barriers serve mid-scale food manufacturers and regional distributors. Cost efficiency dominates purchasing criteria for bakery and confectionery compounders.
- Drums:Steel and fiber drums with nitrogen flushing protect hygroscopic caseinates during ocean freight to Asian nutraceutical processors. Container integrity specifications tighten for pharmaceutical-grade material.
- Tetra Paks:Aseptic carton systems enable liquid caseinate suspensions for beverage fortification applications. Extended shelf-life dairy brands in Scandinavia specify this format for manufacturing line integration.
- Bulk Containers:Flexible intermediate bulk containers and tanker deliveries serve integrated dairy processors with dedicated ingredient handling infrastructure. Oceania's rennet casein exports to European mozzarella manufacturers utilize this format for cost minimization.
Bulk containers and drums together handle the majority of tonnage; Tetra Pak aseptic formats are climbing fastest on beverage fortification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in Oceania and Europe supply casein derivatives to concentrated demand corridors in Germany, India, and the United States, creating freight-dependent value chains shaped by divergent regulatory standards.
New Zealand
Integrated dairy cooperatives dominate rennet casein output for European mozzarella manufacturers. The country's national food safety authority enforces stringent residue monitoring for export-bound protein isolates. Canterbury's dairy processing belt anchors farm-to-ingredient traceability systems that satisfy EU REACH disclosure requirements.
Germany
Precision nutrition contract manufacturers drive pharmaceutical-grade micellar casein procurement for clinical and sports applications. EFSA heavy metal limits for dairy protein isolates filter supplier qualification toward vertically integrated operations. Bavaria's manufacturing corridor hosts multi-year offtake negotiations between ready-to-mix protein brands and fractionation equipment operators.
United States
Wisconsin's mozzarella production corridors sustain acid casein demand for stretch and melt specifications in processed cheese. FDA Grade A Pasteurized Milk Ordinance standards impose 18-24 month validation cycles for infant formula-bound material. The Midwest dairy belt concentrates backward integration into milk pooling to buffer skim milk powder price volatility.
India
Nutraceutical processors import caseinates for sports nutrition and clinical dietary supplement formulation. FSSAI-mandated BIS certification creates premium positioning for compliant suppliers while excluding non-compliant entrants. Maharashtra's food processing zones concentrate demand for certified micellar casein among domestic supplement brands.
Netherlands
Mid-scale dairy processors deploy ceramic membrane filtration to capture margin from commodity ingredient traders. The EU CSRD carbon disclosure rules favor suppliers with verified farm-to-ingredient emissions data. The Randstad region's urban proximity enables decentralized protein fractionation capacity serving northwest European beverage fortification demand.
Casein and Caseinates Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the casein value chain, with integrated dairy cooperatives holding extraction infrastructure advantages over specialized ingredient traders. The supplier base concentrates around three tiers: Oceania-based milk pool controllers, European pharmaceutical-grade specialists, and North American diversified dairy processors. Strategic moves center on membrane filtration technology licensing and multi-year equipment servicing subscriptions that lock customer relationships.
Within the integrated cooperative tier, FrieslandCampina and Fonterra Co-operative Group exemplify milk pool anchoring strategies that control upstream supply security. Arla Foods occupies a position among European specialists targeting pharmaceutical-grade certification barriers. These three entities represent divergent geographic production bases while converging on traceability investments that satisfy tightening chemical disclosure rules across multiple jurisdictions.
| Leading Market Players |
|---|
| FrieslandCampina |
| Fonterra Co-operative Group |
| Arla Foods |
| Groupe Lactalis |
| Kerry Group |
| Lactalis Ingredients |
| Saputo |
| Westland Milk Products |
| AMCO Proteins |
| Others |
Cost & Logistics Intelligence
Skim milk powder feedstock costs cascade through three pricing tiers, with pharmaceutical-grade micellar casein commanding premiums over commodity acid-precipitated grades as New Zealand milk pool volatility transmits downstream to European contract manufacturers.
Pricing Analysis
Margin tightening in commodity caseinate reflects skim milk powder price swings that compress predictability for non-integrated processors. Three-tier pricing structure across pharmaceutical, food-grade, and industrial certification levels separates infant formula-bound material from processed cheese applications. Cost-down pressure on standard-grade caseinates accelerates because pea protein isolates narrow functionality gaps in emulsification. Food manufacturers exhibit highest price sensitivity; pharmaceutical channels accept premiums for batch-level documentation.
Supply Chain Analysis
REACH chemical disclosure and FDA Grade A Pasteurized Milk Ordinance certification gate supplier participation toward vertically integrated operations with captive laboratory testing. Production concentrates in New Zealand, the Netherlands, and Germany, drawing from raw milk, ceramic membrane systems, and alkali treatment chemicals. Single-source vulnerability runs through Oceania's climate-exposed milk supply. Distribution runs through direct procurement relationships between sports nutrition brands and fractionation operators that compress traditional ingredient trader roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade validation timelines create supply-constrained conditions that prop pricing for qualified micellar casein suppliers serving enteral nutrition and clinical applications.
For Market Incumbents: Lock in multi-year equipment servicing subscriptions that convert capital sales into recurring revenue streams and anchor customer relationships. Deepen backward integration into milk pooling to buffer skim milk powder volatility that threatens margin predictability. Prioritize carbon intensity disclosure investments ahead of EU CSRD enforcement to capture first-mover positioning in verified farm-to-ingredient emissions data.
For New Entrants and Emerging Players: Sports nutrition contract manufacturers in Germany's precision nutrition corridor represent the most penetrable channel for qualified micellar casein supply. Target mid-scale dairy processors deploying ceramic membrane filtration in the Netherlands and Denmark where decentralized capacity challenges commodity trader margins. Pursue direct procurement relationships with ready-to-mix protein brands that displace traditional ingredient distributor roles.
For Investors and Strategic Acquirers: FSSAI-mandated BIS certification enforcement in India is the leading indicator that regulatory fragmentation will deepen supplier qualification barriers across nutraceutical channels. Long-term viability favors vertically integrated operations with traceability infrastructure spanning farm-to-ingredient documentation. Watch membrane filtration technology licensing deals as signals of competitive repositioning between commodity and specialty grade production.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Licensing | Ceramic microfiltration systems decentralize protein fractionation capacity toward regional processors near urban demand clusters. |
| Multi-Year Equipment Servicing Subscriptions | Technical support contracts rebalance processor monetization toward recurring revenue and locked customer relationships. |
| Carbon Intensity Disclosure Programs | Verified farm-to-ingredient emissions data satisfies EU CSRD requirements and creates first-mover advantage in retail shelf placement. |
| Direct Procurement Relationship Development | Sports nutrition brands negotiating volume locks bypass traditional ingredient distributors and compress channel margins. |
| Pharmaceutical-Grade Certification Investment | FDA Grade A Pasteurized Milk Ordinance compliance entrenchs supplier positioning in infant formula and enteral nutrition channels. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs that combined with primary interviews across dairy processing executives, protein fractionation equipment operators, sports nutrition brand procurement leads, and pharmaceutical formulation scientists. EFSA residue limit documentation, FDA Grade A Pasteurized Milk Ordinance standards, FSSAI BIS certification requirements, and Oceania dairy cooperative disclosures provided regulatory validation. Bottom-up capacity modeling and top-down demand estimation triangulated market sizing across the analysis window.
Granularity-level modeling tracked casein type, application tier, end-user regulatory burden, and packaging format throughout the forecast period. CAGRs derived from segment-level volume trajectories weighted by pricing power differentials between pharmaceutical-grade micellar casein and commodity acid-precipitated material. Inputs included membrane filtration capacity deployment schedules, skim milk powder price correlation coefficients, and certification timeline distributions across regulatory jurisdictions.
Caveats apply where REACH disclosure rule amendments, FSSAI certification enforcement shifts, or climate-driven Oceania milk supply disruptions could materially shift the outlook. Forecasts reflect assumptions about protein fractionation technology diffusion rates and sports nutrition brand procurement pattern stability. A model refresh is warranted upon material change in ceramic membrane system cost curves or pharmaceutical-grade validation timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Liquid Feed Market
Ingredients
Feed Premix Market
Ingredients
Carotenoids Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
Fig Ingredient Market
Ingredients
France Sodium Reduction Ingredients Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Fonio Flour Market
Ingredients
Casein Hydrolysate Market
Ingredients
Europe Plant Protein Ingredients Market
Ingredients
Tomato Concentrate Market
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
South America Phytosterols Market
Ingredients
Cooking Coconut Milk Market
Ingredients
North America Malt Ingredients Market
Ingredients
Organic Starch Market